
 Europe Adhesives Market | 2026-2036
Europe Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Adhesives Market Foresight
Buyer concentration in Europe's automotive and construction sectors is pivoting toward tier-one suppliers and national infrastructure consortia with multi-year framework agreements. Henkel AG & Co. KGaA leverages its German manufacturing footprint to dominate reactive adhesive supply for automotive OEMs. Sika AG anchors construction bonding demand through specialized distribution networks across Alpine and Mediterranean markets. Arkema competes in high-performance acrylic segments for electronics assembly, where specification control determines vendor selection.
Adhesives are non-metallic substances applied to surfaces that develop adhesion and cohesion through chemical reaction, solvent evaporation, or cooling to bond dissimilar materials; European formulations increasingly incorporate bio-based polyols and low-VOC water-borne systems to meet ECHA thresholds. Water-based technology leads volume shipments in packaging and consumer goods, though reactive systems capture margin pools in automotive structural bonding. Hot melt applications sustain growth in electronics assembly lines requiring rapid cure cycles and clean room compatibility.
REACH registration through ECHA governs monomer and additive disclosure, while the EU Green Deal's industrial emissions targets pressure solvent-based formulations toward phase-out. The F-Gas Regulation indirectly shapes polyurethane adhesive production by restricting blowing agents in downstream insulation markets. Stakeholders must monitor bio-feedstock certification schemes and national building codes in France and Italy that increasingly mandate environmental product declarations for public procurement eligibility.
Market Dynamics
REACH compliance through ECHA is forcing adhesive formulators across Europe to retire solvent-based chemistries and rebuild supply chains around bio-polyols and water-borne systems, compressing margin structures while opening specification windows for compliant suppliers.
Growth Catalysts
- Automotive lightweighting mandates:Germany's KBA enforces CO2 reduction targets that favor adhesive bonding over mechanical fasteners in vehicle assembly, expanding structural adhesive specifications at BMW, Mercedes-Benz, and Volkswagen plants.
- EU Green Deal industrial emissions targets:The framework pressures construction sectors in France and Italy to specify low-VOC adhesives for public procurement eligibility, redirecting specification control toward compliant formulators.
- Bio-based polyol innovation:Castor oil and lignin-derived feedstocks from agricultural cooperatives in Spain and Portugal are achieving performance parity with petrochemical alternatives in polyurethane adhesive segments.
Market Restraints
- Feedstock concentration risk:Isocyanate precursors for polyurethane adhesives concentrate in German and Belgian chemical clusters, exposing formulators to single-source dependency and force majeure vulnerability.
- REACH registration cost escalation:ECHA's data requirements for novel bio-based monomers impose six-figure compliance burdens that exclude mid-tier formulators from premium specification pools.
- Mechanical fastener residual preference:Italian and Eastern European automotive tier suppliers retain welded joint specifications for crash-critical assemblies where adhesive bonding lacks decades of liability data.
Strategic Opportunities
- Polish and Romanian manufacturing expansion:Automotive OEM supplier parks in Poznan and Craiova lack qualified adhesive distributors, creating first-mover advantage for technical service-capable formulators.
- Environmental Product Declaration mandates:France's RE2020 building code and Italy's CAM criteria increasingly require EPD-certified adhesives for public infrastructure tenders, rewarding early certifiers with specification lock-in.
- UV-LED curing convergence:Electronics assembly lines in Slovakia and Hungary are integrating UV-LED curing equipment with acrylic adhesive formulations, enabling sub-second cure cycles for high-mix production.
Industry Challenges
- Formulation chemist scarcity:European universities produce insufficient polymer science graduates with REACH dossier preparation expertise, extending new product development timelines by 12-18 months.
- Legacy equipment incompatibility:Water-borne adhesive transitions require heated tank and pump retrofits at automotive OEM plants, creating capital allocation conflicts with electrification investments.
- Cross-border waste classification:Adhesive packaging and cured waste trigger divergent hazardous waste codes across German Lander and French regions, complicating pan-European service contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Adhesives Market |
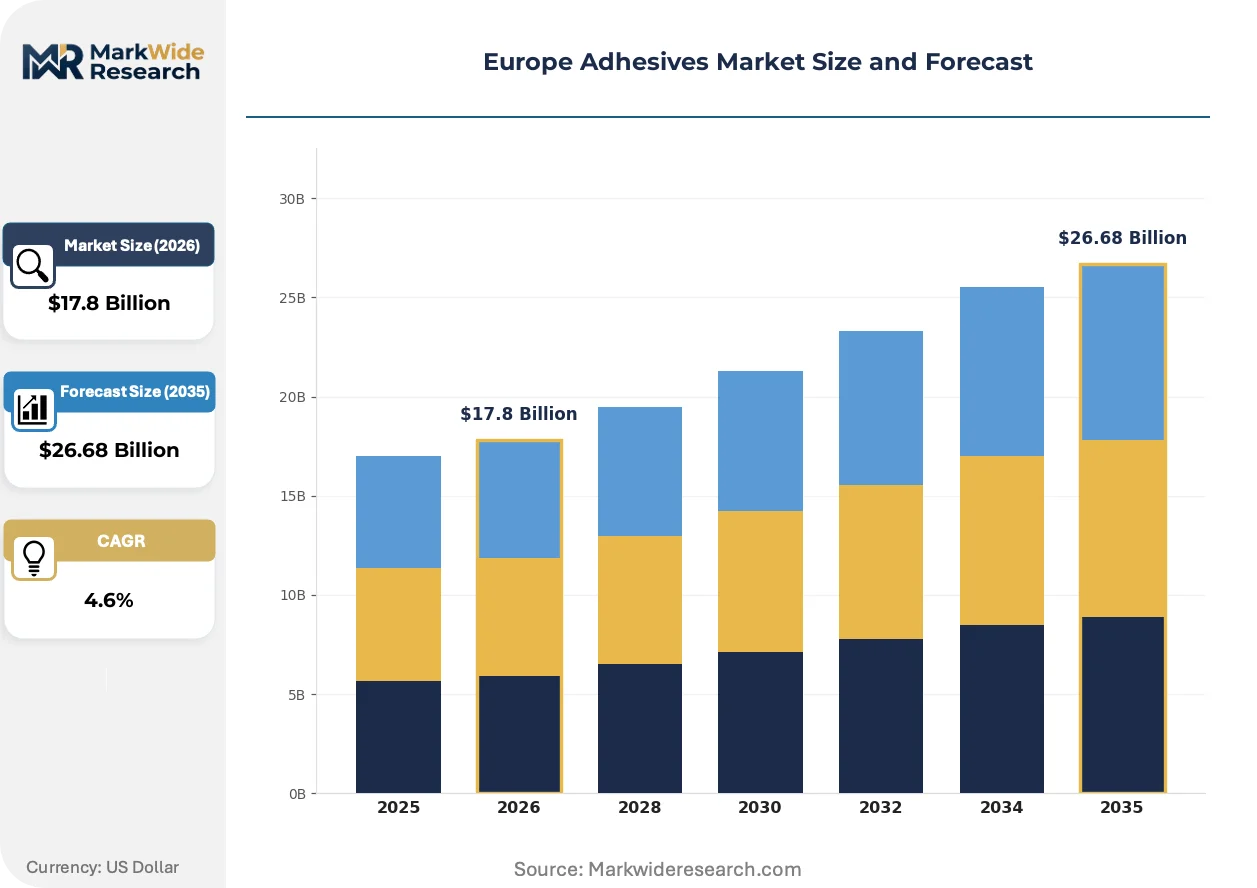
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
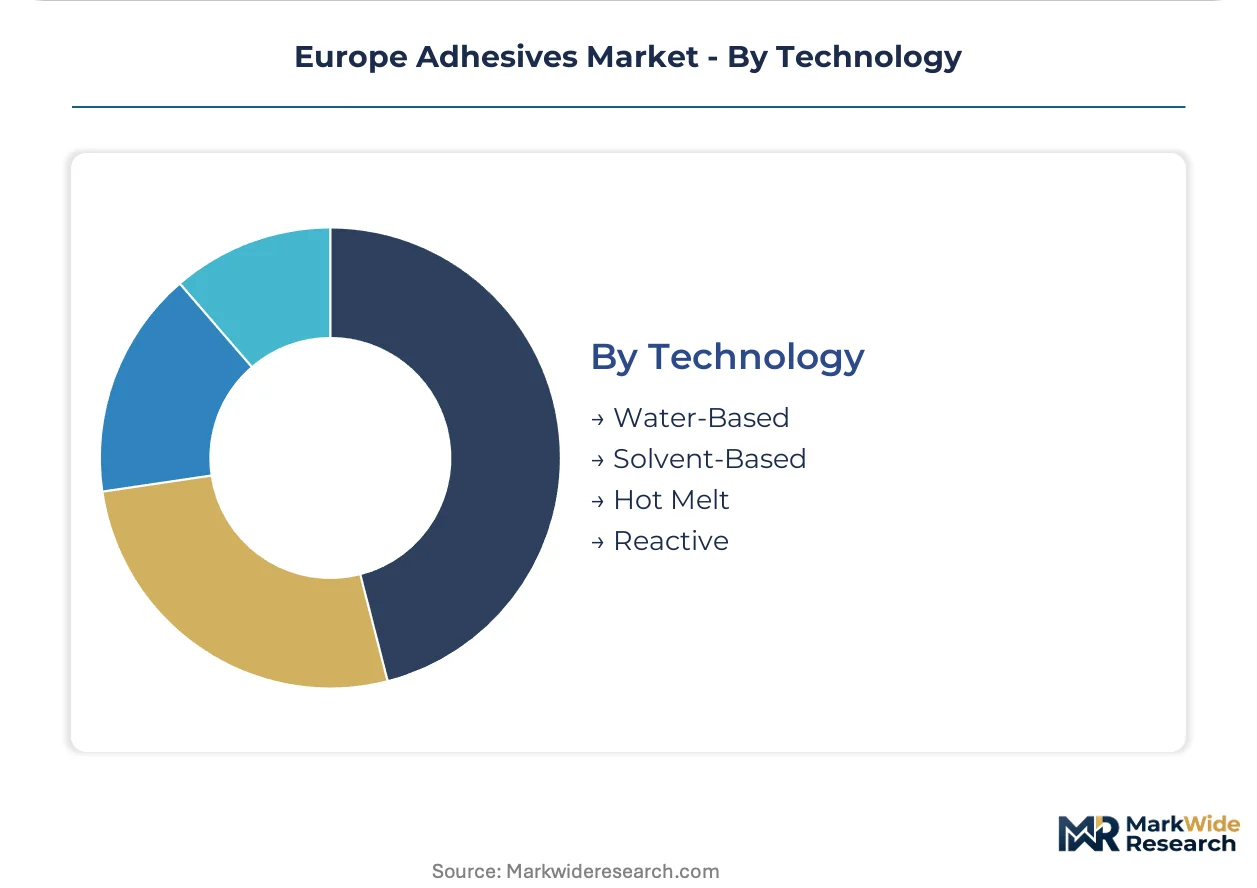
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Silicone End Use Industry: Construction, Automotive, Packaging, Electronics Application: Bonding, Coating, Sealing, Surfaces Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, 3M Company, Arkema, Dow Inc., H.B. Fuller Company, Wacker Chemie AG, Avery Dennison Corporation, Illinois Tool Works Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Adhesives Market Shifts & Advancements
Bio-based feedstock substitution and digital curing control are restructuring European adhesive value chains, compressing traditional solvent-based segments while elevating specification complexity in automotive and electronics bonding.
Reactive polyurethane systems incorporating castor oil-derived polyols are absorbing specification share from conventional petrochemical formulations in automotive structural bonding applications. BMW's Leipzig and Regensburg plants have qualified these materials for roof bonding and battery enclosure assembly since 2023. The technology is absorbing margin from solvent-based competitors while commanding 15-20% formulation premiums justified by carbon footprint reductions.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents is redirecting polyurethane adhesive production toward pentane and water-blown alternatives. Downstream insulation manufacturers in Germany and Belgium are reformulating to maintain thermal performance without restricted inputs. Construction adhesive segments serving facade and window installation are absorbing compliance costs through modified application equipment and adjusted open-time specifications.
Specification authority is migrating from purchasing departments to ESG and regulatory affairs functions at European automotive OEMs and construction consortia. Framework agreements now embed lifecycle carbon thresholds and ECHA SVHC screening requirements that disqualify incumbent suppliers lacking disclosure infrastructure. This pattern concentrates procurement among Henkel, Sika, and Arkema in Germany and France, while excluding smaller Italian and Spanish formulators from multi-year contracts.
Europe Adhesives Market Segmentation
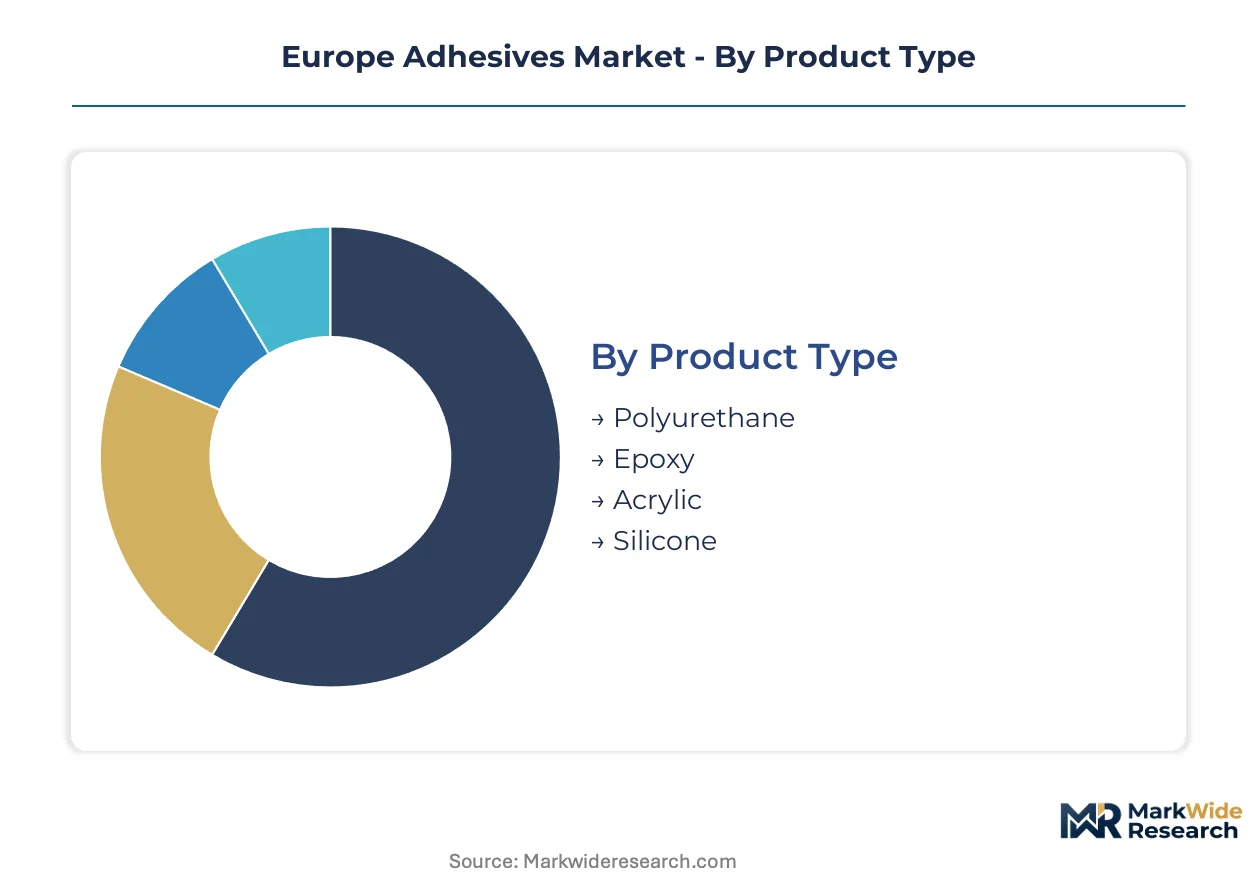
European adhesive procurement increasingly hinges on specification control rather than price competition. Formulators must align segment portfolios with REACH compliance timelines and automotive OEM qualification protocols to capture multi-year framework agreements.
Product Type:
Supply concentration in German and Belgian chemical clusters shapes competitive dynamics across polymer chemistry segments.
- Polyurethane:Two-part systems incorporating castor oil-derived polyols dominate structural bonding applications. BMW's Leipzig and Regensburg plants have qualified these materials for roof bonding and battery enclosure assembly, absorbing margin from petrochemical alternatives while commanding formulation premiums justified by carbon footprint reductions.
- Epoxy:High-performance thermosets with superior chemical resistance and load-bearing characteristics anchor electronics assembly and aerospace applications. Demand concentrates in Slovakia and Hungary where contract manufacturers service German automotive electronics specifications.
- Acrylic:UV-curable formulations enable sub-second cure cycles for high-mix electronics production lines.
- Silicone:Flexible, temperature-stable elastomers seal facade joints and automotive lighting assemblies across Alpine climates.
Today's leader: Polyurethane. Tomorrow's challenger: Epoxy.
End Use Industry:
Application-specific qualification protocols create divergent margin structures across vertical demand pools.
- Construction:Low-VOC water-borne and reactive systems absorb specification share as France's RE2020 building code and Italy's CAM criteria mandate EPD-certified products for public infrastructure tenders. Sika AG anchors demand through specialized distribution networks across Alpine and Mediterranean markets.
- Automotive:Structural adhesives displace mechanical fasteners as Germany's KBA enforces CO2 reduction targets. BMW, Mercedes-Benz, and Volkswagen plants have expanded adhesive bonding specifications for lightweighting programs.
- Packaging:Water-based acrylics and hot melts sustain volume shipments in food and consumer goods applications.
- Electronics:High-purity acrylic and epoxy formulations serve clean room assembly lines in Slovakia and Hungary.
Construction commands specification premiums today. Automotive represents the steepest expansion trajectory.
Application:
Functional differentiation determines equipment compatibility and curing infrastructure requirements.
- Bonding:Structural load transfer applications in automotive and construction demand reactive polyurethane and epoxy systems with documented shear strength and fatigue resistance. Henkel AG leverages its German manufacturing footprint to dominate reactive adhesive supply for automotive OEMs.
- Sealing:Flexible silicone and modified silicone formulations accommodate thermal expansion in building envelopes and automotive lighting. Alpine climate exposure drives specification toward UV-stable, low-modulus elastomers.
- Coating:Protective layers requiring chemical resistance and abrasion tolerance in industrial equipment.
- Surfaces:Preparation and treatment chemistries enabling adhesion to low-energy substrates.
Bonding captures the deepest specification control. Sealing offers the most defensible regional franchise.
Technology:
Regulatory phase-out schedules and capital equipment requirements stratify competitive entry barriers.
- Reactive:Two-component polyurethane and epoxy systems cure through chemical reaction to form thermoset bonds with superior structural performance. These formulations capture margin pools in automotive structural bonding where specification control determines vendor selection.
- Water-Based:Emulsion polymers displace solvent-borne alternatives as ECHA thresholds tighten. Packaging and consumer goods applications sustain volume leadership despite heated tank retrofits required at OEM plants.
- Hot Melt:Thermoplastic formulations enable rapid processing in electronics assembly lines requiring clean room compatibility.
- Solvent-Based:Declining segment facing EU Green Deal industrial emissions pressure and progressive phase-out in public procurement eligibility.
Reactive systems dominate premium positioning. Water-based formulations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer science graduates from RWTH Aachen and ETH Zurich anchor Europe's adhesive formulation workforce, concentrating technical talent within Germany's industrial corridor and Switzerland's Alpine chemical belt. This expertise concentration shapes regional competitive positioning across the continent.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg drive structural adhesive specifications for lightweighting programs at BMW, Mercedes-Benz, and Volkswagen plants. KBA enforcement of CO2 reduction targets accelerates adhesive bonding substitution for mechanical fasteners. The Rhine-Ruhr chemical cluster houses isocyanate precursor production, creating feedstock concentration risk for polyurethane formulators.
France
Construction consortia in Île-de-France and Auvergne-Rhône-Alpes specify low-VOC adhesives under RE2020 building code mandates for public infrastructure tenders. ECHA thresholds tighten procurement eligibility, redirecting specification control toward compliant suppliers. Lyon-based distribution networks serve Alpine facade sealing applications requiring UV-stable silicone formulations.
Italy
Automotive tier suppliers in Piedmont and Emilia-Romagna retain welded joint specifications for crash-critical assemblies where adhesive bonding lacks liability data. CAM criteria for public procurement increasingly mandate EPD-certified products, excluding smaller domestic formulators from multi-year contracts. Milan's industrial district hosts specialized packaging adhesive converters serving Mediterranean consumer goods markets.
Poland
Automotive supplier parks in Poznań lack qualified adhesive distributors, creating first-mover advantage for technical service-capable formulators. EU Green Deal industrial emissions targets pressure local manufacturers toward water-borne system transitions. The Silesian chemical basin provides regional feedstock access for mid-tier polyurethane compounders.
Spain
Agricultural cooperatives in Castilla-La Mancha and Andalusia supply castor oil-derived bio-polyols achieving performance parity with petrochemical alternatives. Portugal's lignin feedstock streams complement Iberian bio-based resin innovation. Barcelona's packaging converters sustain volume demand for water-based acrylic adhesives in food and consumer goods applications.
Europe Adhesives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Europe's adhesive value chain, creating a tiered competitive structure. German and Swiss chemical majors leverage integrated feedstock positions and REACH dossier expertise to dominate premium specification pools. Three archetypes define competitive positioning: vertically integrated resin producers, application-focused technical specialists, and regional distribution-centric compounders. Capacity expansion in Eastern European manufacturing zones and strategic partnerships for bio-feedstock certification represent the dominant competitive moves reshaping market access.
Among Germany-based diversified chemical groups, Henkel AG & Co. KGaA and Wacker Chemie AG exemplify vertically integrated archetypes with captive resin production and established automotive OEM qualification protocols. Sika AG occupies a position as a Swiss technical specialist anchored in construction bonding applications through Alpine and Mediterranean distribution networks. These three companies represent the concentration of specification control in reactive adhesive supply and facade sealing segments where regulatory compliance and multi-year framework agreements create defensive market positions.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| 3M Company |
| Arkema |
| Dow Inc. |
| H.B. Fuller Company |
| Wacker Chemie AG |
| Avery Dennison Corporation |
| Illinois Tool Works Inc. |
| Others |
Supply & Pricing Matrix
Polymer science graduates from RWTH Aachen and ETH Zurich anchor Europe's adhesive formulation workforce, concentrating technical talent within Germany's industrial corridor. Labor-cost differentials between these premium-tier research hubs and emerging Eastern European manufacturing zones drive pricing-tier spreads across reactive system specifications.
Pricing Analysis
Bundled technical service contracts dominate premium-tier procurement, while unbundled commodity formulations compete on spot pricing. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant reactive systems from water-borne alternatives and residual solvent-based inventories. Cost compression in standard-tier water-borne segments is intensifying because heated tank retrofits at automotive OEM plants strain capital allocation. Construction consortia in France and Italy exhibit highest price sensitivity due to public procurement budget constraints, while German automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for adhesive packaging and cured waste trigger divergent hazardous waste codes across German Lander and French regions, complicating pan-European service contracts. Isocyanate precursors concentrate in German and Belgian chemical clusters, while bio-polyol feedstocks draw from Spanish and Portuguese agricultural cooperatives. Single-source vulnerability in polyurethane precursor supply poses structural risk amid force majeure exposure. Distribution runs through specialized technical distributors serving automotive OEM supplier parks and construction consortia with just-in-time delivery requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's adhesives market functions as a regulatory compounder where REACH compliance timelines and EU Green Deal emissions targets continuously reshape procurement eligibility. France's RE2020 building code milestone has redirected construction specification control toward EPD-certified suppliers.
For Market Incumbents: Extend qualification protocols for bio-based polyurethane systems to capture BMW and Mercedes-Benz battery enclosure specifications before competitors achieve performance parity. Deepen backward integration into castor oil-derived polyol supply through partnerships with Iberian agricultural cooperatives. This defends margin position against emerging pure-play bio-resin specialists.
For New Entrants and Emerging Players: Direct-to-technical-buyer digital platforms bypass incumbent distributor lock-in across Polish and Romanian automotive supplier parks. Poznań and Craiova manufacturing zones present the most penetrable geography due to qualified adhesive distributor scarcity. Target UV-LED curing equipment integration partnerships with Slovakian and Hungarian electronics contract manufacturers.
For Investors and Strategic Acquirers: German automotive OEMs are the most active acquirer in this space, seeking captive adhesive formulation capabilities for electrification platform standardization. Mid-tier compounders with REACH dossier expertise and Eastern European technical service infrastructure represent priority acquisition targets. Monitor ECHA SVHC candidate list expansions for inflection signals that would accelerate solvent-based formulation obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polyol Supply | Captive access to Iberian castor oil feedstocks secures carbon footprint advantages for automotive OEM qualifications. |
| REACH Dossier Investment for Novel Monomers | ECHA registration for lignin-derived intermediates opens specification windows in public procurement eligibility pools. |
| Technical Service Expansion in Eastern Europe | Qualified adhesive distributor presence in Poznań supplier parks captures first-mover advantage in automotive lightweighting programs. |
| UV-LED Curing Equipment Partnership | Integration with Slovakian electronics assembly lines enables sub-second cure cycle specifications for high-mix production. |
| EPD Certification Acceleration | Early environmental product declaration attainment locks in specification control for France RE2020 and Italy CAM tender eligibility. |
Research Methodology
Direct dialogue with adhesive formulator R&D directors, automotive OEM procurement leads, construction consortia technical buyers, and ECHA regulatory consultants grounded qualitative insights. Secondary validation drew from ECHA registration databases, EU customs trade flows for isocyanate precursors, SEC filings of diversified chemical groups, and national building code implementation notices. Bottom-up segment sizing triangulated against top-down chemical industry association aggregates.
Market value and volume estimates emerged from multi-dimensional segmentation across polymer chemistry, end-use industry, application function, and curing technology. Modeled dimensions included reactive versus water-borne technology splits, automotive versus construction demand pools, and regional production hub clustering. CAGRs derived from regression analysis of historical qualification timelines and regulatory phase-out schedules, incorporating automotive OEM lightweighting program commitments and EU Green Deal implementation pacing.
The model assumes a particular technology adoption path; alternative pathways for UV-LED curing equipment penetration would alter the outlook for acrylic adhesive demand trajectories. Forecasts reflect assumptions about REACH registration cost trajectories and bio-feedstock certification scheme harmonization. Practitioners should monitor ECHA SVHC candidate list expansions and national building code amendment cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
United States Adhesives Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market