
 Asia-Pacific Solid State Battery Market | 2026-2036
Asia-Pacific Solid State Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Solid State Battery Market Insights
UN 38.3 lithium battery transport certification is rotating as the baseline qualification gating commercial shipments across the Asia-Pacific. Samsung SDI leverages its Korean pilot-line infrastructure to accelerate cycle-life testing. Toyota Motor Corporation anchors the region's oxide-electrolyte development through its Nagoya research complex. CATL competes on sulfide-based cell architectures with integrated cathode manufacturing.
A solid-state battery replaces flammable liquid electrolytes with ceramic, glass, or polymer ionic conductors, achieving energy densities above 400 Wh/kg while eliminating thermal runaway risks below 300°C decomposition thresholds. The technology serves electric vehicles and grid storage where safety margins and volumetric efficiency determine total cost of ownership. Bulk solid-state cells dominate current pilot capacity due to compatibility with existing lithium-ion winding equipment, while thin-film architectures capture premium medical device applications requiring sub-millimeter form factors. Hybrid electrolyte formulations lead R&D investment as manufacturers balance ionic conductivity against manufacturing yield.
Japan's METI funds solid-state commercialization through its Green Innovation Fund, while South Korea's KATS enforces revised K62133 safety standards for next-generation cells. China's SAMR integrates solid-state requirements into GB/T battery certification protocols, tightening market access for uncertified suppliers. Stakeholders must monitor electrolyte material supply agreements and qualification timelines as regional production scales from pilot to gigawatt-hour output.
Market Dynamics
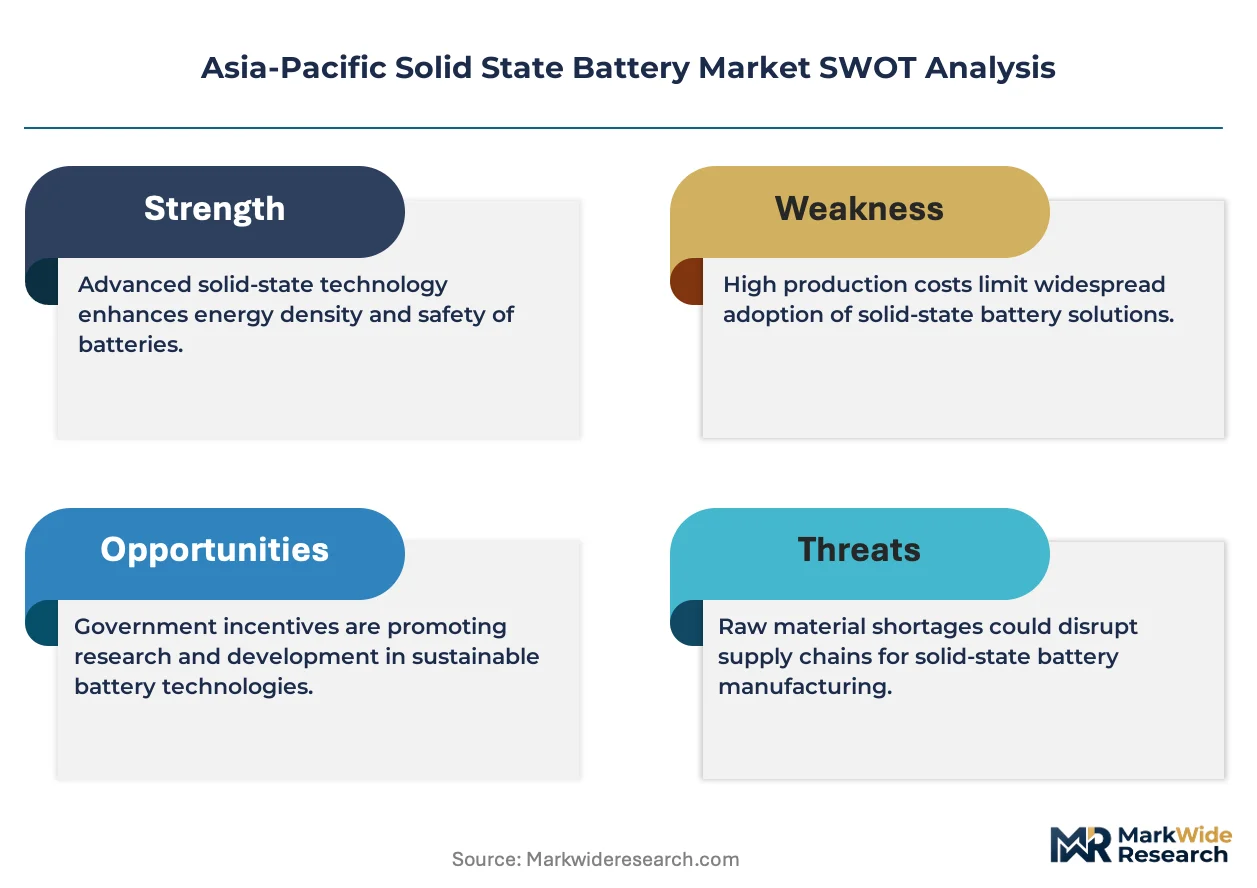
Oxide-electrolyte manufacturing scale-up in Japan's Nagoya-Osaka corridor is compressing certification timelines and forcing sulfide-based competitors to accelerate pilot-line investments or risk supply contract losses.
Growth Catalysts
- Japan's METI Green Innovation Fund:Direct capital allocation to solid-state commercialization projects reduces private R&D risk and accelerates prototype-to-production transitions for domestic manufacturers.
- Electric vehicle procurement:Korean and Japanese automakers are binding multi-year offtake agreements with cell suppliers, creating demand visibility that justifies gigafactory-scale electrolyte production investments.
- Lithium-metal anode maturation:Advances in dendrite suppression and interface engineering are pushing energy densities toward 400 Wh/kg thresholds, unlocking extended-range vehicle architectures.
Market Restraints
- Ceramic electrolyte sintering costs:High-temperature processing requirements for oxide-based cells consume 40% more energy per kilowatt-hour than conventional lithium-ion winding, inflating unit economics at pilot scale.
- Japanese sulfide supply concentration:Precursor material production clusters heavily around Osaka-Kobe industrial zones, exposing procurement chains to seismic disruption risks and limiting supplier diversification.
- China's SAMR certification friction:Extended GB/T protocol revision timelines for solid-state chemistries delay market entry for uncertified foreign suppliers, compressing first-mover windows.
Strategic Opportunities
- South Korea's K62133 safety standard revision:Updated testing protocols for next-generation cells create regulatory clarity that attracts investment into Korean pilot-line infrastructure and regional export hubs.
- Grid storage applications:Stationary energy systems with 12-hour discharge requirements represent an underpenetrated segment where solid-state thermal stability eliminates cooling system costs and footprint constraints.
- Hybrid electrolyte convergence:Composite ceramic-polymer formulations are opening manufacturing pathways that bridge existing lithium-ion equipment compatibility with solid-state performance gains.
Industry Challenges
- Thin-film deposition talent scarcity:Vacuum processing expertise for sub-micron electrolyte layers concentrates in Japanese semiconductor equipment firms, constraining workforce mobility into battery manufacturing.
- UN 38.3 transport certification timelines:Extended cycle-life testing requirements for lithium-metal cells delay commercial shipment authorization, freezing revenue recognition for pilot-scale producers.
- Interface engineering IP complexity:Dense patent thickets around anode-electrolyte bonding technologies force licensing negotiations that extend product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Solid State Battery Market |
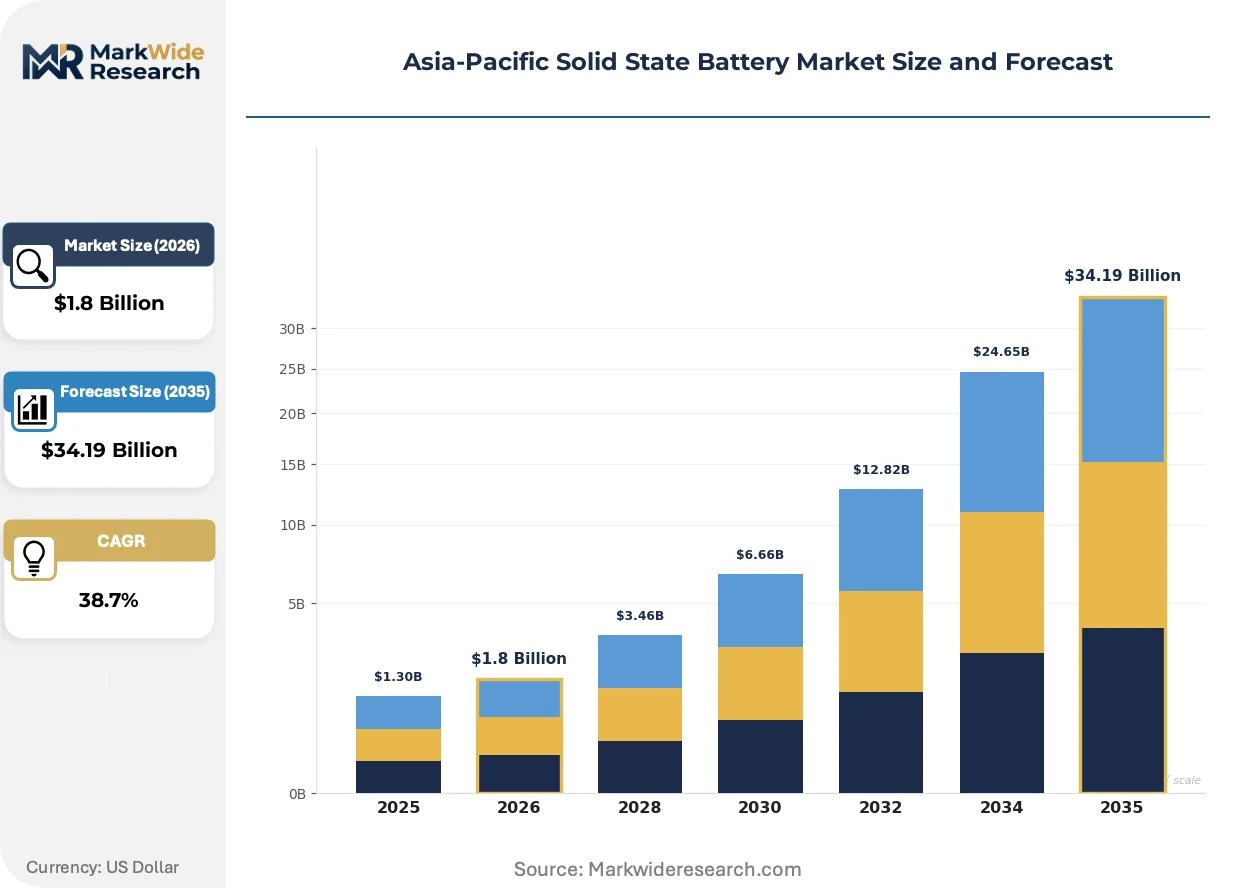
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $34.19 Billion |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Film, Coated, Bulk, Matrix End User: Consumer Electronics, Automotive, Aerospace, Industrial Technology: Lithium-Ion, Solid Polymer, Inorganic, Hybrid Application: Energy Storage, Electric Vehicles, Portable Devices, Medical Devices |
| Companies Covered | Samsung SDI, Panasonic Corporation, Toyota Motor Corporation, LG Energy Solution, CATL, Hitachi Zosen, Murata Manufacturing, ProLogium Technology, BYD, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Solid State Battery Market Trends and Innovations
Solid-state architectures are forcing parallel innovation across materials processing, safety certification, and manufacturing equipment. Three developments are compressing commercialization timelines.
Hybrid electrolyte formulations combining sulfide ionic conductors with oxide mechanical stability are miniaturizing cell form factors for medical implant applications. Japanese device manufacturers are qualifying sub-2mm configurations for cardiac monitoring systems. This convergence is compressing the addressable market gap between bulk automotive cells and thin-film consumer electronics.
China's MIIT battery safety mandates are tightening thermal runaway testing protocols for next-generation chemistries. Domestic manufacturers must demonstrate 300°C decomposition thresholds before receiving production licenses. Korean and Japanese suppliers are responding by accelerating oxide-electrolyte development to preempt regulatory exclusion from Chinese EV supply chains.
Automotive OEMs are consolidating cell procurement under long-term framework agreements rather than spot purchasing. Tier-1 suppliers in Japan and Korea are displacing speculative volume commitments with binding minimum offtake guarantees. This pattern is most visible in Toyota-Panasonic joint development structures, where shared R&D costs lock in exclusive supply relationships through 2030.
Asia-Pacific Solid State Battery Market Segmentation
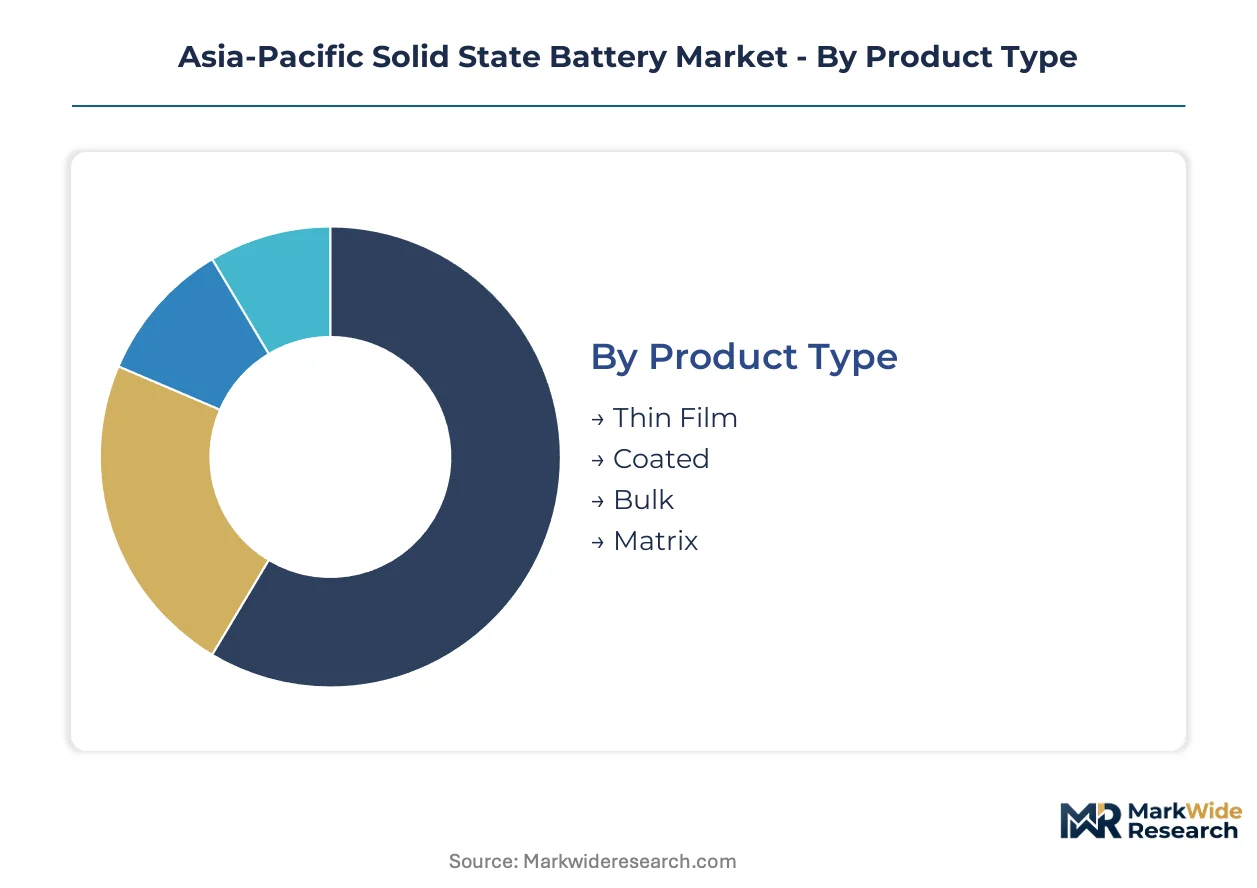
Solid-state battery architectures fragment across manufacturing maturity, application thermal requirements, and electrolyte chemistry compatibility. Segment boundaries determine which suppliers capture early commercial volume versus which face extended qualification timelines.
Product Type:
Margin pools concentrate in configurations that leverage existing lithium-ion winding infrastructure while delivering safety premiums.
- Thin Film:Sub-micron electrolyte layers deposited via vacuum processing achieve sub-2mm form factors for cardiac monitoring and neural implant applications. Japanese medical device manufacturers in the Nagoya-Osaka corridor dominate procurement, though vacuum processing talent scarcity constrains workforce expansion from semiconductor equipment firms.
- Bulk:Pressed ceramic or glass-ceramic pellets compatible with conventional electrode stacking equipment. Korean and Japanese automakers bind multi-year offtake agreements for electric vehicle integration, where 400 Wh/kg energy density targets justify premium unit economics.
- Coated:Conventional electrodes overlaid with solid electrolyte slurries, bridging liquid-electrolyte manufacturing with solid-state thermal stability. China's MIIT safety mandates favor this intermediate pathway for domestic certification.
- Matrix:Composite structures embedding active materials within rigid electrolyte scaffolds. Industrial grid storage pilots in South Korea evaluate 12-hour discharge configurations.
Bulk holds installed capacity. Thin Film is rotating up the share rankings.
End User:
Customer-type segmentation reveals where binding offtake agreements are displacing speculative volume commitments.
- Automotive:Toyota-Panasonic joint development structures lock exclusive supply relationships through shared R&D cost models. Korean OEMs accelerate sulfide-based cell procurement as lithium-metal anode designs mature.
- Consumer Electronics:Premium smartphone and wearable manufacturers qualify sub-3mm cells for flagship product lines. Japanese suppliers leverage oxide-electrolyte stability to preempt thermal runaway testing protocol revisions.
- Aerospace:Satellites and electric aircraft demand extreme temperature tolerance and zero-flammability margins. Certification timelines extend 18-24 months beyond automotive due to FAA-equivalent airworthiness requirements.
- Industrial:Automated manufacturing equipment and robotics applications prioritize cycle-life durability over energy density. Chinese industrial automation clusters evaluate hybrid electrolyte formulations for factory-floor deployment.
Automotive commands procurement volume. Consumer Electronics is climbing the fastest as medical-implant convergence accelerates.
Technology:
Electrolyte chemistry determines which regional production clusters capture technology leadership versus licensing dependency.
- Solid Polymer:Flexible ionic conductors processed at ambient temperatures, compatible with roll-to-roll manufacturing. South Korean pilot-line infrastructure targets medical device qualification under revised K62133 safety standards.
- Inorganic:Ceramic and glass-ceramic electrolytes with 300°C decomposition thresholds. Japan's METI Green Innovation Fund accelerates Nagoya-Osaka corridor scale-up, compressing certification timelines for oxide-based architectures.
- Lithium-Ion:Conventional liquid-electrolyte cells with solid-state interface modifications. Transition pathway for Chinese manufacturers adapting to GB/T protocol revisions.
- Hybrid:Composite ceramic-polymer formulations balancing ionic conductivity against manufacturing yield. Emerging as the dominant R&D investment category across Korean and Japanese national technology roadmaps.
Inorganic holds patent thicket advantages. Hybrid is gaining share fastest as equipment compatibility bridges pilot-to-production transitions.
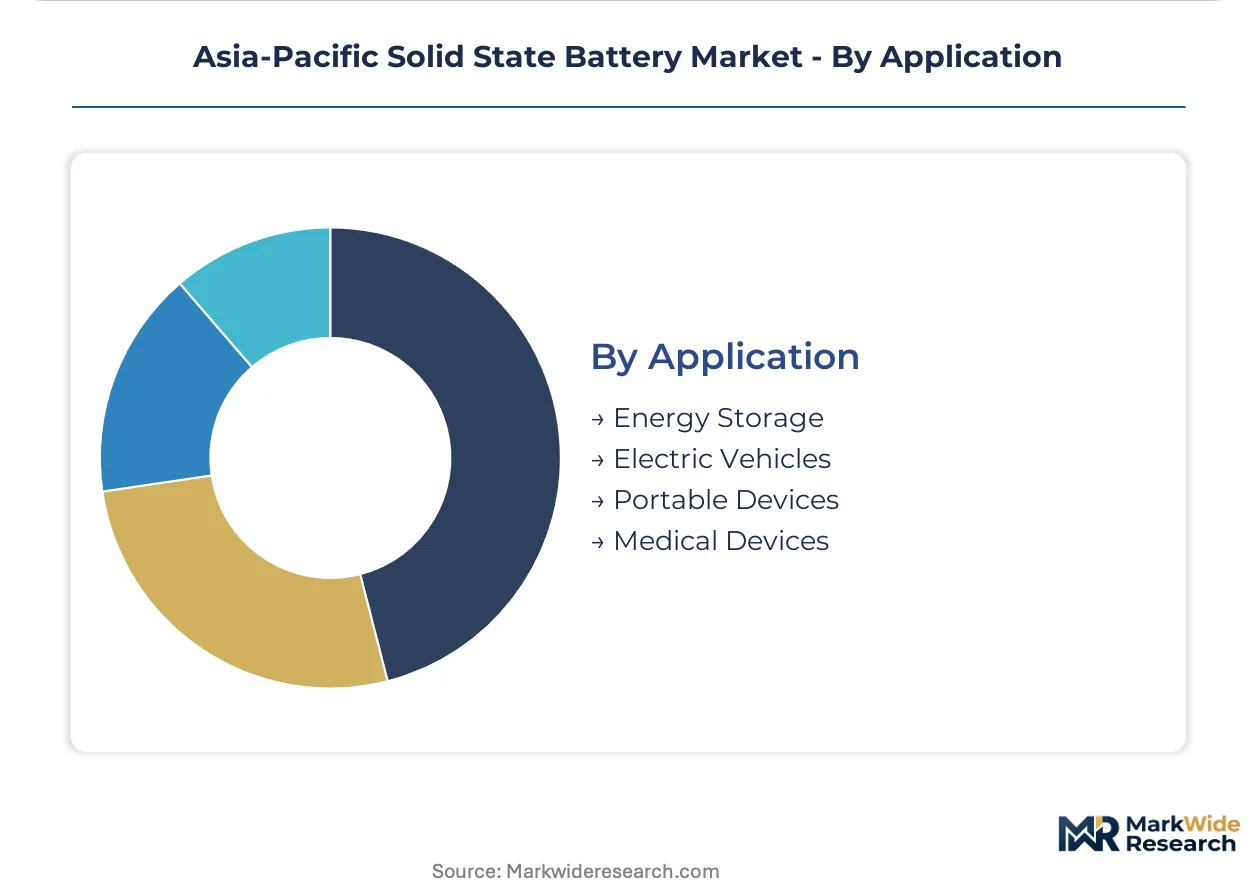
Application:
Application segmentation tracks where thermal stability eliminates cooling system costs and footprint constraints.
- Electric Vehicles:Extended-range architectures requiring 400 Wh/kg thresholds. Korean and Japanese automakers consolidate procurement under long-term framework agreements with binding minimum offtake guarantees.
- Energy Storage:Stationary systems with 12-hour discharge requirements represent underpenetrated segments where solid-state thermal stability eliminates auxiliary cooling infrastructure. South Korean utility pilots evaluate grid-scale deployment.
- Portable Devices:Premium consumer electronics demanding sub-millimeter form factors with safety margins. Japanese suppliers qualify sub-2mm configurations for cardiac monitoring convergence.
- Medical Devices:Implantable applications requiring absolute thermal runaway elimination. Regulatory alignment between Japan's PMDA and South Korea's MFDS accelerates cross-border qualification pathways.
Electric Vehicles anchors capital deployment. Energy Storage is rotating up the share rankings as grid-scale pilots validate total cost of ownership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI Green Innovation Fund channels capital toward solid-state commercialization, while China's MIIT battery safety mandates and South Korea's KATS standard revisions create divergent regulatory pathways across the region.
Japan
Toyota Motor Corporation and Panasonic Corporation anchor oxide-electrolyte development through shared R&D cost structures. METI's technology roadmaps compress certification timelines for next-generation chemistries. The Nagoya-Osaka manufacturing corridor concentrates prototype-to-production transitions, with pilot-line infrastructure scaling toward gigafactory output.
China
CATL and BYD compete on sulfide-based cell architectures with integrated cathode manufacturing capabilities. SAMR's GB/T protocol revisions for solid-state chemistries tighten market access for uncertified foreign suppliers. Yangtze River Delta production clusters adapt existing lithium-ion winding equipment for hybrid electrolyte formulations.
South Korea
Samsung SDI and LG Energy Solution leverage pilot-line infrastructure to accelerate cycle-life testing under revised K62133 safety standards. Korean automakers bind multi-year offtake agreements with cell suppliers, creating demand visibility for electrolyte production investments. Seoul Capital Area research complexes focus on lithium-metal anode maturation.
Taiwan
ProLogium Technology exemplifies specialized solid-state development with ceramic electrolyte expertise. The island's semiconductor equipment talent pool supports vacuum processing capabilities for thin-film architectures. Hsinchu Science Park clusters medical device qualification pathways for sub-2mm cell configurations.
Asia-Pacific Solid State Battery Market Competitive Landscape
Player mix skews toward diversified conglomerates with captive automotive demand and specialized pure-play developers. Market structure concentrates around Japanese and Korean industrial groups with integrated supply chains, while Chinese state-backed enterprises compete on manufacturing scale. Strategic archetypes include automotive-captive cell producers, independent electrolyte specialists, and materials-integrated conglomerates. Dominant competitive moves involve long-term framework agreements locking exclusive supply relationships and pilot-line capacity expansion racing against certification timelines.
Among Japan-based industrial groups, Toyota Motor Corporation and Panasonic Corporation occupy positions exemplifying automotive-captive integration through joint development structures. Samsung SDI represents the Korean conglomerate archetype leveraging existing pilot-line infrastructure. These three entities anchor regional technology leadership across oxide and sulfide electrolyte pathways without yet achieving commercial shipment authorization at scale.
| Leading Market Players |
|---|
| Samsung SDI |
| Panasonic Corporation |
| Toyota Motor Corporation |
| LG Energy Solution |
| CATL |
| Hitachi Zosen |
| Murata Manufacturing |
| ProLogium Technology |
| BYD |
| Others |
Pricing and Supply Chain Analysis
Ninety-day electrolyte precursor inventory buffers at Osaka-Kobe industrial clusters concentrate procurement leverage among oxide-electrolyte manufacturers while compressing pricing premiums for sulfide-based competitors facing extended UN 38.3 certification timelines. This lead-time asymmetry between certified and uncertified suppliers is reshaping contract structures across Japanese and Korean automotive offtake negotiations.
Pricing Analysis
Certification level under UN 38.3 and GB/T protocols creates the primary spread between premium and standard tiers. Contract-based long-term offtake agreements dominate automotive procurement, with pricing stratifying across pilot-line, gigafactory-scale, and mass-production tiers based on volume scale and interface engineering IP access. Cost compression in sulfide-electrolyte processing is intensifying because ceramic sintering energy requirements inflate unit economics at pilot scale. Grid storage buyers exhibit highest price sensitivity due to total-cost-of-ownership benchmarking against liquid-electrolyte alternatives, while medical device manufacturers accept premium positioning for sub-2mm form factor exclusivity.
Supply Chain Analysis
Port congestion at Busan and Shanghai container terminals elevates inbound logistics costs for lithium-metal precursor shipments from Australian and Chilean extraction sites. Geographic supply concentration centers on Japan's Nagoya-Osaka corridor, South Korea's Seoul Capital Area, and China's Yangtze River Delta production clusters. Raw material dependencies draw from spodumene concentrate, lithium hydroxide, and ceramic oxide powders. Single-source vulnerability around Japanese sulfide precursor production exposes procurement chains to seismic disruption risks. Distribution runs through Tier 1 cell manufacturer direct contracts rather than spot-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific solid-state battery market is cycling through a certification-driven recovery phase as lithium-metal anode maturation unlocks extended-range vehicle architectures and binding offtake agreements replace speculative volume commitments.
For Market Incumbents: Compound technology leadership through captive lithium-metal anode production investments in Nagoya-Osaka and Seoul Capital Area corridors to defend against sulfide-electrolyte substitution threats. Accelerate GB/T and K62133 certification submissions to preempt regulatory exclusion from Chinese and Korean EV supply chains, locking exclusive supply relationships through shared R&D cost structures. For New Entrants and Emerging Players: Differentiate on hybrid electrolyte formulations that bridge existing lithium-ion winding equipment compatibility with solid-state thermal stability gains. Target grid storage applications as the most penetrable segment, where 12-hour discharge requirements and cooling system cost elimination create first-mover windows. Pursue medical device qualification pathways through Taiwan's Hsinchu Science Park vacuum processing infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded pilot-line capacity and captive automotive demand but lacking commercial shipment authorization. Long-term viability over the next decade rests on electrolyte material supply agreements and qualification timeline execution rather than manufacturing scale alone. Watch for UN 38.3 transport certification authorization as the inflection signal separating revenue-generating producers from pre-commercial development-stage entities.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Toyota-Panasonic joint development structures lock exclusive supply relationships through shared R&D cost models. |
| Capacity Expansion | Samsung SDI leverages Korean pilot-line infrastructure to accelerate cycle-life testing under revised K62133 standards. |
| Technology Licensing | CATL competes on sulfide-based cell architectures with integrated cathode manufacturing capabilities. |
| Joint Venture | ProLogium Technology exemplifies specialized solid-state development with ceramic electrolyte expertise in Taiwan. |
| Green Certification Program | Japan's METI Green Innovation Fund channels capital toward solid-state commercialization projects. |
Research Methodology
A spread of perspectives from cell manufacturing executives, automotive procurement leads, electrolyte materials specialists, and regulatory affairs directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through METI technology roadmaps, MIIT battery safety mandates, K62133 standard revision documents, and UN 38.3 certification protocols. Customs and trade data from Japan, South Korea, and China supplemented bottom-up capacity assessments and top-down demand modeling triangulation.
Segmentation dimensions modeled span product type, end user, technology, and application categories across the projection horizon. The analytical framework disaggregates bulk, thin-film, coated, and matrix configurations by automotive, consumer electronics, aerospace, and industrial demand archetypes. CAGRs were derived from electrolyte production capacity buildout trajectories, lithium-metal anode maturation curves, and certification timeline probability distributions without year-specific anchoring.
Material uncertainties — regulatory protocol revision delays, seismic disruption to Japanese sulfide supply clusters, and lithium-metal dendrite suppression setbacks — sit outside the modeled envelope. Forecasts reflect assumptions about pilot-line-to-gigafactory transition velocities and binding offtake agreement conversion rates. Practitioners should keep alternative scenarios live as GB/T, K62133, and UN 38.3 certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Li-Sulfur Battery Market