
 18650 Lithium Battery for Electric Vehicle Market | 2026-2036
18650 Lithium Battery for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
18650 Lithium Battery for Electric Vehicle Market Insights
Market Context
Project finance tied to battery-as-a-service leasing is rewriting capital deployment for cell suppliers. Panasonic leverages vertical integration into cathode material production to sustain margin control. Samsung SDI anchors its competitive stance through R&D intensity in high-nickel chemistries. LG Chem navigates geographic diversification by operating manufacturing footprints across multiple continents.
Technical Definition and Segment Structure
The 18650 lithium battery for electric vehicle denotes a cylindrical cell measuring 18mm in diameter and 65mm in length, typically employing lithium-ion chemistry with nickel-manganese-cobalt or lithium-iron-phosphate cathodes to deliver 2,000–3,500 mAh capacity for traction power. Its primary commercial purpose centers on providing modular, thermally manageable energy storage for electric drivetrains where space constraints and weight distribution govern design. NMC technology occupies the premium tier of the chemistry landscape due to energy density advantages in passenger vehicle applications. The OEM end-user channel controls volume allocation through long-term supply agreements that lock in multi-year offtake. High capacity product types compete for positioning within the e-bike and two-wheeler segments where range anxiety drives purchasing decisions.
Regulatory Framework and Outlook
China's MIIT enforces GB standards for cell safety and cycle life that determine market access for domestic and imported 18650 cells. The EU's Battery Regulation and REACH compliance requirements shape material sourcing rules and end-of-life recycling obligations for suppliers serving European automotive OEMs. India's BIS certification and PLI scheme for advanced chemistry cells are redirecting investment toward localized manufacturing capacity. Stakeholders must monitor how carbon border adjustments and evolving chemistry-specific safety protocols will alter cost structures and sourcing geography.
Market Dynamics
Cell chemistry standardization around high-nickel NMC formulations is compressing supplier differentiation and forcing cathode material procurement consolidation across the 18650 EV battery supply base.
Growth Catalysts
- GB Standards Compliance:China's MIIT enforcement of GB/T 31484-2015 cycle-life benchmarks is accelerating domestic cell qualification and filtering out subscale producers from Jiangsu province manufacturing corridors.
- Light Commercial Fleet Electrification:North American van operators are scaling 18650 pack procurement for last-mile delivery routes where thermal runaway protocols and modular swap systems reduce downtime.
- Silicon Anode Infusion:Silicon-carbon composite anodes are penetrating high-capacity 18650 variants, extending gravimetric energy density for two-wheeler OEMs competing on range specifications.
Market Restraints
- Cobalt Supply Concentration:DRC-origin cobalt processing bottlenecks and Indonesian nickel matte export licensing are amplifying raw material cost volatility for NMC cathode producers.
- Prismatic Format Substitution:Automotive OEMs above compact vehicle classes are migrating traction pack designs toward prismatic and blade cell architectures, constraining 18650 addressable market expansion.
- REACH Material Compliance:ECHA substance restrictions on nickel compounds and fluorinated electrolyte additives are elevating reformulation costs for cells destined for EU automotive qualification.
Strategic Opportunities
- India PLI Localization:India's Production-Linked Incentive scheme for advanced chemistry cells is redirecting cathode precursor investment toward Gujarat and Tamil Nadu manufacturing zones.
- Battery-as-a-Service Leasing:Pay-per-kilometer financing models are emerging for electric two-wheeler fleets in Southeast Asian urban corridors, decoupling cell ownership from vehicle acquisition.
- Solid-State Interface Convergence:Hybrid solid-liquid electrolyte architectures are converging with 18650 form factors, opening thermal stability premiums for premium e-bike and power tool segments.
Industry Challenges
- Electrolyte Formulation Talent Scarcity:Industrial-scale expertise in non-flammable electrolyte salt synthesis remains concentrated among a limited cohort of Japanese and South Korean material specialists.
- UN 38.3 Certification Timelines:Extended safety testing protocols for air transport classification are compressing product launch windows for suppliers serving cross-border e-commerce channels.
- Legacy BMS Integration Friction:Electrification retrofits of internal combustion platforms require 18650 pack voltage and communication protocol adaptation, complicating OEM validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 18650 Lithium Battery for Electric Vehicle Market |
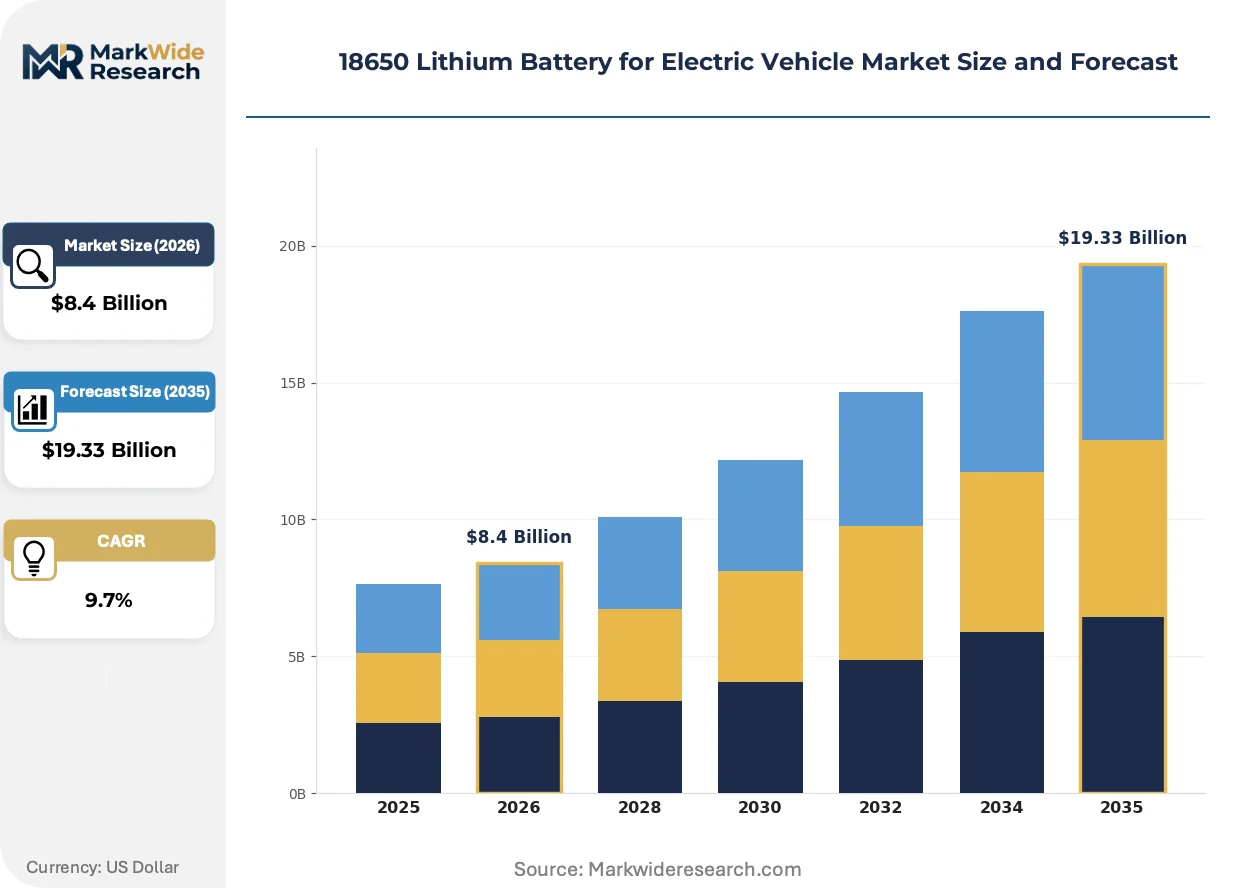
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, High Capacity, High Discharge, Cylindrical End User: OEMs, Aftermarket Providers, Fleet Operators, Manufacturers Technology: LFP, NMC, NCA, LTO Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, E-Bikes |
| Companies Covered | Panasonic, Samsung SDI, LG Chem, CATL, BYD, Sony, Tianjin Lishen, Hefei Guoxuan, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
18650 Lithium Battery for Electric Vehicle Market Trends and Innovations
Electrolyte chemistry evolution and cell-to-pack thermal management architectures are redefining performance benchmarks and supplier capability requirements across the 18650 EV battery category.
Solid-state electrolyte research is migrating from laboratory demonstration to pilot-scale 18650 prototyping, with sulfide-based ceramic-polymer composites targeting 4.5V-class cathode stability. Korean material houses are accelerating sample programs for European premium e-bike OEMs. This migration is compressing the performance gap between liquid and solid-state systems ahead of full commercialization.
REACH substance screening under EU Battery Regulation Article 6 is forcing electrolyte additive substitution across cobalt-intensive chemistries. The industrial consequence is a supply chain scramble for phosphorus-based flame retardants and fluorine-reduced conductive salts. High-nickel NMC cells for German automotive qualification are experiencing the most acute reformulation pressure.
Direct-to-fleet procurement platforms are disintermediating traditional distributor networks for light commercial vehicle operators in California and Texas. Telematics-integrated pack monitoring is replacing upfront capital purchase with usage-based service contracts. This channel compression is most visible among North American last-mile delivery consolidators optimizing total cost of ownership metrics.
18650 Lithium Battery for Electric Vehicle Market Segmentation
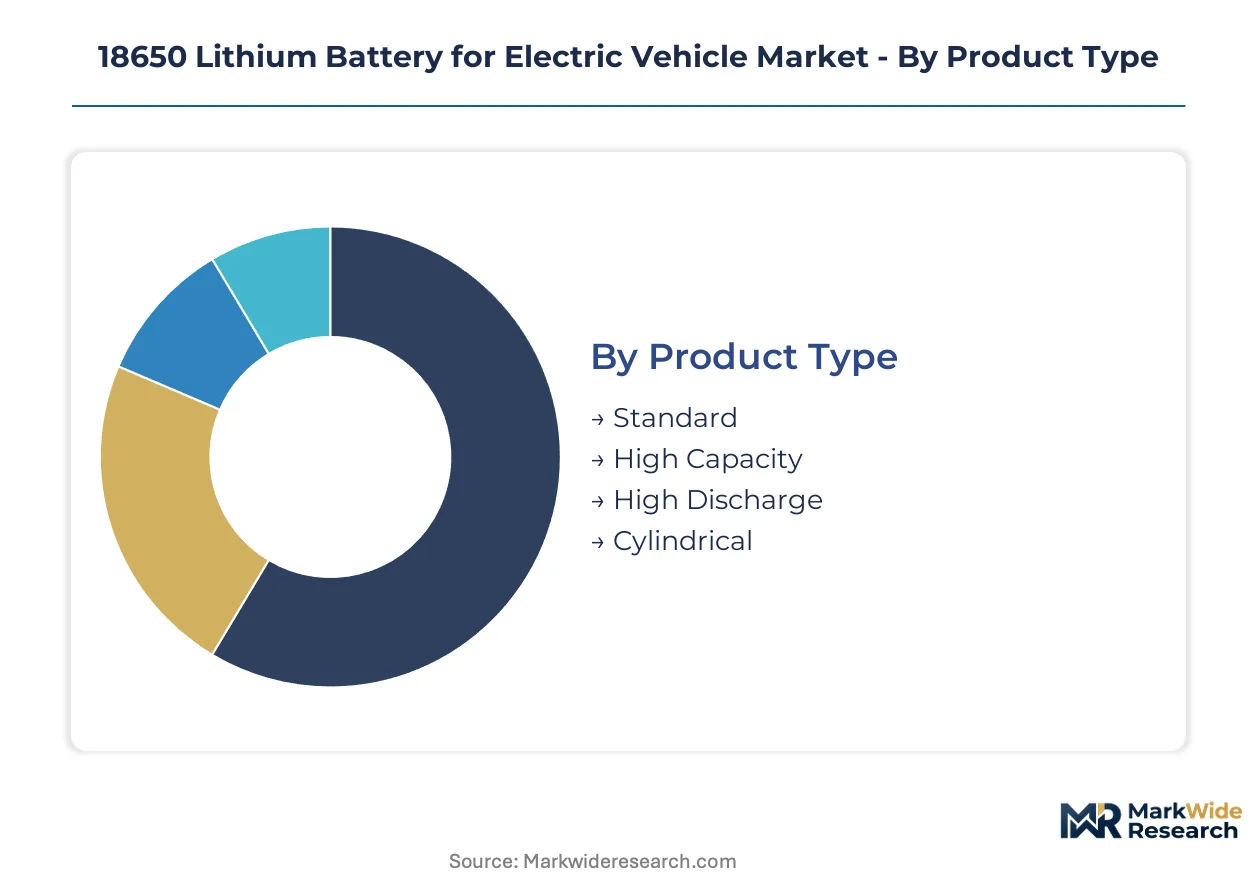
Segmentation in the 18650 EV battery market determines procurement patterns across divergent thermal management requirements and cycle-life expectations. Fleet operators prioritize standardized pack architectures for swap compatibility, while OEMs demand chemistry-specific qualification protocols that lock in multi-year supply relationships.
Product Type:
After-sales-service intensity varies dramatically across product tiers, with high-discharge variants demanding specialized diagnostic equipment and field replacement training that aftermarket providers must maintain.
- Standard:Cells delivering 2,000–2,600 mAh capacity dominate light commercial van retrofit programs across California and Texas last-mile delivery corridors, where modular swap systems reduce vehicle downtime. Fleet operators in these markets prioritize interchangeability over peak performance.
- High Capacity:Silicon-carbon composite anodes extend gravimetric energy density to 3,500 mAh for premium e-bike OEMs competing on range specifications in German and Dutch urban mobility markets. Demand concentrates among European manufacturers qualifying for EU Battery Regulation Article 6 compliance.
- High Discharge:Power-dense configurations serve power tool and performance e-mobility segments requiring sustained 10C+ discharge rates.
- Cylindrical:The foundational 18mm × 65mm form factor retains manufacturing scale advantages in Jiangsu province and Shenzhen corridor cell plants.
Standard product types hold the largest share; momentum sits with high capacity variants.
End User:
Cost tier stratification separates capital-intensive OEM qualification programs from working-capital-light aftermarket trading relationships.
- OEMs:Long-term supply agreements lock in multi-year offtake volumes with chemistry-specific validation cycles tied to UN 38.3 certification timelines. German automotive qualification programs impose the most stringent reformulation requirements for high-nickel NMC cells.
- Fleet Operators:Direct procurement platforms in North America are disintermediating distributor networks, with telematics-integrated pack monitoring enabling usage-based service contracts rather than upfront capital purchase.
- Aftermarket Providers:Independent service networks manage cell replacement logistics for out-of-warranty electric two-wheeler fleets across Southeast Asian urban corridors.
- Manufacturers:Pack integrators serving niche mobility applications require flexible volume commitments below OEM minimum order thresholds.
OEMs anchor volume concentration; fleet operators are expanding most quickly.
Technology:
Application severity dictates chemistry selection, with thermal runaway tolerance and fast-charge capability driving divergent formulation priorities.
- NMC:Nickel-manganese-cobalt cathodes occupy the premium tier for passenger vehicle energy density requirements, though DRC-origin cobalt processing bottlenecks amplify raw material cost volatility. Korean material houses dominate high-nickel precursor supply.
- LFP:Lithium-iron-phosphate formulations trade energy density for cycle-life stability and thermal safety, penetrating commercial vehicle segments where total cost of ownership calculations favor longevity over range.
- NCA:Nickel-cobalt-aluminum variants serve high-performance applications requiring extreme gravimetric density.
- LTO:Lithium-titanate oxide anodes enable 10,000+ cycle lifespans for heavy-duty commercial vehicles with intensive duty cycles.
NMC retains revenue concentration; LFP gains share fastest.
Application:
Geographic clustering aligns application demand with regional mobility infrastructure and regulatory incentive structures.
- Two-Wheelers:Battery-as-a-service leasing models are emerging for electric scooter fleets in Indonesian and Vietnamese urban corridors, decoupling cell ownership from vehicle acquisition. India's PLI scheme for advanced chemistry cells redirects investment toward Gujarat manufacturing zones.
- E-Bikes:Premium European OEMs drive qualification requirements for sulfide-based solid-state electrolyte prototypes, with Korean material houses accelerating sample programs.
- Passenger Vehicles:Compact vehicle classes retain 18650 compatibility, though prismatic format substitution constrains addressable market expansion above this segment.
- Commercial Vehicles:Light van electrification concentrates procurement in North American last-mile delivery networks.
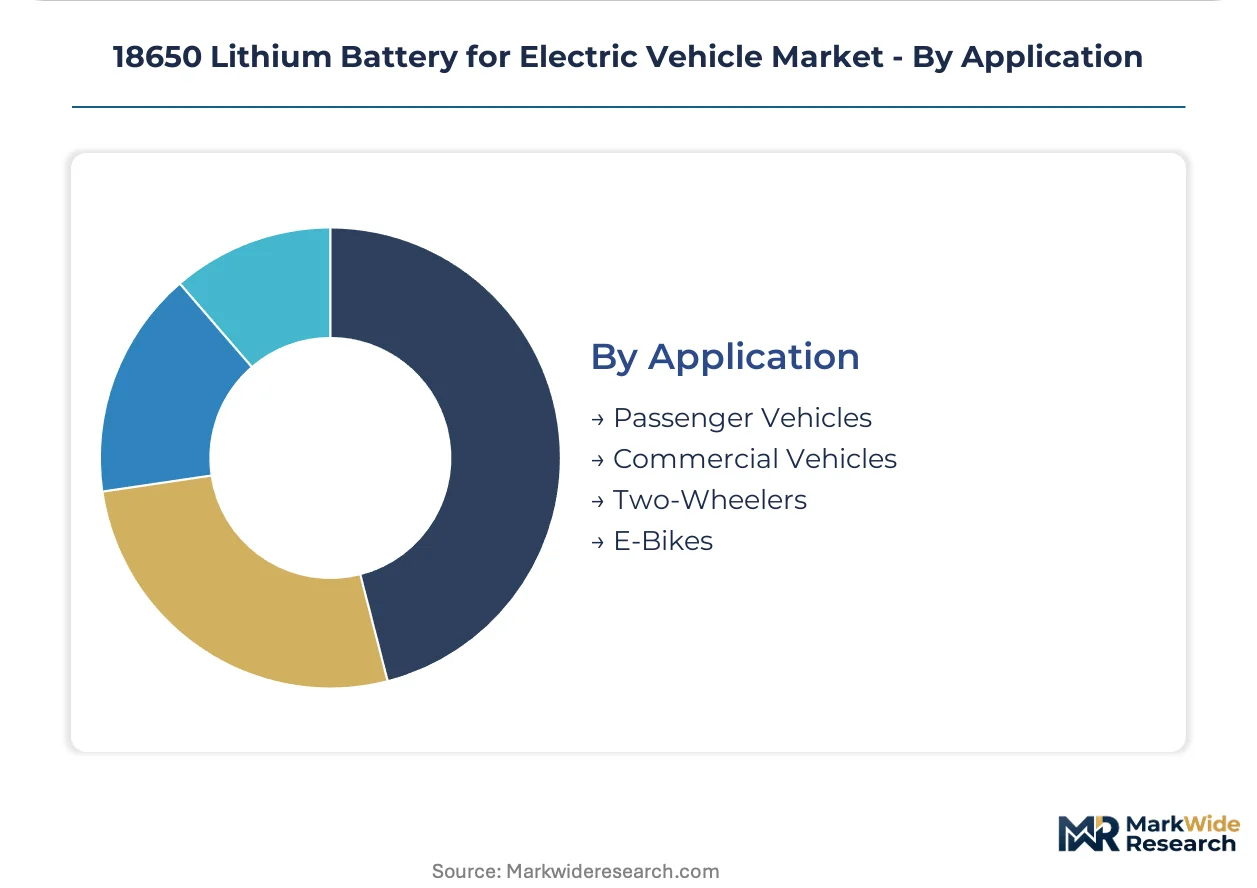
Two-wheelers hold the largest addressable volume; e-bikes show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in 18650 cells tilt toward net surplus positions in East Asian manufacturing corridors, while European and North American markets absorb cross-border shipments to feed fleet electrification programs. Currency hedging and tariff engineering now determine contract viability more than unit economics alone.
China
Jiangsu province cell plants supply NMC-format packs for light commercial van retrofits across domestic logistics networks. MIIT enforcement of GB/T 31484-2015 cycle-life benchmarks filters subscale producers from qualification pipelines. The greater Shenzhen manufacturing corridor concentrates high-capacity variant output for premium e-bike OEMs.
United States
California and Texas last-mile delivery operators scale direct procurement platforms for modular swap-compatible pack architectures. NHTSA thermal runaway protocols and UN 38.3 certification timelines compress product launch windows for cross-border suppliers. Telematics-integrated battery-as-a-service leasing decouples cell ownership from vehicle acquisition in urban freight corridors.
Germany
Premium e-bike OEMs drive qualification requirements for sulfide-based solid-state electrolyte prototypes from Korean material houses. ECHA REACH substance restrictions on nickel compounds elevate reformulation costs for high-nickel NMC cells. The Baden-Württemberg automotive cluster anchors chemistry-specific validation cycles tied to OEM multi-year offtake agreements.
India
Gujarat and Tamil Nadu manufacturing zones attract cathode precursor investment redirected by the PLI scheme for advanced chemistry cells. BIS certification requirements reshape import substitution patterns for electric two-wheeler fleets. Battery-as-a-service leasing models emerge for scooter operators in Indonesian and Vietnamese urban corridors served by Indian pack integrators.
South Korea
High-nickel precursor supply from Korean material houses accelerates sample programs for European solid-state electrolyte qualification. MFDS-equivalent safety benchmarking and R&D intensity in ceramic-polymer composites sustain competitive positioning. The Busan-Ulsan industrial corridor concentrates electrolyte salt synthesis expertise among a limited specialist cohort.
18650 Lithium Battery for Electric Vehicle Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with cathode precursor and electrolyte formulation capabilities. The supplier base consolidates around three structural tiers: captive automotive divisions, independent cell manufacturers, and material-focused chemical conglomerates. Chemistry standardization around high-nickel NMC compresses differentiation, forcing backward integration into mining partnerships and forward integration into pack assembly. Geographic diversification and capacity expansion represent the dominant competitive moves as tariff exposure reshapes footprint decisions.
Among East Asian fabricators, Panasonic Corporation, Samsung SDI Co., Ltd., and LG Chem Ltd. occupy positions spanning the integrated system tier. These entities exemplify the chemical-to-cell conglomerate archetype, with organizational structures reflecting captive control over cathode material production and downstream pack integration. Their geographic footprints span multiple continents, insulating contract viability from single-jurisdiction regulatory shifts. Chinese specialists including Contemporary Amperex Technology Co., Limited and BYD Company Limited represent the scale-driven domestic market anchor archetype, with corporate forms emphasizing vertical scope from mineral processing through vehicle deployment.
| Leading Market Players |
|---|
| Panasonic |
| Samsung SDI |
| LG Chem |
| CATL |
| BYD |
| Sony |
| Tianjin Lishen |
| Hefei Guoxuan |
| Hitachi |
| Others |
Pricing and Supply Chain Analysis
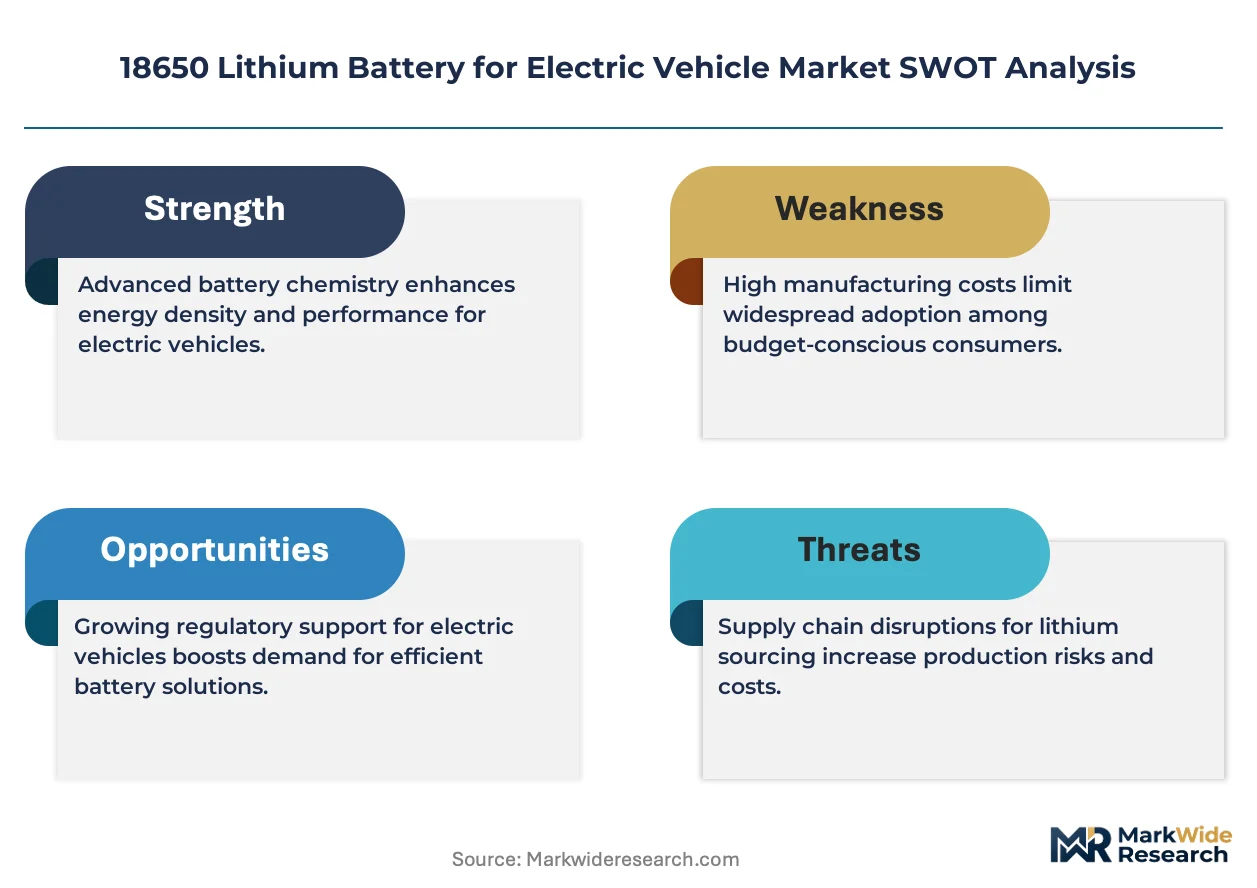
DRC-origin cobalt processing bottlenecks determine both pricing tier spreads and supply chain shape across the 18650 EV battery market, compressing margins for high-nickel NMC cathode producers while forcing geographic diversification into Indonesian nickel matte corridors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the 18650 EV battery market. Pricing stratifies across premium NMC, standard LFP, and economy-tier cylindrical configurations, with certification grade under EU Battery Regulation and volume scale serving as primary differentiation drivers. Cost compression in high-nickel cathode tiers is intensifying because Indonesian export licensing amplifies raw material cost volatility. Fleet operators exhibit highest price sensitivity due to total cost of ownership calculations, while premium e-bike OEMs prioritize energy density over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for 18650 cell suppliers. Manufacturing concentrates in China, South Korea, and Japan, with cathode precursor synthesis drawing from DRC cobalt, Indonesian nickel, and Chilean lithium deposits. Single-source vulnerability in electrolyte salt synthesis rests on concentrated Japanese and South Korean specialist capacity. Distribution runs through direct-to-fleet procurement platforms in North America and OEM supply agreements in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 18650 lithium battery for electric vehicle market sits in early-cycle expansion, with battery-as-a-service leasing models accelerating fleet electrification penetration across North American last-mile delivery corridors.
For Market Incumbents: Build captive cathode material production moats to offset DRC cobalt volatility and Indonesian nickel licensing friction. Samsung SDI and LG Chem exemplify R&D intensity in high-nickel chemistries as defensive positioning against prismatic format substitution. Capacity addition in Gujarat and Tamil Nadu manufacturing zones captures India PLI scheme localization incentives. Certification investment for EU Battery Regulation REACH compliance preserves German automotive qualification pipelines.
For New Entrants and Emerging Players: Mid-market fleet operators in California and Texas represent the most penetrable entry point, where telematics-integrated pack monitoring enables usage-based service contracts without upfront capital barriers. Southeast Asian electric two-wheeler battery-as-a-service leasing in Indonesian and Vietnamese urban corridors offers secondary white-space expansion. Go-to-market execution should anchor on direct procurement platform partnerships rather than traditional distributor network replication.
For Investors and Strategic Acquirers: China's MIIT enforcement of GB/T 31484-2015 cycle-life benchmarks reshapes the acquisition landscape by filtering subscale Jiangsu province producers from qualification pipelines. Long-term viability centers on electrolyte formulation talent scarcity and solid-state interface convergence capabilities across the projection horizon. Target acquisition archetypes include Korean material houses with ceramic-polymer composite R&D depth. The signal to watch is hybrid solid-liquid electrolyte architecture pilot-scale validation timelines for premium e-bike OEM qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Panasonic's captive supply of nickel-manganese-cobalt materials sustains margin control against raw material volatility. |
| Geographic Manufacturing Footprint Expansion | LG Chem's multi-continental cell plants insulate contract viability from single-jurisdiction tariff exposure. |
| Battery-as-a-Service Platform Development | Telematics-integrated leasing decouples cell ownership from vehicle acquisition for North American fleet operators. |
| Solid-State Electrolyte R&D Partnership | Korean material houses accelerate sulfide-based ceramic-polymer composite sample programs for German e-bike OEMs. |
| India PLI Localization Investment | Cathode precursor capacity in Gujarat and Tamil Nadu redirects supply chains toward BIS-certified domestic qualification. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Plant managers at Jiangsu province cell facilities, procurement leads at North American last-mile delivery fleet operators, technical R&D directors at Korean material houses, and aftermarket service heads across Southeast Asian urban corridors provided operational perspective. Secondary validation drew from MIIT GB standard publications, ECHA REACH substance restriction databases, India PLI scheme administrative guidance, and UN 38.3 certification timelines. Bottom-up cell production estimates and top-down electric vehicle deployment trajectories were reconciled through iterative triangulation.
Calibration against historical capacity expansion patterns and raw material cost cycles informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-user channel structure, cathode chemistry format, and regional manufacturing cluster. CAGRs were derived from slope-intercept fitting of qualified production capacity against electric two-wheeler and light commercial vehicle adoption curves. Industry-specific forecast inputs incorporated silicon anode infusion penetration rates and solid-state electrolyte pilot-scale validation milestones.
Practitioners should monitor Indonesian nickel export licensing decisions, EU Battery Regulation Article 6 enforcement timing, and prismatic format substitution velocity in compact passenger vehicle classes for early signals. Forecasts reflect assumptions regarding GB standards compliance filtration rates and PLI scheme incentive continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
Lithium Sulfur Dioxide Battery Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market