
 Automotive Lithium Ion Battery Market | 2026-2036
Automotive Lithium Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lithium Ion Battery Market Analysis
Cell-grade pricing is rebalancing between nickel-cobalt formulations and iron-phosphate platforms as automakers split procurement across range-extended premium lines and cost-optimized volume models. CATL dominates cylindrical and prismatic output for European and Chinese OEM programs. BYD leverages captive LFP supply to anchor vertical integration across passenger and commercial vehicle segments. Samsung SDI competes in the premium pouch cell tier where energy density thresholds exceed 300 Wh per kilogram.
Automotive lithium ion batteries are rechargeable electrochemical cells employing lithium intercalation compounds at the cathode and graphite or silicon-blend anodes, typically operating at nominal voltages of 3.2 to 3.7 volts per cell with cycle life ratings exceeding 1,000 deep discharges. Their primary commercial purpose is to store and deliver traction energy for electric propulsion systems in road vehicles. Prismatic cells occupy the dominant share in passenger vehicle battery packs due to space-efficient stacking and thermal management integration. LFP chemistry leads volume growth in commercial vehicle and two-wheeler applications where cost per kilowatt-hour and thermal stability outweigh energy density priorities. NMC formulations retain margin concentration in premium passenger vehicles where OEMs specify maximum range per charge.
China's MIIT enforces GB standards for cell safety and recycling traceability, while the EU's Battery Regulation mandates carbon footprint disclosure and recycled content quotas for market access. The US EPA and NHTSA coordinate tailpipe and fuel economy rules that indirectly mandate electrification share targets for domestic OEM fleets. Stakeholders must monitor divergence between regional compliance regimes as they decide localization strategies for cell production and active material refining.
Market Dynamics
Cell chemistry bifurcation between nickel-cobalt and iron-phosphate platforms is fragmenting procurement strategies as automakers segment their lineups between range-optimized premium vehicles and cost-driven volume production.
Growth Catalysts
- EU Battery Regulation:Mandates for carbon footprint disclosure and recycled content quotas are accelerating investment in closed-loop refining infrastructure across European manufacturing zones.
- Urban transit electrification:Municipal bus fleet procurement in Chinese megacities is absorbing multi-gigawatt-hour annual cell volumes through centralized tender processes.
- Solid-state pilot lines:Semi-solid electrolyte formulations are progressing from laboratory validation to automotive qualification cycles with energy density targets above four hundred watt-hours per kilogram.
Market Restraints
- Cathode material concentration:Refined lithium and cobalt processing capacity clusters in the Democratic Republic of Congo and Chilean salar basins, creating single-source vulnerability for tier-one cell manufacturers.
- GB standards compliance:China's MIIT certification timelines for cell safety and recycling traceability extend qualification periods by twelve to eighteen months for non-domestic suppliers.
- Silicon anode swelling:Volume expansion during lithiation cycles above three hundred percent limits silicon-blend anode substitution rates in prismatic cell designs.
Strategic Opportunities
- Second-life stationary storage:Decommissioned automotive packs with seventy percent remaining capacity are redirecting toward grid-scale buffering installations in German and Californian utility territories.
- Direct cathode recycling:Hydrometallurgical recovery processes that preserve crystal structure are reducing active material reprocessing energy by sixty percent versus conventional smelting routes.
- India PLI scheme:Production-linked incentives for cell and module manufacturing are attracting gigafactory commitments from Korean and Chinese suppliers to Gujarat and Tamil Nadu industrial corridors.
Industry Challenges
- Thermal runaway containment engineering:Propagation prevention between adjacent cells requires multi-layer ceramic coatings and venting architectures that extend pack design cycles.
- Battery management system firmware validation:Functional safety certification to ISO 26262 ASIL-D standards demands million-kilometer equivalent testing before production release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lithium Ion Battery Market |
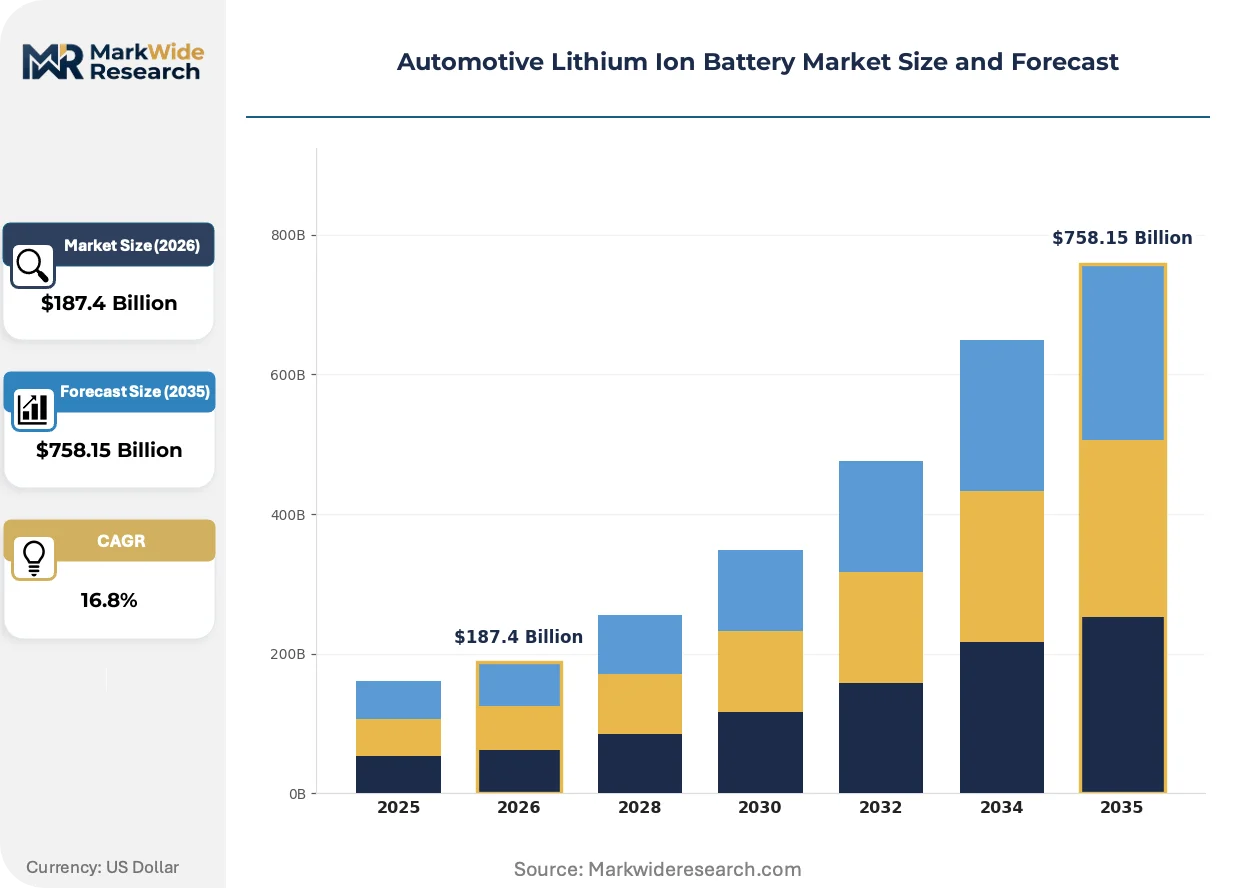
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic Cells, Cylindrical Cells, Pouch Cells, Module Packs Technology: NMC, LFP, NCA, Graphene Application: Passenger Vehicles, Commercial Vehicles, Electric Buses, Two-wheelers End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators |
| Companies Covered | SK On, EVE Energy, CATL, Gotion High-Tech, Samsung SDI, BYD, Panasonic, SVOLT, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lithium Ion Battery Market Emerging Trajectories
Manufacturing process innovation and chemistry platform diversification are compressing cell cost curves while elevating performance thresholds for next-generation electric vehicle architectures.
Cell-to-pack architectures are eliminating modular grouping structures and integrating cooling channels directly into the structural battery enclosure. Chinese and European OEMs are qualifying these designs for their 2027 model year platforms. The approach is decentralizing thermal management component sourcing from specialized subsystem suppliers toward in-house pack assembly operations.
REACH substance restrictions on nickel compounds are compelling cathode suppliers to accelerate low-cobalt NMCA formulations and high-voltage LFP variants. The regulation is forcing reformulation of electrolyte additives to maintain cycle stability under elevated operating voltages. Premium passenger vehicle programs in Germany and Scandinavia are absorbing the cost premiums to maintain access to the European market.
Fleet operators are consolidating procurement through battery-as-a-service contracts that unbundle cell ownership from vehicle acquisition. Logistics and ride-hail operators in Shenzhen and São Paulo are piloting per-kilometer usage fees with guaranteed residual value recovery. This model is concentrating negotiating leverage among large fleet aggregators and compressing margin capture for cell manufacturers.
Automotive Lithium Ion Battery Market Segmentation
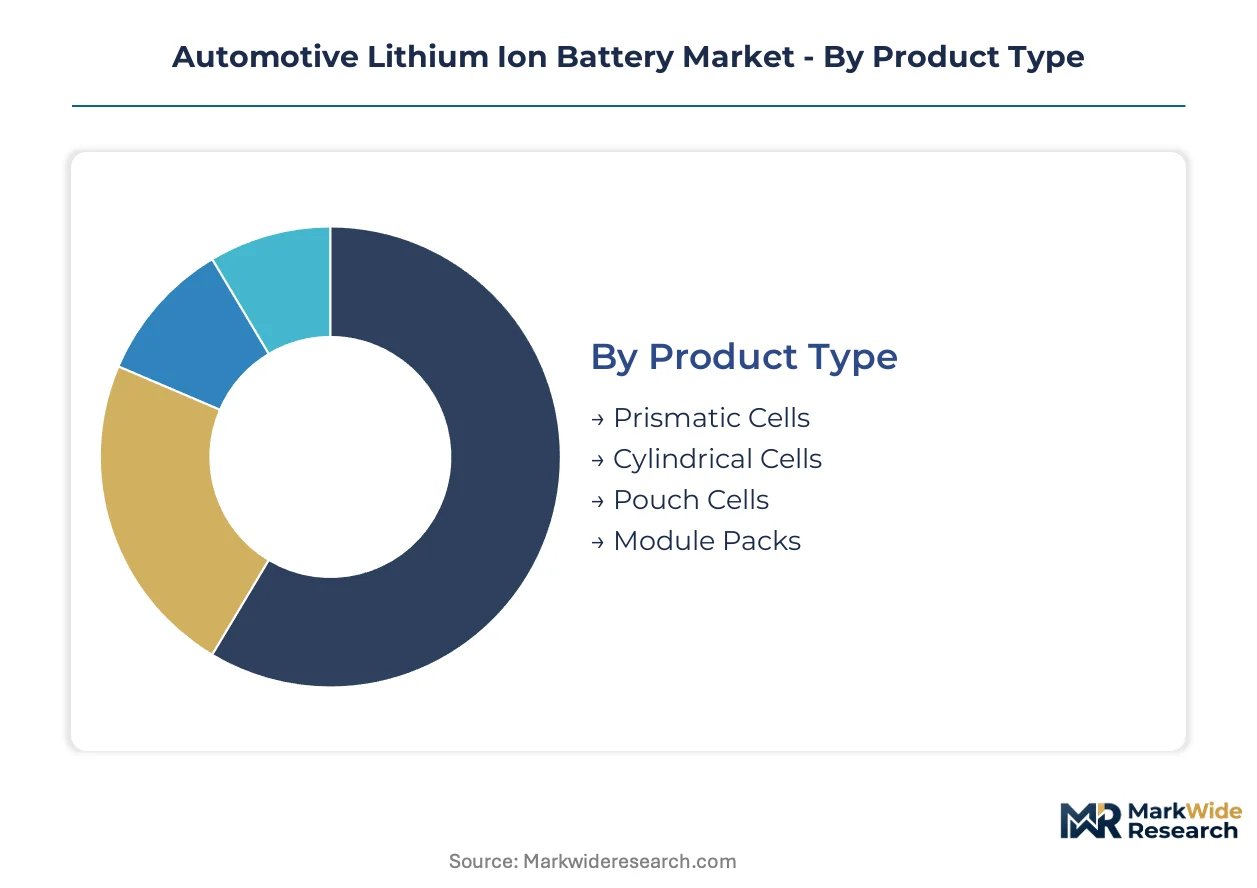
Cell form factor, cathode chemistry, vehicle class, and supply chain position each impose distinct capital requirements and margin structures. Procurement patterns diverge sharply across these dimensions as automakers balance energy density targets against thermal stability and unit economics.
Product Type:
Prismatic cell production demands the heaviest upfront tooling investment due to precision stacking equipment and cleanroom infrastructure requirements.
- Prismatic Cells:Aluminum-housed rectangular cells stack directly into pack enclosures without cylindrical spacing losses. CATL and BYD anchor multi-gigawatt-hour output corridors in Jiangsu and Guangdong provinces serving domestic Chinese OEMs and European export programs.
- Cylindrical Cells:Rolled electrode jellyrolls in steel cans tolerate higher internal pressures and enable automated winding at speed. Tesla's 4680 format and legacy 2170 supply chains concentrate cylindrical demand in Nevada and Shanghai manufacturing zones.
- Pouch Cells:Laminated aluminum polymer housings maximize packaging efficiency for premium sedan platforms.
- Module Packs:Pre-assembled cell groupings with integrated battery management hardware streamline OEM final assembly.
Prismatic cells absorb the bulk of installed capacity; cylindrical formats are expanding most quickly.
Technology:
Cathode active material selection governs both raw material exposure and manufacturing process complexity.
- NMC:Nickel-manganese-cobalt layered oxides deliver highest energy density for range-critical passenger applications. European premium OEMs specify high-nickel variants despite cobalt supply concentration in the Democratic Republic of Congo.
- LFP:Lithium iron phosphate eliminates cobalt entirely and tolerates thermal abuse without oxygen release. BYD's Blade Battery architecture and CATL's cell-to-pack LFP designs dominate commercial vehicle and entry passenger segments in China.
- NCA:Nickel-cobalt-aluminum cathodes occupy a narrowing premium niche where cylindrical cell formats prevail.
- Graphene:Conductive additive enhancements for fast-charge anode formulations remain at pilot scale.
LFP chemistry commands the greatest production volume; NMC retains the steepest expansion trajectory in premium segments.
Application:
Vehicle duty cycles determine thermal management intensity and cycle life specifications.
- Passenger Vehicles:Light-duty platforms prioritize gravimetric energy density and fast-charge capability. Pack sizes range from 50 to 120 kilowatt-hours across European and Chinese model lineups.
- Commercial Vehicles:Delivery vans and medium-duty trucks demand calendar life exceeding eight years under continuous cycling. LFP chemistry dominates this segment due to cost per kilowatt-hour and thermal stability.
- Electric Buses:Urban transit fleets operate predictable routes with overnight depot charging.
- Two-wheelers:Swappable battery formats for electric scooters concentrate demand in Indian and Southeast Asian urban corridors.
Passenger vehicles absorb the bulk of installed capacity; commercial vehicles are expanding most quickly.
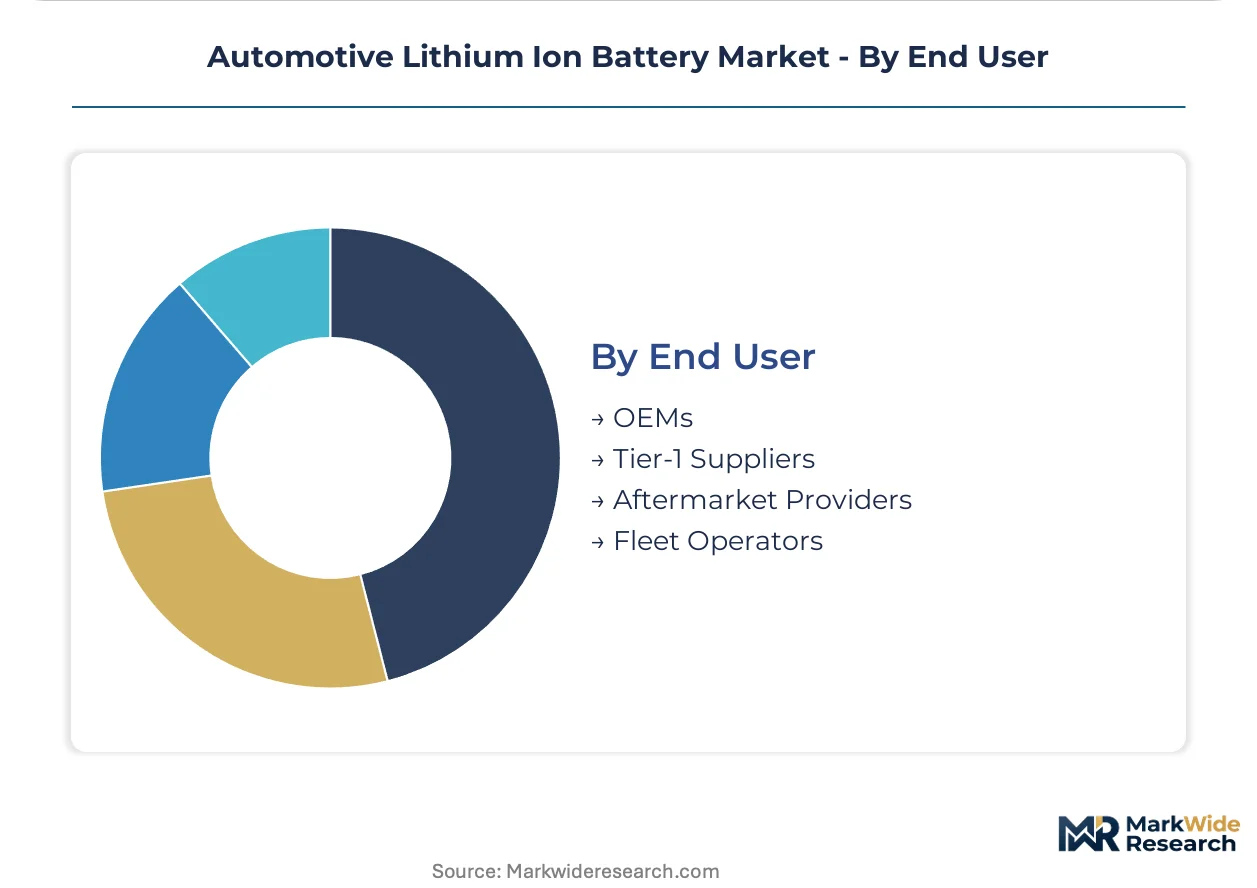
End User:
Direct versus indirect procurement relationships reshape pricing power and technical specification control.
- OEMs:Volkswagen, BYD, and Tesla operate captive cell supply agreements or in-house production. Direct procurement locks in volume commitments across multi-year platform cycles.
- Tier-1 Suppliers:Bosch, CATL, and LG Energy Solution deliver complete pack assemblies with integrated thermal management. These suppliers retain cell chemistry selection authority within OEM performance envelopes.
- Aftermarket Providers:Replacement pack suppliers serve aging first-generation electric vehicle fleets.
- Fleet Operators:Ride-hail and logistics aggregators negotiate battery-as-a-service contracts decoupling cell ownership from vehicle acquisition.
OEMs absorb the bulk of installed capacity; fleet operators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Changzhou anchors the world's densest concentration of automotive lithium ion cell manufacturing, with CATL's headquarters and adjacent supplier parks processing cathode materials from nearby Zhenjiang refineries.
China
Urban transit electrification in Shenzhen and Guangzhou absorbs multi-gigawatt-hour annual volumes through municipal tender processes. MIIT enforces GB standards for cell safety certification and recycling traceability that extend qualification timelines for non-domestic suppliers. Jiangsu and Guangdong provinces host gigafactory clusters where CATL and BYD serve domestic OEMs and European export programs.
Germany
Premium passenger vehicle programs from Stuttgart and Munich OEMs specify high-nickel NMC formulations despite cobalt supply concentration risks. REACH substance restrictions on nickel compounds accelerate low-cobalt NMCA cathode development and high-voltage LFP variants. The Eifel region and Saxony host cell assembly operations feeding pack integration plants in Lower Saxony.
United States
IRA production tax credits attract Korean and Chinese suppliers to establish cell manufacturing in Nevada and Georgia. EPA and NHTSA coordinate tailpipe and fuel economy rules that mandate electrification share targets for domestic OEM fleets. The Detroit Three anchor demand concentration in the Midwest while Tesla's cylindrical cell demand concentrates in Austin and Fremont zones.
South Korea
Premium pouch cell demand for European luxury OEMs drives qualification cycles for energy density thresholds exceeding 300 watt-hours per kilogram. METI-aligned technical standards and KBA homologation requirements shape export-oriented product development. Gyeonggi and Chungnam provinces host cathode material refining and cell assembly corridors serving German and US automotive customers.
India
Two-wheeler swappable battery formats concentrate demand in Bengaluru and Delhi urban corridors for electric scooter fleet operators. PLI scheme production-linked incentives attract gigafactory commitments from Korean and Chinese suppliers to Gujarat and Tamil Nadu industrial zones. BIS certification timelines for cell safety create entry barriers that favor early movers with established testing relationships.
Automotive Lithium Ion Battery Market Vendor Landscape
Premium-margin players sit above commodity-margin players across chemistry specialization and integration depth. The vendor base organizes into three tiers: captive cell producers serving affiliated OEMs, independent suppliers delivering to multiple automakers, and specialist manufacturers focused on single form factors or chemistries. Capacity expansion and strategic raw material partnerships constitute the dominant competitive moves as firms secure lithium and cobalt offtake agreements.
Among Korean suppliers, SK On and Samsung SDI occupy positions within the premium-tier pouch and cylindrical segments, while LG Energy Solution exemplifies the independent multi-customer archetype serving European and North American OEMs simultaneously. Chinese players CATL and BYD anchor the scale-driven end, with the former representing the independent supplier model across chemistry platforms and the latter exemplifying captive vertical integration from mining through vehicle assembly. Panasonic occupies a specialized position in cylindrical formats tied to specific OEM partnerships.
| Leading Market Players |
|---|
| SK On |
| EVE Energy |
| CATL |
| Gotion High-Tech |
| Samsung SDI |
| BYD |
| Panasonic |
| SVOLT |
| LG Energy Solution |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China's Jiangsu and Guangdong corridors anchor cell manufacturing capacity, translating state-supported financing into aggressive pricing discipline that compresses margins for independent suppliers serving European and North American OEMs. This ownership pattern feeds directly into procurement strategies, as automakers split volume commitments between cost-optimized iron-phosphate platforms and premium nickel-cobalt formulations.
Pricing Analysis
Energy-density-based pricing anchors contract structures, with premium passenger vehicle programs absorbing cost premiums for high-nickel NMC cells exceeding three hundred watt-hours per kilogram. Price differentiation separates certified automotive-grade supply meeting GB standards and ISO 26262 from industrial-grade alternatives. Cost compression in iron-phosphate tiers is intensifying because BYD and CATL scale cell-to-pack architectures. Fleet operators negotiating battery-as-a-service contracts exhibit highest price sensitivity; German luxury OEMs remain least sensitive.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Volkswagen, BYD, and Tesla, while tier-1 integrators like LG Energy Solution and SK On serve multi-customer portfolios. Raw material refining concentrates in Chilean salar basins for lithium and the Democratic Republic of Congo for cobalt, with cathode precursor processing anchored in China and South Korea. Single-source vulnerability in cobalt offtake creates structural risk. Distribution runs through long-term contract offtakes rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's carbon footprint disclosure mandates and recycled content quotas erect compliance barriers that favor incumbents with established closed-loop refining infrastructure, transforming regulatory adherence into a sustainable competitive moat.
For Market Incumbents: Hedge against silicon-anode substitution limits by diversifying cathode chemistry portfolios across LFP and low-cobalt NMCA variants. Secure lithium offtake agreements in Australian and Chilean mining corridors before resource nationalism tightens export controls. Defensive consolidation through acquisition of direct cathode recycling specialists preserves margin structure against hydrometallurgical disruptors. For New Entrants and Emerging Players: Capture white-space in India's PLI-subsidized manufacturing zones where BIS certification barriers have slowed Korean and Chinese supplier timelines. Target two-wheeler swappable battery formats in Bengaluru and Delhi corridors where fleet operators seek alternatives to incumbent pricing. Pursue joint-venture structures with established cathode material refiners to bypass eighteen-month MIIT qualification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with captive LFP technology and existing European OEM qualification relationships in Germany's Eifel region and Saxony. Long-term viability centers on backward integration into lithium refining and recycling infrastructure rather than pure cell assembly scale. Monitor EU Battery Regulation enforcement intensity as inflection indicator for margin compression in non-compliant supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Adoption | Eliminates modular grouping costs for CATL and BYD serving 2027 European OEM platforms. |
| Direct Cathode Recycling Investment | Reduces reprocessing energy sixty percent versus smelting for German closed-loop refiners. |
| Solid-State Pilot Line Qualification | Positions Samsung SDI for premium pouch contracts exceeding three hundred Wh per kilogram. |
| Battery-as-a-Service Contracting | Concentrates fleet operator leverage in Shenzhen and São Paulo urban logistics corridors. |
| Lithium Refining Backward Integration | Secures offtake certainty for cell manufacturers facing Chilean and Australian export restrictions. |
Methodological Framework
Trade databases, MIIT certification registries, and EU Battery Regulation implementation documents formed the secondary backbone, cross-referenced against primary interviews with cell manufacturing executives, OEM platform engineers, cathode material procurement leads, and fleet operator sustainability officers. Bottom-up volume builds from individual gigafactory announcements and tender awards were triangulated against top-down demand projections derived from vehicle electrification mandates.
Bottom-up modeling tracked cell chemistry splits, form factor adoption curves, and regional production capacity across the analysis window. Segmentation dimensions included vehicle class, cathode chemistry platform, cell form factor, and supply chain position. CAGRs were derived from slope analysis of annual capacity additions against demand absorption rates. Key inputs incorporated lithium carbonate price trajectories and GB standards compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state chemistry breakthroughs and cobalt supply disruptions from central African logistics corridors. Forecasts reflect documented assumptions regarding OEM platform launch schedules and subsidy phase-out trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Anode Material for Sodium-Ion Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
Liquid Lithium Ion Battery Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market
Lithium-ion Battery
Thin Film Lithium-Ion Battery Market
Lithium-ion Battery
Global Lithium Ion Cell and Battery Pack Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market