
 Automotive 48V Lithium Battery Market | 2026-2036
Automotive 48V Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive 48V Lithium Battery Market Insights
The EU Green Deal is consolidating demand for 48V architectures across European passenger car platforms. Robert Bosch GmbH leverages its integrated powertrain division to dominate module supply for German OEM mild-hybrid programs. Valeo SA anchors its position through dedicated 48V eDrive systems, while Denso Corporation competes on thermal management integration for Asian vehicle platforms.
Automotive 48V lithium batteries are rechargeable electrochemical storage systems operating at nominal 48 volts, typically employing lithium-ion cells with nickel-manganese-cobalt or lithium-iron-phosphate cathodes to support belt-driven starter-generators and torque-assist functions. These systems enable recuperative braking energy capture and electric boost during acceleration, reducing internal combustion engine load cycles to meet fleet emissions targets. The technology dimension shows lithium-iron-phosphate chemistry extending cycle life for high-duty auxiliary power applications, while lithium-ion formulations lead drive train integration due to superior energy density. OEM end users concentrate procurement volumes through long-term supply agreements, whereas aftermarket providers occupy fragmented service and replacement channels with lower margin profiles.
EMA's battery sustainability directives and REACH chemical compliance frameworks shape cell material sourcing and end-of-life recycling obligations across European supply chains. EPA tailpipe standards and NHTSA fuel economy rules in the United States push domestic automakers toward 48V adoption as a cost-effective compliance bridge. China's SAMR enforces GB standards for power battery safety and performance, creating market access conditions for foreign cell producers. Stakeholders must monitor how regulatory stringency divergence between jurisdictions influences platform standardization decisions and supplier qualification timelines.
Market Dynamics
OEM procurement of mild-hybrid powertrains is consolidating around 48V architectures as Europe's F-Gas Regulation and CO2 fleet mandates tighten compliance windows for passenger car platforms.
Growth Catalysts
- F-Gas Regulation phase-down:The EU's hydrofluorocarbon reduction timeline accelerates automaker adoption of 48V belt-driven starter-generators to replace conventional air conditioning compressors and reduce refrigerant leakage penalties.
- CO2 fleet mandates:Germany's KBA enforces manufacturer-specific emission ceilings that make 48V torque-assist systems the lowest-cost compliance pathway for ICE-dominant vehicle portfolios.
- Lithium-iron-phosphate chemistry maturation:Cell producers in China and South Korea have scaled LFP production for auxiliary power applications, extending cycle life beyond 4,000 charge events for high-duty mild-hybrid cycling.
Market Restraints
- Cobalt and nickel price volatility:NMC cathode formulations remain exposed to London Metal Exchange commodity swings that compress module gross margins during supply disruptions.
- Cell production concentration:Cylindrical and prismatic cell supply chains cluster in China's Jiangsu and Guangdong provinces, creating single-geography dependency risks for European module assemblers.
- Full-electric substitution threat:Battery-electric platforms above 60kWh nominal capacity eliminate the 48V intermediate step entirely, capping the technology's addressable vehicle segment.
Strategic Opportunities
- Commercial vehicle electrification:Light-duty trucks and delivery vans in South Korea represent an underpenetrated application where 48V mild-hybrid architectures bridge diesel phase-out timelines without full powertrain redesign.
- India's FAME-III incentive structure:The country's Ministry of Heavy Industries is structuring production-linked incentives for hybrid component localization that could open dedicated 48V module assembly capacity.
- Thermal management convergence:Integration of 48V e-compressors with battery cooling loops creates white space for suppliers combining power electronics and HVAC expertise.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D qualification for 48V battery management systems extends development cycles by 14-18 months, compressing platform launch windows.
- Legacy 12V electrical architecture integration:DC-DC converter design complexity rises as mild-hybrid systems must maintain stable 12V supply for body electronics during 48V torque-assist events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive 48V Lithium Battery Market |
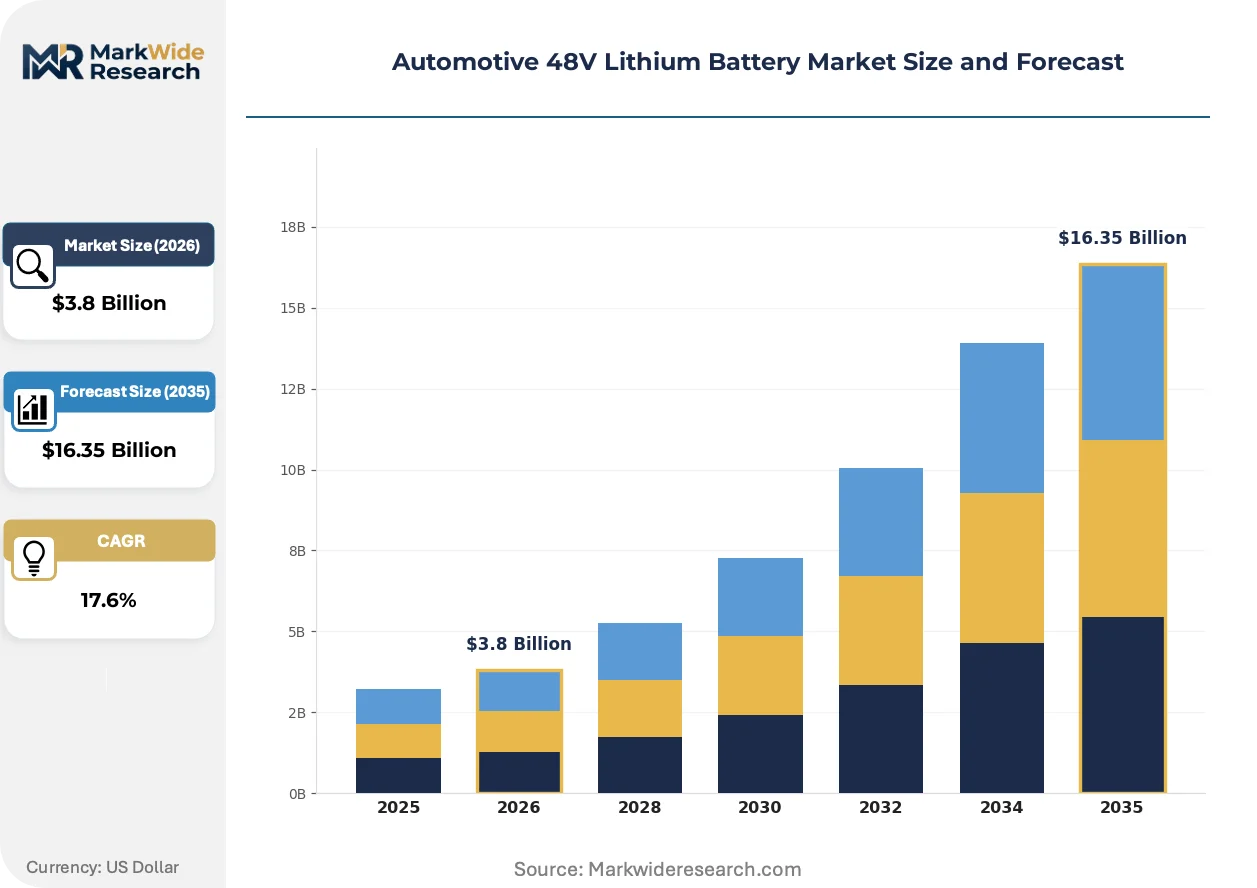
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Plug-in Hybrid, Electric Vehicle, Start-Stop System Application: Drive Train, Energy Storage, Auxiliary Power, Regenerative Braking End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Technology: Lithium-Ion, Lithium-Polymer, Lithium-Iron Phosphate, Others |
| Companies Covered | Robert Bosch GmbH, Valeo SA, BorgWarner Inc., Continental AG, Mitsubishi Electric Corporation, Denso Corporation, Hyundai Mobis Co., Ltd., Hitachi, Ltd., Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive 48V Lithium Battery Market Trends and Innovations
Cell chemistry diversification and regulatory stringency divergence are fragmenting platform standardization while creating specialization premiums for suppliers with multi-chemistry module capabilities.
Lithium-iron-phosphate formulations are overtaking nickel-manganese-cobalt in auxiliary power applications where cycle durability outweighs energy density requirements. Fleet operators in Germany specify LFP-based 48V systems for start-stop intensive urban delivery routes. This chemistry migration is compressing NMC cell pricing premiums and forcing cathode suppliers to segment production lines by duty-cycle application.
REACH chemical compliance frameworks are mandating supply chain disclosure granularity for cobalt, lithium, and graphite sourcing that extends qualification timelines for European-bound modules. The ECHA's Substances of Very High Concern candidate list now encompasses multiple electrolyte additives, forcing reformulation of thermal runaway suppression chemistries. Module producers are responding by establishing dedicated European cell finishing capacity to satisfy origin-traceability requirements.
Long-term supply agreements now dominate OEM procurement, with German and South Korean automakers locking 5-7 year volume commitments to secure allocation from constrained cell production lines. Tier-1 suppliers are displacing spot-market purchasing with captive offtake contracts that embed price-volume flex mechanisms. This contractual shift is most pronounced in Stuttgart and Seoul, where platform-specific module designs limit second-source substitution.
Automotive 48V Lithium Battery Market Segmentation
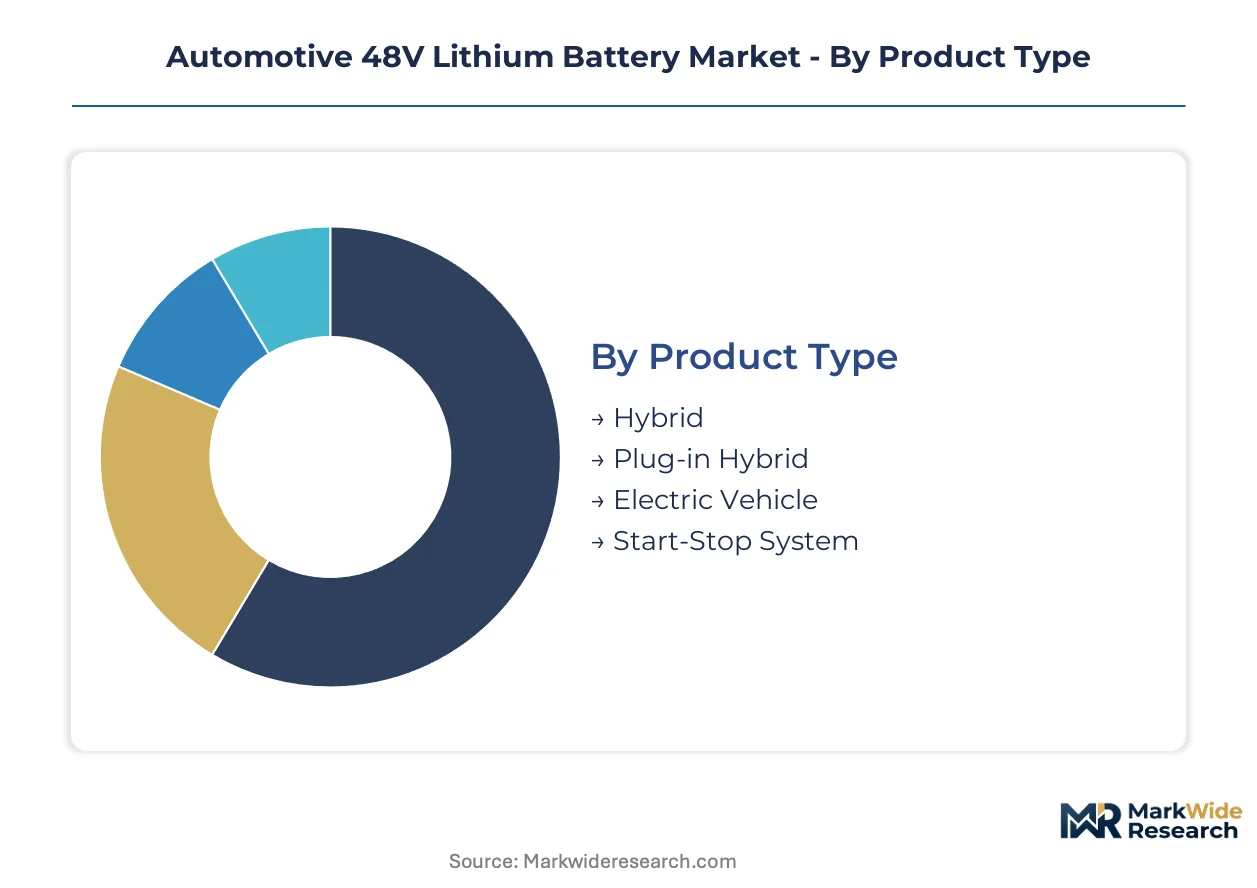
Automotive 48V lithium battery segmentation reflects divergent technical requirements across mild-hybrid architectures and full-electric transition pathways. Chemistry selection, duty-cycle intensity, and integration depth with ICE powertrains determine procurement specifications and supplier qualification criteria.
Product Type:
Technology intensity and electrification depth define cost structures and cell chemistry requirements across vehicle electrification tiers.
- Hybrid:Belt-driven starter-generator systems dominate German OEM procurement for passenger car CO2 compliance. Mild-hybrid architectures concentrate demand in Stuttgart and Wolfsburg manufacturing clusters where 48V torque-assist reduces ICE load cycles.
- Plug-in Hybrid:Dual-voltage architectures requiring 48V auxiliary support alongside high-voltage traction batteries. South Korean automakers in Seoul and Ulsan anchor procurement for PHEV platforms bridging full-electric transition timelines.
- Electric Vehicle:Auxiliary 48V systems support thermal management and power steering in full-electric architectures above 400V nominal.
- Start-Stop System:Entry-level micro-hybrid applications with shallow cycling requirements and compressed module costs.
Hybrid leads on scale; Plug-in Hybrid leads on momentum.
Application:
Functional integration depth determines thermal management complexity and cycle life specifications for 48V module suppliers.
- Drive Train:Torque-assist and electric boost functions demand high discharge-rate capability from nickel-manganese-cobalt cell formulations. German KBA emission enforcement tightens procurement specifications for drive train-integrated 48V systems in Munich and Ingolstadt production lines.
- Energy Storage:Recuperative braking energy capture requires rapid charge acceptance and calendar life stability. Chinese SAMR GB standards for power battery safety shape qualification protocols for energy storage applications in Shanghai and Shenzhen manufacturing bases.
- Auxiliary Power:HVAC and active suspension loads favor lithium-iron-phosphate chemistry for extended cycle durability.
- Regenerative Braking:Stop-start intensive urban duty cycles stress cell thermal management and state-of-charge algorithms.
Drive Train commands premium pricing; Energy Storage expands most quickly.
End User:
Procurement scale and contract structure fragment margin profiles across direct OEM supply and replacement channels.
- OEMs:Long-term supply agreements with 5-7 year volume commitments dominate Stuttgart and Seoul procurement. Platform-specific module designs limit second-source substitution for German and South Korean automakers.
- Aftermarket Providers:Fragmented service and replacement channels operate on lower margin profiles with spot-market cell purchasing.
- Fleet Operators:Urban delivery specifications in Berlin and Hamburg prioritize LFP-based 48V systems for start-stop durability.
- Vehicle Assemblers:Contract manufacturing arrangements for niche and regional vehicle platforms with limited vertical integration.
OEMs concentrate procurement volume; Fleet Operators are gaining share fastest.
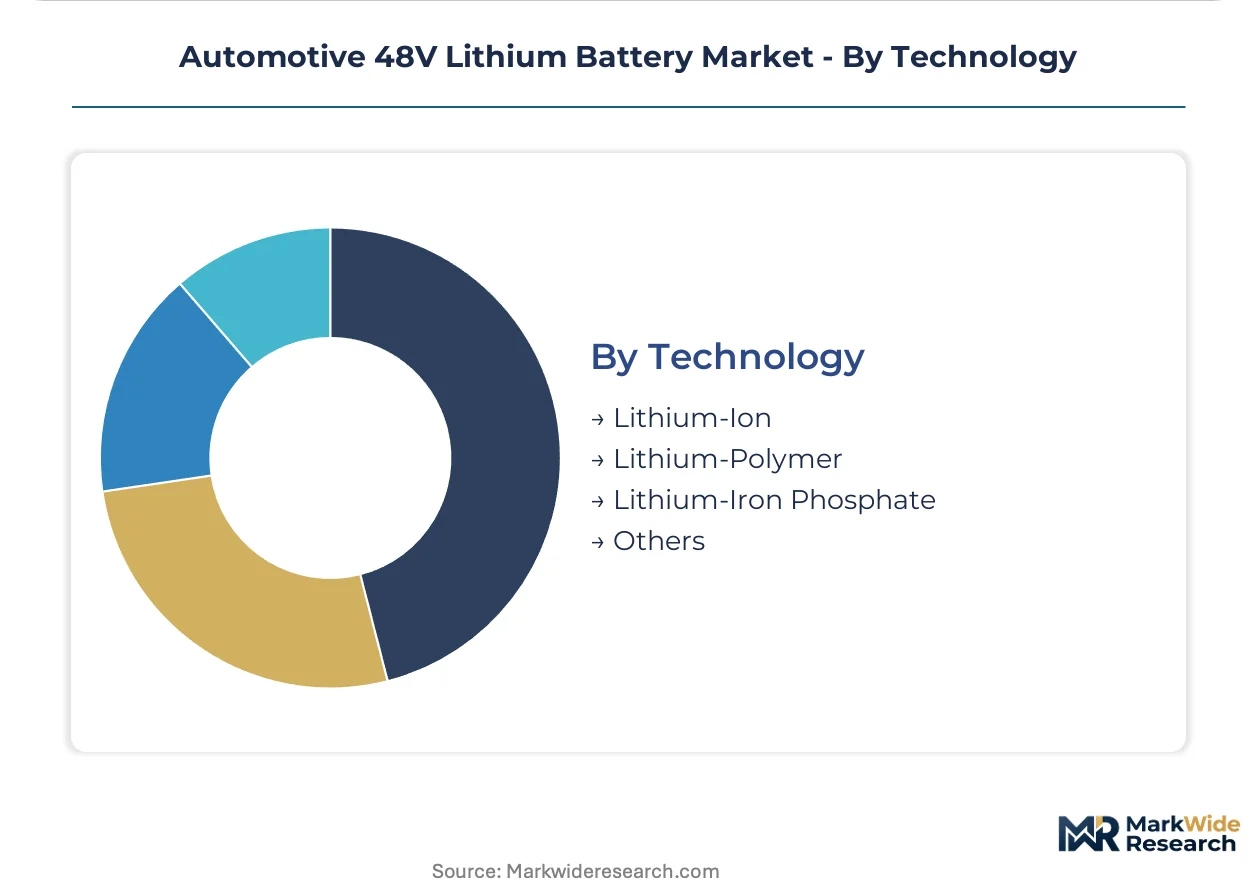
Technology:
Cell chemistry trade-offs between energy density and cycle life reshape competitive positioning across application tiers.
- Lithium-Ion:Nickel-manganese-cobalt formulations lead drive train integration due to superior gravimetric energy density. ECHA REACH compliance frameworks extend qualification timelines for European-bound lithium-ion modules.
- Lithium-Iron Phosphate:Cycle life exceeding 4,000 charge events captures auxiliary power applications. Chinese and South Korean cell producers have scaled LFP production for high-duty mild-hybrid cycling in Jiangsu and Guangdong provinces.
- Lithium-Polymer:Pouch cell configurations enable flexible module packaging for space-constrained vehicle architectures.
- Others:Emerging solid-state and sodium-ion formulations remain pre-commercial for automotive 48V applications.
Lithium-Ion dominates current procurement; Lithium-Iron Phosphate shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive electrification laid the groundwork for 48V lithium battery scaling during the 2010s, with Stuttgart and Wolfsburg engineering centers pioneering mild-hybrid architectures before regulatory mandates accelerated deployment across passenger car platforms.
Germany
KBA emission ceilings and the F-Gas Regulation phase-down drive OEM procurement of belt-driven starter-generator systems. The EU Green Deal tightens compliance windows for ICE-dominant portfolios. Module assembly concentrates in Stuttgart, where tier-1 suppliers operate dedicated production lines for premium passenger car platforms.
China
Domestic automaker demand for cost-effective CO2 reduction solutions accelerates LFP cell adoption for auxiliary power applications. SAMR enforces GB standards for power battery safety and performance, shaping qualification protocols. Cell production clusters in Jiangsu and Guangdong provinces supply both domestic module assemblers and European-bound exports.
South Korea
Seoul and Ulsan anchor PHEV platform development requiring dual-voltage auxiliary support alongside high-voltage traction batteries. The country's industrial policy supports battery component localization through production-linked incentives. Hyundai Mobis and affiliated suppliers operate integrated module assembly in the Seoul Capital Area.
United States
EPA tailpipe standards and NHTSA fuel economy rules push domestic automakers toward 48V adoption as a compliance bridge for light truck portfolios. The Inflation Reduction Act provisions influence domestic content preferences for battery assembly. Michigan and Ohio manufacturing corridors host module integration facilities serving Detroit-based OEM programs.
India
FAME-III incentive structures from the Ministry of Heavy Industries target hybrid component localization for cost-sensitive vehicle segments. The country's automotive regulator mandates safety performance benchmarks for energy storage systems. Tamil Nadu and Maharashtra industrial corridors attract module assembly investments serving domestic passenger car and two-wheeler electrification.
Automotive 48V Lithium Battery Market Competitive Landscape
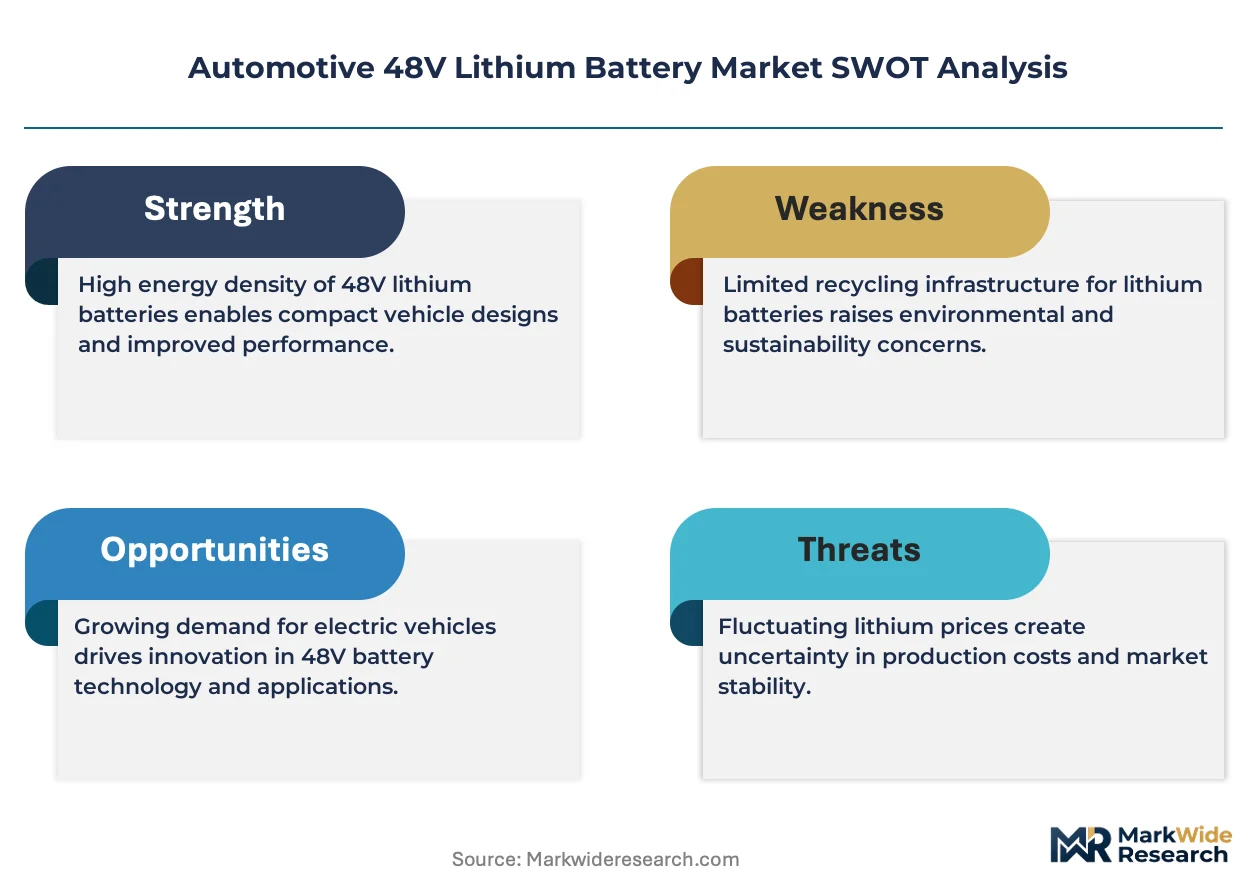
Premium-margin players sit above commodity-margin players across chemistry specialization and integration depth, with tier-1 automotive suppliers commanding long-term OEM contracts while second-tier assemblers compete on spot-market flexibility. The vendor base separates into three strategic archetypes: integrated powertrain divisions with captive cell offtake, dedicated battery system specialists with multi-chemistry capabilities, and diversified electronics conglomerates leveraging thermal management expertise. Capacity expansion and strategic partnerships dominate competitive moves, with producers securing dedicated cell allocation through multi-year volume commitments.
Among German-based integrated suppliers, Robert Bosch GmbH and Continental AG occupy positions representing the powertrain-integrated archetype, leveraging established OEM relationships for mild-hybrid module supply. Valeo SA exemplifies the dedicated system specialist tier with focused eDrive capabilities, while Denso Corporation anchors the diversified electronics grouping with thermal management convergence expertise. These three company structures illustrate how geographic origin and corporate form shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Valeo SA |
| BorgWarner Inc. |
| Continental AG |
| Mitsubishi Electric Corporation |
| Denso Corporation |
| Hyundai Mobis Co., Ltd. |
| Hitachi, Ltd. |
| Magna International Inc. |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange cobalt and nickel price volatility cascades through cathode supplier margins into three-tier pricing structure across premium, standard, and economy levels for 48V module assemblers. OEM long-term offtake agreements embed price-volume flex mechanisms that buffer tier-1 suppliers from spot-market swings while compressing margins for aftermarket providers.
Pricing Analysis
Contract-based long-term offtake dominates OEM procurement, with volume-scale and ISO 26262 ASIL-D certification tier as primary price differentiation drivers. Cost compression in standard-grade NMC modules is intensifying because Chinese cell producers have scaled LFP lines for auxiliary power applications. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership procurement models, whereas premium German OEMs prioritize qualification reliability over unit economics.
Supply Chain Analysis
Battery end-of-life flows and cell refurbishment channels remain underdeveloped, creating stranded asset risks for European module assemblers facing EMA sustainability directives. Cell production concentrates in China's Jiangsu and Guangdong provinces, with cathode active materials drawing from Indonesian nickel and Chilean lithium feedstocks. Single-geography dependency in cylindrical cell supply creates tariff exposure vulnerability. Distribution runs through tier-1 supplier integration facilities in Stuttgart, Seoul, and Michigan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive 48V lithium battery procurement has shifted toward premium-cycle LFP specifications for high-duty mild-hybrid applications, elevating chemistry specialization above commodity scale.
For Market Incumbents: Anticipate full-electric platform substitution above 60kWh by locking 5-7 year volume commitments with Seoul and Stuttgart OEMs before platform standardization windows close. Backward integration into LFP cell finishing capacity in Europe satisfies REACH origin-traceability requirements and defends margin position against Chinese cell producer direct sales expansion. For New Entrants and Emerging Players: Solid-state cell prototyping for 48V auxiliary power creates technology-first wedge into thermal management convergence opportunities where HVAC and battery cooling loops integrate. India's FAME-III production-linked incentives represent the most penetrable geography for module assembly localization, with go-to-market anchored through fleet operator direct contracts bypassing entrenched OEM supply agreements. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-chemistry module capabilities face qualification timeline compression from ECHA SVHC list expansion. Acquisition targets with captive European cell finishing capacity and ASIL-D certified battery management systems offer strongest 5-10 year viability. Monitor EU F-Gas Regulation enforcement intensity for compliance-bridge demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| LFP Cell Finishing Capacity Expansion | European-bound modules satisfy ECHA REACH origin-traceability mandates and compress qualification timelines. |
| Long-Term Supply Agreement Restructuring | Price-volume flex mechanisms with Stuttgart OEMs secure allocation from constrained Jiangsu production lines. |
| ASIL-D Certification Investment | ISO 26262 qualification extends development cycles but unlocks premium-tier procurement from German KBA-regulated platforms. |
| Thermal Management Convergence Partnership | 48V e-compressor integration with battery cooling loops captures white space from HVAC-electronics supplier overlap. |
| India FAME-III Localization | Tamil Nadu module assembly investments access production-linked incentives for cost-sensitive vehicle segments. |
Research Methodology
Bottom-up OEM platform modeling reconciled against top-down cell production tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet operator maintenance heads combined with secondary validation from vehicle production databases, IHS Markit registration data, SAMR GB standard filings, and ECHA SVHC candidate list updates. Triangulation across supply-side capacity announcements and demand-side platform launch schedules calibrated segment-level projections.
Input-output matrices map propulsion architecture, vehicle class, content per vehicle, and regional production cluster dimensions across the projection horizon. CAGRs derive from installed base accumulation models incorporating replacement cycle assumptions and technology substitution elasticity. Forecast inputs include KBA emission ceiling enforcement trajectories and F-Gas Regulation phase-down timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to full-electric platform penetration rates and cobalt price volatility. Practitioners should monitor EU Green Deal CO2 fleet mandate stringency revisions and Chinese LFP export capacity expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Consumer Lithium-Ion Battery Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Liquid Lithium Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Cylindrical Lithium-Ion Battery Market