
 Lithium-Ion Batteries Electric Bike Market | 2026-2036
Lithium-Ion Batteries Electric Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Batteries Electric Bike Market Insights
The EU Green Deal is decoupling electric bike battery procurement from carbon-intensive supply chains, forcing pack assemblers to document lifecycle emissions. Samsung SDI leverages its Hungarian cell plant to serve European OEMs with localized production. BYD anchors cost leadership through in-house cathode production and captive lithium sourcing. Panasonic dominates premium cylindrical cell supply for high-torque mountain bike motors.
Lithium-ion batteries for electric bikes are rechargeable electrochemical storage systems, typically employing nickel-manganese-cobalt or lithium iron phosphate cathodes in 36V to 48V configurations, engineered for 500 to 1,000 full discharge cycles. These packs power pedal-assist and throttle-based propulsion across urban mobility and recreational applications. The battery chemistry dimension shows LiFePO4 gaining ground in fleet applications where thermal stability and cycle longevity outweigh energy density priorities. Capacity segmentation reveals ultra-high packs commanding margin premiums in cargo bike and delivery service configurations, while standard capacity occupies volume share in private commuter sales.
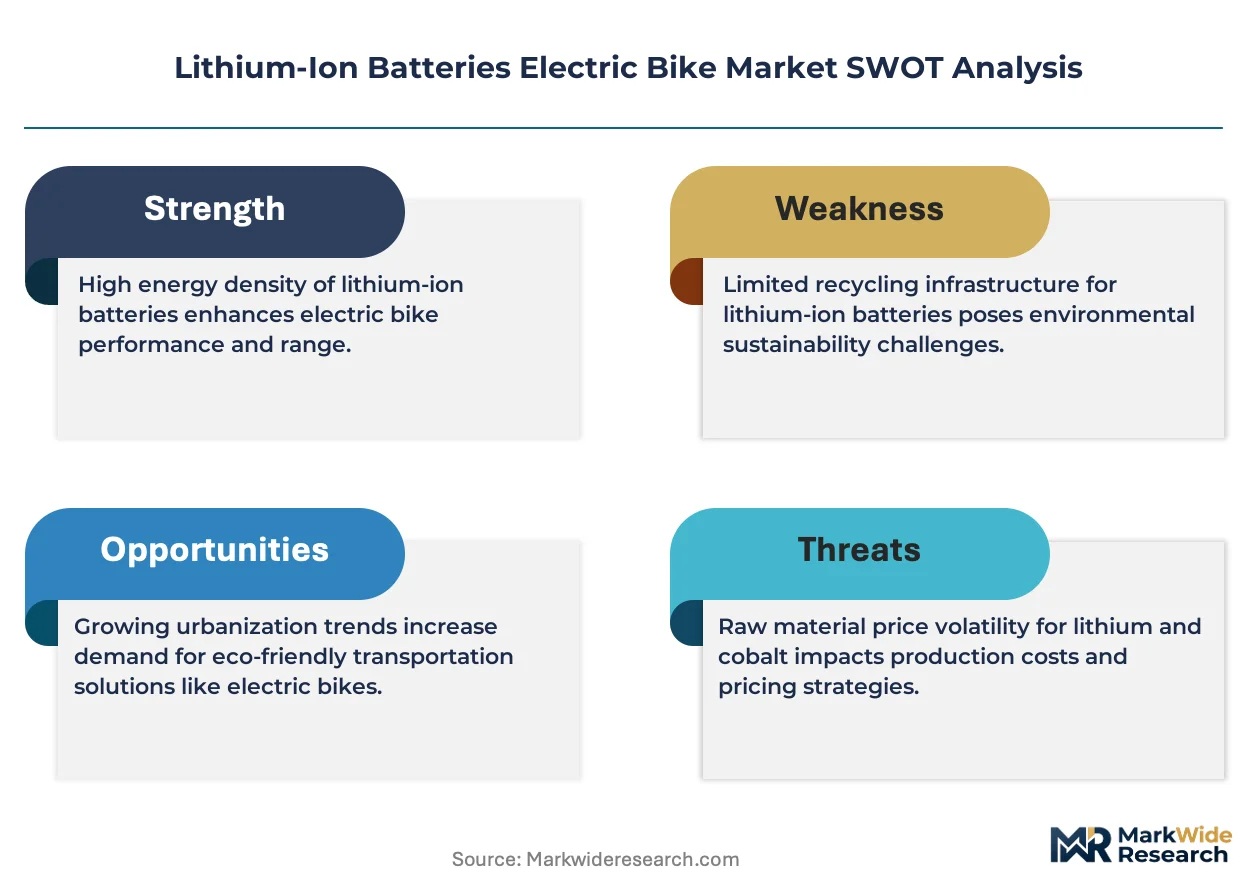
China's NMPA enforces compulsory GB standards testing for cell safety and transport classification, restricting market access for uncertified imports. The EU's CE marking and REACH compliance requirements extend to battery recyclability disclosures, reshaping how pack makers design end-of-life protocols. Stakeholders must monitor how ECHA's evolving substance restrictions on nickel and cobalt compounds affect cathode material sourcing economics and supplier qualification timelines.
Market Dynamics
Cell-to-pack thermal management standardization is compressing procurement timelines for OEMs while GB standards and REACH compliance force parallel certification tracks across export corridors.
Growth Catalysts
- EU Green Deal carbon accounting:Lifecycle disclosure mandates are redirecting procurement toward low-emission cell suppliers with documented Scope 3 data.
- Urban last-mile logistics:Delivery fleet operators in Chinese manufacturing clusters are scaling 48V high-capacity pack orders for cargo bike configurations.
- LiFePO4 chemistry maturation:Thermal stability advantages are displacing NMC in fleet applications where cycle longevity outweighs energy density priorities.
Market Restraints
- Lithium carbonate volatility:Cathode material input costs swing with spot market pricing, compressing pack assembler margins on fixed-price contracts.
- Yangtze River Delta concentration:Cell-to-pack assembly gravity in one Chinese corridor creates single-point vulnerability for European and North American supply security.
- F-Gas Regulation compliance friction:Thermal management system refrigerant restrictions extend qualification timelines for energy-dense pack designs targeting EU markets.
Strategic Opportunities
- Indian BIS certification pathway:Untapped domestic production incentives under PLI schemes attract pack assemblers establishing localized cell sourcing.
- Battery-swapping infrastructure:Interchangeable pack standards enable subscription-based ownership models for commercial fleet operators.
- Solid-state electrolyte convergence:Polymer ceramic composite research programs promise energy density step-changes for premium torque applications.
Industry Challenges
- Thermal runaway simulation expertise:Pack engineers with computational fluid dynamics and abuse testing capabilities command scarcity premiums in hiring markets.
- Dual certification timelines:Parallel NMPA GB testing and UN 38.3 transport classification create 14-18 month product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Batteries Electric Bike Market |
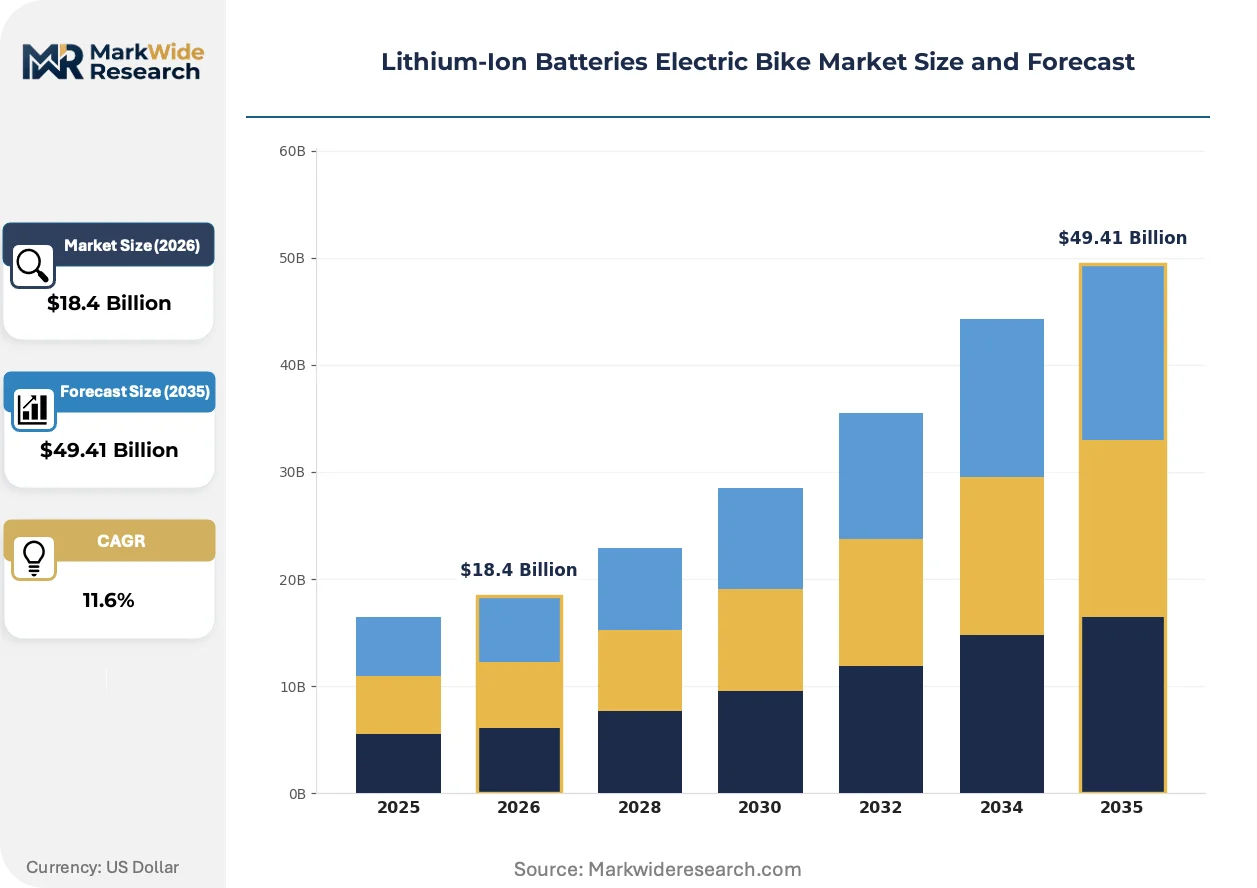
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commuter Bikes, Mountain Bikes, Folding Bikes, Cruiser Bikes Capacity: Standard, High, Ultra-High, Low Battery Chemistry: LiNiCoMnO2, LiFePO4, LiCoO2, LiMn2O4 End User: Private Consumers, Corporate Fleets, Delivery Services, Rental Services |
| Companies Covered | Samsung SDI, LG Energy Solution, Panasonic Corporation, BYD, Phylion Battery, BMZ Group, Amperex Technology, Bosch, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Batteries Electric Bike Market Trends and Innovations
Smart battery management systems are evolving from passive monitoring to predictive maintenance platforms, compressing warranty liability and enabling usage-based financing models.
Solid-state electrolyte research is integrating ceramic-polymer composite layers into prototype cells, replacing flammable liquid electrolytes with fire-resistant alternatives. High-torque mountain bike OEMs are piloting these packs for premium segments where safety certification commands price premiums. The technology is integrating thermal stability guarantees that extend cycle warranties beyond current liquid-electrolyte limits.
China's NMPA is tightening GB 31241 cell safety testing protocols, mandating nail penetration and overcharge abuse documentation for all domestic sales. Export-oriented pack assemblers must maintain dual qualification tracks to serve EU REACH recyclability requirements simultaneously. European cargo bike manufacturers are responding by consolidating supplier audits around certified cell sources with pre-validated transport classifications.
Fleet procurement is consolidating around total-cost-of-ownership contracts that unbundle battery capital expenditure from vehicle acquisition. Commercial operators in logistics corridors are shifting toward lease-based pack replacement programs with guaranteed cycle minimums. This restructuring is most visible across Asia-Pacific urban delivery networks where vehicle uptime metrics dominate supplier selection criteria.
Lithium-Ion Batteries Electric Bike Market Segmentation
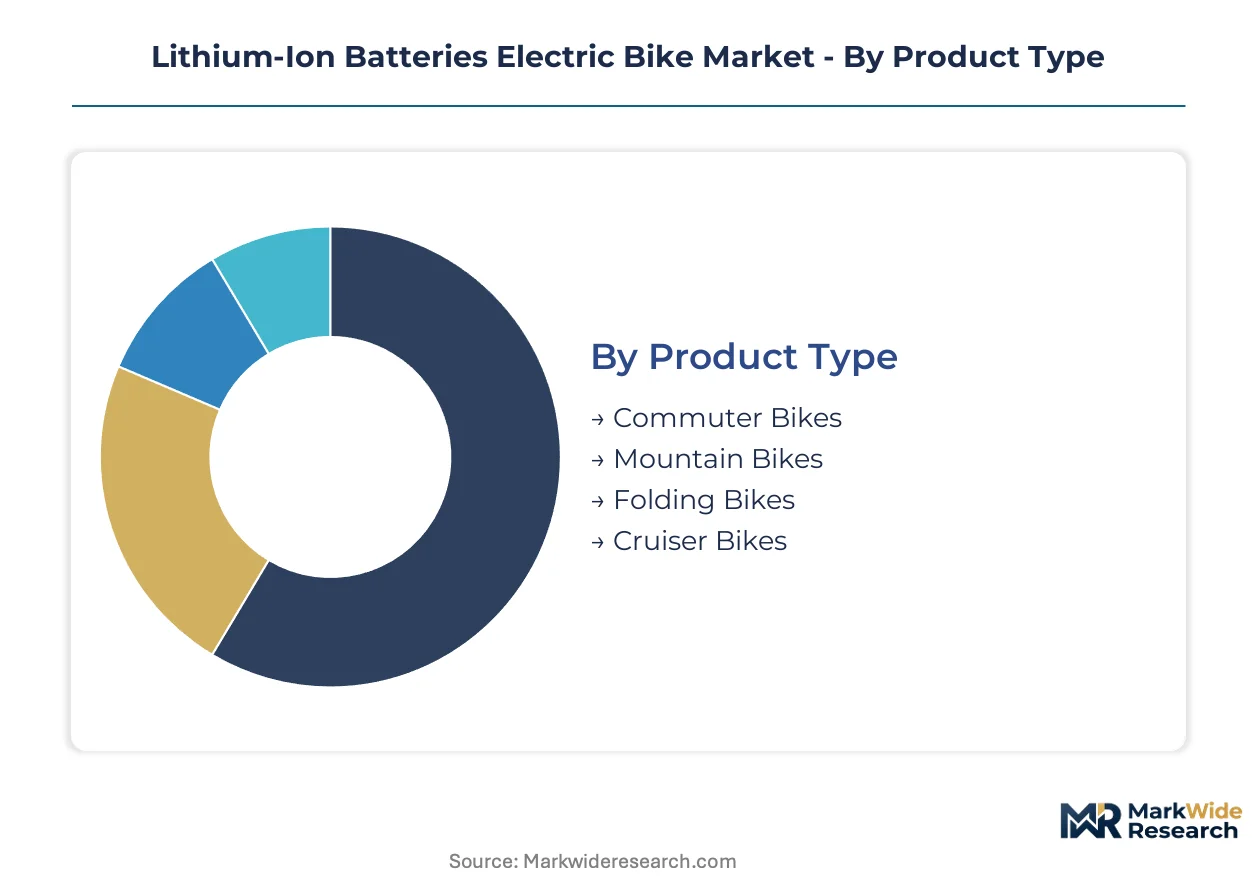
Battery chemistry and capacity configurations determine certification pathways and thermal management requirements across electric bike applications. Product type and end-user segmentation reveal divergent procurement patterns between private ownership and commercial fleet operators.
Product Type:
EU F-Gas Regulation refrigerant restrictions and UN 38.3 transport classifications apply differentially across frame geometries and motor torque specifications.
- Commuter Bikes:Step-through and diamond-frame configurations dominate private ownership with 36V to 48V standard-capacity packs. Demand clusters in Dutch and German urban corridors where EU Green Deal lifecycle disclosure mandates favor suppliers with documented Scope 3 emissions data.
- Mountain Bikes:High-torque mid-drive motors require premium cylindrical cells with enhanced discharge rates. Panasonic anchors supply for this segment through validated abuse-testing protocols that satisfy both China's NMPA GB standards and REACH compliance requirements.
- Folding Bikes:Compact form factors prioritize energy density over cycle longevity in 20-inch wheel configurations.
- Cruiser Bikes:Relaxed geometry frames accommodate larger battery enclosures with minimal thermal constraints.
Leading the category by volume: Commuter Bikes. Growing fastest: Mountain Bikes.
Capacity:
Cost tier stratification separates fleet procurement contracts from retail replacement sales through guaranteed cycle minimums and lease structures.
- Ultra-High:Cargo bike and commercial delivery configurations demand 48V systems exceeding 20Ah with forced-air or liquid thermal management. BYD's in-house cathode production anchors cost leadership for this tier across Yangtze River Delta assembly operations.
- High:Extended-range commuter packs balance energy density with pack weight for hill-climb performance. Samsung SDI's Hungarian cell plant serves European OEMs with localized production that satisfies EU Green Deal carbon accounting requirements.
- Standard:Volume share in private commuter sales with 36V configurations and passive cooling.
- Low:Entry-tier replacement market with minimal BMS functionality and shorter warranty terms.
Highest margin capture: Ultra-High. Steepest expansion trajectory: High.
Battery Chemistry:
Application maturity determines whether thermal stability or energy density priorities dominate cathode material selection.
- LiFePO4:Lithium iron phosphate chemistry delivers 2,000-plus cycle lifespans with inherent thermal stability. Fleet operators across Asia-Pacific logistics corridors are consolidating procurement around this chemistry where vehicle uptime metrics dominate supplier selection.
- LiNiCoMnO2:Nickel-manganese-cobalt formulations maximize volumetric energy density for premium torque applications. ECHA's evolving substance restrictions on nickel and cobalt compounds are extending supplier qualification timelines for European market access.
- LiCoO2:Cobalt-dominant chemistry persists in compact folding bike packs where space constraints override cost considerations.
- LiMn2O4:Manganese-spinel formulations occupy mid-tier price positioning with moderate cycle longevity.
Fleet procurement concentration: LiFePO4. Premium segment anchor: LiNiCoMnO2.
End User:
Customer type segmentation separates capital expenditure ownership models from subscription-based battery service agreements.
- Corporate Fleets:Total-cost-of-ownership contracts unbundle battery capital expenditure from vehicle acquisition with guaranteed cycle minimums. Lease-based pack replacement programs are restructuring procurement across German and French urban delivery networks.
- Delivery Services:Battery-swapping infrastructure enables subscription-based ownership with interchangeable pack standards. India's BIS certification pathway and PLI production incentives are attracting pack assemblers establishing localized cell sourcing for this segment.
- Private Consumers:Retail replacement sales dominate with standard-capacity configurations and passive BMS monitoring.
- Rental Services:High-utilization operators prioritize rapid-charge compatibility and abuse-tolerant cell chemistries.
Fastest contract restructuring: Corporate Fleets. Emerging infrastructure investment: Delivery Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell-to-pack assembly concentrates in China's Yangtze River Delta while consumption spreads across logistics corridors in Germany, India, and the United States. This production-consumption divide shapes certification requirements and supplier qualification timelines.
China
Urban last-mile delivery fleets in Shanghai and Hangzhou are scaling 48V high-capacity procurement for cargo bike configurations. NMPA enforces compulsory GB 31241 cell safety testing with nail penetration and overcharge abuse documentation. The Yangtze River Delta manufacturing cluster anchors Panasonic, BYD, and Samsung SDI operations serving export markets.
Germany
Dutch and German urban corridors drive private commuter demand for 36V to 48V standard-capacity packs with documented Scope 3 emissions data. EU Green Deal lifecycle disclosure mandates redirect procurement toward low-emission cell suppliers. KBA and REACH compliance requirements reshape end-of-life protocol design for pack makers.
India
Delivery services in Mumbai and Delhi-NCR are consolidating around battery-swapping infrastructure with interchangeable pack standards. BIS certification pathways and PLI production incentives attract pack assemblers establishing localized cell sourcing. The country's national standards body tightens domestic safety protocols for fleet applications.
United States
Recreational mountain bike demand in Colorado and Pacific Northwest corridors requires premium cylindrical cells with enhanced discharge rates. EPA and DOT transport classification rules apply parallel to UN 38.3 testing for cross-border pack shipments. Regional distributors consolidate supplier audits around pre-validated cell sources.
South Korea
MFDS-aligned safety standards support domestic cell qualification for export-oriented pack assemblers. Seoul-based research programs advance solid-state electrolyte prototypes for premium torque applications. The country's national industrial policy channels funding toward ceramic-polymer composite cell development.
Lithium-Ion Batteries Electric Bike Market Competitive Landscape
The competitive structure tilts toward integrated cell-to-pack specialists with captive cathode production and in-house thermal management capabilities. Tier-one assemblers dominate premium segments through validated abuse-testing protocols, while mid-tier fabricators compete on cost leadership for fleet procurement contracts. Two strategic archetypes define positioning: vertically integrated battery conglomerates with upstream material control, and specialized pack assemblers with modular BMS platforms. Capacity expansion and geographic licensing partnerships represent the dominant competitive moves across both tiers.
Among Asia-Pacific-based conglomerates, Samsung SDI and BYD occupy positions exemplifying divergent strategic paths—Samsung SDI through European-localized production, BYD through cost leadership anchored in captive lithium sourcing. Panasonic Corporation sits within the premium cylindrical cell tier, representing validated supply relationships for high-torque motor configurations. Bosch anchors the European fabrication archetype with modular pack architectures serving multiple OEM qualification tracks simultaneously.
| Leading Market Players |
|---|
| Samsung SDI |
| LG Energy Solution |
| Panasonic Corporation |
| BYD |
| Phylion Battery |
| BMZ Group |
| Amperex Technology |
| Bosch |
| Murata Manufacturing |
| Others |
Pricing and Supply Chain Analysis
Captive cathode production anchors pricing power for integrated pack assemblers while outsourced cell sourcing leaves mid-tier fabricators exposed to lithium carbonate spot volatility. China's Yangtze River Delta concentration creates divergent margin structures between upstream-integrated conglomerates and modular BMS specialists.
Pricing Analysis
Margin tightening in standard-capacity tiers reflects fixed-price contract exposure to cathode material swings. Three-tier pricing structure across premium cylindrical, high-capacity prismatic, and economy pouch configurations segments buyers by certification grade and thermal management sophistication. Fleet procurement contracts with guaranteed cycle minimums show lowest price sensitivity, while retail replacement channels face acute cost-down pressure from commoditized imports.
Supply Chain Analysis
India's PLI domestic-content mandates are reshaping sourcing patterns for delivery-service pack assemblers targeting BIS certification. Cell-to-pack assembly draws from China's Yangtze River Delta, South Korea's battery materials corridor, and Japan's cylindrical cell specialists. Single-source vulnerability concentrates in NMPA-certified cell supply for EU-bound exports. Distribution runs through OEM direct procurement for premium tiers and distributor networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around pack assemblers with validated abuse-testing protocols and captive cathode supply, as dual certification timelines force weaker players toward contract manufacturing roles.
For Market Incumbents: Anchor premium positioning through NMPA-EU dual certification investments that extend product launch cycles beyond 14 months for challengers. Deepen upstream control over lithium sourcing to insulate margins from carbonate spot volatility. Defend against solid-state electrolyte disruption by piloting ceramic-polymer prototypes with high-torque mountain bike OEMs.
For New Entrants and Emerging Players: Capture India's battery-swapping infrastructure buildout by establishing BIS-certified cell sourcing under PLI production incentives. Target delivery-service fleet operators with subscription-based ownership models that unbundle capital expenditure. Enter through modular BMS platforms serving multiple OEM qualification tracks simultaneously.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated battery conglomerates seeking thermal management expertise and validated transport classifications. Long-term viability favors pack assemblers with computational fluid dynamics capabilities and pre-validated UN 38.3 documentation. Watch ECHA substance restrictions on nickel and cobalt compounds as inflection signal for cathode chemistry transitions.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Parallel NMPA GB and REACH compliance compresses competitor launch timelines by 8-12 months. |
| Captive Cathode Production | In-house lithium iron phosphate synthesis insulates margins from carbonate spot volatility. |
| Battery-Swapping Infrastructure | Interchangeable pack standards enable subscription revenue models for fleet operators. |
| Solid-State Electrolyte R&D | Ceramic-polymer prototypes command premium positioning in high-torque mountain bike segments. |
| Localized Cell Manufacturing | Hungarian or Indian production satisfies EU Green Deal carbon accounting and PLI incentives. |
Research Methodology
Independent corroboration across cell manufacturer supply chain directors, OEM platform engineers, and fleet procurement managers underwrites the qualitative findings. Secondary validation draws from NMPA GB standard filings, EU REACH substance restriction updates, UN 38.3 transport classification databases, and customs trade records. Bottom-up pack shipment data triangulates against top-down electric bike production estimates across the analysis window.
Rate-of-change decomposition separates volume growth from value expansion across battery chemistry, capacity tier, and end-user segmentation. The analytical framework models commuter, mountain, folding, and cargo bike configurations alongside private ownership, corporate fleet, and delivery-service demand patterns. CAGRs derive from segment-level growth rates weighted by base-period revenue shares. Forecast inputs incorporate lithium carbonate price trajectory assumptions and certification timeline elasticity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state electrolyte commercialization timelines and ECHA cobalt restriction severity. The analysis assumes NMPA and REACH compliance requirements remain stable through the projection horizon. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market
Lithium-ion Battery
China Electric Vehicle Battery Manufacturing Market
Lithium-ion Battery
Aluminium Ion Battery Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Lithium Battery Pack Market