
 Scientific Text Analytics and Annotators Market | 2026-2036
Scientific Text Analytics and Annotators Market Size, Share, and Industry Trends Forecast 2026-2036
Scientific Text Analytics and Annotators Market Analytics
Modular API-first packaging is broadening buyer choice in scientific text analytics. Scale AI leverages its workforce infrastructure to sustain high-volume biomedical annotation contracts. Labelbox competes through flexible ontology design tools that accommodate multi-site research protocols. Appen Limited anchors its position with linguist-verified annotation layers for peer-review-grade datasets.
Scientific text analytics and annotators comprise software systems that apply natural language processing, named entity recognition, and relationship extraction to structured and unstructured scientific corpora, typically operating at token-level granularity across domain-specific ontologies such as MeSH, UMLS, or GO to enable machine-readable knowledge graphs for research automation. Their primary commercial purpose is to reduce manual curation burden in evidence synthesis and regulatory submission preparation. Text mining software dominates current deployment due to mature integration with PubMed and patent databases, while machine learning platforms represent the fastest-expanding segment as end-to-end training pipelines disassemble point solutions. Cloud-based deployment captures the largest margin pools by converting perpetual licenses into recurring SaaS revenue with automatic ontology updates.
FDA algorithmic transparency guidance, the EU AI Act high-risk system classification, and HIPAA de-identification standards collectively shape product roadmaps by mandating explainability logs and audit trails for clinical NLP outputs. ISO 27001 certification has become a de facto market access requirement for vendors serving pharmaceutical sponsors. Stakeholders must decide whether to build compliant annotation infrastructure in-house or absorb vendor premiums for pre-certified platforms.
Market Dynamics
Modular API architectures are fragmenting procurement power in scientific text analytics, allowing biotech firms to assemble annotation pipelines from specialized vendors rather than accepting monolithic enterprise suites.
Growth Catalysts
- FDA Algorithmic Transparency Guidance:Pharmaceutical sponsors now require explainability logs for clinical NLP outputs, forcing platform upgrades that expand vendor serviceable addressable market.
- Multi-omics Integration Workflows:Proteomics and metabolomics researchers are adopting unified annotation ontologies that bridge gene expression databases with unstructured literature corpora.
- Boston-San Francisco Biotech Clustering:Geographic concentration of venture-funded drug discovery startups generates localized demand spikes for high-throughput annotation services.
Market Restraints
- Specialized Linguist Labor Pool Constraints:Domain expertise in biomedical ontology curation commands premium wages that compress annotation service margins.
- EU AI Act High-Risk System Classification:Clinical NLP tools face mandatory conformity assessments that extend sales cycles by months.
- Cloud Infrastructure Concentration:Three hyperscalers control the substrate for most SaaS annotation platforms, creating vendor lock-in risk and pricing power asymmetry.
Strategic Opportunities
- Real-World Evidence Regulatory Acceptance:FDA guidance on RWE submissions creates demand for annotation tools that structure patient narrative data from electronic health records.
- Patent Analytics Convergence:Intellectual property law firms are purchasing scientific text mining licenses to automate prior art searches in chemistry and biology filings.
- Federated Learning Architectures:Multi-site hospital networks need annotation platforms that train models without centralizing protected health information across institutional boundaries.
Industry Challenges
- Interoperability with Legacy Curation Workflows:Established pharmaceutical knowledge management systems resist API integration, forcing expensive middleware development.
- ISO 27001 Certification Timeline:Sixteen-month audit cycles delay market entry for annotation startups targeting enterprise sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scientific Text Analytics and Annotators Market |
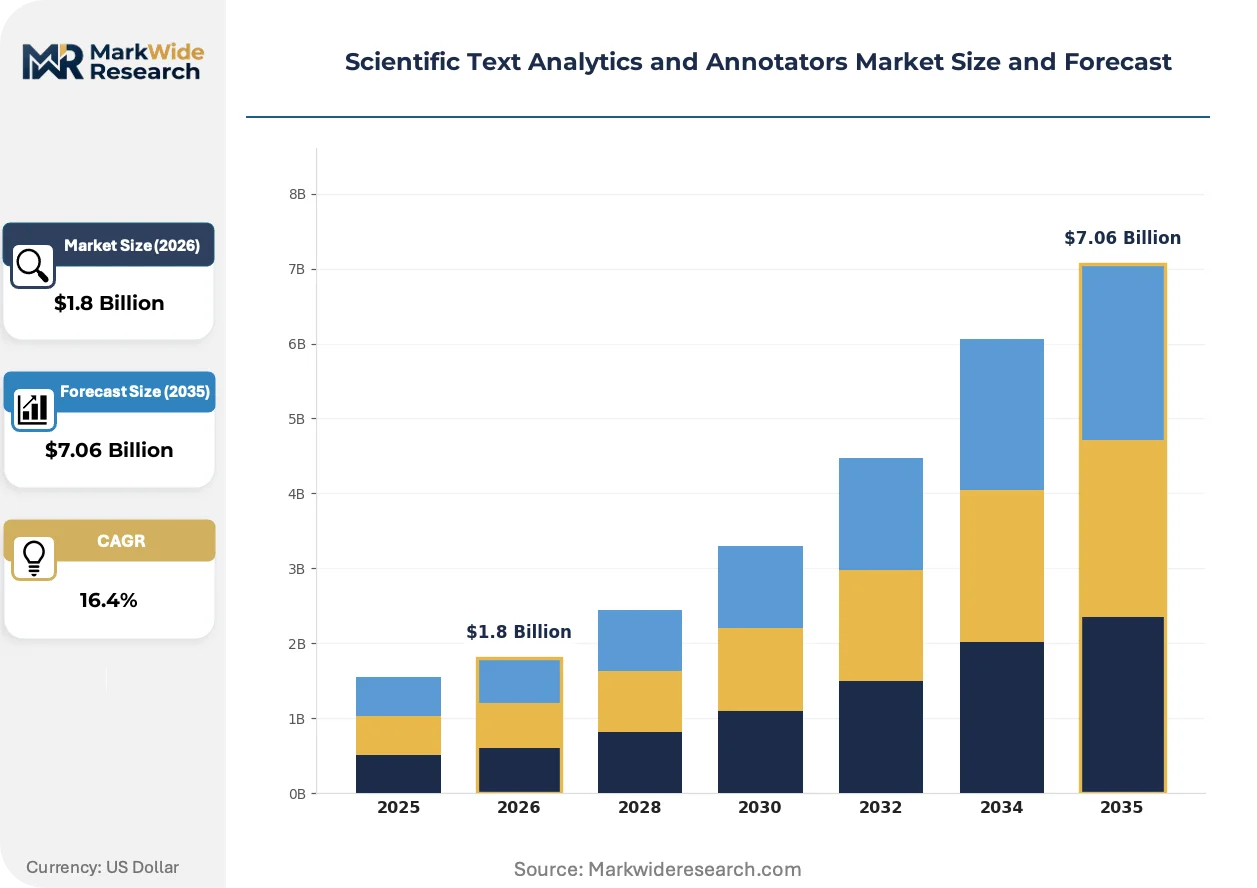
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Annotation Tools, Text Mining Software, Machine Learning Platforms, Application Programming Interfaces End User: Research Institutions, Pharmaceutical Companies, Academic Organizations, Government Agencies Application: Clinical Trials, Drug Discovery, Bioinformatics, Literature Review Deployment: On-Premises, Cloud-Based, Hybrid Solutions, SaaS |
| Companies Covered | Appen Limited, Scale AI, Labelbox, CloudFactory, iMerit, Lionbridge AI, Alegion, SuperAnnotate, Cogito Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scientific Text Analytics and Annotators Market Evolving Landscape
Foundation models pretrained on biomedical literature are compressing the annotation labor intensity that once defined this market, while regulatory pressure on algorithmic accountability is reshaping product architecture requirements.
Transformer-based entity recognition systems are absorbing the token-level annotation tasks previously performed by human curators in systematic review preparation. Contract research organizations are deploying these models for adverse event extraction from clinical trial narratives. This absorption is collapsing the per-document cost structure that sustained traditional annotation service providers.
The EU AI Act's high-risk system classification mandates technical documentation and human oversight protocols for clinical NLP tools deployed in diagnostic support. European health technology assessment bodies are incorporating these requirements into reimbursement evaluations. Vendors serving EMA submission pathways are restructuring product roadmaps to embed explainability layers.
Biotech procurement teams are unbundling annotation services from end-to-end AI platform subscriptions, negotiating point solutions for specific ontology types. This disaggregation favors specialized vendors with deep MeSH or UMLS expertise over generalist machine learning platforms. The pattern is most pronounced among Series B-funded drug discovery startups in Cambridge and South San Francisco.
Scientific Text Analytics and Annotators Market Segmentation
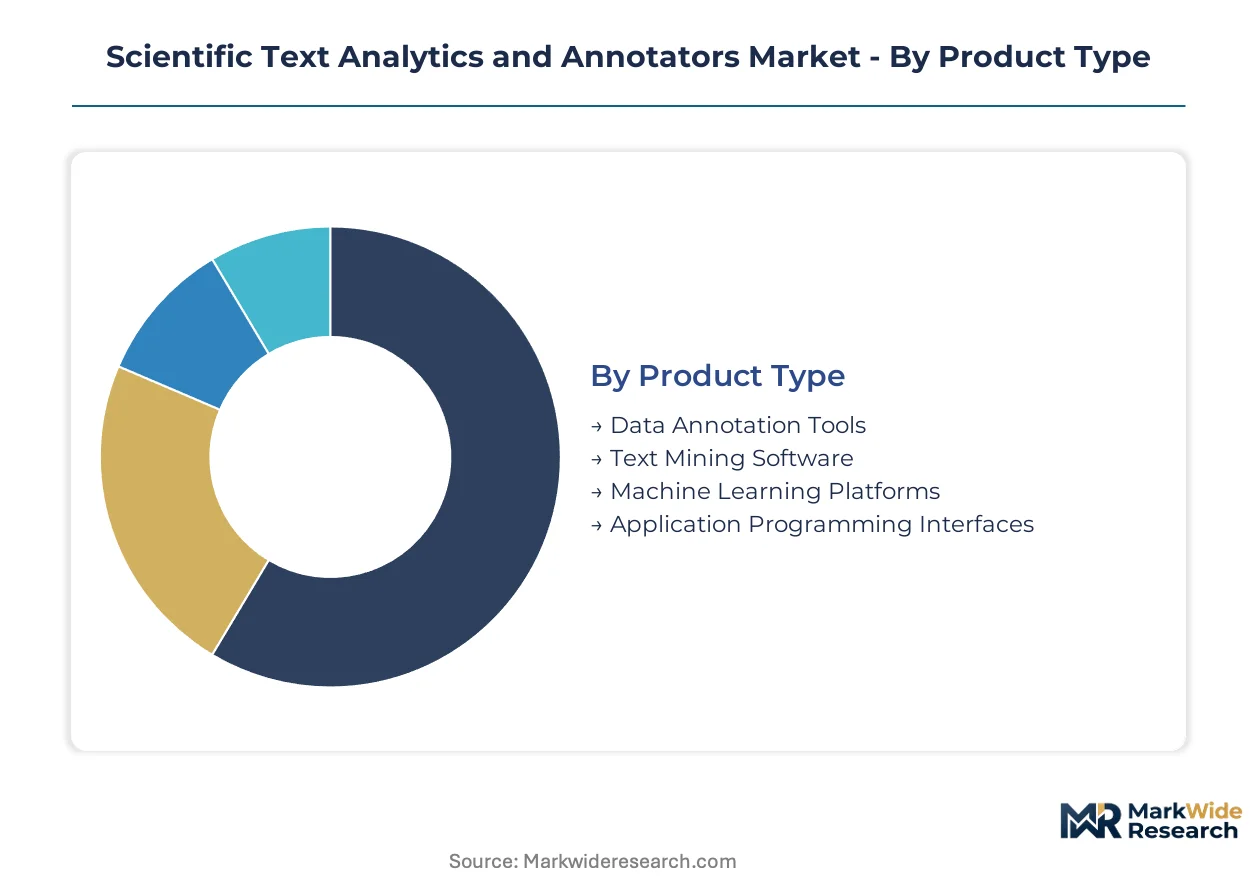
Segmentation in scientific text analytics reflects divergent procurement patterns between established pharmaceutical enterprises and agile research startups. Deployment choices and product architectures separate high-volume annotation pipelines from precision curation workflows.
Product Type:
Volume concentration sits with text mining suites, while premium margins attach to machine learning platforms that bundle training infrastructure.
- Data Annotation Tools:Modular interfaces for token-level labeling across biomedical ontologies such as MeSH and UMLS. Demand clusters at contract research organizations in Cambridge, Massachusetts, where high-throughput clinical trial documentation requires scalable curator workstations.
- Text Mining Software:Mature integration with PubMed, patent databases, and regulatory document repositories. Pharmaceutical sponsors in Basel, Switzerland, deploy these systems for adverse event extraction and periodic safety update report preparation.
- Machine Learning Platforms:End-to-end training pipelines with automated ontology updates.
- Application Programming Interfaces:RESTful endpoints for embedding annotation into existing knowledge management stacks.
Mature deployment sits with Text Mining Software. Newer deployment is concentrated in Machine Learning Platforms.
End User:
Customer type splits between sponsor-funded commercial research and publicly funded academic investigation, with procurement authority concentrated in different organizational layers.
- Pharmaceutical Companies:Enterprise procurement teams negotiate multi-year platform licenses with mandatory ISO 27001 certification and audit trail capabilities. FDA algorithmic transparency guidance drives upgrade cycles for clinical NLP tools used in regulatory submissions.
- Research Institutions:Federally funded laboratories with distributed annotation needs across multi-site consortia. The National Institutes of Health grant portfolio in Bethesda, Maryland, sustains demand for collaborative ontology development environments.
- Academic Organizations:Department-level purchasing with limited integration requirements.
- Government Agencies:Regulatory bodies requiring de-identification standards compliance.
Established procurement sits with Pharmaceutical Companies. Expanding deployment is concentrated in Research Institutions.
Application:
Use case concentration tracks the regulatory value chain, from exploratory discovery through submission-grade evidence synthesis.
- Drug Discovery:Target identification and mechanism-of-action extraction from unstructured literature corpora. Venture-funded biotechs in South San Francisco deploy annotation platforms to compress target validation timelines ahead of Series C fundraising.
- Clinical Trials:Structured extraction of patient narrative data from case report forms and electronic health records. EMA submission pathways require explainability logs that reshape platform architecture for European sponsors.
- Bioinformatics:Multi-omics integration bridging gene expression databases with literature evidence.
- Literature Review:Systematic review automation for evidence synthesis in health technology assessment.
Revenue concentration sits with Clinical Trials. Steepest expansion trajectory is concentrated in Drug Discovery.
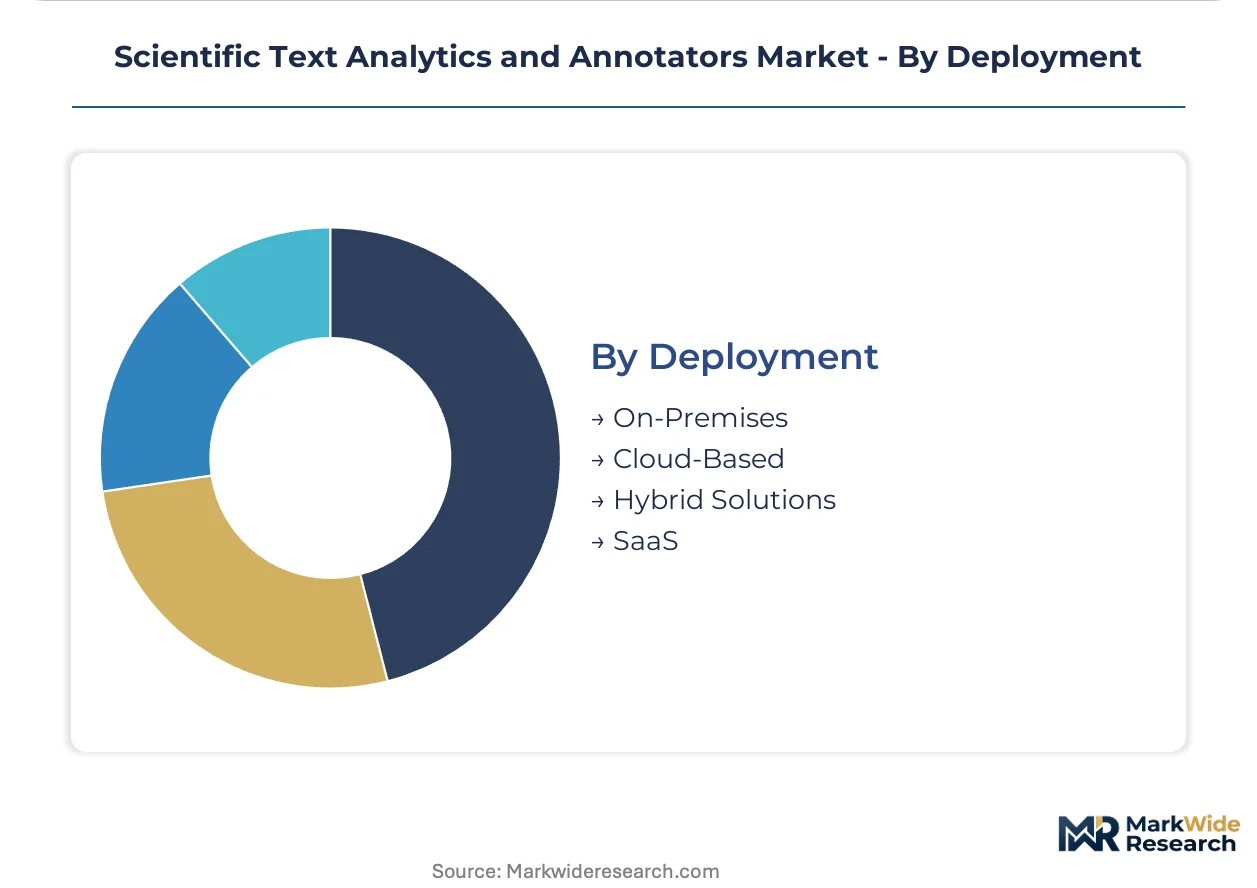
Deployment:
Infrastructure choice reflects data sovereignty requirements against the operational burden of self-managed systems.
- Cloud-Based:Recurring SaaS revenue models with automatic ontology updates and elastic compute for batch processing. Three hyperscalers control underlying infrastructure, creating pricing power asymmetry for annotation vendors.
- SaaS:Pre-configured annotation environments with subscription pricing and managed security compliance. HIPAA de-identification standards and EU AI Act conformity assessments favor vendors with pre-certified platforms.
- On-Premises:Air-gapped installations for proprietary compound libraries.
- Hybrid Solutions:Split architectures with sensitive data on local infrastructure and compute-intensive processing in cloud environments.
Margin concentration sits with Cloud-Based deployment. Security-sensitive adoption is concentrated in On-Premises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotech clustering in designated innovation zones concentrates procurement authority for annotation platforms. Federal research funding and special economic zone tax incentives shape vendor selection criteria across major markets.
United States
NIH grant portfolios and venture capital deployment in Cambridge and South San Francisco drive platform adoption. FDA algorithmic transparency guidance mandates explainability logs for clinical NLP tools used in regulatory submissions. The Greater Boston biotech corridor sustains demand for high-throughput annotation services among Series B-funded drug discovery startups.
Germany
Pharmaceutical sponsors in Basel-adjacent Baden-Württemberg deploy text mining systems for EMA submission preparation. EU AI Act high-risk system classification requires conformity assessments that extend sales cycles for clinical NLP vendors. The Rhine-Neckar biotech cluster generates localized demand for ontology-compliant annotation infrastructure.
United Kingdom
Research institutions across the Golden Triangle of Cambridge, Oxford, and London procure collaborative annotation environments for multi-site consortia. MHRA alignment with FDA guidance on algorithmic accountability shapes platform upgrade requirements. The Francis Crick Institute in London anchors demand for peer-review-grade dataset curation.
Switzerland
Pharmaceutical headquarters concentration in Basel drives enterprise procurement of ISO 27001-certified annotation platforms. Swissmedic pharmacovigilance requirements mandate audit trail capabilities for adverse event extraction systems. The BioValley cluster spanning Basel-Freiburg-Strasbourg generates cross-border demand for multilingual ontology support.
India
Contract research organizations in Hyderabad and Bengaluru leverage cost arbitrage for high-volume biomedical annotation labor. CDSCO pharmacovigilance reporting requirements create demand for structured extraction tools from case report forms. The Genome Valley biotech corridor in Telangana attracts annotation platform vendors seeking offshore delivery partnerships.
Scientific Text Analytics and Annotators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the annotation platform market. The vendor base separates into three tiers: workforce infrastructure operators, ontology design specialists, and linguist-verified quality layers. Strategic differentiation centers on modular API packaging versus end-to-end platform bundling. M&A activity targets specialized ontology expertise, while geographic expansion focuses on biotech cluster proximity.
Within the workforce infrastructure tier, Scale AI exemplifies high-volume contract execution. Labelbox occupies a position among ontology design specialists with flexible protocol accommodation. Appen Limited anchors the linguist-verified quality segment for peer-review-grade dataset preparation.
| Leading Market Players |
|---|
| Appen Limited |
| Scale AI |
| Labelbox |
| CloudFactory |
| iMerit |
| Lionbridge AI |
| Alegion |
| SuperAnnotate |
| Cogito Tech |
| Others |
Value Network & Pricing Analysis
ISO 27001 certification tiers bifurcate vendor positioning between premium pre-certified platforms and economy-grade uncertified alternatives, with this divergence manifesting in both annual contract values and supply chain sourcing strategies. Pharmaceutical sponsors absorb certification premiums to compress procurement cycles, while biotech startups trade compliance gaps for lower upfront commitments.
Pricing Analysis
Lead-time-driven pricing compression rewards vendors with pre-built explainability architectures under FDA algorithmic transparency guidance. SaaS subscription tiers stratify across enterprise, mid-market, and research-lab levels, with price differentiation anchored in audit trail granularity and ontology update frequency. Pricing pressure intensifies in the mid-market segment as foundation models collapse per-document annotation costs. Academic organizations exhibit highest price sensitivity due to grant-funded budget constraints, while pharmaceutical companies prioritize compliance certainty over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler cloud infrastructure concentrated in the United States, Ireland, and Singapore. Annotation platform vendors draw from specialized linguist labor pools in India and the Philippines, alongside GPU compute clusters in Taiwan and South Korea. Supply chain risk centers on regulatory restriction exposure where EU AI Act conformity assessment delays extend platform deployment timelines. Distribution runs through direct enterprise sales teams for pharmaceutical sponsors and channel partnerships with academic consortia for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scientific text analytics market functions as a cost-of-compliance story where EU AI Act high-risk system classification erects barrier-to-entry moats favoring pre-certified incumbents with sixteen-month audit completion records.
For Market Incumbents: Anticipate margin compression from foundation model commoditization by deepening ontology specialization in MeSH and UMLS domains. Defensive consolidation through acquisition of federated learning specialists addresses emerging demand from multi-site hospital networks. ISO 27001 certification maintenance represents the priority defensive lever against uncertified entrants. For New Entrants and Emerging Players: Contract research organizations in Hyderabad and Bengaluru present the most penetrable channel partner type for offshore annotation service penetration. White-space concentration sits with patent analytics workflows for intellectual property law firms and real-world evidence structuring for EHR data pipelines. Go-to-market positioning through API-first modular packaging bypasses incumbent platform bundling advantages. For Investors and Strategic Acquirers: Re-rating potential sits with ontology design specialists given EU AI Act technical documentation requirements expanding addressable market. Long-term viability favors vendors with linguist-verified quality layers and pre-existing FDA submission pathway relationships. Acquisition target archetype: federated learning infrastructure providers with hospital network pilot contracts. Signal to monitor: EMA reimbursement evaluation incorporation of explainability mandates as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable biotech firms to assemble annotation pipelines from specialized vendors rather than monolithic suites. |
| Acquisition of Specialist Firm | Deep MeSH or UMLS expertise commands premium valuations as biotech procurement teams unbundle annotation from end-to-end AI subscriptions. |
| Geographic Expansion | Proximity to Cambridge and South San Francisco biotech clusters captures localized demand spikes from Series B-funded drug discovery startups. |
| Strategic Partnership | Hyperscaler alliances address cloud infrastructure concentration risk while accelerating ISO 27001 certification timelines for emerging vendors. |
| Product Launch | Explainability layer embedding aligns with FDA algorithmic transparency guidance and EMA technical documentation requirements. |
Research Methodology
Independent corroboration across regulatory affairs directors, platform engineering leads, and biotech procurement officers underwrites the qualitative findings in this analysis. Primary fieldwork combined structured interviews with contract research organization executives, NIH grant administrators, and pharmaceutical knowledge management heads. Secondary validation drew from FDA guidance documents, EMA submission databases, ClinicalTrials.gov protocol records, and ISO certification registries. Bottom-up annotation platform deployment counts and top-down research funding allocation estimates were triangulated to anchor segmentation splits.
Rate-of-change decomposition across the analysis window modeled how foundation model adoption, regulatory compliance cost escalation, and biotech venture deployment patterns would interact. Segmentation dimensions included product architecture type, end-user procurement authority level, application regulatory value chain position, and deployment infrastructure choice. CAGRs were derived from fitted adoption curves calibrated to NIH grant portfolio trajectories and FDA submission volume trends. Hyperscaler capex disclosures and pharmaceutical R&D intensity ratios provided industry-specific forecast inputs.
Caveats apply where EU AI Act implementation timelines or FDA guidance finalization could materially shift the outlook for clinical NLP tool classification. Forecasts reflect assumptions about linguist labor pool expansion rates and foundation model performance improvement trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
IT Operation Analytics (ITOA) Market
Analytics
Learning Analytics Solution Market
Analytics
Europe Crowd Analytics Market
Analytics
Location Analytics Market
Analytics
Global Telecom Analytics Market
Analytics
Product Analytics Market
Analytics
Global Data Fusion Market
Analytics
Location Analytics Adoption Spending Market
Analytics
UAE Geospatial Analytics Market
Analytics
Complex Event Processing Market
Analytics
Weather Data Services Market
Analytics
Global Network Analytics Market
Analytics
North America Operational Intelligence Market
Analytics
Connected Device Analytics Market
Analytics
Content Analytics and Discovery Software Market
Analytics
Asia-Pacific HR Analytics Market