
 Sweden ICT Market | 2026-2036
Sweden ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden ICT Market Analytics
Healthcare is restructuring its technology procurement priorities across Sweden, shifting capital toward integrated digital infrastructure and away from standalone departmental systems. Cisco Systems anchors its position through deep networking specialization in Nordic hospital networks. IBM Corporation competes via its AI and quantum computing research presence in Stockholm. Microsoft Corporation extends its cloud footprint through sustained public sector partnership density.
Sweden ICT encompasses information and communication technology infrastructure, software platforms, and digital services operating across fixed and mobile networks with data transmission thresholds exceeding 100 Gbps in core backbone segments, serving enterprise automation, public administration, and consumer connectivity purposes. Cloud Solutions is capturing disproportionate investment flow as enterprises migrate legacy workloads, while Cybersecurity commands premium pricing amid stricter breach disclosure mandates. Services maintains mature margin pools in systems integration, though AI within the Technology dimension is expanding fastest among buyer evaluation criteria.
The Swedish Post and Telecom Authority enforces network resilience standards and spectrum allocation rules that directly shape operator infrastructure capex cycles, while the Swedish Data Protection Authority applies GDPR with sector-specific guidance for healthcare and financial data processing. BIS certification requirements for imported hardware components create compliance checkpoints at the procurement stage. Stakeholders must weigh EU AI Act conformity costs against the competitive disadvantage of delayed algorithmic deployment in public sector tenders.
Market Dynamics
Swedish healthcare providers are restructuring capital allocation toward integrated digital infrastructure, driven by the EU AI Act's algorithmic conformity requirements and Stockholm's metropolitan technology corridor concentration.
Growth Catalysts
- EU AI Act:Mandatory conformity assessments for high-risk algorithmic systems are accelerating procurement of certified AI infrastructure among Swedish public sector buyers.
- Cloud migration:Enterprise workload consolidation onto hyperscale platforms is displacing legacy on-premise data centers across manufacturing and financial services.
- Healthcare digitalization:Regional health authorities in Stockholm, Gothenburg, and Malmö are mandating interoperable electronic health record systems.
Market Restraints
- Hardware import dependencies:BIS certification requirements for network equipment create procurement delays and compliance cost layers for non-EU component sourcing.
- Specialized talent scarcity:Shortage of AI ethics auditors and quantum computing specialists constrains deployment velocity for advanced systems.
- Spectrum allocation bottlenecks:Swedish Post and Telecom Authority auction timelines delay 5G standalone network rollouts in northern counties.
Strategic Opportunities
- Quantum computing integration:Convergence of quantum simulation with pharmaceutical R&D workflows opens specialized service contracts in Uppsala's life sciences cluster.
- Edge infrastructure expansion:Underpenetrated industrial zones in Norrland present greenfield deployment opportunities for low-latency manufacturing automation.
- Green data center mandates:Sweden's national digitalization strategy incentives for carbon-neutral compute are attracting hyperscale facility investments.
Industry Challenges
- Interoperability complexity:Legacy hospital information systems resist seamless API integration with modern cloud-native platforms, forcing costly middleware development.
- Compliance timeline compression:Swedish Data Protection Authority's sector-specific GDPR guidance for healthcare creates documentation burdens that extend sales cycles.
- Skills transition friction:Network engineering teams require reskilling for software-defined infrastructure management, slowing enterprise adoption curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden ICT Market |
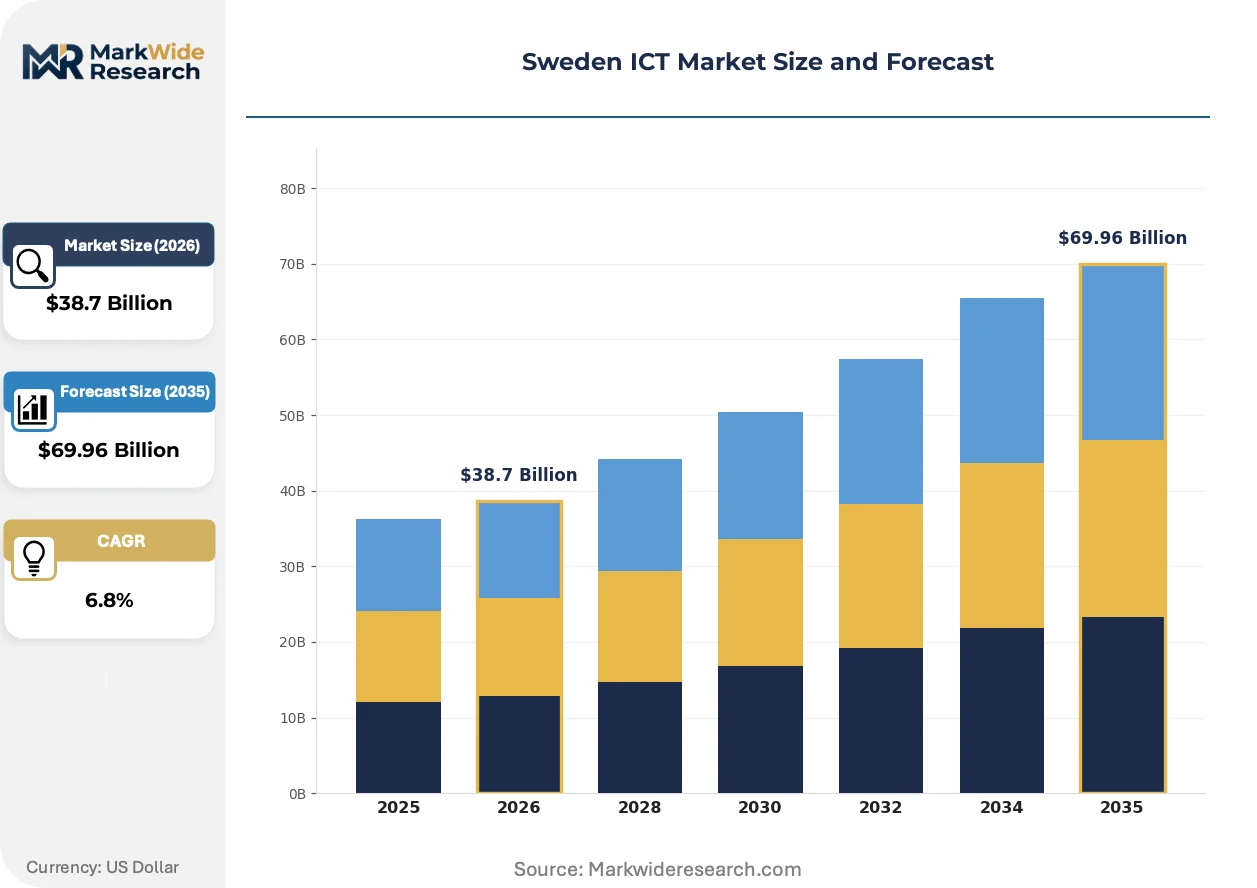
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Cloud Solutions End User: Banking, Education, Healthcare, Retail Technology: AI, IoT, Cybersecurity, Blockchain Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Cisco Systems, Google LLC, IBM Corporation, Tata Consultancy Services, Capgemini, Microsoft Corporation, Amazon, Accenture, Oracle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden ICT Market Evolving Landscape
Algorithmic accountability requirements and infrastructure consolidation are compressing vendor landscapes while reshaping how Swedish enterprises evaluate technology procurement.
Software-defined networking is consolidating control plane functions across Swedish hospital networks and municipal broadband operators. Regional health authorities in Stockholm County Council are deploying these architectures to reduce operational overhead. This consolidation is compressing the number of approved networking vendors in public sector tenders.
Swedish Data Protection Authority guidance on automated decision-making is tightening documentation requirements for AI system procurement. Healthcare providers must now maintain algorithmic impact assessments alongside traditional technical specifications. Medical imaging and diagnostic AI vendors face extended validation timelines before hospital deployment.
Subscription-based infrastructure consumption is displacing perpetual licensing in Swedish enterprise software procurement. Manufacturing firms in Gothenburg's automotive cluster are leading this transition toward operational expenditure models. Channel partners are restructuring compensation around recurring revenue rather than upfront license margins.
Sweden ICT Market Segmentation
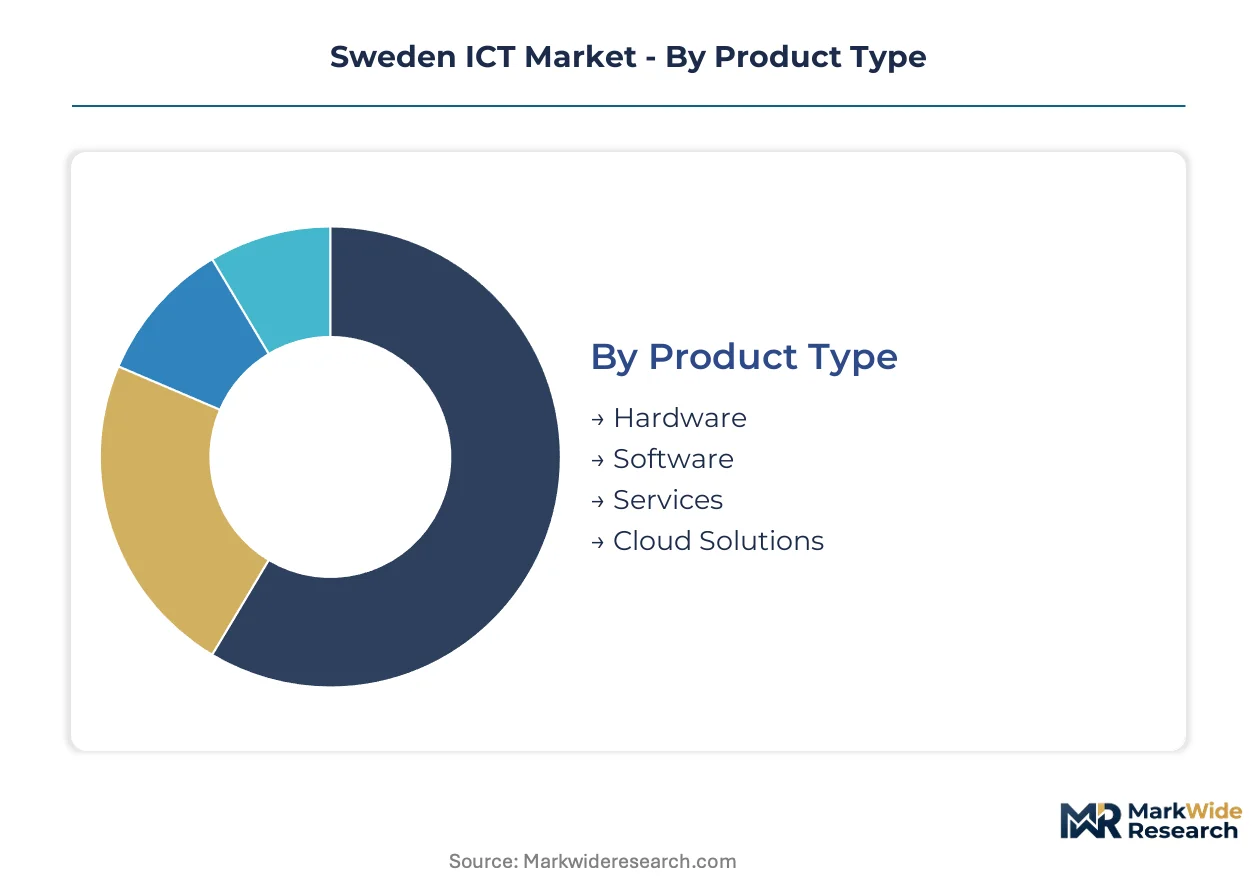
Swedish enterprises evaluate ICT procurement through four intersecting dimensions that determine compliance burden, capex profile, and integration complexity. Each segmentation axis carries distinct regulatory and operational implications for buyers in Stockholm's metropolitan technology corridor.
Product Type:
Hardware commands the largest absolute spend but compresses margins through import certification requirements, while software and services capture expanding share through subscription monetization.
- Hardware:Network equipment, servers, and endpoint devices subject to BIS certification checkpoints at procurement. Regional health authorities in Stockholm County Council prioritize hardware with embedded security modules for hospital network resilience.
- Software:Enterprise applications, operating systems, and middleware platforms delivered via perpetual or subscription licensing. Manufacturing firms in Gothenburg's automotive cluster are displacing perpetual licenses with SaaS consumption models.
- Services:Systems integration, managed operations, and consulting engagements. Mature margin pools persist in healthcare interoperability projects, though AI ethics auditing services are climbing the fastest.
- Cloud Solutions:Hyperscale infrastructure, platform services, and software-as-a-service offerings. Sweden's national digitalization strategy incentives for carbon-neutral compute are attracting hyperscale facility investments near Norrland's renewable energy sources.
Mature deployment sits with Services. Newer deployment is concentrated in Cloud Solutions.
End User:
Healthcare and banking concentrate premium procurement spend due to regulatory density, while education and retail operate on compressed evaluation cycles.
- Healthcare:Regional health authorities mandate interoperable electronic health record systems across Stockholm, Gothenburg, and Malmö. EU AI Act conformity assessments extend validation timelines for diagnostic algorithm procurement.
- Banking:Financial institutions face Swedish Data Protection Authority sector-specific GDPR guidance for automated decision-making. Algorithmic impact assessments now accompany traditional technical specifications in RFP documentation.
- Education:Municipal school systems and universities procurement standardized productivity and collaboration platforms. Cost sensitivity dominates evaluation criteria with limited specialized compliance requirements.
- Retail:Omnichannel commerce infrastructure and customer analytics platforms. Edge deployment for inventory management is gaining share fastest among mid-sized retail chains.
Procurement maturity clusters in Healthcare. Steepest expansion trajectory appears in Retail edge infrastructure.
Technology:
Cybersecurity and AI attract premium pricing through compliance mandates, while IoT and blockchain serve narrower application profiles.
- AI:Machine learning platforms, natural language processing, and computer vision systems. Medical imaging vendors face extended validation timelines before hospital deployment due to automated decision-making documentation requirements.
- Cybersecurity:Network security, identity management, and threat detection solutions. Stricter breach disclosure mandates command premium pricing across banking and healthcare verticals.
- IoT:Industrial sensors, connected devices, and edge computing nodes. Manufacturing automation in Norrland's underpenetrated industrial zones presents greenfield deployment opportunities.
- Blockchain:Distributed ledger applications for supply chain traceability and digital identity. Narrow adoption concentrated in financial services pilot programs with limited production scale.
Commercial maturity rests with Cybersecurity. Fastest technology climb belongs to AI infrastructure procurement.
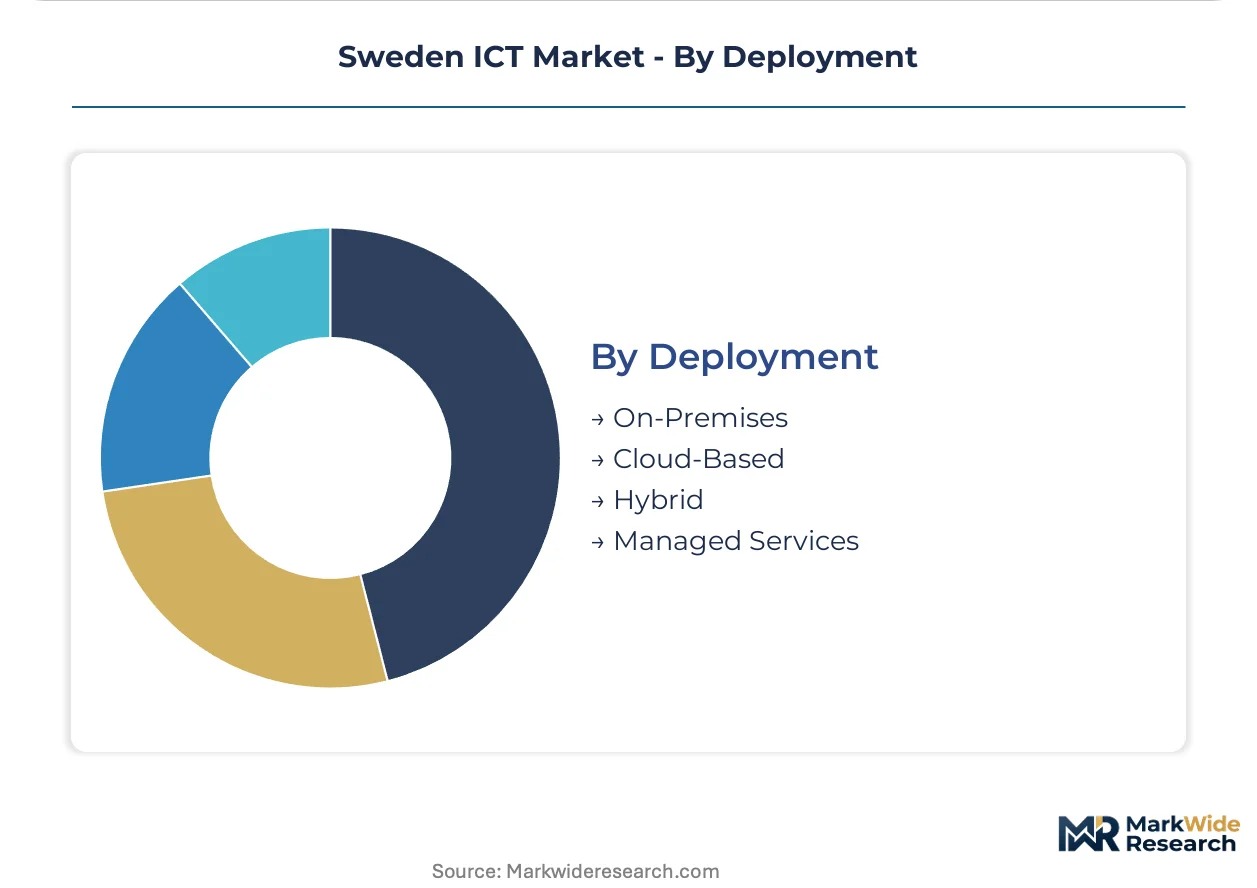
Deployment:
Cloud-based and hybrid models displace on-premises estates, while managed services capture outsourcing demand from skills-constrained organizations.
- On-Premises:Legacy data center infrastructure and dedicated hardware installations. Manufacturing and public administration retain substantial installed base resisting full migration.
- Cloud-Based:Public cloud consumption across compute, storage, and application layers. Enterprise workload consolidation onto hyperscale platforms is displacing legacy data centers.
- Hybrid:Orchestrated workloads spanning private infrastructure and public cloud resources. Banking regulators prefer hybrid architectures for sensitive data residency requirements.
- Managed Services:Outsourced infrastructure operations and security monitoring. Skills transition friction in network engineering teams accelerates managed service adoption.
Legacy concentration remains with On-Premises. Deployment momentum centers on Hybrid architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden produces advanced ICT infrastructure components while consuming integrated digital services across its metropolitan corridor. Domestic manufacturing concentrates on networking hardware and quantum research equipment. Service consumption outpaces production growth in cloud platforms and AI-enabled software layers.
Stockholm County
Regional health authorities mandate interoperable electronic health record systems across hospital networks. The Swedish Data Protection Authority applies sector-specific GDPR guidance for healthcare data processing. Kista Science City hosts quantum computing research facilities attracting pharmaceutical R&D contracts.
Västra Götaland
Gothenburg's automotive cluster drives enterprise workload consolidation onto hyperscale cloud platforms. The Swedish Post and Telecom Authority enforces network resilience standards shaping operator infrastructure investment cycles. Manufacturing firms in Torslanda industrial zone lead subscription-based infrastructure consumption models.
Skåne County
Malmö's regional health authority accelerates diagnostic AI procurement with extended validation timelines. EU AI Act conformity assessments compress vendor approval processes for algorithmic systems. Medicon Valley life sciences corridor integrates quantum simulation into pharmaceutical development workflows.
Norrland
Underpenetrated industrial zones present greenfield edge infrastructure opportunities for manufacturing automation. Sweden's national digitalization strategy incentives attract hyperscale data center investments near renewable energy sources. Piteå's greenfield compute facilities serve carbon-neutral mandates.
Sweden ICT Market Competitive Landscape
Top-tier vendors anchor hyperscale cloud and enterprise networking, while mid-tier specialists capture healthcare interoperability and quantum consulting engagements. Market structure tilts toward consolidated infrastructure layers with fragmented service overlays. Strategic archetypes include networking hardware specialists, cloud platform operators, and AI ethics auditors. Dominant competitive moves span strategic public sector partnerships and geographic expansion into underpenetrated industrial zones.
Within the cloud platform tier, Microsoft Corporation and Amazon exemplify hyperscale operators extending public sector partnership density. Cisco Systems anchors networking specialization across Nordic hospital networks. IBM Corporation occupies a position in AI and quantum computing research presence.
| Leading Market Players |
|---|
| Cisco Systems |
| Google LLC |
| IBM Corporation |
| Tata Consultancy Services |
| Capgemini |
| Microsoft Corporation |
| Amazon |
| Accenture |
| Oracle |
| Others |
Value Network & Pricing Analysis
Semiconductor component costs cascade through Swedish ICT procurement tiers, with BIS-certified networking hardware commanding premium pricing while subscription-based SaaS consumption compresses perpetual license margins across Stockholm's enterprise buyers.
Pricing Analysis
Margin tightening in hardware tiers reflects BIS certification overhead and import compliance layers. Three-tier pricing structure across certified, standard, and economy levels separates healthcare providers with EU AI Act mandates from cost-sensitive municipal education buyers. Pricing pressure intensifies in on-premises infrastructure as cloud migration accelerates. Education sector procurement committees exhibit highest price sensitivity; banking compliance officers demonstrate lowest.
Supply Chain Analysis
Certification gating through BIS checkpoints concentrates hardware sourcing from Germany, Taiwan, and China. Swedish ICT supply chains draw from specialized semiconductor foundries, rare earth magnet producers, and precision optical component manufacturers. Single-source vulnerability persists in quantum computing cryogenic systems. Distribution runs through authorized channel partners with government contracting credentials.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized AI ethics auditor scarcity props pricing for compliance services across Swedish healthcare and banking verticals.
For Market Incumbents: Cement market position through quantum computing research facility expansion in Kista Science City and exclusive Stockholm County Council networking vendor status. Threat from hyperscale cloud operators displacing on-premises infrastructure demands defensive certification investment in EU AI Act conformity assessment capabilities. For New Entrants and Emerging Players: Direct-to-government digital procurement portals offer lowest-friction entry path. White-space targets concentrate in Norrland edge infrastructure for manufacturing automation and pharmaceutical R&D quantum simulation contracts. Go-to-market through Swedish Post and Telecom Authority pre-approved vendor lists accelerates public sector access. For Investors and Strategic Acquirers: Extended validation timeline announcements for diagnostic AI hospital deployments are the leading indicator that algorithmic accountability service demand is inflecting. Long-term viability centers on compliance-automation platform consolidation. Acquisition target archetype: mid-tier healthcare interoperability specialists with Swedish Data Protection Authority audit relationships. Signal to watch: Stockholm County Council tender documentation requiring algorithmic impact assessments.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Swedish Data Protection Authority guidance creates mandatory procurement filter for high-risk algorithmic systems. |
| Quantum Computing Research Partnership | Kista Science City facilities attract pharmaceutical R&D contracts from Uppsala life sciences cluster. |
| Green Data Center Capacity Expansion | Norrland renewable energy proximity satisfies Sweden's national digitalization strategy carbon-neutral mandates. |
| Healthcare Interoperability Platform Integration | Stockholm County Council EHR mandates force middleware consolidation among regional health authorities. |
| Edge Infrastructure Geographic Expansion | Underpenetrated industrial zones in northern counties present manufacturing automation greenfield opportunities. |
Research Methodology
Document review covered Swedish Post and Telecom Authority spectrum allocation records, Swedish Data Protection Authority sector guidance, EU AI Act implementation timelines, and hyperscaler capex disclosures, complemented by interviews with hospital CIOs, regional health authority procurement leads, quantum computing research directors, and enterprise IT infrastructure managers. Secondary sources included PTS regulatory filings, European Commission digitalization strategy documents, and operator infrastructure investment announcements. Bottom-up procurement data triangulated against top-down market sizing.
Market value and volume outputs across the projection horizon reflect segment-level modeling across deployment model, end-user vertical, technology layer, and geographic adoption pattern. CAGRs were derived from weighted regression of historical investment flows and policy-mandated procurement timelines. Industry-specific inputs incorporated EU AI Act implementation phases and Sweden's national digitalization strategy incentive structures.
Inputs from Swedish regulatory filings and regional health authority tender databases were available through the study window; gaps in real-time private cloud consumption metering introduce uncertainty bands around SaaS migration velocity estimates. Forecasts reflect documented assumptions regarding compliance timeline adherence and spectrum auction schedule execution. A model refresh is warranted upon material change in EU AI Act enforcement intensity or Swedish Post and Telecom Authority infrastructure resilience standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Research and Development (Randd) Analytics Market
Analytics
APAC Retail Analytics Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
IT Operation Analytics (ITOA) Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
Audio and Video Analytics Software Market
Analytics
Global Clickstream Analytics Market
Analytics
Dark Analytics Market
Analytics
Marketing Analytics Market
Analytics
RAN Analytics and Monitoring Market
Analytics
FMCG Spending on Analytics Market
Analytics
Israel Geospatial Analytics Market
Analytics
Statistical Analytics Market
Analytics
Global Web Analytics Software Market
Analytics
Pandemic Analytics Market
Analytics
Latin America Location Based Data Analytics Market