
 Investigative Analytics Market | 2026-2036
Investigative Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Investigative Analytics Market Foresight
GDPR's extraterritorial enforcement is rebalancing compliance spending toward explainable AI architectures. IBM leverages its hybrid cloud footprint to anchor enterprise investigative deployments across regulated sectors. Palantir Technologies competes on government-grade security clearances and ontology-driven data fusion. SAS Institute differentiates through decades-deep statistical computing heritage and vertical-specific model libraries.
Investigative Analytics denotes the systematic application of statistical methods, machine learning algorithms, and network analysis techniques to structured and unstructured data sources for detecting anomalies, reconstructing events, and attributing actors in legal, financial, or security contexts. Cloud-based deployment is capturing the fastest expansion as elastic compute meets episodic investigation workloads, while on-premises retains dominance where classified or sovereign data constraints apply. Among end users, financial institutions occupy the deepest margin pools due to recurring compliance mandates, whereas law enforcement represents the most politically visible growth vector as agencies confront digital evidence proliferation.
The EU AI Act, SEC disclosure rules, and national financial intelligence unit directives collectively shape product roadmaps by mandating audit trails, human-in-the-loop safeguards, and bias documentation. ISO 27001 and SOC 2 Type II certifications function as table stakes for vendor qualification in procurement pipelines serving regulated buyers. Stakeholders must weigh interoperability investments against the fragmentation risk posed by divergent jurisdictional algorithmic governance regimes.
Market Dynamics
The EU AI Act's risk-tiered compliance framework is compressing vendor qualification timelines while forcing architectural redesigns toward explainable decision systems. Financial institutions and federal agencies now demand audit-ready pipelines that expose model logic to regulatory scrutiny.
Growth Catalysts
- Algorithmic Accountability Mandates:The EU AI Act imposes documentation burdens on high-risk automated systems. Vendors with pre-built bias detection modules capture procurement preference.
- Elastic Cloud Infrastructure:Episodic investigation workloads favor consumption-based compute. Federal modernization programs in the United States accelerate migration from fixed-capacity data centers.
- Digital Evidence Proliferation:Law enforcement agencies confront petabyte-scale multimedia archives. Network analysis tools that reconstruct actor relationships from fragmented metadata win budget allocation.
Market Restraints
- Sovereign Data Constraints:Classified investigations in defense and intelligence sectors mandate air-gapped deployments. On-premises infrastructure carries 40-60% higher total cost of ownership versus cloud alternatives.
- Specialized Talent Scarcity:Forensic data scientists with security clearance and statistical computing expertise command premium compensation. Hiring cycles extend 6-9 months for cleared positions.
- Jurisdictional Fragmentation:Divergent algorithmic governance regimes between the EU, United States, and Asia-Pacific force redundant certification investments. ISO 27001 and SOC 2 Type II function as baseline qualifiers only.
Strategic Opportunities
- Explainable AI Architectures:GDPR's extraterritorial enforcement creates demand for interpretable model outputs. Vendors embedding LIME or SHAP visualizations differentiate in regulated sectors.
- Real-Time Streaming Analytics:Fusion of Apache Kafka pipelines with graph databases enables continuous anomaly detection. Financial transaction monitoring represents the immediate beachhead.
- Subnational Government Contracts:State and municipal law enforcement agencies lag federal capabilities. Modular, pre-configured investigative platforms address budget-constrained buyers.
Industry Challenges
- Legacy System Integration:Decades-old case management databases resist API connectivity. Middleware development consumes 30-40% of implementation budgets.
- Cross-Domain Data Fusion:Structured financial records and unstructured open-source intelligence require ontology alignment. Palantir's knowledge graph approach sets interoperability expectations.
- Human-in-the-Loop Design:Regulatory mandates for meaningful human oversight complicate automation roadmaps. Workflow engineering must preserve investigator autonomy without throttling throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Investigative Analytics Market |
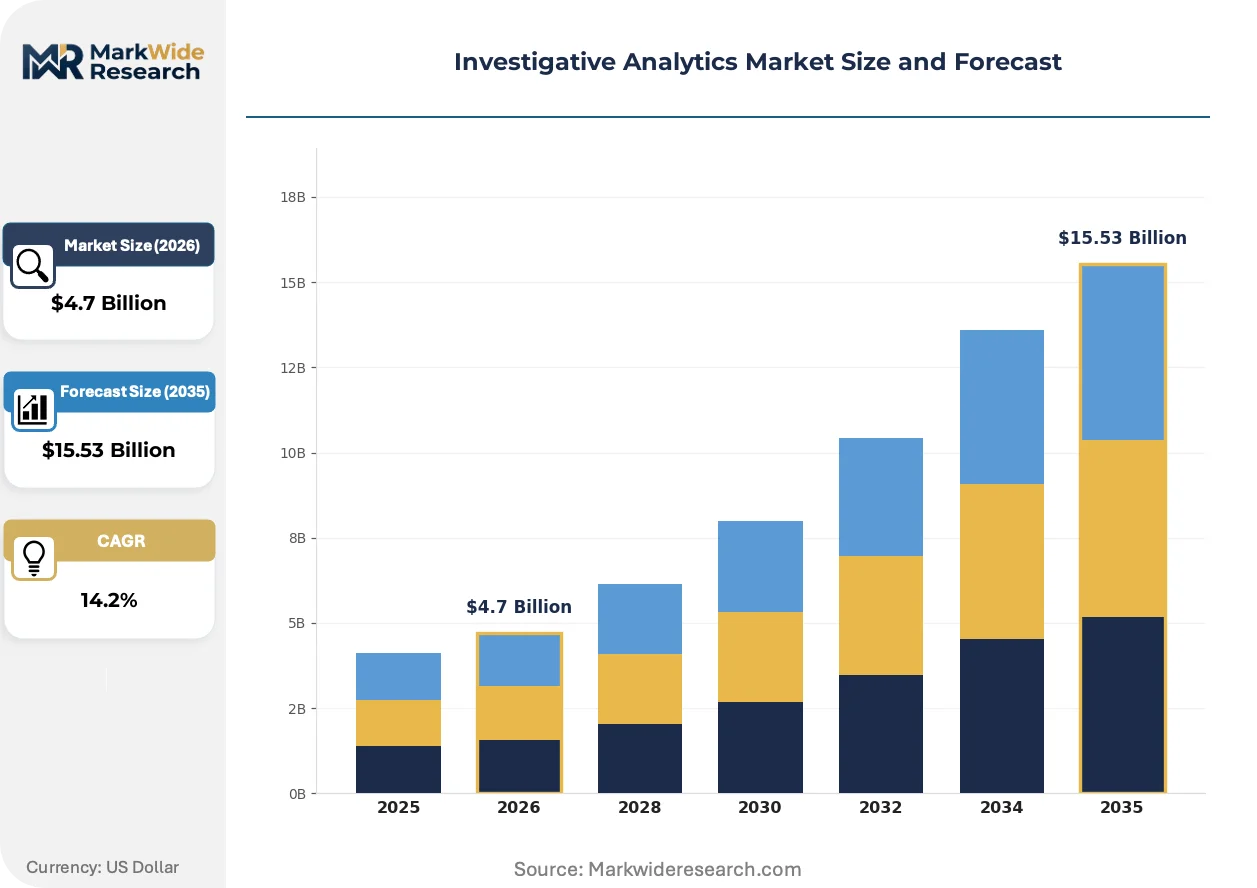
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Law Enforcement, Financial Institutions, Regulatory Bodies, Corporates Application: Fraud Detection, Risk Analysis, Compliance Monitoring, Criminal Investigation Technology: Machine Learning, Data Mining, Predictive Analytics, Visualization Tools |
| Companies Covered | IBM, SAS Institute, Palantir Technologies, Mu Sigma, Fractal Analytics, Deloitte, McKinsey & Company, Tiger Analytics, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Investigative Analytics Market Shifts & Advancements
Graph neural networks and transformer-based entity resolution are compressing investigation timelines from weeks to hours. Vendors race to embed these capabilities into consumable SaaS layers.
Graph neural networks ingest multi-relational data to identify non-obvious actor connections. Financial crime units at major banks deploy these systems for layered transaction tracing. The technology is expanding into supply chain due diligence and sanctions compliance workflows.
The EU AI Act's high-risk system classification triggers conformity assessment requirements for automated decision tools. Product roadmaps must now incorporate technical documentation, risk management systems, and human oversight mechanisms. Investigative platforms serving EU financial intelligence units face the most compressed compliance deadlines.
Subscription pricing with usage-based overage is displacing perpetual license models in mid-market accounts. Channel partners now deliver implementation and training as bundled services. This shift is most visible among United States municipal police departments with constrained capital budgets.
Investigative Analytics Market Segmentation
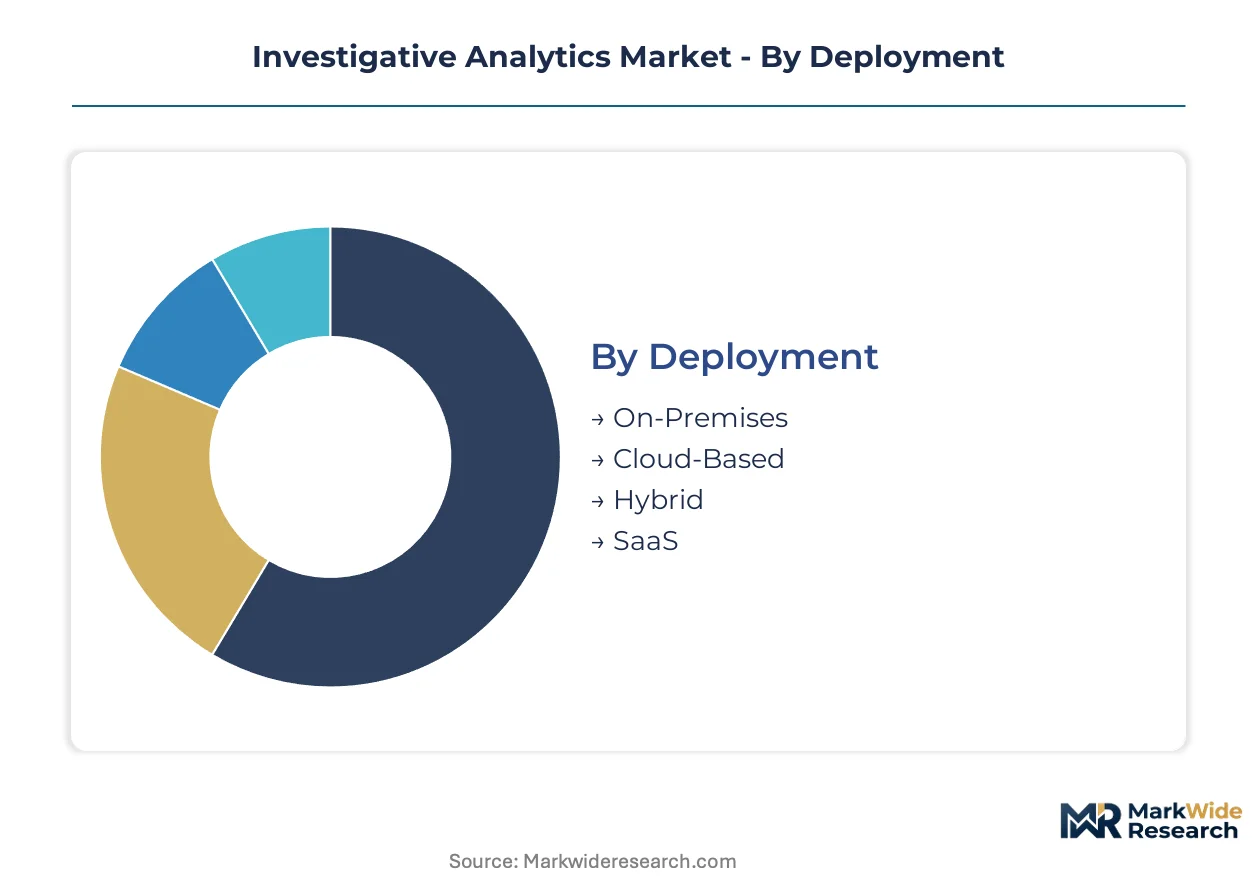
Segmentation in investigative analytics reveals how compliance architecture and data sovereignty requirements reshape procurement patterns across deployment modes, user categories, and technology stacks. Vendors must align certification roadmaps with the specific audit trails each segment demands.
Deployment:
ISO 27001 and SOC 2 Type II certifications function as baseline qualifiers for cloud and SaaS offerings, while air-gapped on-premises deployments require government security clearances and specialized facility accreditations.
- On-Premises:Physically isolated infrastructure housed within client-controlled data centers. Defense and intelligence agencies in the United States mandate these deployments for classified investigations, accepting 40-60% higher total cost of ownership to maintain sovereign data control.
- Cloud-Based:Elastic compute resources provisioned through hyperscaler partnerships. Financial institutions in Germany and France are migrating compliance workloads to EU-sovereign cloud regions to satisfy GDPR data localization requirements.
- Hybrid:Architectures split sensitive processing on-premises while leveraging cloud burst capacity for compute-intensive analytics. Regulatory bodies in the United Kingdom favor this model for balancing audit trail custody with cost efficiency.
- SaaS:Pre-configured investigative platforms delivered via subscription. Municipal police departments across the United States select these offerings for rapid deployment without capital expenditure approval cycles.
On-Premises sits at the top of the volume ranking, with Cloud-Based climbing the fastest.
End User:
Cost tier differentiation separates enterprise-grade platforms with dedicated implementation teams from modular solutions targeting budget-constrained agencies.
- Law Enforcement:Federal, state, and municipal agencies confronting petabyte-scale digital evidence archives. Agencies in the United States allocate modernization budgets toward network analysis tools that reconstruct actor relationships from fragmented metadata.
- Financial Institutions:Banks, insurers, and payment processors subject to recurring compliance mandates. Institutions in Switzerland and Singapore deploy these systems for real-time transaction monitoring and sanctions screening.
- Regulatory Bodies:Financial intelligence units and sector supervisors requiring audit-ready pipelines. EU AI Act documentation burdens are compressing procurement timelines for these buyers.
- Corporates:Multinational enterprises conducting internal investigations and supply chain due diligence. Manufacturing conglomerates in Japan utilize these platforms for vendor risk assessment and fraud prevention.
Financial Institutions command the deepest margin pools, while Law Enforcement shows the steepest expansion trajectory.
Application:
Application maturity varies by regulatory trigger density, with fraud detection representing the most standardized workflow and criminal investigation demanding the most customization.
- Fraud Detection:Pattern recognition systems identifying anomalous transactions, claims, or procurement activities. Banks in the United States and United Kingdom deploy machine learning models that flag layered money movement in real time.
- Risk Analysis:Quantitative assessment of counterparty, operational, and reputational exposures. Asset managers in Luxembourg integrate these capabilities into client onboarding and ongoing monitoring protocols.
- Compliance Monitoring:Continuous surveillance of regulatory adherence across jurisdictions. EU financial intelligence units prioritize platforms with pre-built bias detection modules to satisfy algorithmic accountability mandates.
- Criminal Investigation:Event reconstruction and actor attribution from heterogeneous evidence sources. Prosecutors in Australia and Canada adopt graph neural network tools to compress investigation timelines from weeks to hours.
Fraud Detection holds the largest installed base, with Criminal Investigation gaining share fastest.
Technology:
Supply concentration in foundation model development is concentrating vendor partnerships around a narrow set of statistical computing and visualization engines.
- Machine Learning:Supervised and unsupervised algorithms for classification, clustering, and anomaly detection. Financial crime units at major banks deploy these systems for adaptive transaction scoring.
- Data Mining:Pattern extraction from structured and unstructured repositories. Law enforcement agencies in the Netherlands apply these techniques to open-source intelligence fusion.
- Predictive Analytics:Forecasting models anticipating risk events or actor behavior. Insurance investigators in South Korea utilize these capabilities for claims fraud propensity scoring.
- Visualization Tools:Interactive dashboards and network graph renderings for investigator consumption. Platforms embedding LIME or SHAP visualizations differentiate in regulated sectors subject to explainability requirements.
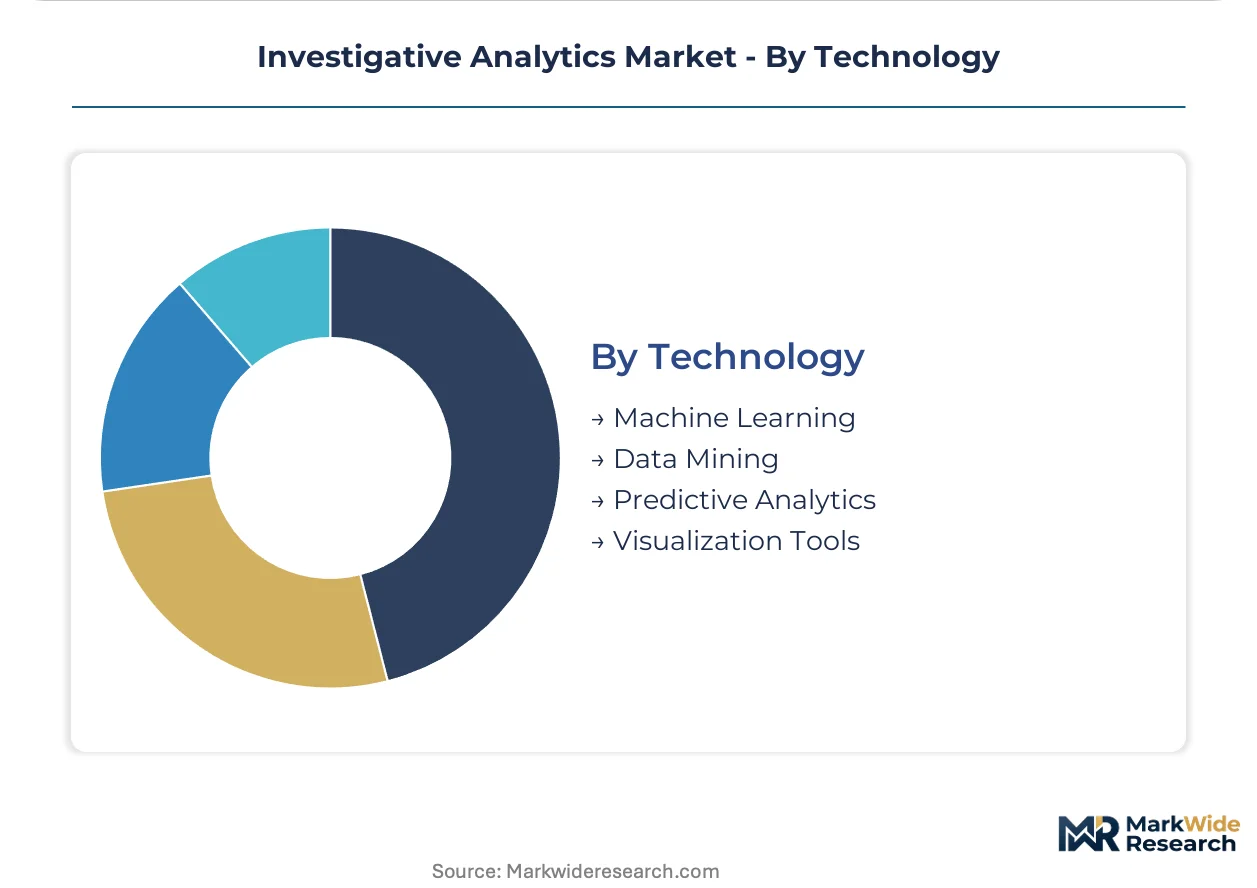
Machine Learning dominates current deployment value, with Visualization Tools expanding most quickly as explainability mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forensic data scientists with security clearance and statistical computing expertise concentrate in the United States, Germany, United Kingdom, Australia, and Singapore, anchoring investigative analytics demand in these jurisdictions.
United States
Federal agencies modernize investigative infrastructure while financial institutions expand fraud detection platforms. SEC disclosure rules and national financial intelligence unit directives mandate audit trails and human-in-the-loop safeguards. The Washington DC-Arlington-Alexandria metro corridor hosts dense concentrations of vendors serving cleared government contracts.
Germany
Banks and insurers subject to recurring compliance mandates drive platform adoption for real-time transaction monitoring. GDPR's extraterritorial enforcement rebalances compliance spending toward explainable AI architectures. Frankfurt's financial services cluster generates concentrated demand for algorithmic accountability solutions.
United Kingdom
Regulatory bodies favor hybrid architectures balancing audit trail custody with cost efficiency. The Financial Conduct Authority's supervisory technology initiatives accelerate procurement of continuous surveillance platforms. London's regulatory technology ecosystem concentrates vendors serving EU-facing financial institutions.
Australia
Prosecutors adopt graph neural network tools to compress criminal investigation timelines from weeks to hours. The country's national financial intelligence unit directives shape product roadmaps for domestic vendors. Sydney's law enforcement technology procurement hub channels federal and state modernization budgets.
Singapore
Financial institutions deploy systems for sanctions screening and counterparty risk assessment. The central bank's technology risk management guidelines influence vendor qualification requirements. The city-state's wealth management and private banking cluster sustains premium-tier platform demand.
Investigative Analytics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment modes and end-user segments. The vendor base stratifies into three tiers: global technology conglomerates with hybrid cloud footprints, government-grade security specialists with ontology-driven platforms, and statistical computing heritage firms with vertical-specific model libraries. Dominant competitive moves include strategic partnerships with hyperscaler cloud providers and portfolio diversification into explainable AI modules.
Within the government-grade security tier, Palantir Technologies and IBM exemplify divergent architectural approaches to classified investigation workflows. SAS Institute occupies a position among statistical computing heritage firms with decades-deep model libraries. Accenture anchors the consulting-anchored systems integrator segment, embedding investigative capabilities into broader enterprise transformation mandates.
| Leading Market Players |
|---|
| IBM |
| SAS Institute |
| Palantir Technologies |
| Mu Sigma |
| Fractal Analytics |
| Deloitte |
| McKinsey & Company |
| Tiger Analytics |
| Accenture |
| Others |
Supply & Pricing Matrix
Hyperscaler compute pricing indices cascade through investigative analytics supply chains, compressing margins for on-premises infrastructure vendors while amplifying pricing power for SaaS-native platforms serving budget-constrained municipal agencies.
Pricing Analysis
Bundled implementation-and-training packages separate enterprise procurement from modular SaaS tiers targeting mid-market accounts. Subscription pricing with usage-based overage displaces perpetual licenses where capital expenditure cycles stretch 12-18 months. Price differentiation rests on security clearance depth and explainable AI certification grade. Municipal police departments exhibit acute price sensitivity; cleared government contractors absorb premium tiers without elasticity.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certifications gate vendor qualification for cloud and SaaS offerings, while FedRAMP and EUCS accreditation demand redundant audit investments. Software development concentrates in the United States, Germany, and United Kingdom; cloud infrastructure draws from hyperscaler regions in Ireland, Frankfurt, and Virginia. Supply chain risk centers on single-source dependency for foundation model APIs. Distribution runs through systems integrators and channel partners delivering bundled deployment services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in investigative analytics hinges on cloud-native delivery models capturing episodic workload economics, while on-premises vendors face 40-60% cost premiums eroding competitive position.
For Market Incumbents: Anticipate regulatory compression in EU AI Act compliance timelines by pre-building bias detection modules and human-in-the-loop workflow templates. Defensive consolidation through acquisition of ontology engineering specialists addresses Palantir's knowledge graph interoperability lead. Certification investment in FedRAMP High and EUCS Level 3 anchors cleared government contract pipelines. For New Entrants and Emerging Players: Channel partners specializing in law enforcement technology procurement offer the fastest route to revenue in state and municipal agencies lagging federal capabilities. White-space targets include subnational government contracts for pre-configured investigative platforms and real-time streaming analytics for regional financial intelligence units. Go-to-market leverage rests on modular deployment avoiding capital expenditure approval cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play SaaS vendors possessing FedRAMP authorization and explainable AI visualization layers. Long-term viability favors platforms embedding graph neural network capabilities into consumable investigative workflows. Watch for inflection signals in EU AI Act enforcement velocity compressing vendor qualification timelines for non-compliant architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Module Development | LIME and SHAP visualizations satisfy GDPR extraterritorial enforcement and SEC disclosure requirements. |
| Hyperscaler Cloud Partnership | Elastic compute provisioning captures episodic investigation workloads from federal modernization programs. |
| Graph Neural Network Integration | Entity resolution compression from weeks to hours wins budget allocation at financial crime units. |
| Subnational Government Channel Buildout | State and municipal law enforcement agencies represent underpenetrated demand with constrained capital budgets. |
| Ontology Engineering Acquisition | Knowledge graph capabilities address cross-domain data fusion expectations set by government-grade competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with forensic data scientists, federal procurement officers, financial crime unit leads, and cloud platform engineers with secondary validation against SEC filings, EU regulatory submissions, hyperscaler capex disclosures, and financial intelligence unit directive documentation. Bottom-up segment sizing and top-down macroeconomic triangulation anchored value estimates.
Segment-weighting approaches distributed value across deployment modes, end-user categories, application types, and technology stacks. Modeled dimensions included sovereign data constraints, security clearance requirements, and regulatory trigger density across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves and compliance mandate enforcement schedules. Forecast inputs incorporated federal modernization budget trajectories and EU AI Act implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to jurisdictional fragmentation in algorithmic governance and hyperscaler pricing volatility. Assumptions reflect documented regulatory trajectories and procurement pipeline visibility. A model refresh is warranted upon material change in EU AI Act enforcement velocity or federal cloud migration acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
North America Crowd Analytics Market
Analytics
Data Wrangling Market
Analytics
Big Data Analytics Market
Analytics
Pandemic Analytics Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Social Business Intelligence Market
Analytics
Weather Data Services Market
Analytics
Mobile Analytics Market
Analytics
Data Mining Tools Market
Analytics
India Geospatial Analytics Market
Analytics
Network Traffic Analytics Market
Analytics
Europe Mobile Analytics Market
Analytics
France Contact Center Analytics Market
Analytics
APAC Data Wrangling Market
Analytics
Embedded Business Intelligence Market
Analytics
ASEAN Geospatial Analytics Market