
 Content Analytics and Discovery Software Market | 2026-2036
Content Analytics and Discovery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Content Analytics and Discovery Software Market Outlook
India's cloud infrastructure build-out is reconfiguring how content analytics vendors approach emerging-market delivery. Microsoft Corporation leverages its Azure data centers in Pune and Hyderabad to sustain low-latency semantic search deployments for South Asian enterprises. Google LLC anchors its competitive position through Vertex AI integration with natural language processing pipelines tailored to multilingual content repositories. Elastic N.V. differentiates via its open-core distribution model, which controls developer adoption across self-managed and SaaS deployment channels.
Content analytics and discovery software encompasses platforms that ingest unstructured text, image, and video assets, applying statistical language models, vector embeddings, and graph-based relationship mapping to extract searchable metadata and surface latent patterns. These systems process content at throughput rates exceeding ten thousand documents per hour while maintaining sub-second query response times, serving enterprises that must audit, classify, and retrieve information across petabyte-scale repositories. Text analytics and semantic search command the largest installed base, though machine learning deployments are expanding fastest as organizations automate tagging and sentiment extraction workflows. Cloud-based delivery now dominates new bookings, while on-premises installations persist in government and financial services segments where data residency requirements restrict off-premise processing.
The EU AI Act, GDPR, and ISO 27001 standards collectively reshape product roadmaps by mandating algorithmic transparency, consent audit trails, and encryption protocols for cross-border content transfers. FDA 21 CFR Part 11 and HIPAA impose additional validation requirements on analytics deployed within US healthcare content workflows. Stakeholders must weigh compliance automation investments against the architectural flexibility needed to absorb forthcoming multimodal discovery capabilities.
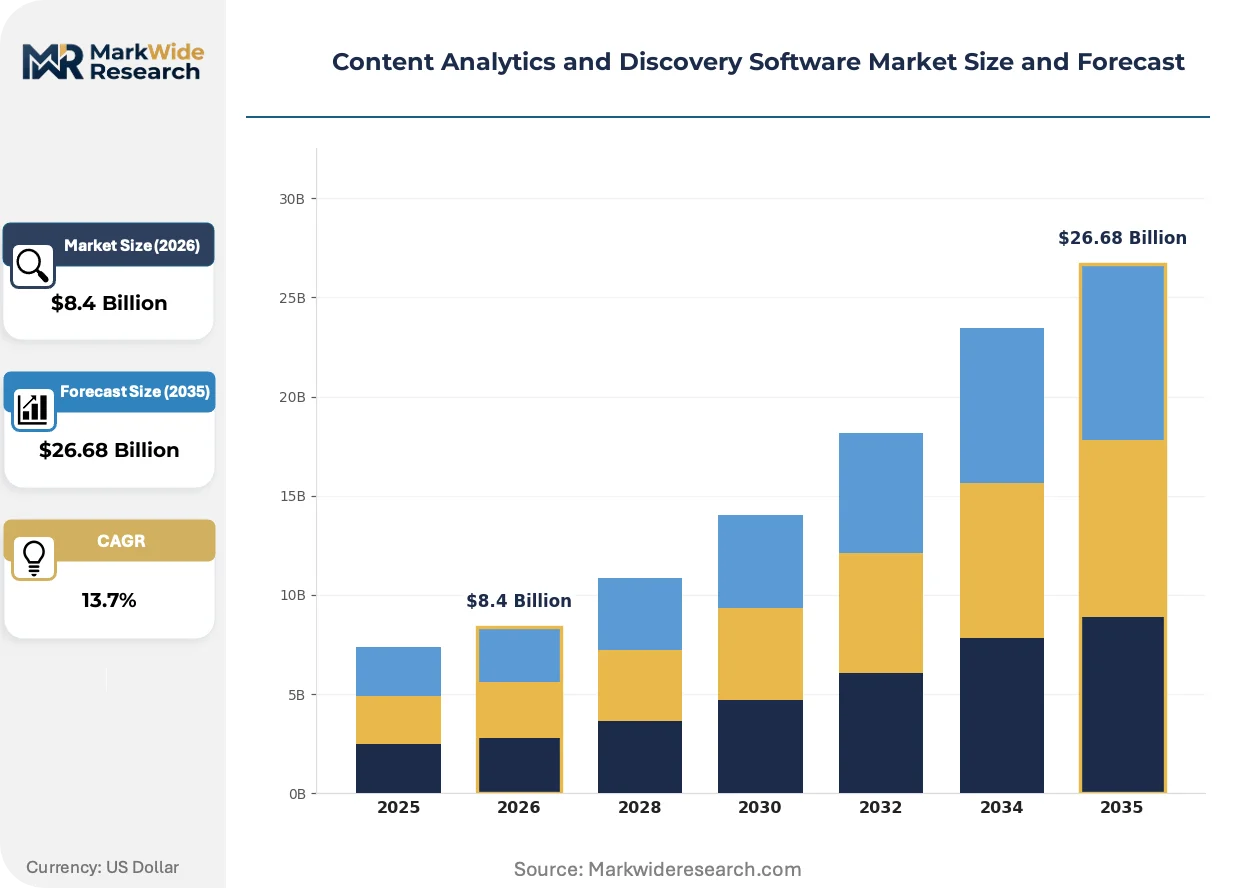
Market Dynamics
Semantic search architectures are compressing deployment cycles for content analytics platforms as enterprises replace keyword-based retrieval with vector embedding pipelines. This shift demands recalibration of vendor roadmaps around latency optimization and multilingual inference capabilities.
Growth Catalysts
- EU AI Act mandates:Automated explainability requirements accelerate procurement of audit-trail-enabled analytics by European financial services and healthcare enterprises.
- Multilingual NLP pipelines:South Asian media conglomerates deploy Indic-language semantic models to index vernacular video archives at scale.
- Vector database adoption:RAG (retrieval-augmented generation) architectures drive replacement of traditional inverted-index search infrastructure across North American enterprise knowledge management teams.
Market Restraints
- GPU compute cost volatility:Inference workload spikes expose buyers to cloud provider pricing surges that destabilize SaaS margin structures.
- Data residency fragmentation:Divergent national sovereignty rules force vendors to maintain redundant training infrastructure across jurisdictional boundaries.
- Legacy ECM lock-in:Proprietary document formats in installed SharePoint and Documentum repositories impede seamless semantic indexing migration.
Strategic Opportunities
- Brazilian enterprise underpenetration:Portuguese-language semantic search remains underserved as local media groups modernize archival digitization.
- Edge deployment channels:On-premise vector inference appliances address classified government workloads in defense and intelligence segments.
- CSRD disclosure automation:European sustainability reporting mandates create demand for ESG document classification and audit-ready extraction pipelines.
Industry Challenges
- MLOps talent scarcity:Shortage of engineers capable of productionizing transformer fine-tuning pipelines delays enterprise deployment timelines.
- ISO 27001 certification timelines:Protracted security audit cycles stall SaaS vendor entry into regulated healthcare and government procurement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Analytics and Discovery Software Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Text Analytics, Data Visualization, Machine Learning, Semantic Search Deployment: On-premises, Cloud-based, Hybrid, SaaS End User: Enterprises, SMEs, Government Agencies, Educational Institutions Technology: Natural Language Processing, Artificial Intelligence, Metadata Analysis, Predictive Analytics |
| Companies Covered | International Business Machines Corporation, Microsoft Corporation, Google LLC, Oracle Corporation, SAP SE, Adobe Inc., OpenText Corporation, Hewlett Packard Enterprise Company, Elastic N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Analytics and Discovery Software Market Strategic Shifts
Foundation model commoditization is redistributing value capture toward orchestration layers and domain-specific fine-tuning stacks. Vendors now compete on inference cost optimization and proprietary embedding quality rather than base model scale.
Transformer-based multimodal encoders are rendering obsolete single-modality search architectures that processed text, image, and video through isolated pipelines. Media archiving teams at broadcast networks adopt unified embedding spaces to cross-search news footage transcripts with visual scene descriptors. This convergence collapses vendor SKU proliferation and forces consolidation of previously separate product lines.
The EU AI Act's risk classification framework imposes documentation burdens on high-stakes content analytics deployments in hiring, credit, and law enforcement contexts. Vendors must embed algorithmic impact assessments and human oversight hooks into product workflows. Healthcare and public sector procurement in Germany, France, and the Netherlands now requires explicit conformity declarations before contract award.
Subscription fatigue among enterprise buyers compresses analytics procurement into outcome-verified pilot structures rather than annual commitments. Media and publishing procurement teams demand proof-of-concept milestones tied to measurable retrieval accuracy gains before scaling licenses. This pattern concentrates in North American mid-market accounts where CFO scrutiny of SaaS spend intensified through 2023-2024 budget cycles.
Content Analytics and Discovery Software Market Segmentation
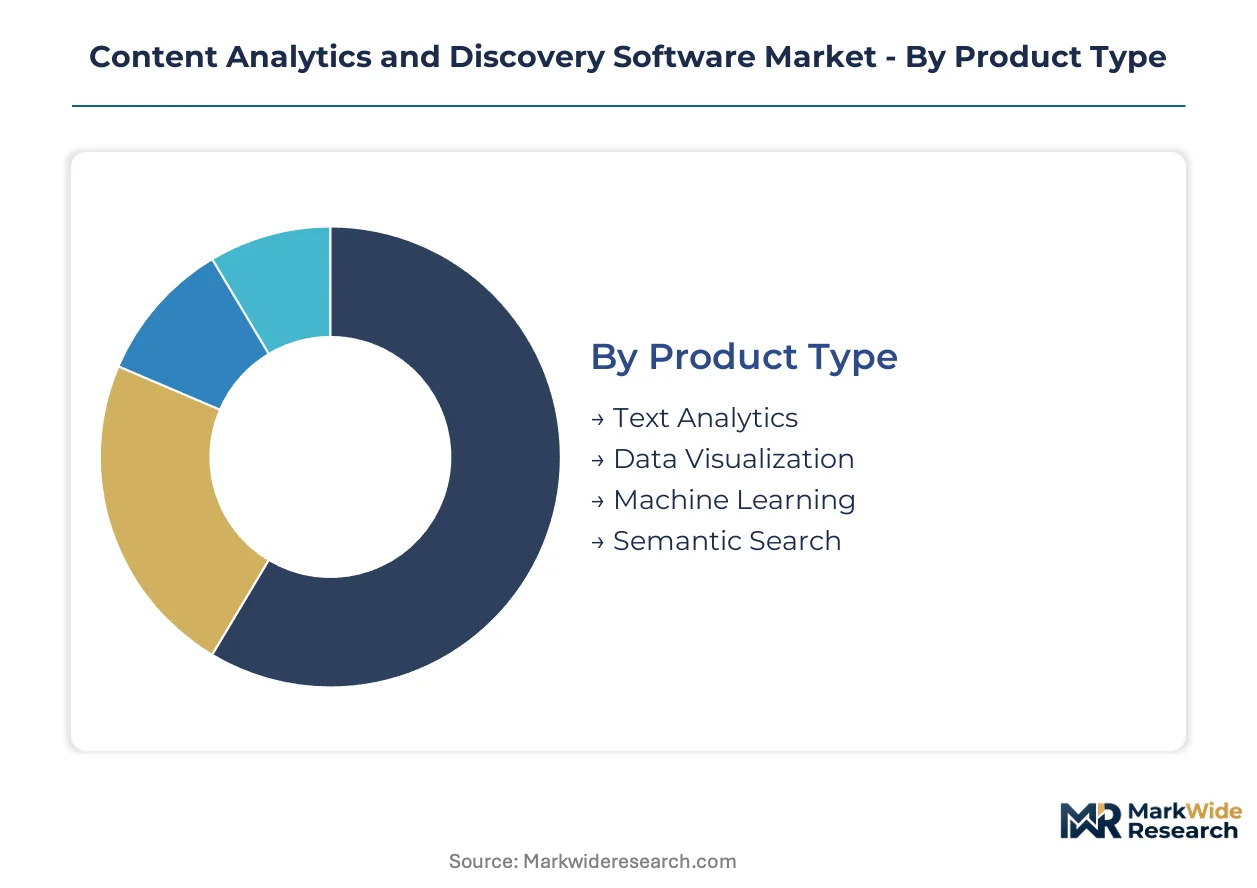
Content analytics vendors architect product portfolios around distinct technical capabilities, delivery models, and buyer sophistication tiers. Each segmentation dimension carries different margin profiles and renewal dynamics that reshape competitive positioning.
Product Type:
Semantic search platforms refresh on eighteen-month cycles as vector database architectures evolve, while data visualization tools stabilize over three-year horizons. Text analytics sits between these poles with model fine-tuning driving mid-cycle upgrades.
- Text Analytics:Statistical and neural methods extract entities, sentiment, and topics from unstructured documents at throughput rates exceeding ten thousand pages hourly. Financial services procurement teams in the United States prioritize these tools for compliance document triage under SEC audit protocols.
- Semantic Search:Vector embedding pipelines replace keyword retrieval with meaning-based matching across multilingual repositories. South Asian media conglomerates deploy Indic-language variants to index vernacular video archives, compressing discovery timeframes from days to minutes.
- Data Visualization:Dashboard layers translate analytics outputs into interactive charts and network graphs for executive consumption.
- Machine Learning:Automated classification and anomaly detection modules require continuous retraining as content distributions shift.
Text analytics dominates installed base. Semantic search is where expansion concentrates.
Deployment:
Cost tiers separate self-managed infrastructure from consumption-billed SaaS, with hybrid architectures capturing buyers seeking workload-specific flexibility.
- Cloud-based:Fully managed vector inference and storage scales elastically with query volume spikes. GDPR Article 44 cross-border transfer restrictions compel European buyers to verify provider data residency certifications before procurement.
- SaaS:Outcome-metered subscriptions align vendor compensation with indexed document volumes or monthly active queries. North American mid-market enterprises favor this model to defer capital commitment during budget scrutiny cycles.
- On-premises:Air-gapped installations serve classified government workloads where network segmentation mandates preclude external connectivity.
- Hybrid:Sensitive content remains on-premise while public models handle non-confidential inference tasks.
Cloud-based delivery captures new bookings. SaaS represents the steepest expansion trajectory.
End User:
Application sophistication varies sharply across buyer categories, with government procurement cycles extending twice as long as commercial equivalents.
- Enterprises:Fortune 500 knowledge management teams consolidate fragmented SharePoint and Documentum repositories through unified semantic layers. These buyers demand ISO 27001 certification and custom fine-tuning pipelines for domain-specific terminology.
- Government Agencies:Defense and intelligence segments require edge-deployed vector inference appliances with tamper-evident hardware modules. EU AI Act risk classification mandates impose documentation burdens on high-stakes deployments in law enforcement contexts.
- SMEs:Limited IT staffing drives preference for managed services with pre-configured industry templates.
- Educational Institutions:Research libraries and digital humanities centers prioritize multilingual capabilities for archival digitization projects.
Enterprises dominate installed base. Government agencies anchor the highest-value contract structures.
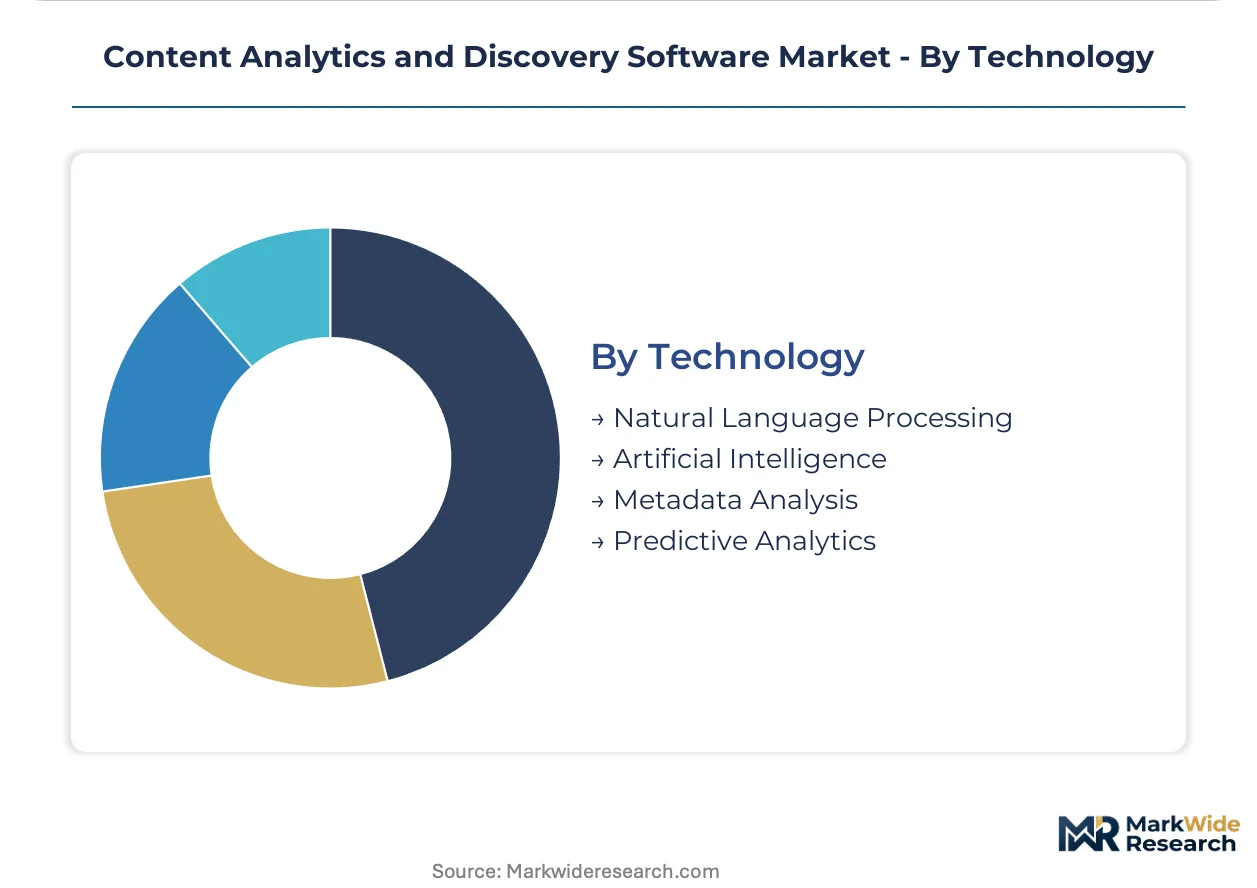
Technology:
Maturity gradients separate production-hardened NLP stacks from emerging predictive capabilities still resolving accuracy variance in edge cases.
- Natural Language Processing:Transformer-based encoders and tokenization pipelines handle syntactic parsing, named entity recognition, and coreference resolution. Brazilian media groups modernizing Portuguese-language archival systems represent an underserved demand concentration.
- Artificial Intelligence:Foundation model orchestration and retrieval-augmented generation architectures automate content synthesis and question-answering workflows. MLOps talent scarcity delays production deployment timelines for transformer fine-tuning pipelines.
- Metadata Analysis:Automated schema extraction and knowledge graph construction surface relationship patterns across document corpora.
- Predictive Analytics:Trend forecasting models project content engagement and emerging topic trajectories.
Natural language processing dominates installed base. Artificial intelligence is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transatlantic fiber optic cables landing at Ashburn, Virginia, and Lisbon anchor the data infrastructure underwriting North American and European demand concentration for content analytics platforms. These submarine systems enable sub-100 millisecond latency for vector search queries across distributed knowledge repositories.
United States
Fortune 500 enterprises in financial services and healthcare drive procurement of semantic search platforms for SEC audit compliance and HIPAA-governed clinical document retrieval. FDA 21 CFR Part 11 validation requirements shape vendor product roadmaps for regulated content workflows. The Boston-Cambridge corridor clusters AI research labs fine-tuning transformer models for specialized legal and biomedical terminology.
Germany
Industrial conglomerates and automotive suppliers deploy multilingual NLP pipelines to unify technical documentation across acquired subsidiaries. The EU AI Act risk classification framework mandates algorithmic impact assessments for HR and credit analytics deployments. Munich and Stuttgart anchor development centers where vendors embed conformity declaration workflows into product architectures.
India
Media conglomerates in Mumbai and Bengaluru scale Indic-language semantic models to index vernacular video archives spanning 22 official languages. The country's data localization directives under the Digital Personal Data Protection Act compel cloud providers to certify domestic data residency. Hyderabad and Pune host Azure data centers sustaining low-latency RAG deployments for South Asian enterprises.
United Kingdom
Publishing houses and broadcast archives in London modernize legacy content management through unified semantic layers replacing fragmented keyword retrieval. The Information Commissioner's Office enforces GDPR Article 44 cross-border transfer restrictions that filter vendor selection toward EU-certified infrastructure. The M4 corridor clusters SaaS vendors tailoring outcome-metered subscriptions to mid-market procurement teams.
Brazil
Media groups in São Paulo and Rio de Janeiro modernize Portuguese-language archival digitization, creating underserved demand for vernacular semantic search capabilities. ANVISA pharmaceutical regulations impose document retention standards that accelerate analytics procurement for compliance triage. Local broadcasters adopt cloud-based vector pipelines to cross-search news footage transcripts with visual metadata descriptors.
Content Analytics and Discovery Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying embedding models, vector databases, and fine-tuning frameworks. The vendor base stratifies into three tiers: hyperscale cloud providers with bundled analytics stacks, independent software vendors with domain-specific orchestration layers, and open-core distributions capturing developer adoption. Consolidation pressure intensifies as foundation model commoditization compresses margins on base capabilities. M&A activity targets fine-tuning specialists and regulatory compliance automation modules.
Within the hyperscale platform tier, Microsoft Corporation and Google LLC anchor competitive positioning through integrated cloud-AI stacks. Elastic N.V. exemplifies the open-core archetype, controlling developer adoption across self-managed and SaaS deployment channels. Oracle Corporation and SAP SE occupy positions in enterprise application-embedded analytics, leveraging existing database relationships to displace standalone search infrastructure.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Microsoft Corporation |
| Google LLC |
| Oracle Corporation |
| SAP SE |
| Adobe Inc. |
| OpenText Corporation |
| Hewlett Packard Enterprise Company |
| Elastic N.V. |
| Others |
Value Chain & Pricing Dynamics
GPU cluster concentration in Taiwan and South Korea anchors inference cost structures for content analytics vendors, compressing margins on SaaS tiers while concentrating profit pools in proprietary embedding model layers and regulatory compliance modules. Cloud hyperscalers leverage captive silicon supply to undercut independent software vendors on base vector search pricing.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for European deployments, mandating algorithmic transparency modules that separate premium compliance-enabled offerings from standard functionality. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 27001 and GDPR Article 44 data residency attestations commanding substantial uplifts. Cost compression in the standard tier intensifies because foundation model commoditization erodes differentiation on base semantic search capabilities. Mid-market enterprises in North America exhibit the highest price sensitivity, deferring capital commitment during budget scrutiny cycles, while government agencies in defense and intelligence segments demonstrate minimal elasticity due to classified workload requirements.
Supply Chain Analysis
NVIDIA H100 and A100 GPU feedstock from Taiwan Semiconductor Manufacturing anchors upstream availability for vector inference infrastructure, with memory module supply from South Korea and specialized networking hardware from the United States completing the critical component stack. Raw material dependencies span high-bandwidth memory dies, CoWoS packaging substrates, and optical transceivers for data center interconnect. Single-source vulnerability around TSMC's leading-edge node concentration exposes vendors to allocation rationing during demand surges. Distribution runs through hyperscaler cloud marketplaces and direct enterprise sales teams, with channel partners capturing mid-market accounts seeking managed deployment support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Content analytics vendors operate within a defensive-moat structure where regulatory entrenchment creates substantial switching costs for enterprise buyers navigating EU AI Act compliance workflows. Network effects in embedding model training data compound incumbent advantages.
For Market Incumbents: Insulate core revenue streams by embedding conformity declaration workflows directly into product architectures, preempting auditor scrutiny cycles that stall competitor entry. Deepen vertical integration into proprietary fine-tuning pipelines for specialized legal and biomedical terminology, capturing margin pools that generic foundation models cannot address. The emergence of Portuguese-language semantic search specialists in Brazil represents a credible flank threat requiring preemption through localized partnership structures.
For New Entrants and Emerging Players: Mid-market media conglomerates in Brazil and Portuguese-language archival digitization projects represent the most penetrable entry point, as incumbent hyperscalers underinvest in vernacular model development. Edge-deployed vector inference appliances for classified government workloads in defense segments offer a second white-space channel where data residency mandates exclude cloud-native competitors. A compliance-automation-first go-to-market angle, leading with EU AI Act documentation tooling rather than base search functionality, accelerates procurement traction with risk-averse European buyers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed fine-tuning specialists holding domain-specific embedding quality advantages in regulated verticals. Long-term viability across the projection horizon hinges on orchestration layer control rather than base model scale, favoring targets with proven MLOps productionization capabilities. The signal to watch is ISO 27001 certification velocity, as stalled audit timelines reliably predict vendor attrition in healthcare and government procurement frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Automation | EU AI Act conformity declarations accelerate European procurement cycles and lock out uncertified competitors. |
| Multilingual Embedding Development | Indic and Portuguese language capabilities unlock underserved demand in South Asian and Brazilian media markets. |
| Edge Vector Inference Appliances | Air-gapped deployments satisfy classified government workloads where cloud connectivity is prohibited. |
| Acquisition of Fine-Tuning Specialists | Domain-specific model quality in legal and biomedical terminology commands pricing power over generic alternatives. |
| Platform Integration Partnerships | Native embedding within SharePoint and Documentum workflows reduces migration friction for legacy ECM replacement. |
Study Parameters
A standing panel of chief technology officers, enterprise knowledge management directors, MLOps platform engineers, and channel integration specialists provided ongoing calibration across the study period. Primary interview data combined with secondary validation from SEC filings of hyperscaler cloud providers, EU regulatory submission databases, and hyperscaler capital expenditure disclosures enabled bottom-up and top-down triangulation of market sizing estimates.
Scenario-bracketing around GPU supply constraints and regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass deployment model, organization size tier, vertical industry, integration complexity with legacy ECM systems, and regional adoption pattern differentiated by data residency mandate stringency. CAGRs were derived from elasticity-adjusted technology diffusion curves incorporating vector database adoption rates and RAG architecture migration timelines as industry-specific forecast inputs.
Practitioners should monitor foundation model commoditization velocity and EU AI Act enforcement precedent for early signals requiring forecast revision. Cross-checking against hyperscaler cloud revenue disclosures and enterprise software procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Augmented Analytics in BFSI Market
Analytics
Europe Crowd Analytics Market
Analytics
Europe Edge Analytics Market
Analytics
Global Clickstream Analytics Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Face Analytics Market
Analytics
Geospatial Analytics Market
Analytics
Event Stream Processing Market
Analytics
Analytics of Things (Aot) Market
Analytics
Global Analytics Market
Analytics
Cloud Performance Management Market
Analytics
Automated Analytics Market
Analytics
Network Analysis Module (NAM) Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
Cloud Analytics Market
Analytics
Data Discovery Market