
 Business Intelligence (BI) Market | 2026-2036
Business Intelligence (BI) Market Size, Share, and Industry Trends Forecast 2026-2036
Business Intelligence (BI) Market Intelligence
The capability gap between cloud-native and legacy on-premise architectures is rotating competitive dynamics across the BI landscape. Microsoft Power BI leverages its Azure ecosystem to anchor enterprise accounts with bundled infrastructure economics. Tableau differentiates through visual analytics depth and a designer-centric interface that sustains premium positioning among data-science-adjacent teams. ThoughtSpot competes on natural language query interfaces that reduce analyst dependency for routine business questions.
Business intelligence encompasses software platforms that ingest structured and unstructured data, apply extract-transform-load (ETL) processes or modern streaming pipelines, and render actionable insights through dashboards, alerts, and predictive models. Cloud-based deployment leads solution type growth as organizations prioritize elastic compute and reduced data-center overhead over capital-intensive on-premise installations. Predictive analytics and data visualization capture expanding margin pools, while reporting functions mature into commodity features bundled within broader enterprise suites. Customer analytics and fraud detection applications absorb disproportionate R&D investment as regulated industries demand real-time pattern recognition.
The EU AI Act, GDPR, and ISO 27001 standards collectively reshape product requirements, mandating algorithmic transparency, data residency controls, and auditable decision trails that elevate engineering costs for cross-border vendors. In the United States, SEC climate disclosure rules and HIPAA safeguards for healthcare analytics create parallel compliance layers that filter market access. Stakeholders must weigh interoperability investments against regulatory fragmentation as jurisdictions diverge on automated decision-making governance.
Market Dynamics
Cloud-native architectures are decomposing the traditional enterprise BI stack, forcing vendors to unbundle monolithic platforms into composable services that integrate with existing data infrastructure rather than replacing it wholesale.
Growth Catalysts
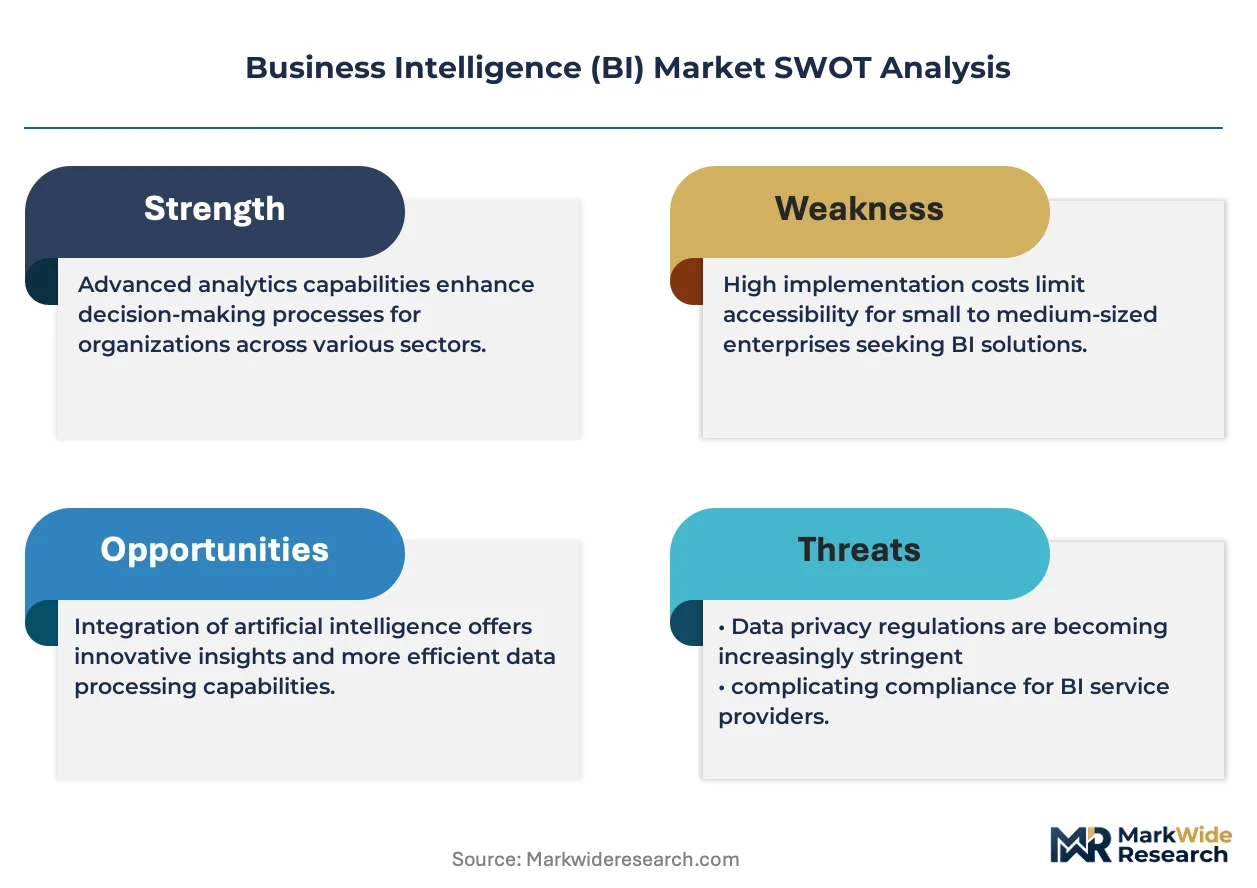
- EU AI Act compliance mandates:Financial services firms in Germany, France, and the Netherlands must deploy explainable AI for credit decisions, accelerating procurement of auditable BI platforms with built-in algorithmic transparency.
- Real-time streaming pipelines:Manufacturing and logistics operators now require sub-second latency for supply chain visibility, pulling cloud-based BI adoption beyond traditional batch-oriented reporting use cases.
- United States enterprise digital transformation budgets:Fortune 500 companies allocate disproportionate technology spending toward unified data platforms, consolidating fragmented analytics point solutions into governed enterprise deployments.
Market Restraints
- Cross-border data residency requirements:GDPR localization rules and China's PIPL fragment cloud infrastructure economics, forcing vendors to maintain redundant regional deployments that inflate operational overhead.
- Specialized talent scarcity:Data engineering and MLOps expertise concentrates in Silicon Valley, London, and Bangalore, creating wage inflation that constrains mid-market adoption velocity.
- Legacy system integration friction:Decades of on-premise data warehouse investments in healthcare and government sectors create technical debt that slows cloud migration timelines.
Strategic Opportunities
- Edge analytics deployment:Retail and industrial operators in Brazil and Mexico seek localized BI processing to reduce cloud egress costs and latency for real-time operational decisions.
- Natural language query interfaces:Convergence of large language models with semantic data layers enables self-service analytics among non-technical business users previously dependent on analyst intermediaries.
- SEC climate disclosure rules:Mandatory Scope 1-3 emissions reporting creates regulatory tailwind for BI platforms with integrated sustainability data models and carbon accounting workflows.
Industry Challenges
- Multi-cloud interoperability complexity:Enterprises demand seamless BI deployment across AWS, Azure, and Google Cloud environments, forcing vendors to abstract infrastructure differences through costly engineering investment.
- Data mesh governance implementation:Federated domain ownership models require retraining centralized IT teams to operate as platform enablers rather than gatekeepers, creating organizational resistance.
- ISO 27001 and SOC 2 certification timelines:Six-to-twelve month audit cycles delay vendor market entry in regulated industries where procurement requires current attestation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Intelligence (BI) Market |
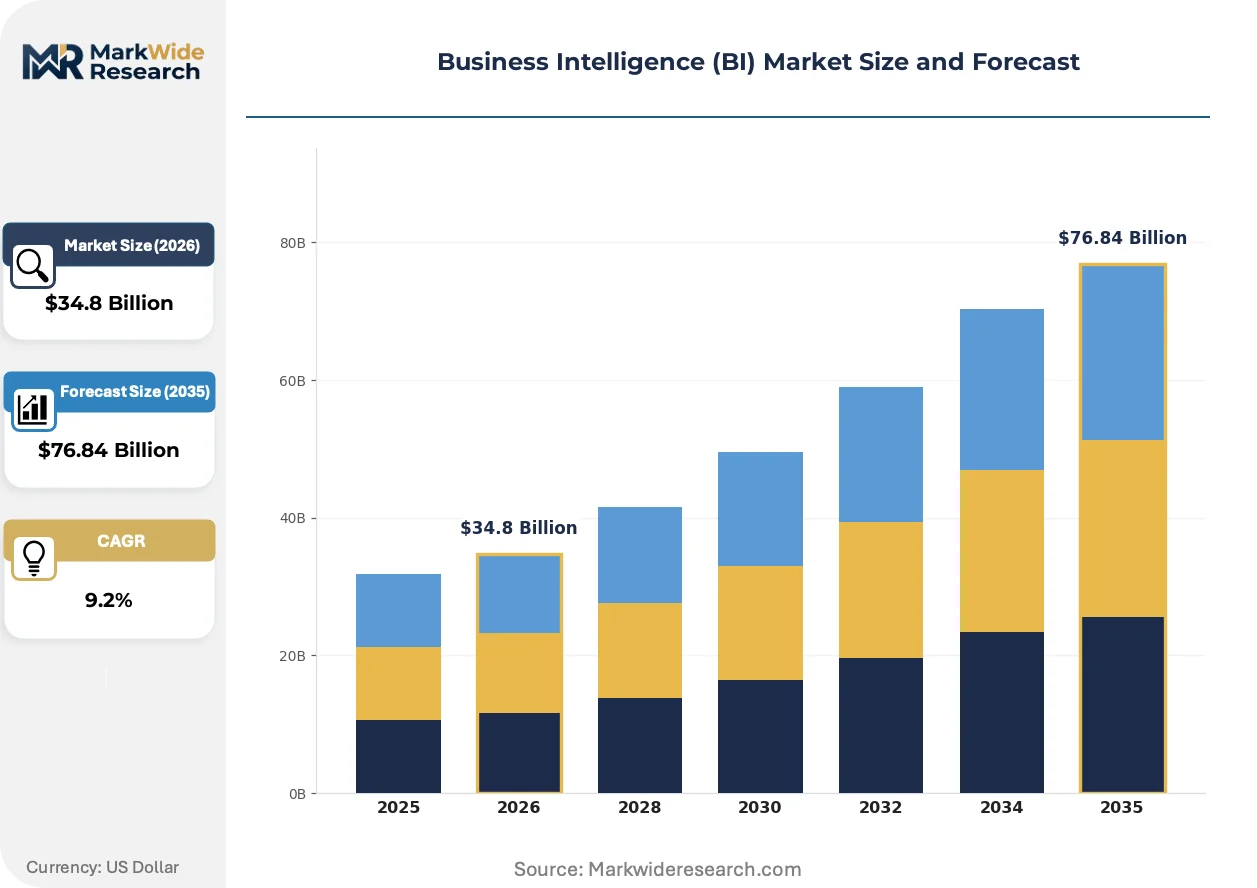
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $76.84 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
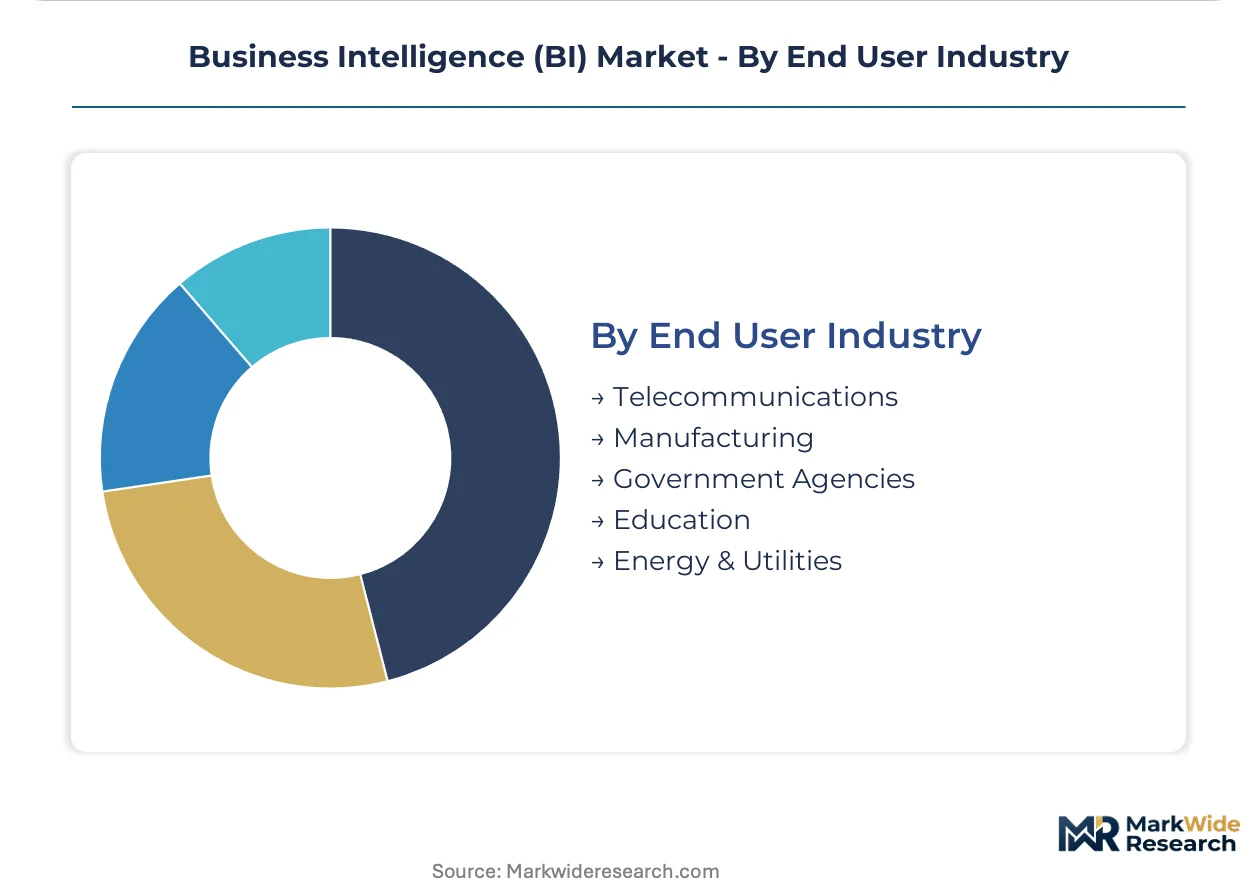
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Hosted Solution Type: Reporting, Data Visualization, Predictive Analytics, Data Mining, Dashboarding Application: Customer Analytics, Risk Management, Supply Chain Analysis, Performance Measurement, Fraud Detection End User Industry: Telecommunications, Manufacturing, Government Agencies, Education, Energy & Utilities |
| Companies Covered | IBM Cognos Analytics, Domo, Microsoft Power BI, Oracle Analytics Cloud, Sisense, Tableau, ThoughtSpot, TIBCO Software, Qlik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Intelligence (BI) Market Strategic Shifts & Innovations
Semantic layer architectures are emerging as the critical control point between raw data infrastructure and consumption interfaces, enabling governance without sacrificing the agility that business users demand from modern analytics.
Composable data architectures built on open table formats like Apache Iceberg and Delta Lake are decomposing proprietary warehouse lock-in, allowing enterprises to query unified datasets across multiple compute engines. Retail and media companies now pilot these standards to avoid vendor concentration risk. The structural consequence is compressing margins for database vendors who previously captured value through query execution monopolies.
CSRD and EU Taxonomy disclosure requirements are mandating granular sustainability reporting from 2024, forcing BI vendors to embed ESG data models and carbon calculation engines into core platform offerings. Industrial and energy sector buyers face the steepest compliance curves. German and French manufacturers are responding by consolidating sustainability and financial reporting onto single BI stacks rather than maintaining parallel systems.
Self-service analytics procurement is bypassing traditional IT gatekeepers as departmental buyers with dedicated budgets acquire embedded BI capabilities through SaaS applications. Salesforce, Workday, and ServiceNow native analytics are displacing standalone platform evaluations in mid-market sales and HR functions. This pattern is most pronounced in the United States, where line-of-business technology spending autonomy exceeds European corporate governance norms.
Business Intelligence (BI) Market Segmentation
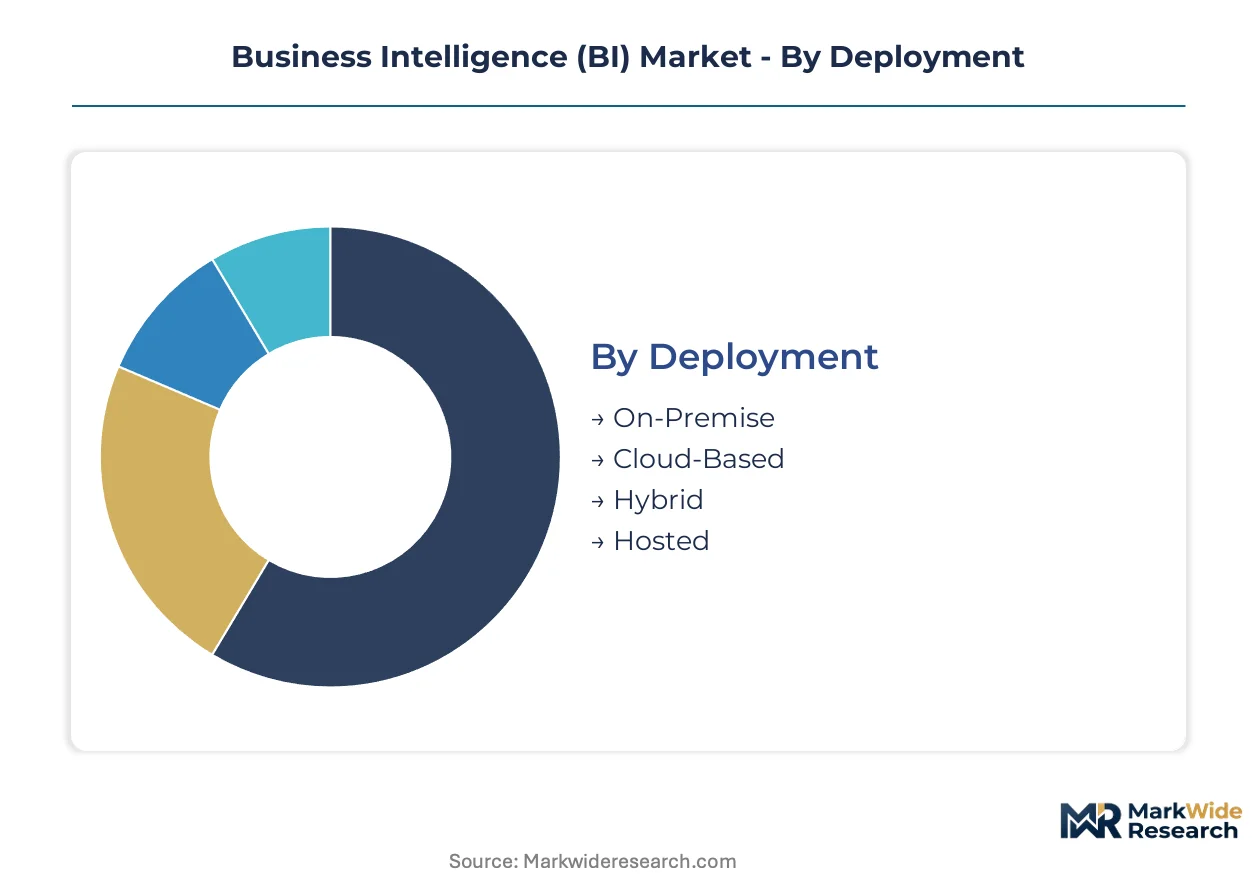
Segmentation in business intelligence reveals how compliance mandates and infrastructure economics reshape procurement patterns across deployment models, solution types, and industry verticals. Understanding these divisions exposes where vendor R&D investments concentrate and where margin compression threatens incumbents.
Deployment:
GDPR data residency rules and China's PIPL fragment infrastructure economics, forcing divergent deployment strategies across jurisdictional boundaries.
- On-Premise:Hardware-anchored installations with direct control over physical servers and network perimeter security. German automotive manufacturers and French defense contractors maintain on-premise dominance due to classified data handling requirements and Bundesamt für Sicherheit in der Informationstechnik (BSI) certification demands. Legacy technical debt in healthcare and government sectors prolongs migration timelines despite higher total cost of ownership.
- Cloud-Based:Elastic compute resources delivered through AWS, Azure, or Google Cloud with consumption-based pricing. United States financial services firms in New York and Chicago accelerate cloud procurement for real-time fraud detection pipelines, driven by SEC guidance on cloud risk management and OCC third-party vendor oversight. Multi-tenant architectures reduce upfront capital requirements while introducing shared responsibility security models.
- Hybrid:Split workloads across on-premise and cloud environments with orchestrated data synchronization. Japanese manufacturers deploy hybrid configurations to satisfy METI data localization guidelines while leveraging cloud burst capacity for quarterly financial consolidation.
- Hosted:Single-tenant managed services where vendors operate dedicated infrastructure on client behalf. Australian healthcare providers prefer hosted deployments to maintain HIPAA-equivalent controls without internal data center operations.
Cloud-Based handles the majority of throughput; Hybrid is expanding most quickly on share as regulated industries seek jurisdictional flexibility.
Solution Type:
Margin pools concentrate where algorithmic complexity creates differentiation, while commoditized functions face bundling pressure from enterprise suites.
- Reporting:Scheduled distribution of tabular data extracts through static formats. Embedded reporting capabilities in Salesforce and Workday displace standalone evaluations in United States mid-market HR and sales functions, compressing pricing power for pure-play vendors.
- Data Visualization:Interactive graphical interfaces enabling exploratory analysis without query language proficiency. Data-science-adjacent teams in London and Bangalore sustain premium positioning for specialized visualization depth, though self-service demands increasingly favor natural language interfaces.
- Predictive Analytics:Machine learning models forecasting outcomes from historical patterns. EU AI Act explainability mandates accelerate procurement of auditable predictive platforms with built-in algorithmic transparency for German and Dutch credit decisions.
- Data Mining:Pattern discovery across unstructured datasets using clustering and association techniques. Retail operators in Brazil deploy data mining for customer segmentation, constrained by cloud egress costs that favor localized processing architectures.
- Dashboarding:Real-time metric displays with alerting thresholds for operational monitoring. Manufacturing and logistics operators require sub-second latency for supply chain visibility, pulling adoption beyond traditional batch-oriented use cases.
Predictive Analytics commands the steepest pricing premiums; Dashboarding shows the broadest penetration across customer tiers.
Application:
Regulatory enforcement intensity determines R&D allocation, with fraud and risk applications absorbing disproportionate investment from compliance-driven buyers.
- Customer Analytics:Segmentation and lifetime value modeling for retention and acquisition optimization. CSRD disclosure requirements force German and French manufacturers to consolidate sustainability and customer data onto single stacks rather than maintaining parallel systems.
- Risk Management:Quantification and monitoring of operational, credit, and market exposures. Basel III operational risk frameworks and ECB stress testing mandates drive sustained procurement among Frankfurt and Paris banking headquarters.
- Supply Chain Analysis:End-to-end visibility across multi-tier supplier networks. SEC climate disclosure rules create regulatory tailwind for platforms with integrated Scope 1-3 emissions tracking and carbon accounting workflows.
- Performance Measurement:KPI tracking against strategic objectives with variance analysis. Government agencies in Washington and state capitals deploy performance dashboards for program accountability under OMB evidence-based policy guidance.
- Fraud Detection:Real-time pattern recognition for transaction and identity anomalies. United States card issuers and payment processors invest heavily in streaming pipelines that reduce detection latency below 100 milliseconds.
Fraud Detection captures the highest per-seat pricing; Supply Chain Analysis is gaining share fastest as reshoring initiatives multiply data sources.
End User Industry:
Digital transformation maturity and data infrastructure legacy create divergent adoption velocities across vertical markets.
- Telecommunications:Network performance optimization and subscriber churn prediction. Indian operators under TRAI data localization mandates deploy edge analytics to reduce international bandwidth costs while maintaining subscriber analytics depth.
- Manufacturing:Predictive maintenance and quality control through sensor data integration. German industrial clusters combine ISO 27001 certification requirements with EU Taxonomy alignment pressures, favoring vendors with pre-audited governance frameworks.
- Government Agencies:Program accountability and citizen service optimization. Federal procurement in Washington and state-level deployments face FedRAMP and StateRAMP authorization timelines that delay vendor market entry by six to twelve months.
- Education:Student outcome tracking and institutional resource allocation. United States K-12 districts and university systems consolidate fragmented analytics point solutions into governed enterprise deployments under tightening state privacy regulations.
- Energy & Utilities:Grid optimization and renewable integration forecasting. FERC Order 2222 distributed energy resource aggregation rules and state renewable portfolio standards accelerate real-time analytics investment among Texas and California grid operators.
Manufacturing contributes the largest absolute spend; Energy & Utilities shows the steepest expansion trajectory as electrification mandates intensify data requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in BI services favor net exporters with mature cloud infrastructure, while import-dependent markets accelerate domestic capacity building through data localization mandates. The United States maintains the largest trade surplus in analytics software and cloud services. Germany and China pursue strategic autonomy through sovereign cloud initiatives.
United States
Fortune 500 digital transformation budgets and SEC climate disclosure rules drive enterprise procurement. Federal procurement through FedRAMP authorization creates six-to-twelve month vendor entry delays. New York and Chicago financial services clusters deploy real-time fraud detection pipelines with sub-second latency requirements.
Germany
EU AI Act explainability mandates and Bundesamt für Sicherheit in der Informationstechnik certification demands reshape vendor selection criteria. German automotive manufacturers in Stuttgart and Munich maintain on-premise dominance for classified data handling. Industrial clusters combine ISO 27001 requirements with EU Taxonomy alignment pressures.
China
Personal Information Protection Law data localization and MIIT cloud service regulations fragment infrastructure economics. Domestic vendors capture public sector and state-owned enterprise deployments. Yangtze River Delta manufacturing hubs pilot edge analytics to reduce international bandwidth costs while maintaining operational analytics depth.
India
Telecom Regulatory Authority of India data localization mandates and RBI operational risk frameworks accelerate domestic cloud investment. Bangalore and Hyderabad data engineering talent pools concentrate MLOps expertise for global delivery models. Indian operators deploy edge analytics to reduce cloud egress costs while maintaining subscriber analytics capabilities.
United Kingdom
Financial Conduct Authority operational resilience requirements and Bank of England stress testing mandates sustain procurement among London banking headquarters. Post-Brexit data adequacy negotiations with the EU create compliance complexity for cross-border analytics deployments. UK fintech clusters in London and Edinburgh drive demand for embedded BI capabilities.
Business Intelligence (BI) Market Key Industry Players
Concentration sits with hyperscale cloud providers bundling analytics with infrastructure economics. The vendor base spans three tiers: integrated platform suites, specialized visualization tools, and emerging natural language query interfaces. Strategic moves center on semantic layer acquisitions and multi-cloud interoperability investments. Partnership architectures with data warehouse and lakehouse vendors reshape distribution economics.
Within the integrated platform tier, Microsoft and Oracle anchor enterprise accounts through bundled cloud infrastructure and database relationships. Tableau and ThoughtSpot occupy differentiated positions on visual analytics depth and natural language interfaces respectively. IBM Cognos Analytics represents the established enterprise incumbent archetype with deep compliance and governance feature sets. These four exemplify how vendor selection increasingly hinges on existing technology ecosystem commitments rather than standalone analytics capabilities.
| Leading Market Players |
|---|
| IBM Cognos Analytics |
| Domo |
| Microsoft Power BI |
| Oracle Analytics Cloud |
| Sisense |
| Tableau |
| ThoughtSpot |
| TIBCO Software |
| Qlik |
| Others |
Cost & Logistics Intelligence
Elastic compute utilization curves at hyperscale cloud providers establish the cost floor for SaaS-delivered analytics, concentrating pricing power among AWS, Azure, and Google Cloud while compressing margins for independent software vendors lacking infrastructure scale. This dynamic forces BI vendors to absorb egress fees and storage premiums into bundled subscriptions, eroding profitability for mid-tier players without ecosystem anchoring.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with predictive analytics modules commanding the steepest premiums due to EU AI Act explainability certification requirements. Price differentiation hinges on data residency controls and ISO 27001 audit depth, while cost compression in standard tiers intensifies as Salesforce and Workday embed reporting capabilities at marginal cost. Healthcare providers exhibit the highest price sensitivity due to constrained IT budgets, whereas Frankfurt banking headquarters demonstrate minimal elasticity for fraud detection latency guarantees.
Supply Chain Analysis
Container availability fluctuations across the Shanghai-Rotterdam trade lane periodically disrupt hardware delivery schedules for on-premise deployments, though cloud-native BI architectures have largely decoupled from physical logistics. Software development concentrates in the United States, India, and Ireland, with engineering talent pools in Bangalore and Hyderabad feeding global delivery models. Supply chain risk centers on single-source vulnerability for GPU-accelerated inference chips sourced from Taiwan and South Korea. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations, with channel partners handling mid-market penetration in Brazil and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switching costs embedded in semantic layer investments and governed data pipelines create durable defensive moats for established vendors, with regulatory entrenchment through FedRAMP and BSI certifications further cementing incumbent positions.
For Market Incumbents: Shield enterprise accounts by deepening integration with existing data lakehouse investments and accelerating multi-cloud interoperability roadmaps. Prioritize ISO 27001 and SOC 2 certification maintenance to exploit six-to-twelve month audit delays that block emerging competitors from regulated procurement cycles. Counter embedded BI displacement from Salesforce and Workday through vertical-specific sustainability data models that address SEC climate disclosure requirements.
For New Entrants and Emerging Players: Anchor in edge analytics deployment opportunities across Brazilian retail and Mexican manufacturing operations, where localized processing architectures reduce cloud egress cost burdens that constrain incumbent pricing flexibility. Target mid-market HR and sales functions with natural language query interfaces that bypass IT gatekeeper dependencies. Pursue partnership routes with regional system integrators possessing existing relationships in data-localization-mandated jurisdictions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms with semantic layer control points, suggesting superior long-term viability across the five-to-ten year investment horizon. Acquisition screening should prioritize vendors with pre-audited governance frameworks and established FedRAMP authorization status. The signal to watch is consolidation velocity in German automotive and French defense verticals, where classified data handling requirements sustain on-premise spending despite broader cloud migration trends.
| Strategic Initiative | Industry Significance |
|---|---|
| Semantic Layer Acquisition | Establishes governance control points between raw data and consumption interfaces for enterprise accounts. |
| Multi-Cloud Interoperability Investment | Addresses AWS-Azure-Google Cloud deployment complexity demanded by Fortune 500 procurement committees. |
| EU AI Act Compliance Certification | Unlocks German and Dutch financial services procurement for credit decision explainability mandates. |
| Edge Analytics Partnership | Captures Brazilian and Mexican manufacturing demand for localized processing and reduced latency. |
| Sustainability Data Model Integration | Aligns platform roadmaps with SEC climate disclosure rules and CSRD reporting requirements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs, IT procurement officers, data platform engineers, and channel integration specialists across the United States, Germany, and India. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie enterprise software rankings, and EU regulatory implementation guidance. Bottom-up deployment estimates triangulated against top-down enterprise technology spending surveys.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure investment trajectories. Forecast inputs incorporated cloud consumption pricing trends, data engineering wage inflation patterns, and compliance timeline accelerations from the EU AI Act and SEC climate rules.
Material uncertainties — regulatory fragmentation, talent scarcity shocks, and hyperscaler pricing volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding digital transformation budget continuity and cloud migration velocity in healthcare and government sectors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe Big Data and Business Analytics Market
Analytics
Attribution Software Market
Analytics
Big Data in Automotive Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
Dark Analytics Market
Analytics
Global Data Prep Market
Analytics
App Analytics Market
Analytics
India Geospatial Analytics Market
Analytics
Network Analytics Services Market
Analytics
Big Data Analytics Market
Analytics
Analytics of Things (Aot) Market
Analytics
Brazil Geospatial Analytics Market
Analytics
Global User and Entity Behavior Analytics Market
Analytics
Asia-Pacific Crowd Analytics Market
Analytics
Global in-Memory Analytics Market
Analytics
Statistical Analytics Market