
 Ready-To-Use Cheese Market | 2026-2036
Ready-To-Use Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Use Cheese Market Analytics
EU Green Deal carbon accounting rules for dairy processing is rebalancing the cost-of-entry calculus for new ready-to-use cheese entrants. The Kraft Heinz Company leverages its North American refrigerated distribution network to sustain shelf-stable cream cheese positioning. Dairy Farmers of America anchors its cooperative supply model across mid-Atlantic and Midwest food manufacturing clusters. Saputo Inc. competes through specialized Italian-style shredded cheese production for foodservice accounts.
Ready-to-use cheese encompasses pre-processed dairy products standardized for immediate culinary application, typically requiring no additional cutting, shredding, or tempering before use; products achieve functional stability through controlled moisture content, emulsifying salt blends, and pasteurization parameters that preserve melt characteristics across temperature ranges. Sliced cheese dominates institutional foodservice procurement due to labor-cost reduction in sandwich assembly operations. Shredded cheese captures expanding pizza chain and frozen prepared meal demand where uniform particle size controls bake consistency. Single-serve packs within the packaging type dimension concentrate margin pools in convenience retail and airline catering channels where portion control commands premium pricing.
FDA dairy plant inspection protocols and USDA grade standards govern product safety and quality benchmarks for US-manufactured ready-to-use cheese, while EFSA nutrition labeling requirements and REACH chemical compliance frameworks shape European market access conditions. These regulatory layers elevate reformulation costs for clean-label transitions but simultaneously create defensible positions for operators with established compliance infrastructure. Stakeholders must monitor evolving extended producer responsibility mandates for flexible film packaging across major dairy-consuming jurisdictions.
Market Dynamics
Quick-service restaurant chains are compressing sandwich assembly times through pre-sliced cheese procurement, while EU Green Deal emissions accounting forces dairy processors to reconfigure thermal energy systems and wastewater treatment infrastructure.
Growth Catalysts
- Quick-service restaurant expansion:Major sandwich and pizza chains are standardizing cheese-forward menu architectures, pulling volume through centralized procurement contracts that favor ready-to-use formats over block cheese.
- REACH chemical compliance frameworks:European packaging material standards are accelerating migration to mono-material flexible films, creating first-mover advantages for processors with integrated film extrusion partnerships.
- Emulsifying salt innovation:Advanced phosphate and citrate blends are extending melt stability across broader temperature windows, enabling new applications in automated pizza ovens and high-speed grilling equipment.
Market Restraints
- Milk powder price volatility:Global dairy commodity swings compress margin predictability for processors locked into annual foodservice contracts with fixed pricing clauses.
- Wisconsin and California supply concentration:Over half of US ready-to-use cheese production clusters within these two states, creating regional weather and logistics vulnerability.
- Plant-based cheese substitution:Oat and cashew-based alternatives are capturing premium positioning in sandwich chains targeting flexitarian demographics.
Strategic Opportunities
- India foodservice penetration:Pizza chain expansion in Bangalore and Mumbai is creating demand for mozzarella shreds with extended shelf life under ambient distribution conditions.
- Extended producer responsibility mandates:EU packaging waste directives are incentivizing closed-loop recycling partnerships between processors and flexible film converters.
- High-pressure processing convergence:HPP pasteurization paired with modified atmosphere packaging is opening clean-label positioning without conventional emulsifying salts.
Industry Challenges
- Food safety certification timelines:SQF and BRC audits require 12-18 month implementation cycles for new production lines, delaying capacity expansion.
- Legacy ERP integration:Lot traceability systems for dairy ingredient genealogy often conflict with modern manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Use Cheese Market |
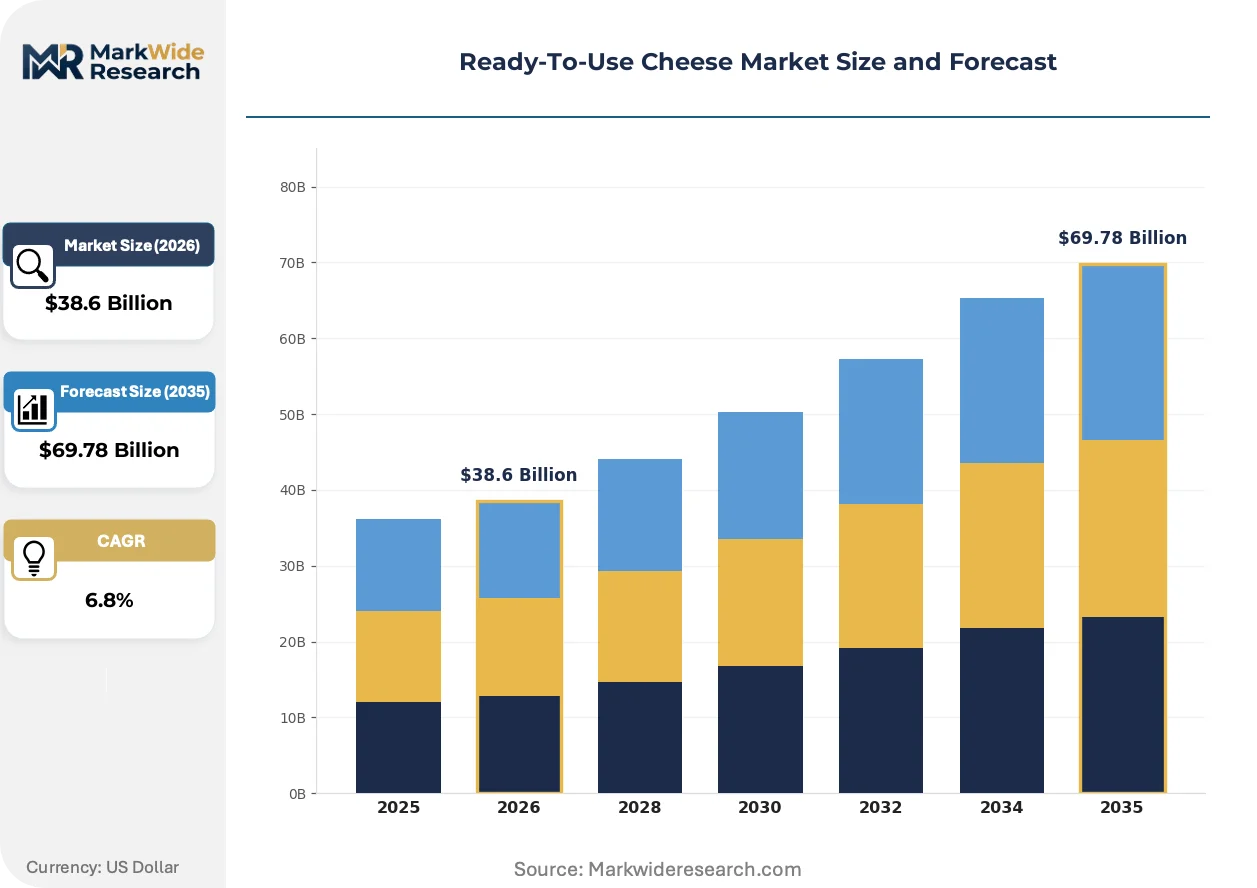
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliced Cheese, Shredded Cheese, Cream Cheese, Cheese Spreads End User: Restaurants, Catering Services, Retail Consumers, Food Manufacturers Packaging Type: Resealable Packs, Tubes, Jars, Single-Serve Packs Sales Channel: Online Retailers, Supermarkets, Convenience Stores, Wholesale Suppliers |
| Companies Covered | The Kraft Heinz Company, Dairy Farmers of America, Saputo Inc., Arla Foods amba, Fonterra Co-operative Group Limited, FrieslandCampina, Glanbia Plc, Sargento Foods Inc., Bel Brands USA, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Use Cheese Market Evolving Landscape
Clean-label reformulation and processing technology convergence are redrawing competitive boundaries between commodity processors and specialty cheese houses.
Enzyme-modified cheese technology is absorbing traditional emulsifying salt functions by accelerating protein breakdown during aging, delivering equivalent melt properties with shorter ingredient declarations. Frozen pizza manufacturers in the US Midwest are piloting this approach at commercial scale. The shift is absorbing market share from conventional process cheese formulations in private-label contracts.
EU Green Deal carbon accounting rules for dairy processing are mandating Scope 1 and 2 emissions disclosure from cheese manufacturers accessing single-market distribution. German and Dutch processors are investing in anaerobic digesters and biogas capture to offset thermal energy requirements. The regulation is compressing cost structures for smaller operators lacking capital for infrastructure retrofit.
Foodservice distributors are consolidating purchasing decisions through category management contracts that bundle cheese with proteins and bakery items. Independent pizzerias in Italy and Spain are losing negotiating leverage as procurement authority concentrates at the distributor level. The pattern is most pronounced in Southern European markets where cash-and-carry wholesale networks are consolidating.
Ready-To-Use Cheese Market Segmentation
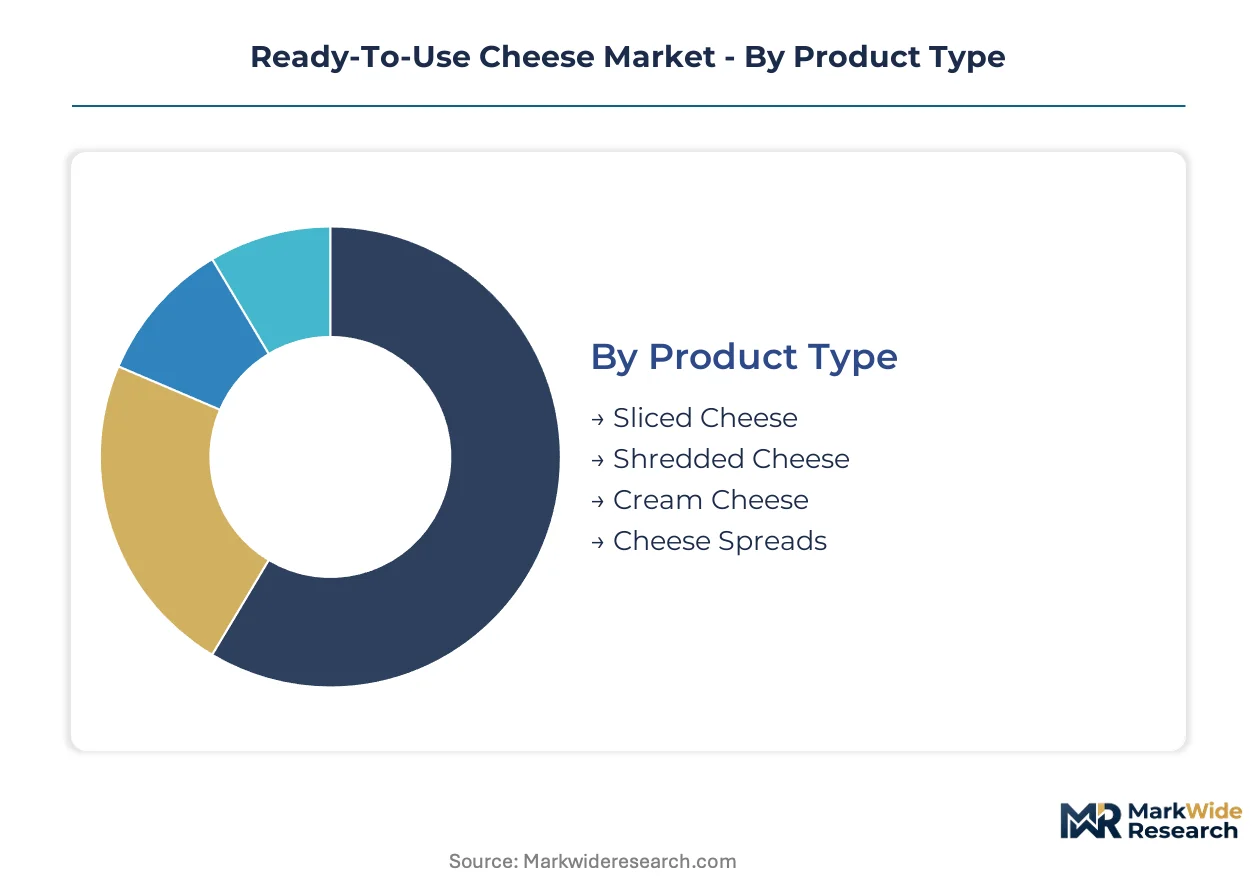
Ready-to-use cheese processors configure production lines around specific functional specifications demanded by downstream buyers. Segmentation discipline separates commodity volume plays from premium positioning strategies across foodservice and retail channels.
Product Type:
Customization intensity varies sharply across this category, with standardized formats dominating institutional procurement while specialty cuts command premium positioning in food manufacturing.
- Sliced Cheese:Uniform thickness tolerances of 1.5-2.0mm with controlled moisture migration barriers enable high-speed sandwich assembly lines. Quick-service restaurant chains in Germany's prepared food corridor are consolidating procurement around single-supplier sliced cheese contracts to reduce SKU complexity.
- Shredded Cheese:Precision-cut particle sizing between 2-4mm ensures consistent melt distribution across automated pizza ovens. Pizza chain expansion in Bangalore and Mumbai is pulling demand for mozzarella shreds with extended ambient shelf life.
- Cream Cheese:Spreadable texture stabilized through controlled fermentation and emulsifier blends targets bagel chains and bakery accounts.
- Cheese Spreads:Processed formulations with added flavoring systems concentrate in European airline catering and convenience retail channels.
Most installed capacity flows through Sliced Cheese. Expansion is steepest in Shredded Cheese.
End User:
Cost tier stratification separates high-volume contract manufacturing from fragmented spot-market purchasing across this dimension.
- Restaurants:Independent pizzerias in Italy and Spain are losing procurement leverage as distributor category management concentrates purchasing authority. Cash-and-carry wholesale consolidation across Southern Europe is accelerating this shift.
- Catering Services:Portion-controlled formats with individual wrapping dominate airline, institutional, and event catering where labor minimization overrides unit cost.
- Retail Consumers:Resealable packaging and clean-label positioning drive premium pricing in supermarket dairy cases.
- Food Manufacturers:Frozen prepared meal producers in the US Midwest specify functional cheese with guaranteed melt stability across freeze-thaw cycles.
Contract volume concentrates with Food Manufacturers. Margin expansion is most pronounced in Catering Services.
Packaging Type:
Application context determines format selection, with ambient distribution requirements and portion control needs driving divergent specifications.
- Resealable Packs:Multi-layer barrier films with oxygen scavenging layers extend refrigerated shelf life for retail repeat-purchase occasions.
- Tubes:Collapsible aluminum-plastic laminates enable controlled dispensing for foodservice saucing applications.
- Jars:Glass and polypropylene containers with wide-mouth designs target deli counter and home entertaining occasions.
- Single-Serve Packs:Hermetically sealed portion units of 15-30g command 40-60% price premiums in convenience retail and airline channels where waste elimination justifies cost.
Production throughput peaks with Resealable Packs. Value per kilogram climbs fastest in Single-Serve Packs.
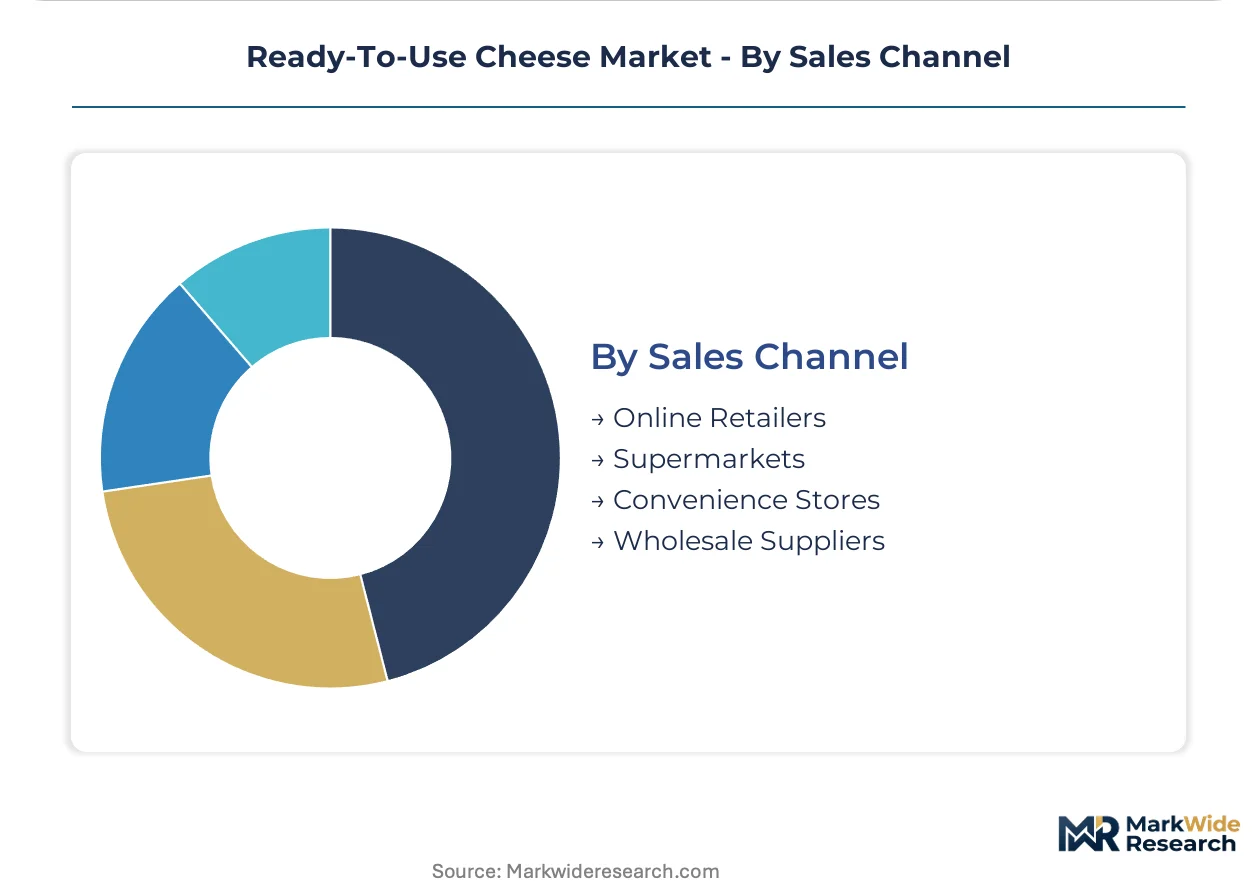
Sales Channel:
Customer type fragmentation separates consolidated national accounts from dispersed independent purchasing across geographic markets.
- Online Retailers:Cold-chain fulfillment capabilities and subscription bundling are capturing urban household demand for specialty cheese formats.
- Supermarkets:Category captain arrangements with major dairy processors determine shelf placement and promotional calendar allocation.
- Convenience Stores:Limited refrigeration space favors ambient-stable processed cheese in grab-and-go configurations.
- Wholesale Suppliers:Broadline foodservice distributors in Germany and the Netherlands are integrating cheese procurement with protein and bakery category management.
Volume throughput dominates Wholesale Suppliers. Digital penetration is expanding most quickly through Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ready-to-use cheese industry traces its commercial origins to post-war American foodservice standardization, where Wisconsin and California processors pioneered pre-sliced formats for emerging quick-service restaurant chains. European adoption followed through industrial dairy cooperatives in the Netherlands and Germany during the 1970s, establishing the transatlantic production geography that persists today.
United States
Quick-service restaurant procurement consolidation and frozen prepared meal manufacturing anchor domestic demand. FDA dairy plant inspection protocols and USDA grade standards govern interstate commerce, elevating compliance costs for cross-border suppliers. Wisconsin's Fox River Valley and California's Central Valley host the majority of national shredded and sliced cheese capacity, with processors investing in automated high-speed cutting lines.
Germany
Prepared food manufacturing corridors in Lower Saxony and North Rhine-Westphalia concentrate institutional cheese procurement. EU Green Deal carbon accounting rules mandate Scope 1 and 2 emissions disclosure, forcing thermal energy retrofits at dairy processing facilities. The country's flexible packaging converters in Bavaria are developing mono-material films to meet REACH chemical compliance for extended producer responsibility mandates.
India
Pizza chain expansion in Bangalore and Mumbai generates demand for mozzarella shreds with ambient distribution stability. FSSAI food safety regulations and BIS packaging standards shape import and local production requirements. Maharashtra's dairy processing clusters near Pune are scaling cheese powder and shred production for foodservice accounts.
Italy
Specialty shredded cheese for European foodservice accounts and domestic pizza operations drives product differentiation. EFSA nutrition labeling requirements and EU packaging waste directives influence reformulation and material selection. Emilia-Romagna's Parmigiano-Reggiano adjacent processors are diversifying into ready-to-use formats for export markets.
Netherlands
Dairy cooperative processing infrastructure and specialized ingredient exports sustain competitive positioning. REACH compliance frameworks and EU Green Deal emissions standards apply uniformly with German neighbors. FrieslandCampina's home market anchors specialized cheese ingredient production for global food manufacturing customers.
Ready-To-Use Cheese Market Competitive Landscape
The competitive structure tilts toward cooperative and publicly traded dairy conglomerates with captive milk supply and established foodservice distribution networks. Scale advantages concentrate in North American and European players with integrated refrigerated logistics. Three archetypes dominate: diversified dairy conglomerates with global ingredient portfolios, national cooperative federations with regional milk supply control, and specialized cheese houses focused on foodservice format innovation. Competitive moves center on backward integration into flexible film packaging partnerships and geographic licensing agreements for enzyme-modified cheese technology.
Among North American diversified processors, The Kraft Heinz Company and Saputo Inc. occupy positions reflecting divergent strategic emphases—refrigerated distribution network leverage versus Italian-style specialty production. Dairy Farmers of America exemplifies the cooperative federation archetype with mid-Atlantic and Midwest supply concentration. European competition clusters around Arla Foods amba and FrieslandCampina, representing dairy cooperative structures with integrated ingredient and consumer brand portfolios.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Dairy Farmers of America |
| Saputo Inc. |
| Arla Foods amba |
| Fonterra Co-operative Group Limited |
| FrieslandCampina |
| Glanbia Plc |
| Sargento Foods Inc. |
| Bel Brands USA, Inc. |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon accounting mandates now gate both qualified supply access and premium-tier pricing eligibility for ready-to-use cheese processors. German and Dutch facilities lacking anaerobic digester infrastructure face exclusion from quick-service restaurant procurement contracts that embed emissions disclosure requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates clean-label enzyme-modified formulations from conventional process cheese and commodity block alternatives. Price differentiation hinges on certification grade for EU Green Deal compliance and volume scale in annual foodservice contracts. Cost compression in the economy tier is intensifying because milk powder commodity swings compress margin predictability for processors locked into fixed-price agreements. Quick-service restaurant chains exhibit the highest price sensitivity, while airline catering channels absorb premium markups for portion-controlled single-serve formats.
Supply Chain Analysis
Milk supply rests on Wisconsin and California dairy cooperative networks that anchor over half of US ready-to-use cheese production capacity. Raw material dependencies center on specialized emulsifying salt blends, mono-material flexible films for REACH compliance, and high-pressure processing equipment for clean-label pasteurization. Single-source vulnerability concentrates in California's Central Valley, where drought risk threatens feed crop availability and milk output stability. Distribution runs through broadline foodservice distributors in Germany and the Netherlands that bundle cheese procurement with protein and bakery category management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ready-to-use cheese functions as a stable compounder anchored by quick-service restaurant procurement consolidation that locks in multi-year volume commitments. Foodservice format standardization creates predictable replacement demand cycles across sandwich and pizza chain expansions.
For Market Incumbents: Lock in backward integration into flexible film extrusion partnerships to secure REACH-compliant mono-material packaging supply before EU extended producer responsibility mandates tighten. Prioritize anaerobic digester retrofit investments at German and Dutch processing facilities to defend margin position against carbon-accounting-driven procurement exclusion. Plant-based cheese substitution in flexitarian-targeting sandwich chains demands accelerated enzyme-modified cheese R&D to compress ingredient declarations. For New Entrants and Emerging Players: High-pressure processing convergence offers a technology-first wedge into clean-label positioning without conventional emulsifying salts. Target India's ambient-stable mozzarella shred segment, where pizza chain expansion in Bangalore and Mumbai outpaces local production capacity. Pursue licensing agreements with enzyme-modified cheese technology holders rather than building captive R&D infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized specialty cheese houses because distributor category management concentrates procurement authority and rewards scale. Five-to-ten year viability favors processors with integrated refrigerated logistics and established SQF or BRC certification infrastructure. Watch FSSAI regulatory evolution in India as the signal indicating when to accelerate foodservice penetration investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flexible Film Extrusion | REACH-compliant mono-material supply secures EU market access ahead of extended producer responsibility mandates. |
| Anaerobic Digester Infrastructure Investment | Biogas capture offsets thermal energy costs and satisfies EU Green Deal Scope 1 disclosure requirements for German processors. |
| Enzyme-Modified Cheese Technology Licensing | Clean-label positioning absorbs market share from conventional process cheese in private-label frozen pizza contracts. |
| Ambient-Stable Shred Formulation Development | Extended shelf life under non-refrigerated distribution unlocks pizza chain procurement in India's emerging foodservice corridors. |
| High-Pressure Processing Line Installation | HPP pasteurization paired with modified atmosphere packaging eliminates emulsifying salts for premium retail positioning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy processing executives, foodservice procurement directors, flexible film converter technical leads, and regulatory compliance officers with secondary validation. Trade data from customs records, SEC filings from publicly traded dairy conglomerates, EU ETS emissions disclosure databases, and FSSAI food safety registration filings anchored supply-side estimates. Bottom-up capacity modeling and top-down demand aggregation triangulated volume figures across the projection horizon.
Comparable-period anchoring tied forward projections to historical production and consumption patterns across the analysis window. Segmentation dimensions modeled included product type, end-user channel, packaging format, and sales channel, with additional granularity on clean-label versus conventional formulation splits. CAGRs derived from regression analysis of volume trends against quick-service restaurant expansion rates, EU regulatory phase-in schedules, and foodservice distributor consolidation patterns. Industry-specific forecast inputs incorporated milk powder commodity price volatility indices and REACH chemical compliance timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement stringency, plant-based cheese substitution velocity, and India cold-chain infrastructure buildout pace. Assumptions reflect documented stakeholder input and published regulatory schedules. A small set of triggers—FSSAI rule finalization, California drought severity, and quick-service restaurant menu architecture shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Low Fat Butter Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
High Protein Yogurt Market
Dairy Products
North America Sour Cream Market
Dairy Products
UHT Milk Market
Dairy Products
Non-Fat Milk Market
Dairy Products
South America Flavored Milk Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Goat Milk Powder Market
Dairy Products
Sheep Milk Market
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Drinkable Yogurt Market