
 Europe Dried Fruit and Edible Nuts Market | 2026-2036
Europe Dried Fruit and Edible Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dried Fruit and Edible Nuts Market Intelligence
The Europe Dried Fruit and Edible Nuts Market is recalibrating around a widening split between premium organic lines and commodity bulk supply. Virgin Nuts B.V. leverages its specialized roasting and flavoring infrastructure to command shelf space in Dutch and Belgian specialty retail. Archer-Daniels-Midland Company anchors its position through backward integration into Turkish and Californian almond origination. Olam International Limited differentiates via its digital traceability platform that tracks cashew lots from West African cooperatives to European confectionery clients.
Dried fruit and edible nuts comprise dehydrated or naturally dried pommes, drupes, berries, and tree nuts with moisture content typically below 20 percent, preserved for extended shelf stability without refrigeration and deployed across food manufacturing, foodservice, and direct consumption channels. Almonds within the product type dimension lead absolute volume due to their versatility in dairy alternatives and bakery formulations, while diced and sliced forms capture disproportionate margin from industrial buyers seeking labor-cost reduction. Online retail within sales channels represents the fastest-expanding route as direct-to-consumer nut subscription models gain traction in Nordic markets.
EFSA governs maximum residue limits and allergen labeling protocols that determine which import lots clear customs at Rotterdam and Hamburg. REACH and the EU Green Deal due diligence framework are forcing traders to document deforestation-free supply chains for Brazilian nuts and Turkish apricots. Stakeholders must monitor how ECHA expands chemical contaminant screening before committing to multi-year procurement contracts with new origin suppliers.
Market Dynamics
The EU Green Deal due diligence framework is forcing traders to reconstruct supply chains for Brazilian nuts and Turkish apricots, creating a compliance moat that favors operators with pre-existing traceability infrastructure over spot-market intermediaries.
Growth Catalysts
- EFSA allergen labeling protocols:Stricter enforcement at Rotterdam and Hamburg customs is filtering out non-compliant import lots, reducing price competition from low-grade suppliers and protecting certified operators.
- Plant-based dairy alternatives:Almond and cashew bases in European oat-milk and yogurt formulations are pulling industrial-grade nut volumes into long-term supply contracts.
- German private-label expansion:Discounter nut portfolios are widening shelf-space allocation for value-added SKUs, concentrating regional demand pull.
Market Restraints
- Water stress in Californian almond orchards:Irrigation restrictions and drought cycles are injecting volatility into the dominant global origin for European imports.
- Turkish apricot supply concentration:Malatya province controls over 80 percent of dried apricot origination, creating single-point vulnerability to climatic shocks and currency swings.
- REACH chemical contaminant screening:ECHA expansion of pesticide residue testing is lengthening customs clearance times and raising rejection rates for West African cashew shipments.
Strategic Opportunities
- Nordic direct-to-consumer subscription models:Swedish and Danish consumers are adopting recurring nut delivery services, opening a channel bypassing traditional retail margin stacking.
- EU Green Deal deforestation-free certification:Early compliance with supply-chain documentation requirements positions operators for preferential procurement terms from major confectionery clients.
- Blockchain-IoT convergence:Integration of distributed ledger systems with humidity sensors during container transit is enabling premium pricing for provably stable moisture-content guarantees.
Industry Challenges
- Roasting technician scarcity:Specialized flavor-development expertise is concentrated among aging workforces in Dutch and Belgian processing facilities, constraining capacity expansion.
- Organic certification timeline compression:Three-year conversion periods for orchard land are misaligned with buyer demand surges, creating supply-demand mismatches.
- Legacy ERP integration with traceability platforms:Mid-sized traders face capex burdens and data-fragmentation risks when overlaying digital lot-tracking onto decades-old inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dried Fruit and Edible Nuts Market |
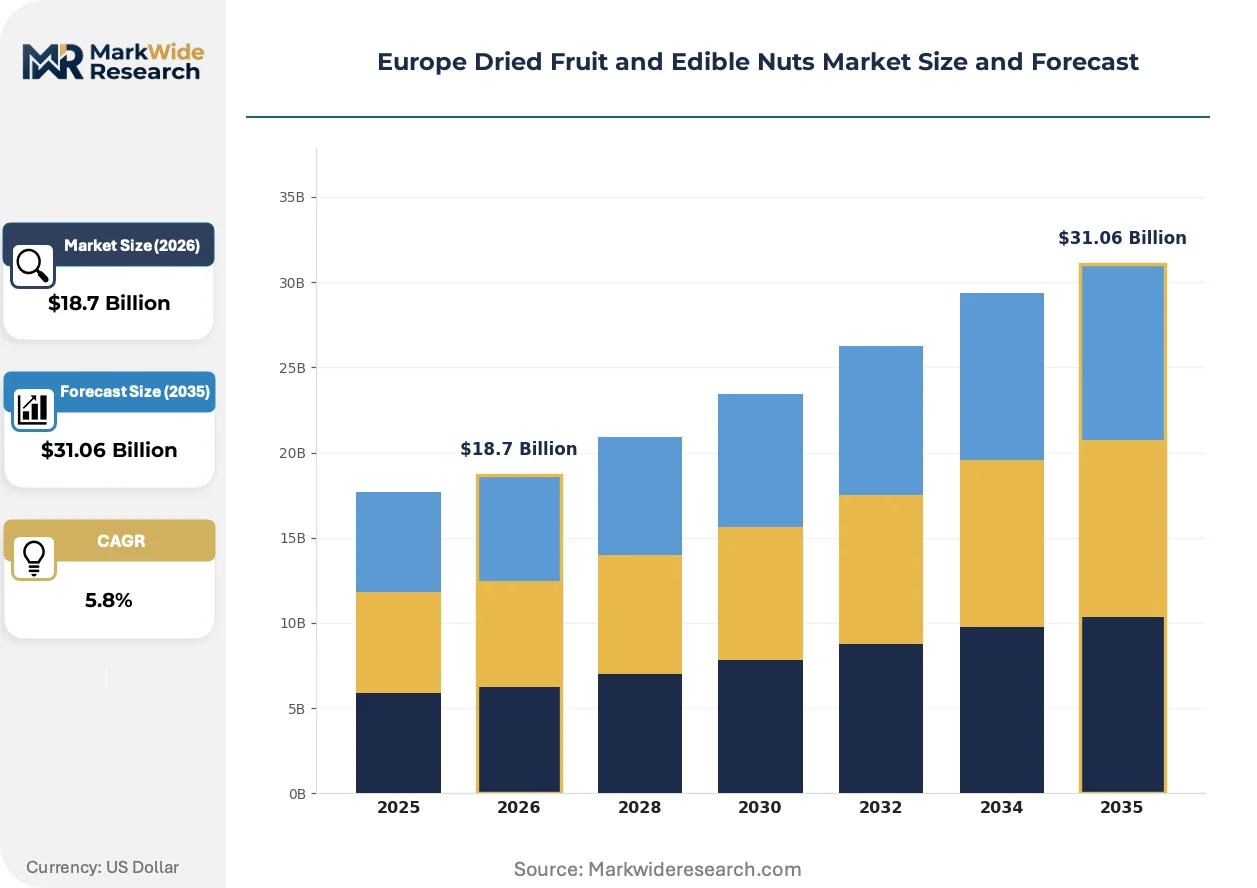
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almonds, Cashews, Raisins, Apricots Form: Diced, Whole, Sliced, Chopped End Use: Baking, Snacking, Cooking, Confectionery Sales Channel: Supermarkets, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | Ocean Spray Cranberries Inc., Virgin Nuts B.V., Archer-Daniels-Midland Company, Kiantama Ltd., HBS Foods Ltd., Olam International Limited, Fresh Nuts GmbH, Murray River Organics, Arimex Uab, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dried Fruit and Edible Nuts Market Strategic Shifts & Innovations
Processing technology and sourcing transparency are converging to reshape competitive positioning across the European dried fruit and edible nuts landscape, with digital traceability and automation separating scalable operators from commodity traders.
Hyperspectral sorting systems are overtaking manual color-based grading in Turkish and Spanish almond processing facilities. Industrial roasters in the Netherlands and Belgium are adopting these optical sorters to detect aflatoxin contamination and shell fragments at line speeds exceeding human capability. The technology is overtaking traditional quality-control labor pools, compressing unit economics for mid-volume processors unable to justify capital deployment.
REACH authorization requirements for food-contact substances are tightening specifications for packaging films used in dried fruit retail packs. ECHA's expanding candidate list of restricted chemicals is forcing converters to reformulate laminates and coatings, adding raw-material cost pressure. German and French private-label buyers are responding by consolidating supplier bases toward vertically integrated packaging firms with in-house compliance laboratories.
Snacking occasions are fragmenting across dayparts and formats, with single-serve nut pouches displacing bulk-bin purchases in convenience retail. Younger consumers in urban UK and Scandinavian markets are prioritizing portion-controlled, flavor-innovated SKUs over traditional commodity bags. This behavioral pivot is most visible in London and Stockholm, where grab-and-go formats now command premium shelf positioning and expanded facings.
Europe Dried Fruit and Edible Nuts Market Segmentation
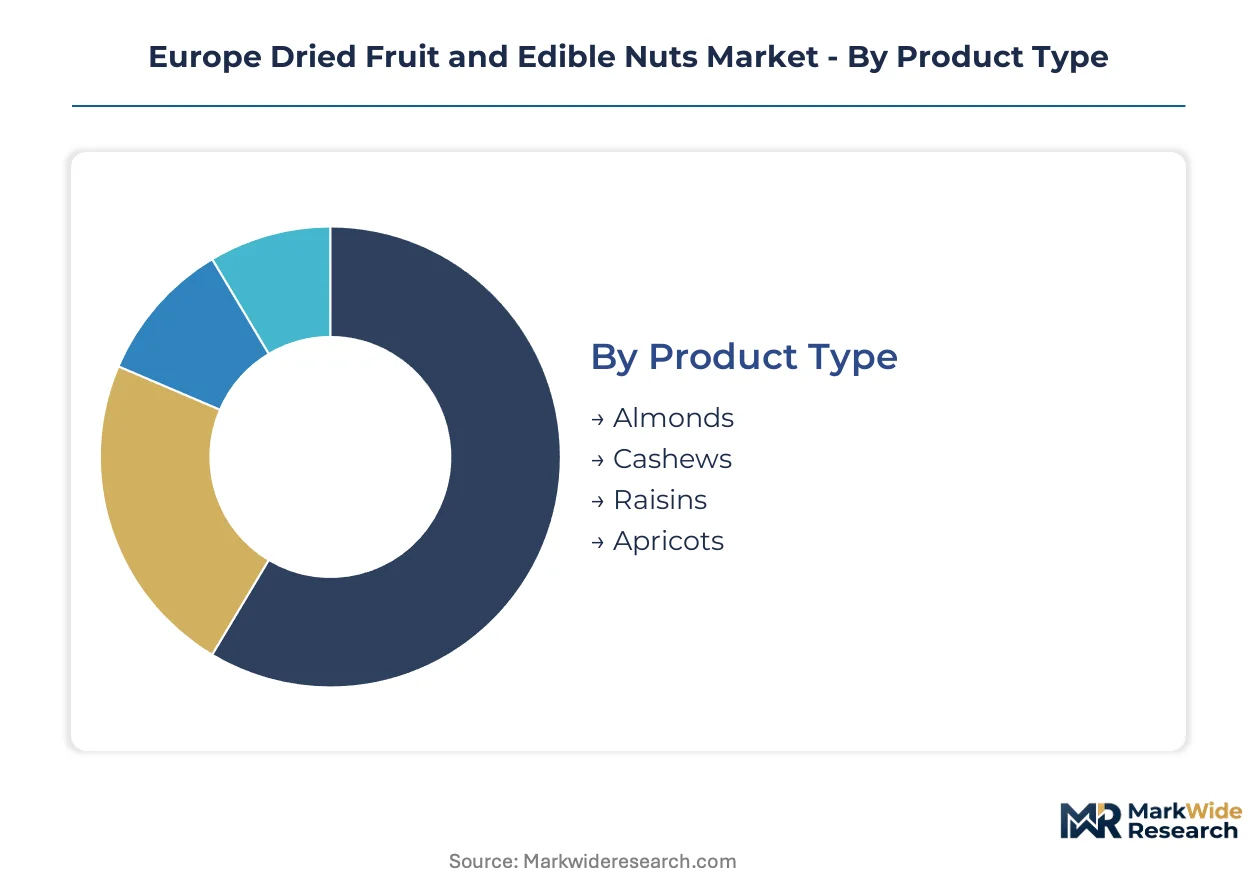
European buyers of dried fruit and edible nuts exhibit sharply divergent procurement behaviors across product specifications, channel preferences, and application requirements. Understanding these fault lines enables suppliers to calibrate pricing, certification investments, and distribution partnerships against actual purchasing logic rather than assumed commodity demand.
Product Type:
Buyers differentiate primarily by functional versatility in downstream formulations and vulnerability to supply-side shocks.
- Almonds:Tree nuts with high protein and healthy fat profiles, processed into whole kernels, blanched slivers, and almond flour for industrial use. German dairy-alternative manufacturers and Dutch bakery ingredient distributors anchor demand, though Californian water restrictions inject price volatility into long-term contracting.
- Cashews:Kidney-shaped nuts requiring steam-shelling and roasting before consumption, valued for creamy texture in vegan cheese and confectionery applications. Nordic oat-milk producers and Belgian chocolate houses are pulling West African origination into direct supply relationships, bypassing traditional spot-market intermediaries.
- Raisins:Dehydrated grape berries with standardized moisture specifications for industrial baking and breakfast cereal inclusion.
- Apricots:Sun-dried or sulfured stone fruit from Turkish Malatya province, concentrated in UK and German snack mixes and Middle Eastern retail imports.
Almonds lead volumes today; cashews are gaining share fastest.
Form:
Processing intensity determines margin capture, with labor-saving cuts commanding premiums from industrial buyers facing wage inflation.
- Diced:Uniform 3-8mm cubes produced through mechanical dicing lines, eliminating manual prep for bakery and confectionery operations. Industrial buyers in France and Italy are consolidating procurement toward diced forms to reduce on-site labor costs and improve batch consistency in automated production lines.
- Sliced:Thin laminar cuts for topping applications in pastries and breakfast cereals, requiring specialized flaking equipment. German muesli manufacturers and Scandinavian crispbread producers specify sliced almonds for visual appeal and controlled toasting behavior, paying 15-25% premiums over whole kernel equivalents.
- Whole:Intact kernels for snacking and premium gift applications, with quality graded by size and defect rates.
- Chopped:Irregular fragments for inclusion in energy bars and granola, produced as byproduct of higher-grade processing.
Whole forms dominate commodity trade; sliced variants expand most quickly in premium channels.
End Use:
Application economics diverge sharply between price-sensitive bulk ingredient demand and branded consumer goods with formulation complexity.
- Snacking:Direct consumption in roasted, flavored, or raw formats through retail and foodservice channels. UK convenience retail and Swedish direct-to-consumer subscription services are fragmenting daypart occasions, with single-serve pouches displacing bulk purchases among urban professionals seeking portion control.
- Baking:Ingredient inclusion in bread, pastries, and cereal products requiring moisture stability and uniform particle size. German industrial bakeries and Italian biscotti manufacturers enforce strict aflatoxin and moisture specifications, rejecting lots that fail hyperspectral sorting thresholds at Rotterdam customs.
- Cooking:Culinary applications in savory dishes, trail mixes, and salad toppings across foodservice and home preparation.
- Confectionery:Inclusion in chocolate pralines, nougat, and marzipan requiring specific roast profiles and particle geometry for texture control.
Baking absorbs the largest ingredient volumes; snacking climbs the fastest as format innovation unlocks new consumption occasions.
Sales Channel:
Channel selection reflects buyer urgency, certification requirements, and tolerance for margin stacking through intermediaries.
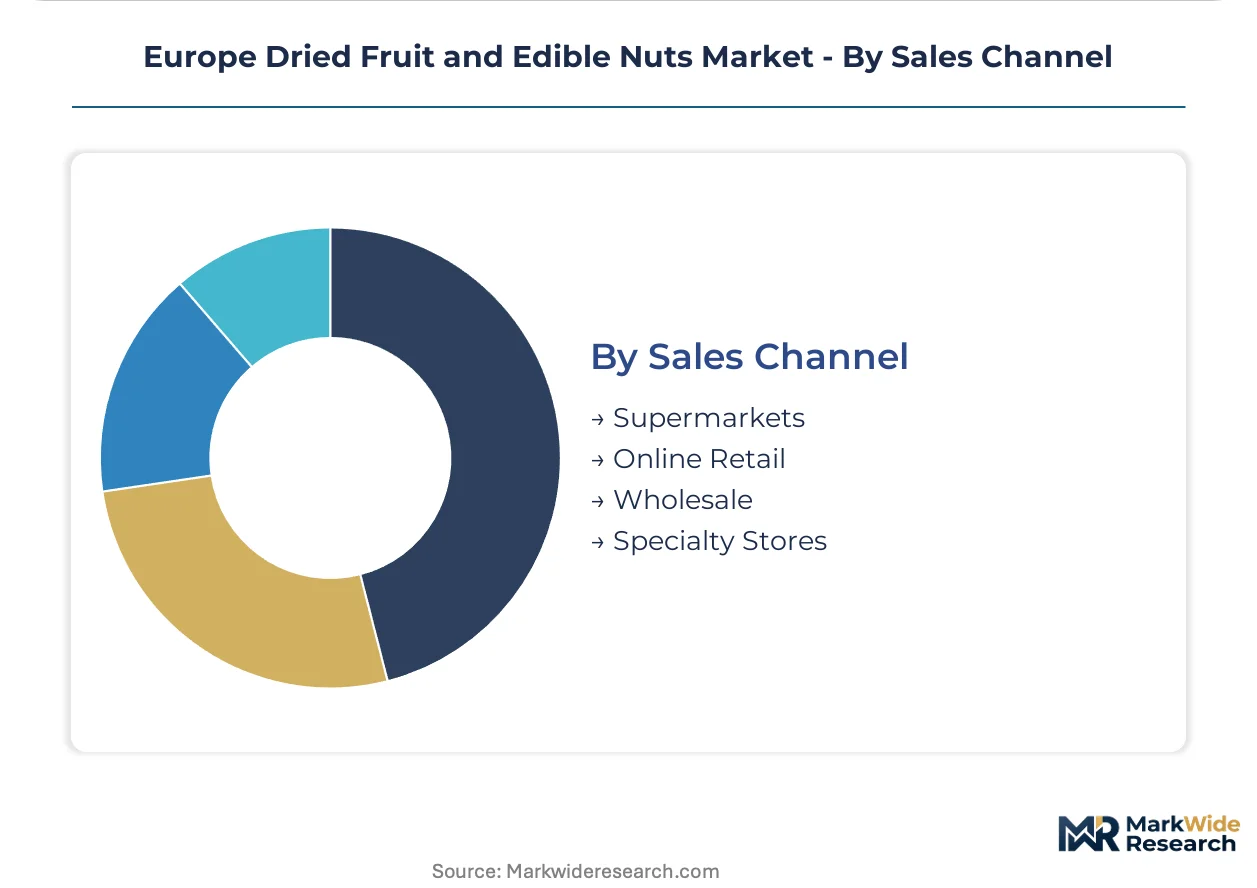
- Online Retail:Direct-to-consumer platforms and brand-owned e-commerce bypassing traditional wholesale structures. Danish and Swedish nut subscription services are scaling recurring revenue models with personalized flavor profiles, while Amazon and specialized health-food platforms expand assortment depth beyond physical retail capacity.
- Supermarkets:Mass-market retail including discounters, hypermarkets, and conventional grocers with private-label dominance. German Aldi and Lidl operations are widening shelf-space allocation for value-added nut SKUs, concentrating regional demand pull through centralized procurement at Rotterdam distribution hubs.
- Specialty Stores:Health-food retailers, organic shops, and gourmet delicatessens with curated assortments and educated staff.
- Wholesale:Foodservice distributors, industrial ingredient suppliers, and export traders handling bulk volumes with minimal processing.
Supermarkets transact the greatest tonnage; online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized roasting technicians cluster in Dutch and Belgian processing corridors, anchoring Europe's value-added nut transformation capacity while EFSA compliance expertise concentrates around Rotterdam and Hamburg customs hubs.
Germany
Private-label discounters Aldi and Lidl are widening shelf-space allocation for value-added nut SKUs, concentrating regional demand pull through centralized procurement at Rotterdam distribution hubs. REACH chemical screening protocols at Hamburg customs filter non-compliant import lots, protecting certified operators. Industrial dairy-alternative manufacturers in Bavaria and North Rhine-Westphalia anchor almond demand for oat-milk formulations.
Netherlands
Rotterdam serves as Europe's primary entry point for Californian almonds and West African cashews, with hyperspectral sorting facilities detecting aflatoxin contamination at line speeds exceeding manual capability. EFSA allergen labeling enforcement filters low-grade suppliers before goods reach German retail. Virgin Nuts B.V. leverages specialized roasting infrastructure to command shelf space in Dutch and Belgian specialty retail channels.
United Kingdom
Urban convenience retail in London fragments snacking occasions, with single-serve nut pouches displacing bulk-bin purchases among professionals seeking portion control. UK snack manufacturers enforce strict moisture specifications on Turkish apricot shipments. Middle Eastern retail imports concentrate dried apricot demand in Greater London and the Midlands.
Sweden
Direct-to-consumer nut subscription services scale recurring revenue models with personalized flavor profiles, bypassing traditional retail margin stacking. Swedish consumers adopt portion-controlled formats faster than continental peers. Nordic oat-milk producers pull West African cashew origination into direct supply relationships.
Belgium
Belgian chocolate houses demand specific roast profiles and particle geometry for praline texture control, sourcing through Antwerp processing facilities. ECHA expanding pesticide residue testing lengthens customs clearance times for non-compliant shipments. Industrial roasters adopt optical sorting systems to compress unit economics against manual quality-control labor pools.
Europe Dried Fruit and Edible Nuts Market Key Industry Players
Top-tier vendors anchor integrated origination and processing operations, while mid-scale traders compete on spot-market flexibility and regional distribution reach. The vendor base stratifies between agricultural conglomerates with backward integration into Turkish and Californian orchards, specialized roasters commanding premium shelf space in Benelux specialty retail, and digital-native direct-to-consumer platforms scaling subscription models. Dominant competitive moves include M&A targeting traceability infrastructure and capacity expansion in automated roasting and flavoring lines.
Within the integrated agricultural tier, Archer-Daniels-Midland Company and Olam International Limited exemplify operators with pre-existing traceability platforms and origination control. Virgin Nuts B.V. occupies a specialized position among Benelux-based roasters leveraging technical flavor-development expertise. These three entities represent contrasting archetypes: conglomerate-scale supply chain integration, mid-cap processing specialization, and hybrid digital-physical distribution models.
| Leading Market Players |
|---|
| Ocean Spray Cranberries Inc. |
| Virgin Nuts B.V. |
| Archer-Daniels-Midland Company |
| Kiantama Ltd. |
| HBS Foods Ltd. |
| Olam International Limited |
| Fresh Nuts GmbH |
| Murray River Organics |
| Arimex Uab |
| Others |
Cost & Logistics Intelligence
Organic-commodity bifurcation splits procurement economics across the Europe Dried Fruit and Edible Nuts Market, with certified deforestation-free lots commanding 20-35% premiums at Rotterdam while bulk Turkish apricot shipments trade on spot moisture specifications. REACH compliance costs and EFSA screening delays feed directly into landed cost structures, forcing traders to choose between margin compression or supplier base consolidation.
Pricing Analysis
Subscription bundling against spot commodity purchasing divides buyer archetypes. Three-tier pricing structure across premium organic, standard conventional, and economy bulk levels tracks certification grade and traceability documentation depth. Pricing pressure stems from Californian water restrictions elevating almond origination costs. Industrial dairy-alternative manufacturers show lowest price sensitivity due to long-term contract structures, while German discounter private-label buyers negotiate aggressively on volume.
Supply Chain Analysis
Dual-sourcing mandates from major confectionery clients require parallel qualification of West African and Southeast Asian cashew processors. Geographic supply concentrates in Turkey for apricots, California for almonds, and Côte d'Ivoire for cashews. Raw material dependencies include irrigation water access, sulfur treatment chemicals, and steam-shelling equipment. Single-origin vulnerability in Malatya apricot production creates climatic shock exposure. Distribution runs through Rotterdam bulk terminals into German centralized procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Dried Fruit and Edible Nuts Market operates as a regulatory compounder where EU Green Deal due diligence deadlines are accelerating compliance infrastructure investment across the supplier base.
For Market Incumbents: To counter spot-market intermediary disintermediation, deepen backward integration into Turkish almond orchards and deploy blockchain-IoT traceability platforms that satisfy ECHA documentation requirements. Prioritize automated roasting capacity expansion in Dutch processing corridors where technician scarcity constrains competitor scale-up. For New Entrants and Emerging Players: Digital-native subscription platforms offer the most penetrable wedge, with Swedish and Danish direct-to-consumer models bypassing retail margin stacking entirely. Target Nordic oat-milk producers seeking direct West African cashew relationships. Launch with personalized flavor-profile algorithms and humidity-guarantee logistics. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized traders face legacy ERP integration burdens against digital traceability mandates. Five-to-ten-year viability favors operators with pre-existing EFSA compliance expertise and Rotterdam customs relationships. Monitor ECHA chemical contaminant list expansion as inflection signal for procurement contract renegotiation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination | Captive Turkish and Californian orchard supply secures deforestation-free certification compliance for EU Green Deal. |
| Blockchain-IoT Traceability Deployment | Distributed ledger systems with humidity sensors enable premium pricing for provably stable moisture-content guarantees. |
| Automated Roasting Capacity Expansion | Optical sorting technology compresses unit economics against aging manual quality-control labor pools in Benelux. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models in Nordic markets bypass traditional retail margin stacking and fragment daypart consumption. |
| EFSA Compliance Laboratory Investment | In-house contaminant screening accelerates Rotterdam customs clearance and reduces rejection rates for West African shipments. |
Research Approach
Multiple input streams — primary interviews with roasting facility managers, EFSA regulatory consultants, and German discounter procurement directors; secondary validation through customs trade databases, EU regulatory filings, and agricultural commodity exchange records; plus industry association statistics from European Snacks Association — were reconciled through bottom-up volume modeling and top-down value triangulation.
Cross-referencing historical shipment patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, processed form, end-use application, and sales channel, with regional regulatory cluster effects layered across country-level demand. CAGRs were derived from trend extrapolation adjusted for EU Green Deal implementation pacing and water stress impacts on Californian origination.
The model holds under stable EFSA enforcement intensity and REACH chemical list expansion; deviation in EU Green Deal due diligence deadline acceleration or Turkish lira volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Packaged Sunflower Seeds Market
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
Pecans Market
Nuts and Seeds
Macadamia Nut Market
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Asia-Pacific Hazelnut Market
Nuts and Seeds
Horse Chestnut Seed Extract Market