
 Germany Cashew Market | 2026-2036
Germany Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Cashew Market Foresight
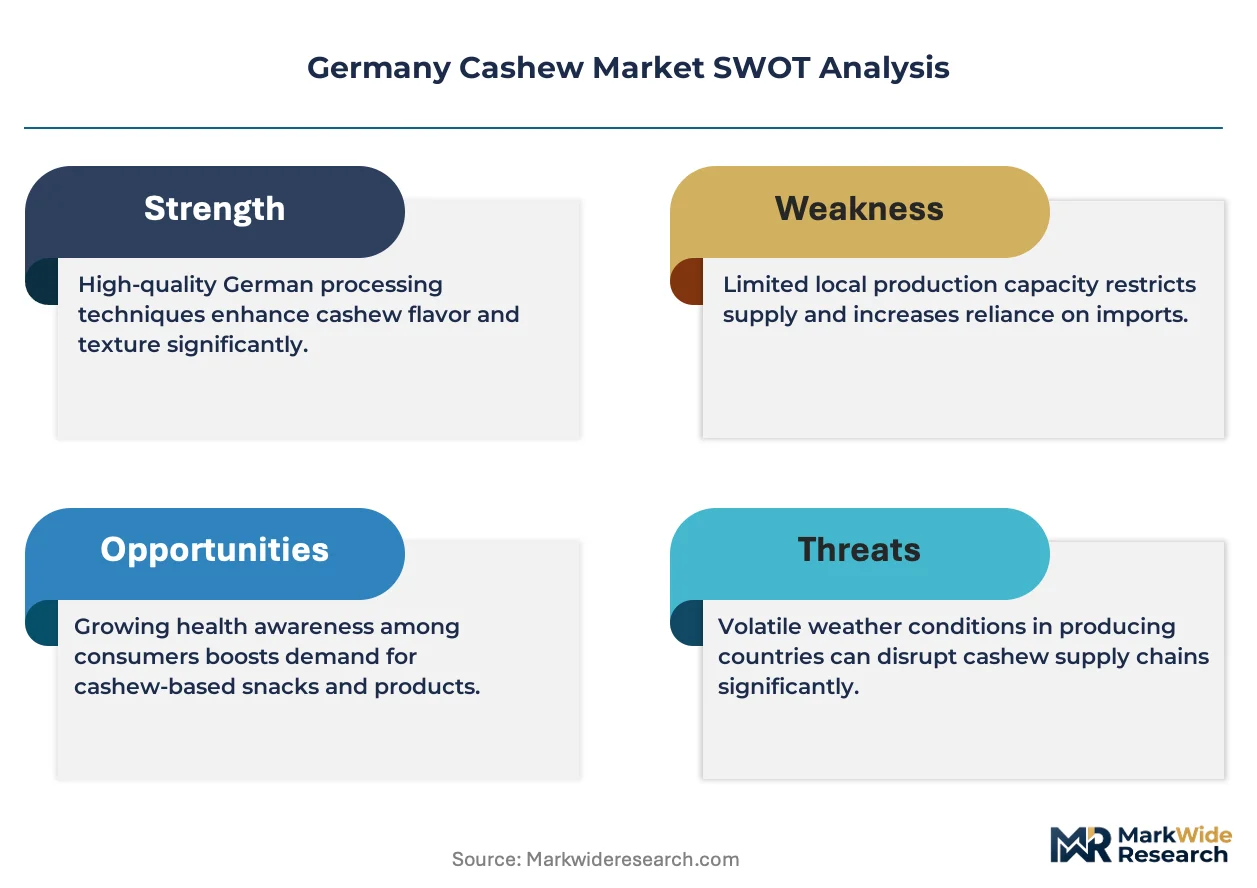
Premium raw cashew pricing is decoupling from commodity roasted grades as German buyers enforce stricter origin and processing specifications. CashewPoint Europe UG leverages direct African sourcing relationships to sustain consistent supply quality for industrial clients. Global Nuts & Dried Fruits GmbH anchors its position through extensive cold-chain distribution across Central European food manufacturers. Bruckmann GmbH differentiates via specialized organic and fair-trade certifications that command shelf-space premiums in German retail.
Cashews are kidney-shaped seeds of Anacardium occidentale, typically containing 47% fat and 18% protein by weight, with kernels processed through steaming, shelling, drying, and peeling stages before food-grade packaging. The kernels serve as functional ingredients in confectionery, dairy alternatives, and clean-label snack formulations due to their creamy texture and neutral flavor profile. Roasted cashews occupy the largest volume share among product types, while cashew milk experiences accelerated growth within dairy-alternative applications. Food manufacturers represent the most concentrated end-user segment, though health and wellness brands capture expanding margin pools through branded superfood positioning.
German cashew imports fall under EFSA food safety standards, EU Deforestation Regulation traceability mandates, and REACH-compliant packaging requirements that collectively elevate compliance costs for smaller traders. The KBA enforces transport emission regulations affecting cold-chain logistics from Hamburg and Bremen ports to inland processing facilities. Organic certification under EU regulation 2018/848 further segments market access for suppliers without accredited supply chains. Stakeholders must monitor evolving due diligence obligations and port-of-entry inspection intensification to preserve market participation.
Market Dynamics
The EU Deforestation Regulation is forcing German cashew distributors to rebuild traceability infrastructure from port to retail shelf, elevating compliance costs while simultaneously creating procurement advantages for verified suppliers.
Growth Catalysts
- Clean-label confectionery demand:Bavarian chocolate manufacturers are expanding cashew inclusions as dairy-free alternatives gain shelf space in REWE and Edeka premium lines.
- EU Organic Regulation 2018/848:Certified organic cashews command price premiums in Hamburg and Berlin metropolitan retail clusters, pulling supply chain investment toward accredited African cooperatives.
- Steam pasteurization adoption:Food safety upgrades at Bremen processing facilities are reducing microbial contamination risks, enabling expanded foodservice distribution to institutional buyers.
Market Restraints
- West African supply concentration:Overreliance on Côte d'Ivoire and Ghana raw nut shipments exposes German importers to weather-driven crop volatility and port congestion.
- REACH packaging compliance:Secondary packaging material certification adds EUR 0.08-0.12 per kilogram for smaller traders lacking economies of scale in testing.
- Pistachio and almond substitution:California almond processors are aggressively pricing into German snack mixes, compressing cashew volume share in economy-tier products.
Strategic Opportunities
- North Rhine-Westphalia food manufacturing corridor:Industrial bakery and muesli producers in Cologne-Düsseldorf axis represent underpenetrated bulk contract opportunities.
- Cashew milk formulation expansion:Oatly and Alpro competitors are testing cashew bases for creamier mouthfeel in barista-grade alternatives.
- KBA emission standard alignment:Cold-chain logistics providers investing in Euro VI-compliant fleets gain preferential access to Munich and Stuttgart organic retail distribution.
Industry Challenges
- EU Deforestation Regulation due diligence documentation:Small and mid-sized importers face 12-18 month certification timelines to satisfy Hamburg port-of-entry inspection protocols.
- Traceability technology integration:Blockchain and satellite mapping systems require capital outlays that strain distributors with sub-500-tonne annual throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Cashew Market |
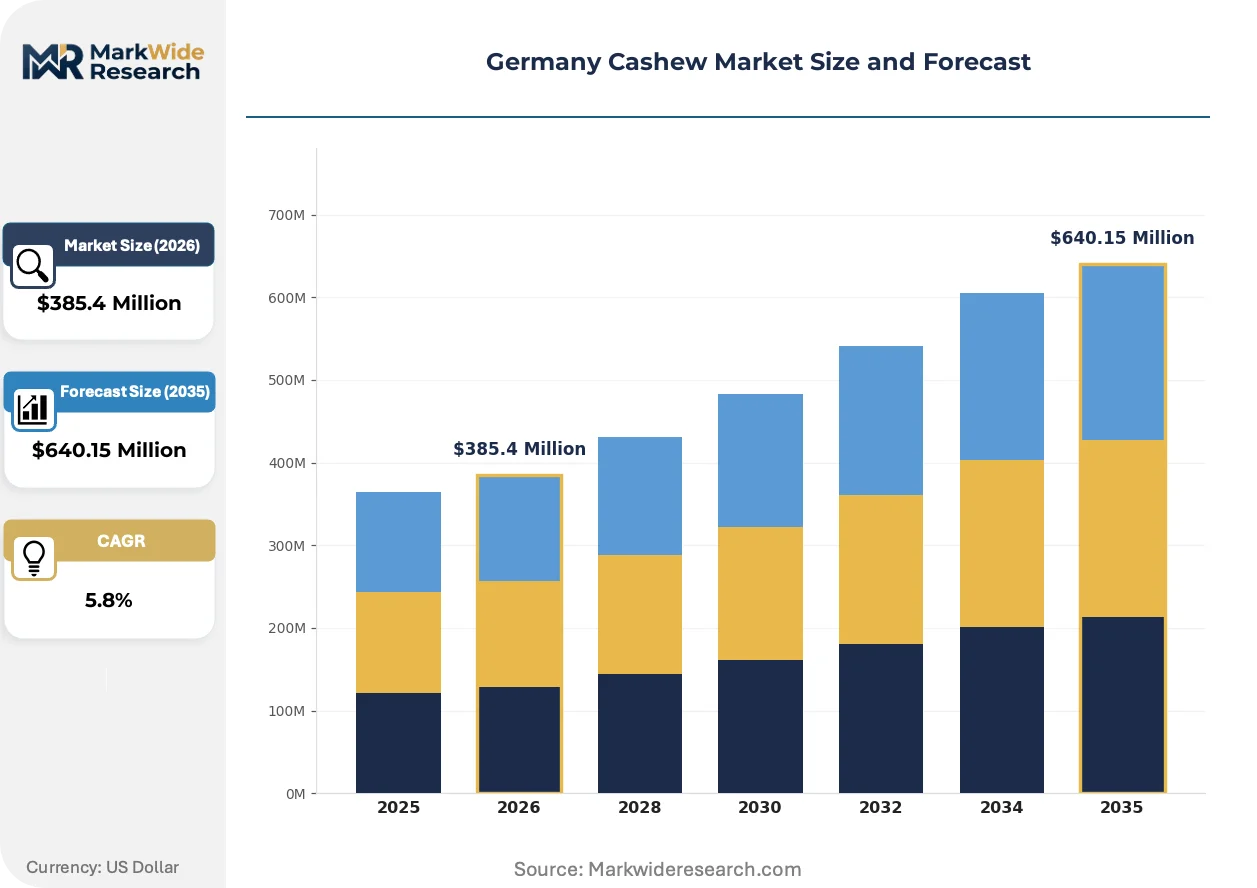
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cashews, Roasted Cashews, Salted Cashews, Cashew Butter, Cashew Milk Application: Snacks, Bakery Products, Dairy Alternatives, Confectionery, Culinary Ingredients End User: Food Manufacturers, Foodservice Providers, Retail Consumers, Health & Wellness Brands, Nutraceutical Companies Distribution Channel: Supermarkets & Hypermarkets, Specialty Stores, Online Retailers, Wholesale Suppliers, Health Food Stores |
| Companies Covered | CashewPoint Europe UG, Global Nuts & Dried Fruits GmbH, Bruckmann GmbH, Nordic Exim GmbH, BioNuts Naturprodukte GmbH, DEBANG EXPORT & IMPORT GMBH, AgroHaus GmbH, PureTropics GmbH, NutriTrade Handels GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Cashew Market Shifts & Advancements
Processing technology and regulatory traceability requirements are converging to reshape how German buyers evaluate supplier relationships beyond price and basic quality metrics.
Steam-based pasteurization equipment with integrated optical sorting is modularizing quality control workflows at Bremen and Hamburg processing facilities. Mid-sized distributors serving North Rhine-Westphalia snack manufacturers are adopting these systems to reduce labor-intensive hand-sorting. The technology is compressing batch processing timelines from 72 hours to sub-24-hour turnaround for food-grade kernel certification.
EFSA food safety standards are tightening aflatoxin testing protocols for tree nut imports entering EU territory. German customs authorities at Hamburg port are implementing enhanced sampling regimes that delay clearance for non-pre-certified shipments. Organic-certified suppliers with documented supply chain controls are securing expedited inspection lanes, creating tiered market access based on compliance investment.
Buyer concentration among REWE Group, EDEKA Zentrale, and Aldi Süd is compressing supplier negotiation leverage for standard-grade roasted cashews. These retail procurement teams are unbundling quality specifications from logistics contracts, forcing traders to compete on traceability documentation and carbon footprint disclosure separately from kernel pricing. The shift is most visible in Munich metropolitan cluster negotiations, where sustainability scoring now precedes price discussions in annual tender rounds.
Germany Cashew Market Segmentation
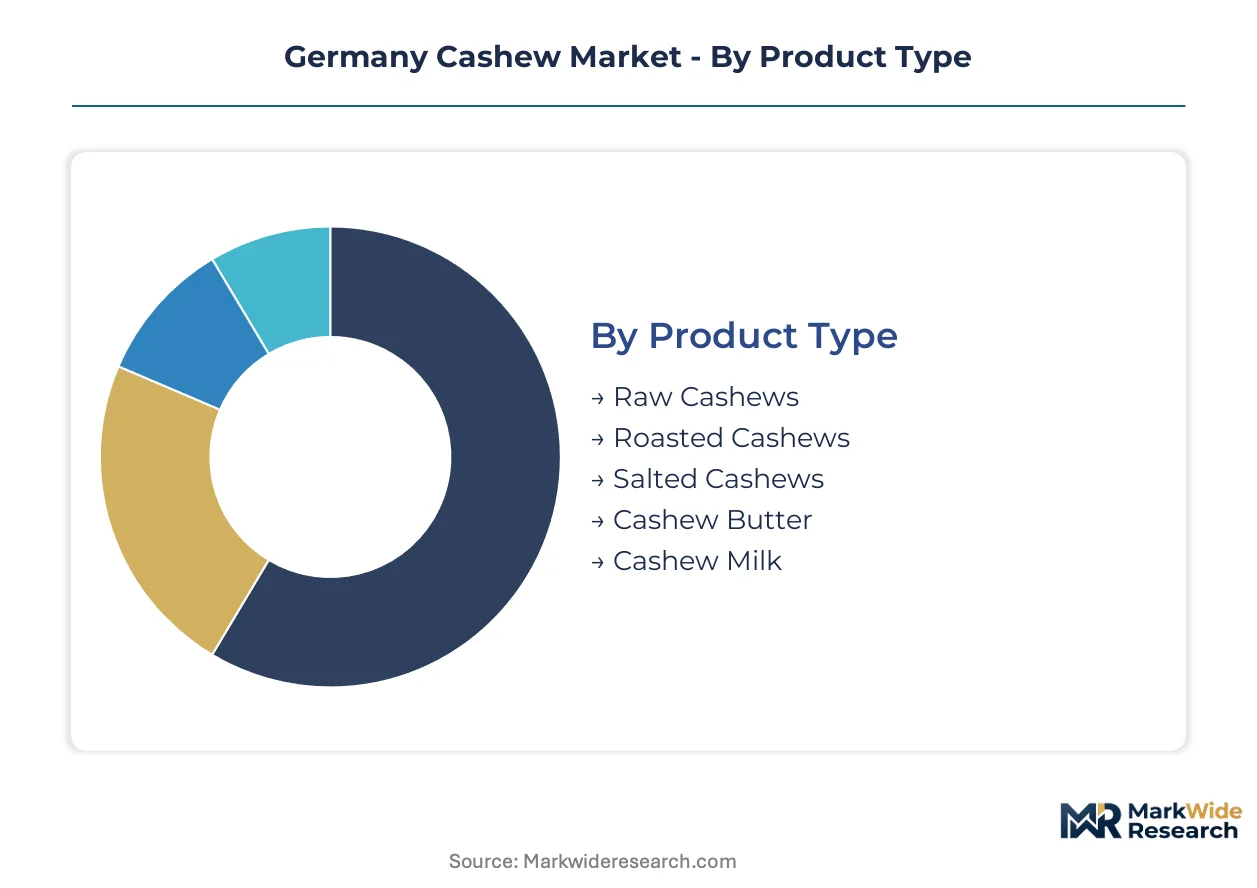
German cashew procurement patterns diverge sharply across product formats and buyer categories. EFSA compliance requirements and EU Deforestation Regulation traceability mandates reshape how segments absorb capital investment and command price premiums.
Product Type:
Capital intensity escalates steeply from commodity roasting lines to aseptic cashew milk processing infrastructure. Steam pasteurization equipment and integrated optical sorting systems represent the largest fixed-asset commitments for German distributors.
- Raw Cashews:Unroasted kernels retain higher oil stability and serve as inputs for industrial food manufacturers requiring custom flavor profiles. Bavarian chocolate processors and North Rhine-Westphalia muesli producers dominate procurement volumes, though EFSA aflatoxin testing protocols at Hamburg port extend clearance timelines for non-pre-certified shipments.
- Cashew Milk:Aseptic filling lines and homogenization equipment demand EUR 2-4 million in upfront processing infrastructure. Oatly and Alpro competitors in Berlin and Munich metropolitan clusters are testing cashew bases for creamier mouthfeel in barista-grade alternatives, pulling supply investment toward dairy-alternative formulation capabilities.
- Roasted Cashews:Oil-roasting and dry-roasting systems require moderate capital outlay for mid-scale German processors serving REWE and Edeka private label programs.
- Salted Cashews:Seasoning tumblers and packaging lines represent lower barrier-to-entry equipment for regional snack distributors.
- Cashew Butter:Grinding and stabilizing machinery targets niche organic retail channels in Hamburg and Stuttgart with clean-label spread positioning.
Roasted cashews absorb the bulk of installed capacity; cashew milk is expanding most quickly.
Application:
Volume concentration and margin capture split unevenly across application categories, with snack manufacturing commanding throughput scale while dairy alternatives extract premium pricing.
- Snacks:Trail mixes and standalone nut packs drive the largest tonnage flows through German distribution networks. REWE Group and Aldi Süd procurement teams unbundle quality specifications from logistics contracts, forcing traceability documentation and carbon footprint disclosure ahead of kernel pricing in annual tender rounds.
- Dairy Alternatives:Cashew bases deliver superior emulsion stability and neutral flavor compared to oat or soy alternatives. Health food stores across Munich and Berlin metropolitan clusters stock refrigerated barista-grade formulations, with EDEKA Zentrale testing shelf-stable variants for premium private label expansion.
- Bakery Products:Muesli and granola producers in Cologne-Düsseldorf axis source bulk roasted splits for cost-controlled inclusion rates.
- Confectionery:Bavarian chocolate manufacturers integrate cashew praline fillings as dairy-free alternatives gain shelf space.
- Culinary Ingredients:Foodservice distributors supply institutional kitchens with pasteurized kernels for sauce and curry applications.
Snacks dominate current throughput volumes; dairy alternatives are climbing the fastest.
End User:
Buyer sophistication and compliance readiness stratify sharply between industrial manufacturers with dedicated quality teams and fragmented retail channels.
- Food Manufacturers:Industrial bakery and confectionery producers in North Rhine-Westphalia enforce strict origin and processing specifications that decouple premium raw cashew pricing from commodity roasted grades. Direct African sourcing relationships through CashewPoint Europe UG sustain consistent supply quality for clients with documented supply chain controls.
- Health & Wellness Brands:Branded superfood positioning captures expanding margin pools through certified organic and fair-trade claims. Bruckmann GmbH leverages specialized certifications to command shelf-space premiums in Hamburg, Berlin, and Munich organic retail clusters.
- Foodservice Providers:Institutional cafeterias and restaurant chains require steam-pasteurized kernels with reduced microbial contamination risks.
- Retail Consumers:Discerning buyers in metropolitan clusters prioritize EU Organic Regulation 2018/848 certification and deforestation-free sourcing claims.
- Nutraceutical Companies:Functional ingredient extraction for protein isolates and oil concentrates targets specialized pharmaceutical-adjacent applications.
Food manufacturers concentrate the largest procurement volumes; health and wellness brands are gaining share fastest.
Distribution Channel:
Cold-chain infrastructure requirements and traceability documentation burdens reshape channel economics for German cashew distributors.
- Supermarkets & Hypermarkets:REWE Group, EDEKA Zentrale, and Aldi Süd concentration compresses supplier negotiation leverage for standard-grade roasted cashews. Sustainability scoring now precedes price discussions in annual tender rounds, with KBA emission standard alignment favoring Euro VI-compliant logistics providers.
- Online Retailers:Direct-to-consumer platforms bypass traditional wholesale markups while requiring sophisticated inventory management for temperature-sensitive organic stock. Global Nuts & Dried Fruits GmbH anchors its position through extensive cold-chain distribution across Central European food manufacturers.
- Specialty Stores:Independent organic retailers in Stuttgart and Munich metropolitan clusters stock premium fair-trade and single-origin SKUs with higher per-kilogram margins.
- Wholesale Suppliers:Bulk distributors serving food manufacturers face REACH packaging compliance costs adding EUR 0.08-0.12 per kilogram for smaller traders lacking economies of scale in testing.
- Health Food Stores:Certified organic cashews command price premiums in Hamburg and Berlin clusters, pulling supply chain investment toward accredited African cooperatives.
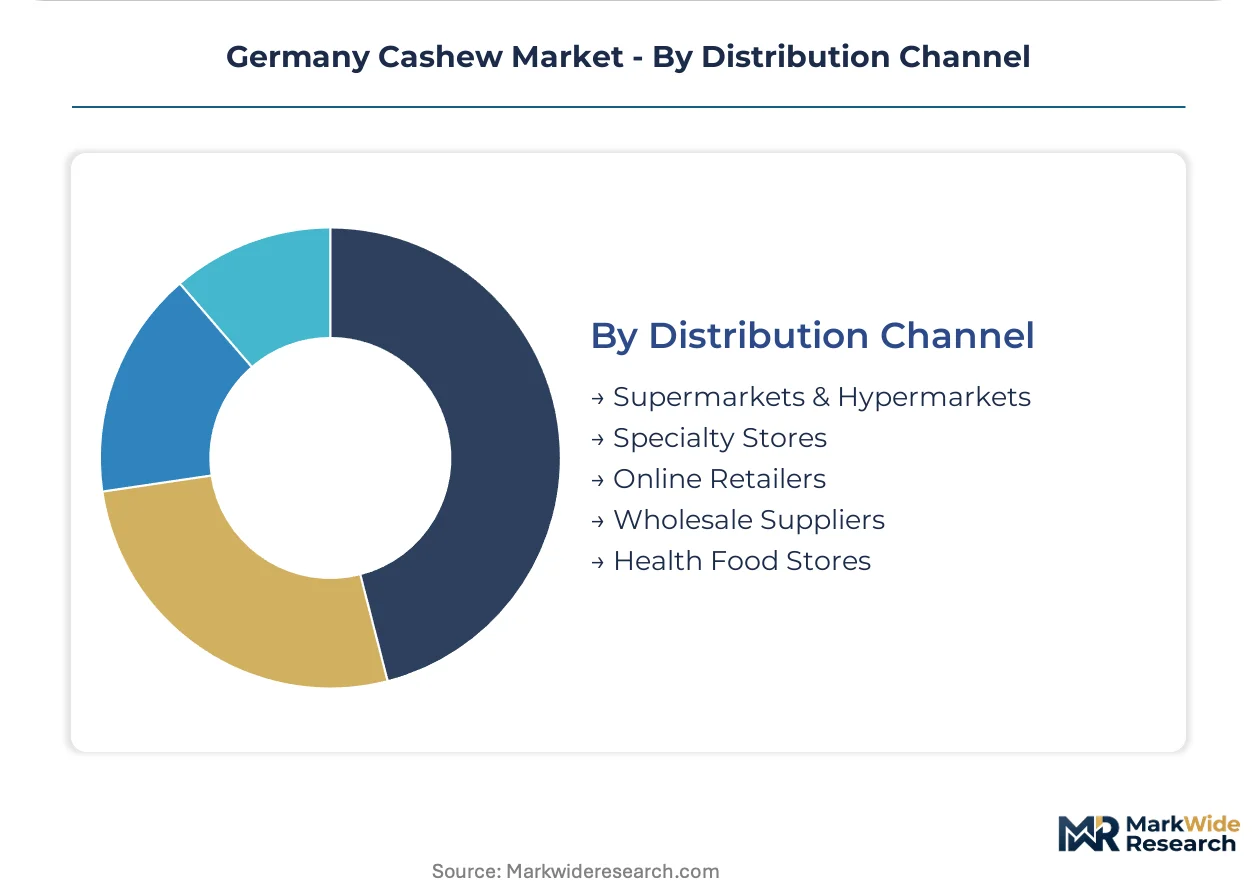
Supermarkets and hypermarkets absorb the bulk of throughput volume; online retailers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg's port infrastructure and Bremen's processing facilities anchor German cashew import and distribution activity, with metropolitan retail clusters in Berlin and Munich driving premium organic demand through specialized procurement channels.
Bavaria
Chocolate manufacturers in the Munich metropolitan cluster are expanding cashew inclusions for dairy-free praline formulations. EFSA food safety standards enforce strict aflatoxin testing protocols for all tree nut shipments entering Bavarian processing facilities. Industrial confectionery corridors around Nuremberg and Augsburg concentrate demand for premium raw kernels with documented origin specifications.
North Rhine-Westphalia
Muesli and granola producers along the Cologne-Düsseldorf axis source bulk roasted cashew splits for cost-controlled inclusion rates. The KBA enforces Euro VI emission standards on cold-chain logistics serving industrial bakery clusters. Food manufacturing corridors in Dortmund and Essen represent underpenetrated contract opportunities for verified suppliers with traceability documentation.
Baden-Württemberg
Stuttgart's organic retail channels command shelf-space premiums for fair-trade certified cashew butter and specialty spreads. EU Organic Regulation 2018/848 certification requirements segment market access for distributors without accredited supply chains. Health food store concentration in Freiburg and Karlsruhe metropolitan areas pulls procurement toward single-origin and cooperative-sourced SKUs.
Hamburg
Port-of-entry inspection intensification at Hamburg customs creates tiered clearance timelines based on pre-certification status. REACH-compliant packaging requirements elevate compliance costs for secondary materials entering German distribution. Cold-chain logistics providers with documented carbon footprint disclosure gain preferential access to metropolitan retail distribution networks.
Berlin
Dairy-alternative formulation labs in the Berlin-Brandenburg corridor are testing cashew milk bases for barista-grade creaminess. EDEKA Zentrale and REWE Group procurement teams unbundle sustainability scoring from price negotiations in annual tender rounds. Specialty coffee shops and independent grocers across Kreuzberg and Prenzlauer Berg drive demand for certified organic and deforestation-free positioning.
Germany Cashew Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and traceability dimensions, with organic and fair-trade credentials commanding measurable shelf-space advantages in metropolitan retail clusters. The vendor base stratifies into three tiers: direct African sourcers with documented cooperative relationships, cold-chain distributors with Central European coverage, and specialized organic certifiers with regional retail penetration. Consolidation pressure concentrates among mid-scale traders lacking economies of scale in EFSA pre-certification and REACH packaging compliance testing. Dominant competitive moves include backward integration into African cooperative sourcing and technology licensing for blockchain traceability documentation.
Within the direct-sourcing archetype, CashewPoint Europe UG represents players leveraging African origin relationships to sustain consistent supply quality for industrial clients. Among cold-chain specialists, Global Nuts & Dried Fruits GmbH occupies a position anchored through extensive distribution infrastructure across Central European food manufacturers. On the certification-specialist tier, Bruckmann GmbH exemplifies differentiation via organic and fair-trade credentials that command measurable premiums in Hamburg, Berlin, and Munich retail clusters.
| Leading Market Players |
|---|
| CashewPoint Europe UG |
| Global Nuts & Dried Fruits GmbH |
| Bruckmann GmbH |
| Nordic Exim GmbH |
| BioNuts Naturprodukte GmbH |
| DEBANG EXPORT & IMPORT GMBH |
| AgroHaus GmbH |
| PureTropics GmbH |
| NutriTrade Handels GmbH |
| Others |
Supply & Pricing Matrix
Raw cashew nut price indices in West Africa cascade through Hamburg port clearance tiers into German distribution, with EU Deforestation Regulation pre-certification status separating expedited inspection lanes from delayed commodity lots. This structural bifurcation concentrates pricing power among verified suppliers while compressing margins for traders lacking documented cooperative relationships.
Pricing Analysis
Yield-based pricing for food-grade kernel certification anchors German procurement contracts, with EFSA aflatoxin compliance tiers separating premium raw grades from commodity roasted volumes. Certification under EU Organic Regulation 2018/848 and fair-trade credentials command measurable shelf-space premiums in Hamburg and Berlin retail clusters. Cost compression in standard-grade roasted segments is intensifying because California almond processors are aggressively pricing into snack mix formulations. Industrial food manufacturers in North Rhine-Westphalia exhibit highest price sensitivity due to bulk contract volumes, while health and wellness brands in Munich metropolitan clusters show least sensitivity given superfood positioning margins.
Supply Chain Analysis
Cold-chain logistics costs from Hamburg and Bremen ports to inland processing facilities are escalating under KBA Euro VI emission standards, favoring fleet operators with compliant vehicles. Raw nut supply concentrates in Côte d'Ivoire, Ghana, and Nigeria, with kernel processing dependent on steaming equipment, optical sorting systems, and aflatoxin testing protocols. Single-source vulnerability runs through West African port congestion and weather-driven crop volatility. Distribution feeds from Bremen processing hubs through wholesale suppliers serving industrial bakery corridors and direct retail channels in metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German cashew procurement operates as a supply-constrained market where EU Deforestation Regulation certification timelines create a 12-18 month capacity bottleneck, propping pricing premiums for verified suppliers against commodity-grade compression.
For Market Incumbents: Anchor market position through backward integration into accredited African cooperatives with documented traceability infrastructure, insulating against EFSA inspection lane delays at Hamburg port. Prioritize certification investment under EU Organic Regulation 2018/848 to defend margin position against almond substitution in economy-tier snack mixes. Channel control through exclusive cold-chain partnerships with Euro VI-compliant logistics providers secures preferential access to Munich and Stuttgart organic retail distribution. For New Entrants and Emerging Players: EU Deforestation Regulation in Germany opens a window for blockchain-traceability specialists to capture mid-scale importer demand lacking capital for in-house satellite mapping systems. The North Rhine-Westphalia industrial bakery corridor represents the most penetrable geography, with Cologne-Düsseldorf axis muesli producers seeking verified suppliers for bulk roasted splits. A go-to-market angle targeting steam-pasteurization equipment leasing alongside kernel supply reduces upfront capital barriers for foodservice distributors. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale traders with established African cooperative relationships but sub-500-tonne annual throughput struggling with REACH packaging compliance costs. Long-term viability over the projection horizon rests on consolidation plays that aggregate traceability infrastructure across fragmented regional distributors. The signal to watch is Hamburg port inspection lane allocation shifts favoring pre-certified organic shipments, indicating tiered market access crystallization.| Strategic Initiative | Industry Significance |
|---|---|
| African Cooperative Backward Integration | Direct sourcing from Côte d'Ivoire and Ghana cooperatives secures EFSA pre-certification status for Hamburg port expedited clearance. |
| Blockchain Traceability Licensing | Satellite mapping and chain-of-custody documentation satisfies EU Deforestation Regulation due diligence for mid-scale importers. |
| Steam Pasteurization Equipment Deployment | Bremen facility upgrades reduce batch processing timelines from 72 hours to sub-24-hour turnaround for food-grade certification. |
| Euro VI Fleet Cold-Chain Partnership | KBA emission standard alignment gains preferential distribution access to Munich and Stuttgart organic retail clusters. |
| Organic Certification Program Expansion | EU Regulation 2018/848 accreditation commands shelf-space premiums in Hamburg, Berlin, and Munich metropolitan retail channels. |
Research Methodology
Document review covered EU trade statistics, EFSA food safety protocols, and REACH compliance guidelines, complemented by interviews with German cashew importers, African cooperative export managers, and Bremen processing facility operators. Secondary validation drew from customs clearance records at Hamburg port, KBA emission standard filings, and organic certification databases under EU Regulation 2018/848. Bottom-up volume estimates from individual processor throughput were triangulated against top-down import value flows across the analysis window.
Cross-referencing historical price index movements with panel input from procurement directors at REWE Group, EDEKA Zentrale, and Aldi Süd shaped the analytical framework. Segmentation dimensions modeled include product type, application category, end-user archetype, and distribution channel complexity. CAGRs were derived from regression analysis of import volume trajectories and premium-grade pricing spreads. Forecast inputs incorporated EU Deforestation Regulation implementation timelines and steam pasteurization technology adoption curves.
The model assumes a particular technology adoption path for blockchain traceability documentation; alternative pathways for satellite-verified cooperative sourcing would alter the compliance cost outlook. Forecasts reflect assumptions regarding EFSA inspection intensification and KBA emission standard enforcement continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Almond Kernels Market
Nuts and Seeds
Europe Hazelnut Market
Nuts and Seeds
Soy Nut Market
Nuts and Seeds
Pecans Market
Nuts and Seeds
Blackcurrant Seed Oil Market
Nuts and Seeds
Bambara Beans Market
Nuts and Seeds
Almond Oil Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Maca Market
Nuts and Seeds
Apricot Kernel Market
Nuts and Seeds
Asia-Pacific Grape Seed Extract Market
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
Butyrospermum Parkii Market
Nuts and Seeds
Low Fat Nut Butter Market
Nuts and Seeds
Peanuts Market