
 Walnut Oil Market | 2026-2036
Walnut Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Walnut Oil Market Outlook
Specialty food retail channels is narrowing as direct-to-consumer platforms and boutique grocers capture premium walnut oil volumes previously held by mass-market supermarkets. Olitalia S.p.A. leverages its Italian distribution network to dominate European food-service supply. Gustav Heess GmbH anchors German retail shelves with cold-pressed variants. La Tourangelle, Inc. competes in North American specialty channels through artisanal positioning and regional mill partnerships.
Walnut oil is a fixed oil expressed from Juglans regia kernels, containing roughly 60-70% linoleic acid and 10-15% oleic acid by weight, with a smoke point near 160°C that restricts its culinary role to low-heat finishing and cold preparations. Unrefined walnut oil commands the highest margin pool among product type segments due to minimal processing and strong flavor retention prized by chefs. Cosmetic applications represent the fastest-growing application segment as formulators substitute walnut oil for mineral bases in skin and hair products. Glass bottle packaging dominates premium positioning despite higher logistics costs, while bulk containers sustain food manufacturer procurement efficiency.
Food manufacturers across the European Union navigate REACH compliance for cosmetic-grade walnut oil exports and EFSA novel food assessments for nutraceutical positioning. The USDA organic certification shapes North American market access for cold-pressed and organic variants, with FDA food facility registration required for all US-bound shipments. Stakeholders must monitor tightening contaminant thresholds for polycyclic aromatic hydrocarbons in unrefined oils and assess whether in-house pressing capacity or third-party toll processing better protects margin structures.
Market Dynamics
Cold-press extraction technology upgrades are compressing thermal degradation losses while tightening polycyclic aromatic hydrocarbon thresholds in unrefined grades force processors to rebuild filtration infrastructure.
Growth Catalysts
- REACH compliance for cosmetic-grade exports:European Union regulatory alignment opens premium pricing tiers for walnut oil meeting ECHA contaminant standards. Formulators in France and Germany prioritize compliant stock for skin and hair applications.
- Gourmet restaurant procurement:Finishing oil demand from high-end culinary establishments drives volume for cold-pressed variants with strong flavor retention. Chefs specify origin-verified stock for tableside presentation.
- Direct-to-consumer platforms:Boutique grocers and specialty e-commerce channels capture premium volumes previously flowing through mass-market supermarkets, shortening distribution layers.
Market Restraints
- Walnut kernel input volatility:Orchard yield fluctuations in France and California concentrate supply risk among a handful of growing regions. Processors face margin compression when harvests underperform.
- Smoke point limitation:The 160°C thermal ceiling restricts walnut oil to cold preparations and low-heat finishing, excluding frying applications that drive volume in commodity edible oils.
- Glass bottle logistics cost:Premium positioning requires fragile packaging that elevates freight expense and breakage rates versus bulk container alternatives favored by food manufacturers.
Strategic Opportunities
- USDA organic certification tailwind:North American market access for certified organic cold-pressed variants commands shelf-space premiums in natural food channels. FDA food facility registration requirements create compliance moats for established suppliers.
- Nutraceutical positioning:EFSA novel food assessment pathways enable omega-3 and antioxidant health claims that expand addressable demand beyond culinary uses.
- Cosmetic mineral oil substitution:Formulators in France and Germany are replacing petroleum-derived bases with walnut oil in skin and hair products, opening formulation partnerships with personal care manufacturers.
Industry Challenges
- In-house pressing versus toll processing:Capital allocation decisions between captive extraction capacity and third-party processing create operational complexity. Margin protection depends on volume predictability that remains elusive for mid-scale processors.
- EFSA novel food timeline:Regulatory approval cycles for health claim positioning extend commercialization timelines. Applicants face documentation burdens that strain smaller producers without dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walnut Oil Market |
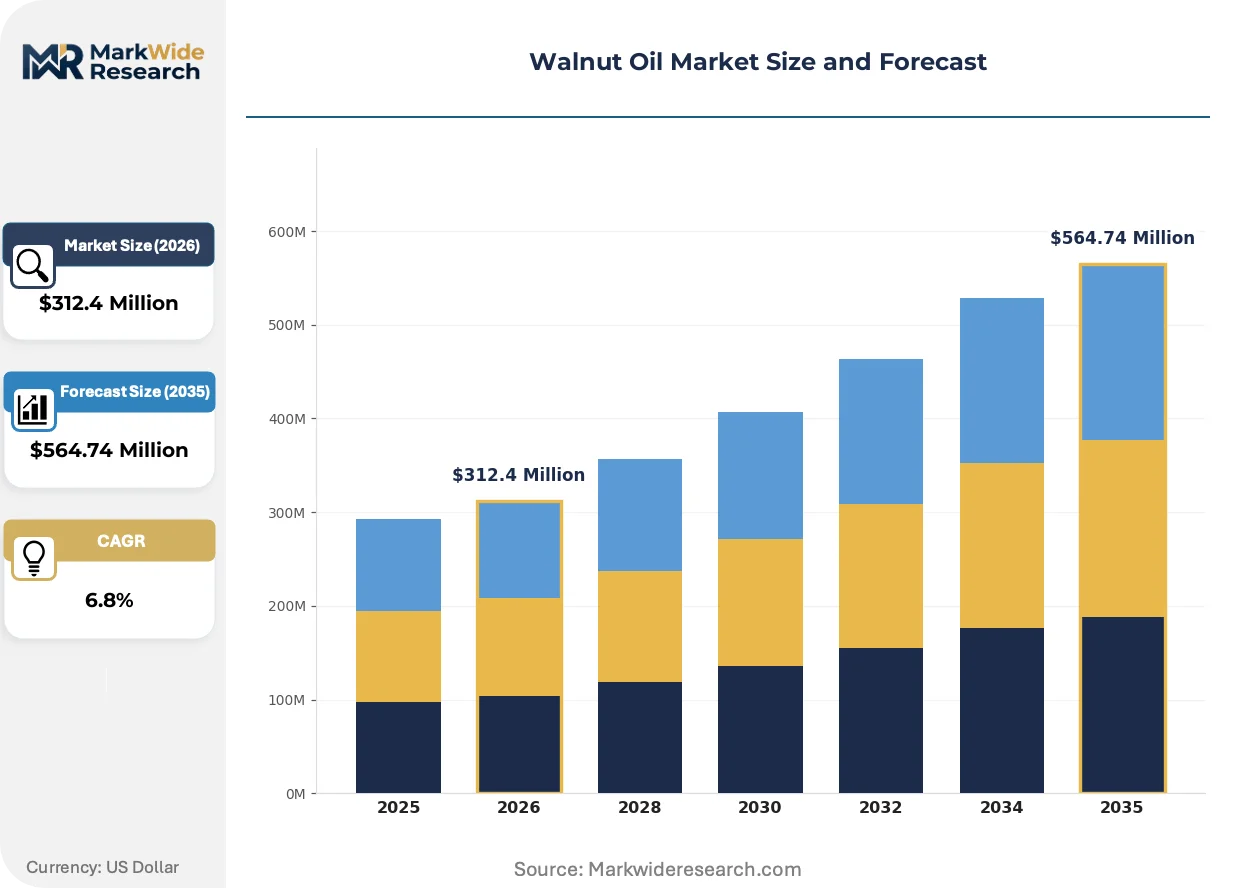
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Walnut Oil, Unrefined Walnut Oil, Organic Walnut Oil, Cold-Pressed Walnut Oil Application: Culinary Uses, Cosmetic Products, Nutraceuticals, Industrial Oils Packaging Type: Glass Bottles, Plastic Bottles, Tubes, Bulk Containers End User: Food Manufacturers, Cosmetic Companies, Pharmacies, Restaurants |
| Companies Covered | Olitalia S.p.A., Gustav Heess GmbH, La Tourangelle, Inc., Royal Nut Company, Caloy, Inc., Emile Noël S.A.S., Bio Planète GmbH, AOS Products Pvt. Ltd., Patanjali Ayurved Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walnut Oil Market Strategic Shifts
Digital traceability systems and extraction automation are compressing quality assurance cycles while regulatory tightening around contaminants is forcing equipment upgrades across processing tiers.
Near-infrared spectroscopy is virtualizing quality control workflows by enabling real-time oil composition verification without laboratory delays. Gourmet food manufacturers in France are adopting inline sensors to certify linoleic acid profiles during pressing operations. This technology is virtualizing the traditional batch-sampling model that previously required 48-hour laboratory turnaround.
REACH enforcement on polycyclic aromatic hydrocarbons is tightening contaminant thresholds for unrefined oils sold into cosmetic applications. European processors must install activated carbon filtration or face exclusion from premium personal care supply chains. German toll processors report capital deployment toward multi-stage purification to retain ECHA-compliant export eligibility.
Chef-driven specification is consolidating procurement around origin-verified, single-orchard bottlings that command tableside storytelling premiums. Direct sourcing relationships between French walnut growers and Parisian restaurant groups are displacing traditional distributor intermediaries. This pattern concentrates most visibly in the Ile-de-France culinary cluster where provenance transparency has become a competitive necessity for wine and oil lists alike.
Walnut Oil Market Segmentation
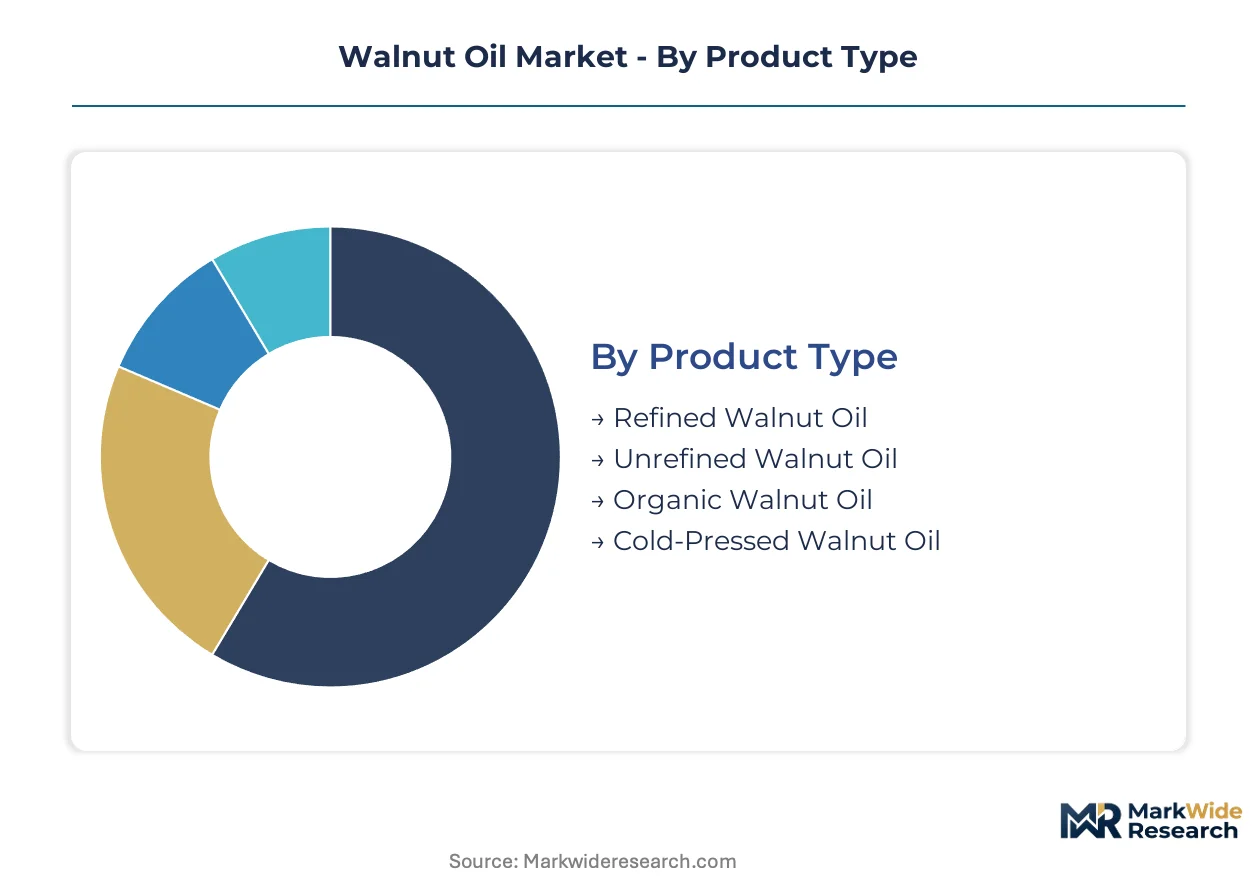
Walnut oil segmentation reveals divergent margin structures across extraction methods and end-use specifications. Procurement cycles vary dramatically between bulk food manufacturing contracts and boutique cosmetic supply agreements.
Product Type:
Cold-pressed and refined variants turn inventory fastest through food-service channels, while organic certification extends sales cycles through compliance documentation.
- Unrefined Walnut Oil:Minimal thermal processing preserves volatile flavor compounds and polyunsaturated fat integrity. Parisian restaurant groups and German gourmet retailers specify this grade for finishing applications where organoleptic intensity justifies per-liter premiums.
- Cold-Pressed Walnut Oil:Mechanical extraction below 40°C limits linoleic acid oxidation while meeting EFSA thresholds for novel food positioning. French cosmetic formulators in Grasse and Lyon prioritize this grade for skin barrier formulations replacing mineral oil bases.
- Refined Walnut Oil:Bleaching and deodorization extends shelf stability for industrial food manufacturing. Neutral flavor profile suits mayonnaise and dressing applications where walnut character must remain subtle.
- Organic Walnut Oil:USDA certification and EU organic logo compliance command slotting fee premiums in natural food channels. California and French Southwest orchard partnerships supply feedstock with full traceability documentation.
Unrefined grades dominate current culinary procurement volumes. Cold-pressed certification is where formulation partnerships with personal care manufacturers are expanding most aggressively.
Application:
Cosmetic applications carry the steepest margin tier despite smaller volume throughput, while culinary uses anchor baseline capacity utilization.
- Cosmetic Products:Emollient properties and linoleic acid content drive substitution for petroleum-derived bases in French and German skin care. REACH compliance requirements filter out non-ECHA-certified suppliers from premium personal care supply chains.
- Culinary Uses:Finishing oil demand concentrates in Ile-de-France restaurant clusters and Italian gastronomic tourism corridors. Smoke point limitations restrict penetration into frying-intensive food-service segments.
- Nutraceuticals:Omega-3 and antioxidant positioning requires EFSA novel food assessment completion. Documentation burdens strain smaller processors without dedicated regulatory affairs capacity.
- Industrial Oils:Wood treatment and lubricant applications absorb lower-grade press cake derivatives. Price sensitivity here limits supplier participation to toll processors with excess capacity.
Culinary applications retain the largest installed demand base. Cosmetic formulations are climbing fastest as mineral oil substitution accelerates among EU personal care manufacturers.
Packaging Type:
Glass bottle logistics constrain replenishment frequency for premium positioning, whereas bulk container contracts stabilize throughput planning.
- Glass Bottles:Amber and cobalt variants protect photo-oxidative stability for unrefined grades. Breakage rates and freight cost elevation limit distribution radius for artisanal mill direct-to-consumer shipments.
- Bulk Containers:Stainless steel totes and food-grade drums sustain food manufacturer procurement efficiency. French industrial dressing producers and German bakery chains specify this format for volume contracts.
- Plastic Bottles:HDPE and PET variants reduce landed cost for mass-market supermarket placement. Oxygen permeability concerns restrict suitability for extended shelf-life unrefined stock.
- Tubes:Aluminum laminate and squeeze formats serve travel-size cosmetic sampling programs. Grasse formulation houses specify this packaging for hotel amenity partnerships and subscription box inserts.
Bulk containers anchor manufacturing-scale procurement commitments. Glass bottles are where provenance storytelling and tableside presentation premiums concentrate.
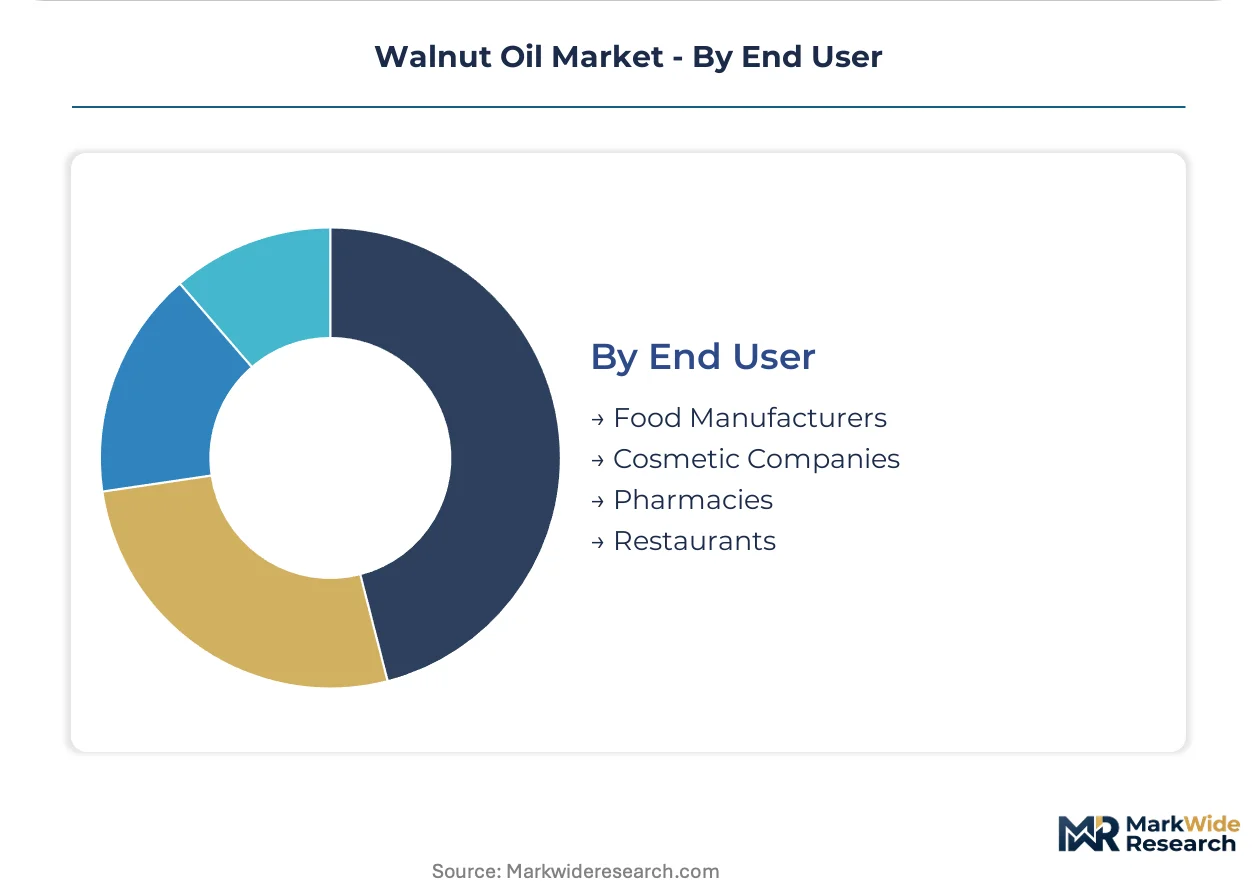
End User:
Restaurant procurement cycles track seasonal menu rotations, while cosmetic company contracts extend through multi-year formulation development timelines.
- Restaurants:Chef-driven specification in Paris, Lyon, and Milan clusters prioritizes origin-verified single-orchard bottlings. Direct sourcing relationships displace traditional distributor intermediaries for high-visibility wine and oil list placement.
- Cosmetic Companies:L'Oréal and Beiersdorf supplier qualification processes demand 18-24 month stability documentation. French toll processors with ECHA-certified filtration infrastructure capture formulation partnership opportunities.
- Food Manufacturers:Industrial dressing and sauce producers in Italy and Spain specify refined grades with consistent oxidative stability metrics. Annual volume commitments support dedicated pressing schedule arrangements.
- Pharmacies:Omega-3 supplement positioning requires pharmacy channel registration in Germany and Austria. Cold-pressed organic variants with novel food clearance command shelf-space premiums in apothecary retail.
Food manufacturers represent the largest contracted volume base. Cosmetic companies are where supplier qualification moats and multi-year partnership value are concentrating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium-grade French walnut oil commands shelf-space premiums two to three times above mass-market Californian equivalents, creating a transatlantic pricing asymmetry that shapes procurement strategies across both continents.
France
Traditional walnut orchards in the Périgord and Isère valleys supply cold-pressed stock to Parisian restaurant groups and Grasse cosmetic formulators. ECHA REACH compliance requirements filter non-certified processors from cosmetic supply chains. The Île-de-France culinary cluster drives origin-verified single-orchard procurement for tableside presentation.
Germany
German gourmet retailers and personal care manufacturers anchor demand for EFSA-compliant cold-pressed variants. BfR contaminant thresholds for polycyclic aromatic hydrocarbons force filtration infrastructure upgrades among toll processors. Bavarian and Baden-Württemberg distribution networks channel premium volumes into pharmacy and natural food channels.
United States
California Central Valley orchards supply feedstock for USDA-certified organic cold-pressed production. FDA food facility registration creates compliance moats for established suppliers targeting natural food retail. Direct-to-consumer platforms and boutique grocers in coastal metropolitan markets displace mass-market supermarket volumes.
Italy
Emilia-Romagna and Piedmont gastronomic tourism corridors concentrate finishing oil demand from chef-driven procurement. Olitalia S.p.A. leverages domestic distribution infrastructure to capture food-service supply contracts. Italian industrial dressing producers specify refined grades for mayonnaise applications requiring neutral flavor profiles.
India
Kashmir Valley walnut cultivation supports emerging cold-pressed extraction capacity serving domestic Ayurvedic and cosmetic markets. FSSAI food safety compliance requirements shape export readiness for personal care manufacturers. AOS Products Pvt. Ltd. and Patanjali Ayurved Limited occupy positions within the domestic supplier tier.
Walnut Oil Market Competitive Environment
Specialty millers and integrated food-service suppliers split the market between artisanal provenance storytelling and industrial scale efficiency. The vendor base concentrates among European cold-press specialists, North American direct-to-consumer platforms, and emerging South Asian Ayurvedic suppliers. Three archetypes dominate: orchard-integrated millers with captive supply, toll processors with ECHA-certified filtration infrastructure, and brand houses with distribution network control. Competitive moves center on backward integration into orchard partnerships and multi-stage purification capacity deployment.
Among European specialists, Gustav Heess GmbH exemplifies the German cold-press archetype with its GmbH structure signaling family-owned precision manufacturing. La Tourangelle, Inc. occupies the North American artisanal positioning tier, its French-derived name anchoring premium culinary association despite US incorporation. Olitalia S.p.A. represents the integrated food-service supply model, its Italian S.p.A. suffix indicating corporate scale and domestic distribution density.
| Leading Market Players |
|---|
| Olitalia S.p.A. |
| Gustav Heess GmbH |
| La Tourangelle, Inc. |
| Royal Nut Company |
| Caloy, Inc. |
| Emile Noël S.A.S. |
| Bio Planète GmbH |
| AOS Products Pvt. Ltd. |
| Patanjali Ayurved Limited |
| Others |
Value Chain & Pricing Dynamics
French Périgord and Isère valley orchards supply over sixty percent of premium cold-pressed feedstock, anchoring margin pools in Parisian restaurant groups and Grasse cosmetic formulators who pay origin-verified premiums. This upstream concentration grants established processors pricing power over boutique buyers while exposing mid-scale competitors to harvest volatility.
Pricing Analysis
Origin-verified single-orchard bottlings command three-to-four-fold premiums over standard cold-pressed grades, with pricing stratifying across premium, standard, and economy tiers driven by certification grade and provenance documentation. ECHA REACH compliance for cosmetic-grade exports adds fifteen to twenty percent to compliant stock. Pricing pressure stems from California Central Valley harvest variability compressing organic feedstock availability. Food manufacturers exhibit highest price sensitivity, while Parisian restaurant groups absorb premiums for tableside storytelling value.
Supply Chain Analysis
Walnut kernel supply draws from France, California, and Kashmir Valley cultivation zones, with linoleic acid content and polycyclic aromatic hydrocarbon thresholds as critical quality gatekeepers. Single-source vulnerability concentrates in French Southwest orchards vulnerable to climatic stress. Distribution runs through three channels: direct sourcing relationships for restaurant clusters, toll processors with ECHA-certified filtration for cosmetic manufacturers, and bulk container contracts for industrial dressing producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Walnut oil procurement operates as a defensive-moat market where ECHA REACH certification and FDA food facility registration create switching costs that entrench established suppliers against new competition.
For Market Incumbents: Pre-empt margin compression by securing captive orchard partnerships in California Central Valley and French Southwest regions before harvest volatility escalates. Invest in multi-stage activated carbon filtration to maintain ECHA-compliant export eligibility as BfR thresholds tighten. Channel control through direct-to-consumer platforms displaces distributor intermediaries and captures provenance premiums.
For New Entrants and Emerging Players: Indian domestic Ayurvedic and cosmetic markets represent the most penetrable entry point given FSSAI compliance requirements filter out multinational competition. Kashmir Valley cold-pressed capacity serving regional personal care manufacturers offers white-space acquisition potential. Grasse formulation house partnerships provide the critical go-to-market angle for cosmetic-grade positioning.
For Investors and Strategic Acquirers: Capital is best deployed toward toll processors with ECHA-certified infrastructure and established cosmetic manufacturer relationships, as these assets compound regulatory entrenchment over a five-to-ten year viability window. Orchard-integrated millers with captive French or Californian supply offer upstream scarcity value. The signal to watch is EFSA novel food assessment timeline acceleration for omega-3 positioning claims.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Partnerships | Captive supply from Périgord or Central Valley orchards secures origin-verified feedstock for premium positioning. |
| ECHA-Certified Filtration Infrastructure Deployment | Multi-stage purification capacity retains cosmetic-grade export eligibility as REACH thresholds tighten. |
| Direct-to-Consumer Platform Launch | Boutique e-commerce channels capture provenance premiums previously flowing through supermarket distributors. |
| EFSA Novel Food Assessment Completion | Omega-3 health claim clearance expands addressable demand beyond culinary into nutraceutical pharmacy channels. |
| Cosmetic Formulation Partnership | L'Oréal and Beiersdorf supplier qualification processes create multi-year revenue visibility for compliant processors. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with cold-press mill operators, cosmetic formulators in Grasse and Lyon, Parisian restaurant procurement heads, and German gourmet retail buyers; and secondary validation through customs trade records, EFSA novel food assessment filings, and ECHA REACH compliance registries. Bottom-up volume triangulation against top-down value estimates calibrated segmentation splits across extraction method, application, and packaging format dimensions.
Forecast inputs span extraction technology adoption curves, regulatory timeline assumptions, and chef-driven procurement pattern shifts across the projection horizon. Modeled dimensions include product type tier, end-use application, packaging format, and regional production cluster. CAGRs were derived from segment-level volume trajectories weighted by price realization trends. Industry-specific inputs incorporate polycyclic aromatic hydrocarbon threshold evolution and organic certification penetration rates.
Practitioners should monitor EFSA novel food assessment backlog, California drought severity indices, and REACH enforcement intensity for early signals of forecast revision. Cross-checking against customs export volume data from French and German statistical agencies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Almond Protein Market
Nuts and Seeds
Macadamia Nut Market
Nuts and Seeds
Global Peanut Meal Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
Flax Seed Meal Market
Nuts and Seeds
Fat Free Peanut Butter Market
Nuts and Seeds
Pecans Market
Nuts and Seeds
Baru Nuts Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Walnut Market