
 Organic Protein Powder Market | 2026-2036
Organic Protein Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Protein Powder Market Analytics
Plant-based food formulation expertise is rotating from niche specialty toward mainstream CPG competency, tightening the labor pool for brands seeking clean-label innovation. Garden of Life leverages its parent company's supply chain scale to dominate shelf presence in natural retail channels. Sunwarrior differentiates through sprouted and fermented protein technologies that appeal to digestive-sensitive consumers. Promix Nutrition anchors its position with third-party testing protocols that sustain premium pricing power.
Organic protein powder denotes dried, mechanically processed protein isolates or concentrates derived from certified organic raw materials, typically containing 15–25 grams of protein per 30-gram serving with restricted synthetic additive profiles. The product serves commercial purposes spanning sports nutrition recovery, meal replacement formulations, and clinical dietary supplementation. Pea protein occupies the fastest-expanding slot within product type classifications as allergen-free positioning and neutral flavor profiles attract formulators. Ready-to-drink formats command margin concentration despite powder retaining volume leadership, while online retail channels are displacing health stores as the primary acquisition path for vegan end users.
The USDA National Organic Program governs ingredient provenance and processing integrity, while FDA labeling rules enforce structure-function claim boundaries that constrain marketing language. The EU Green Deal's Farm-to-Fork strategy is reshaping import requirements for organic commodities entering European processing facilities. Stakeholders must monitor evolving certification harmonization between USDA and EU organic standards to preempt supply chain fragmentation.
Market Dynamics
Home workout cultures have permanently altered protein consumption patterns, shifting volume from gym-centric impulse purchases toward planned subscription replenishment and functional food integration.
Growth Catalysts
- USDA Organic Certification:The National Organic Program creates label differentiation that commands shelf price premiums and locks in supply contracts with certified ingredient growers.
- Pea Protein Processing Advances:Mechanical fractionation improvements eliminate beany off-notes, enabling clean-label formulations that replace soy and whey in allergen-sensitive applications.
- Fitness Enthusiast Segment Expansion:Strength training participation rates in United States metropolitan clusters sustain double-digit powder consumption velocity through direct-to-consumer channels.
Market Restraints
- Organic Commodity Price Volatility:Certified pea and rice protein concentrate costs fluctuate with weather-dependent harvest yields in Canada and Ukraine growing regions.
- Single-Source Supply Concentration:North American organic brown rice protein relies heavily on Arkansas and California processing facilities, creating geographic vulnerability.
- Technical Solubility Limitations:Plant protein isolates exhibit inferior cold-water dispersibility versus whey, constraining ready-to-drink format adoption.
Strategic Opportunities
- Clinical Dietary Supplementation:Hospital and long-term care facilities seek texture-modified, high-protein additives for dysphagia patients and post-surgical recovery protocols.
- EU Green Deal Alignment:Farm-to-Fork strategy incentivizes organic protein imports that meet regenerative agriculture benchmarks, opening premium positioning for compliant suppliers.
- Direct-to-Consumer Subscription Models:Algorithm-driven personalization platforms capture lifetime value through flavor rotation and delivery timing optimization.
Industry Challenges
- Clean-Label Formulation Expertise Gap:Brands struggle to source food scientists proficient in natural flavor masking and emulsion stability without synthetic additives.
- Dual Certification Timeline Compression:Simultaneous USDA Organic and NSF Sport validations extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Protein Powder Market |
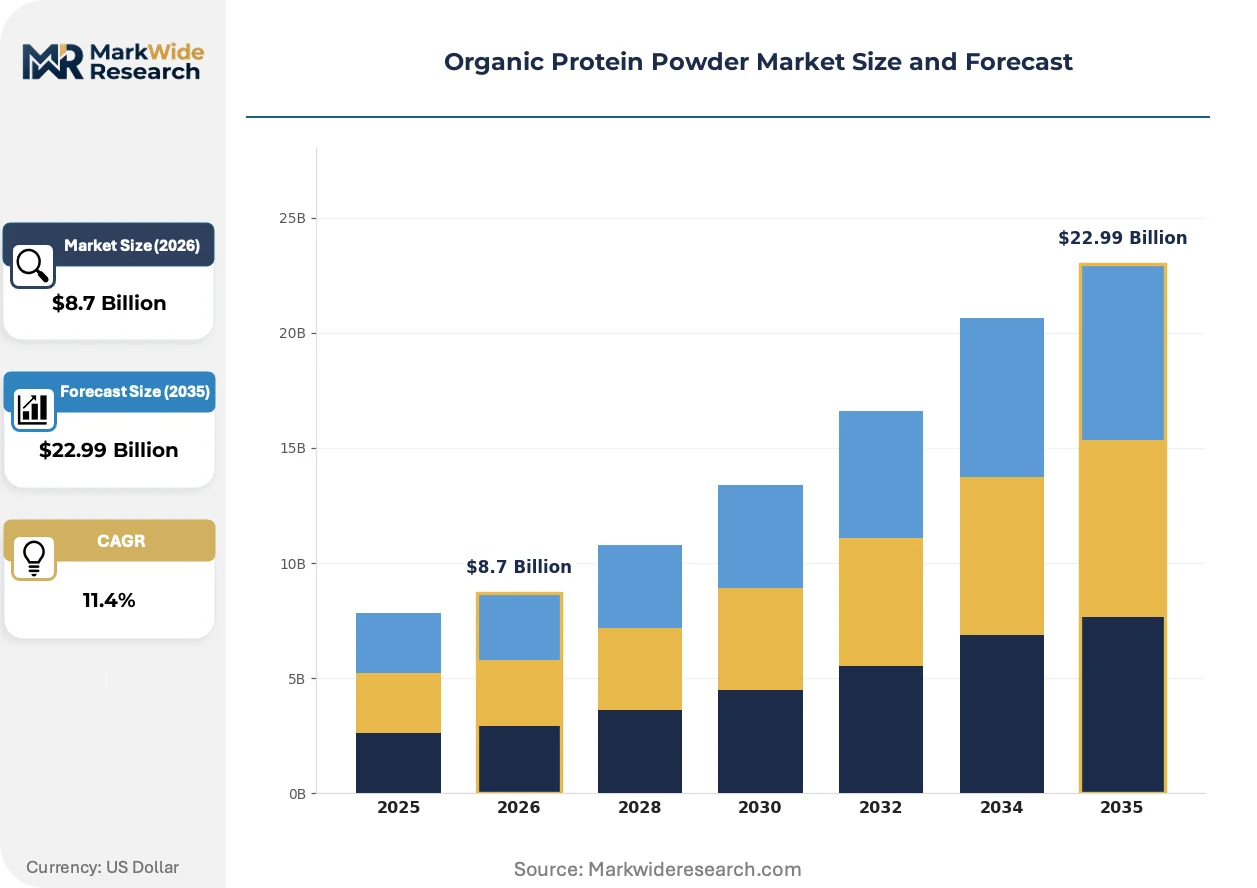
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey, Pea, Soy, Hemp Form: Powder, Ready-to-Drink, Bars, Capsules End User: Athletes, Fitness Enthusiasts, Health-Conscious Consumers, Vegans Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms |
| Companies Covered | Garden of Life, Sunwarrior, Truvani, Sprout Living, Promix Nutrition, Transparent Labs, Ritual, Ora Organic, Organifi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Protein Powder Market Evolving Landscape
Sprouted and fermented protein technologies are rewriting digestive tolerance standards, while regulatory divergence between USDA and EU organic frameworks forces parallel supply chain investments.
Fermentation-enhanced protein concentrates are bifurcating the premium tier. Enzymatic pre-digestion reduces anti-nutrient loads and improves amino acid bioavailability for sensitive consumers. Specialty retailers in United States coastal markets stock these skus at 40-60% price premiums over conventional isolates, compressing margin structures for legacy heat-processed alternatives.
The EU Green Deal's Farm-to-Fork strategy tightens import documentation for organic commodities entering Rotterdam and Hamburg processing hubs. European formulators now demand batch-level regenerative agriculture certificates that exceed baseline EU Organic standards. North American exporters respond by segregating supply chains and pursuing dual certification to maintain continental market access.
Subscription-based replenishment has displaced health store foot traffic as the dominant acquisition path for vegan end users. Digital-native brands capture recurring revenue through mobile-optimized reordering interfaces that integrate with fitness tracking applications. This behavioral shift concentrates most visible in United States urban markets where same-day delivery logistics have matured.
Organic Protein Powder Market Segmentation
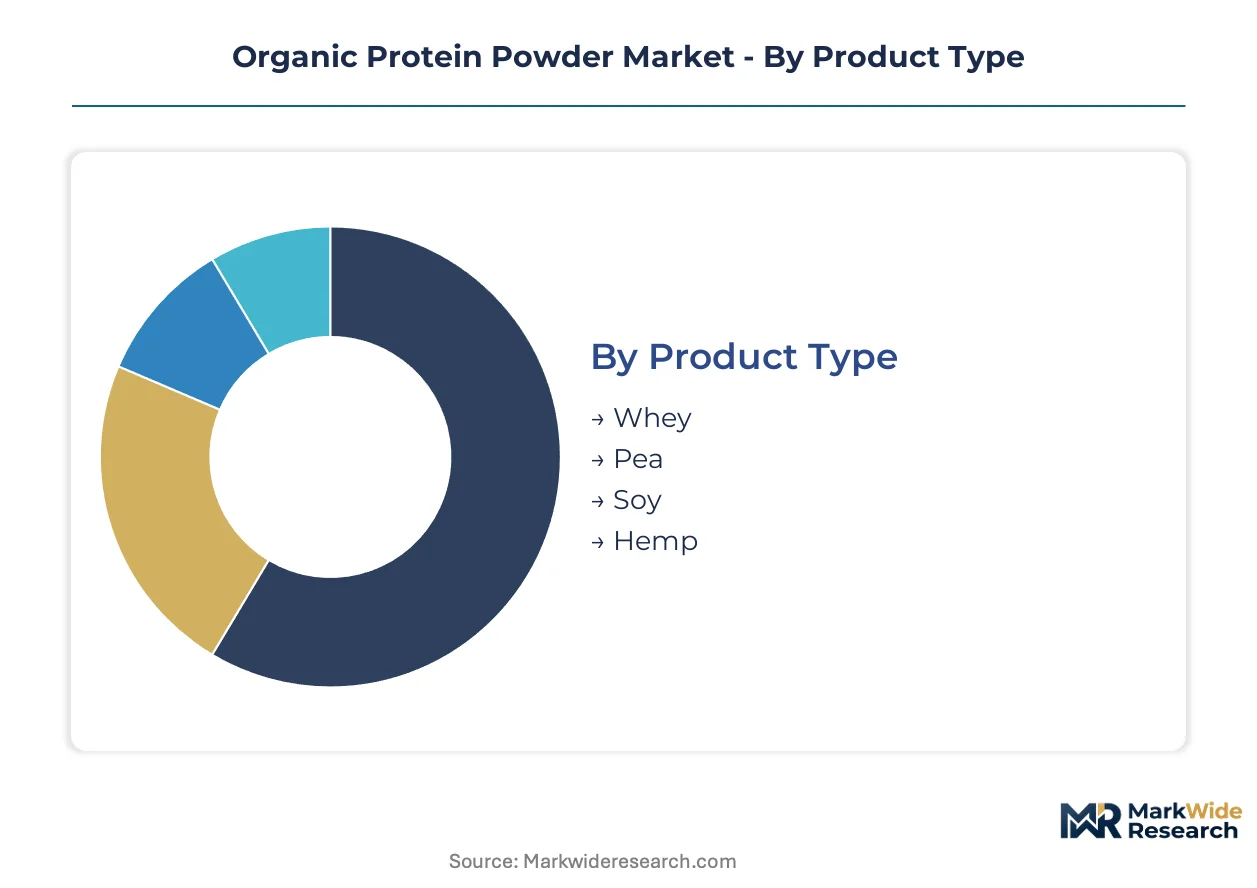
Segmentation in organic protein powder reveals how formulation choices, consumption occasions, and purchase pathways split margin pools across distinct customer missions. Understanding these divides exposes where brands must build specialized capabilities versus where scale economics dominate.
Product Type:
Margin pools concentrate in allergen-free and digestive-tolerant formulations that command shelf price premiums over commodity alternatives.
- Pea:Mechanical fractionation advances have eliminated beany off-notes, enabling clean-label formulations that replace soy and whey in allergen-sensitive applications. Demand concentrates in United States metropolitan fitness clusters where vegan positioning drives direct-to-consumer velocity.
- Whey:Despite organic certification constraints on dairy sourcing, whey retains formulation familiarity among legacy sports nutrition users. Supply contracts with certified organic dairy cooperatives in Wisconsin and New Zealand lock in premium positioning.
- Soy:Isoflavone concerns and allergen labeling requirements have compressed soy's addressable market to price-sensitive institutional buyers.
- Hemp:Omega fatty acid co-benefits attract wellness-positioned brands, though THC threshold compliance adds regulatory testing costs.
The dominant share belongs to whey, while pea is closing the gap fastest.
Form:
Volume leadership sits with powder formats, yet margin accretion flows toward convenience-driven ready-to-drink and bar configurations.
- Powder:Retains volume leadership through cost-per-gram efficiency and flavor customization flexibility. Home workout cultures in United States suburbs sustain subscription replenishment models.
- Ready-to-Drink:Commands margin concentration despite smaller volume share, as cold-chain distribution and on-the-go consumption occasions justify 60-80% price premiums over equivalent powder servings.
- Bars:Texture-modified formats capture meal-replacement occasions with binding and shelf-stability challenges that favor established CPG manufacturers.
- Capsules:Clinical dietary supplementation and travel-portable dosing drive niche demand from dysphagia patients and frequent travelers.
Powder retains the largest revenue base, yet ready-to-drink formats are expanding most quickly.
End User:
Customer mission differentiation separates performance-obsessed buyers seeking recovery optimization from lifestyle buyers prioritizing clean-label alignment.
- Fitness Enthusiasts:Strength training participation rates sustain double-digit powder consumption velocity through algorithm-driven subscription platforms that optimize delivery timing.
- Health-Conscious Consumers:USDA organic certification serves as primary filter, with label literacy driving preference for single-ingredient concentrates over proprietary blends.
- Athletes:NSF Sport and Informed Sport certification requirements constrain product selection to tested SKUs, compressing margin through third-party validation costs.
- Vegans:Ethical positioning combines with digestive sensitivity to favor sprouted and fermented protein technologies stocked at 40-60% premiums in coastal United States specialty retail.
The dominant share belongs to health-conscious consumers, while fitness enthusiasts are gaining share fastest.
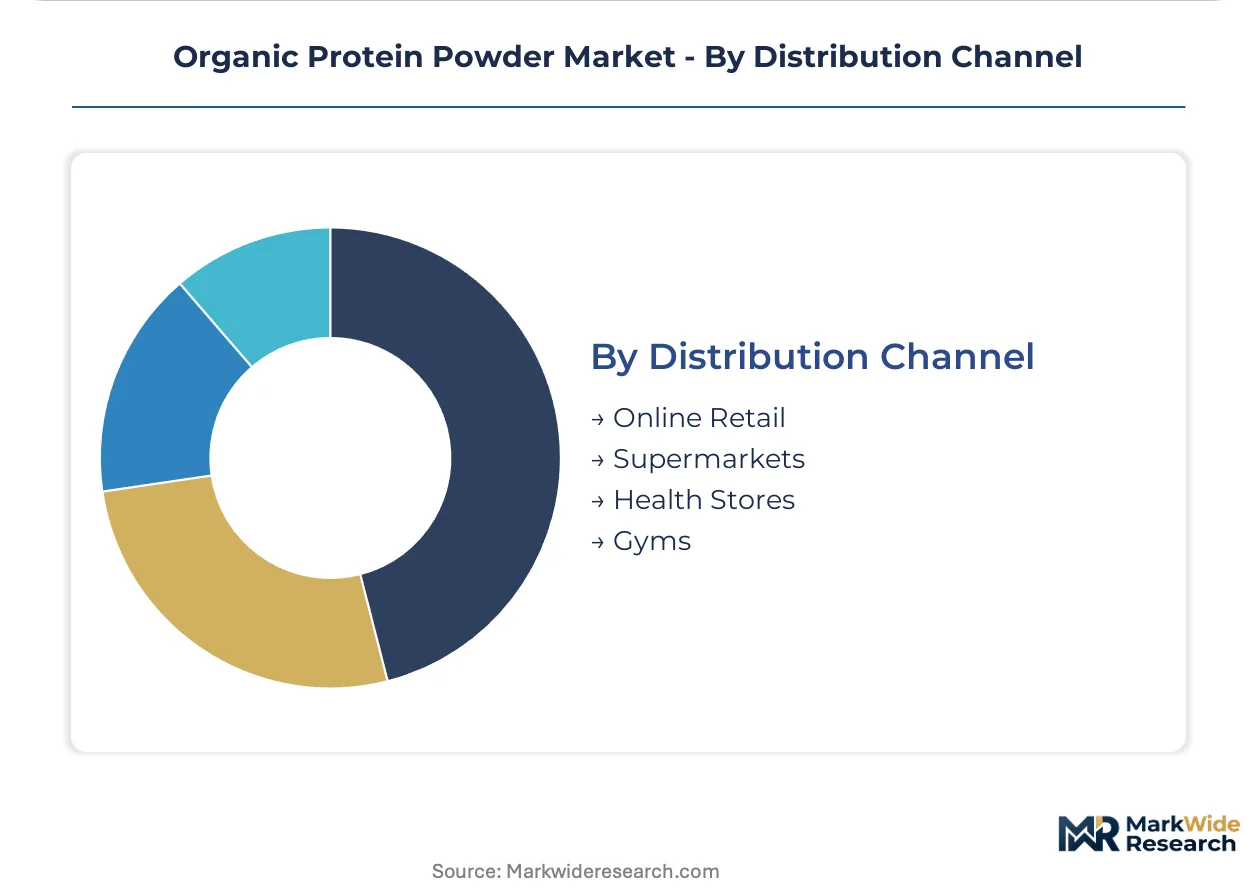
Distribution Channel:
Channel economics bifurcate between high-touch discovery environments and low-friction replenishment platforms.
- Online Retail:Algorithm-driven personalization and mobile-optimized reordering interfaces have displaced health stores as primary acquisition path for vegan end users. Same-day delivery logistics in United States urban markets concentrate recurring revenue capture.
- Supermarkets:Mainstream shelf presence requires slotting fee investments that favor parent-company supply chain scale, with natural retail chains anchoring organic-specific merchandising.
- Health Stores:Staff recommendation and sampling sustain discovery for fermented and sprouted premium tiers, though foot traffic erosion compresses growth.
- Gyms:Impulse purchase occasions have declined as home workout cultures shift volume toward planned subscription replenishment.
Online retail holds the dominant position, while supermarkets are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA National Organic Program anchors regulatory frameworks in the United States, while the EU Green Deal's Farm-to-Fork strategy reshapes import requirements across European processing facilities. Demand concentrates in metropolitan fitness clusters where direct-to-consumer subscription models displace traditional retail channels.
United States
Strength training participation rates in metropolitan clusters sustain double-digit powder consumption velocity through algorithm-driven subscription platforms. The USDA National Organic Program governs ingredient provenance and processing integrity for all certified products. Brooklyn and Austin anchor emerging brand headquarters where digital-native companies optimize mobile-optimized reordering interfaces.
Germany
Regenerative agriculture benchmarks exceed baseline EU Organic standards, tightening documentation for organic commodities entering Rotterdam and Hamburg processing hubs. The EU Green Deal's Farm-to-Fork strategy incentivizes imports meeting stricter sustainability criteria. Berlin and Munich host specialty retailers stocking fermented protein concentrates at substantial price premiums over conventional isolates.
Canada
Certified organic pea protein concentrate costs fluctuate with weather-dependent harvest yields in Prairie growing regions. Health Canada maintains labeling rules that enforce structure-function claim boundaries constraining marketing language. Toronto and Vancouver concentrate direct-to-consumer fulfillment infrastructure serving cross-border demand.
United Kingdom
Post-Brexit regulatory divergence forces parallel supply chain investments to maintain continental European market access. The Food Standards Agency enforces novel food approvals for emerging protein technologies. London anchors specialty retail chains where staff recommendation sustains discovery for premium-tier formulations.
Australia
TGA oversight of therapeutic claims shapes clinical dietary supplementation positioning for texture-modified, high-protein additives. Organic certification harmonization pressures exporters pursuing dual USDA and EU market access. Sydney and Melbourne concentrate fitness enthusiast populations driving subscription replenishment model adoption.
Organic Protein Powder Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with parent-company supply chain scale determining shelf presence in natural retail channels. The middle tier fragments across sprouted and fermented technology specialists, third-party testing protocol adherents, and digital-native subscription platforms. Two strategic archetypes dominate: supply-chain-integrated incumbents leveraging captive ingredient sourcing, and agile direct-to-consumer challengers optimizing algorithm-driven personalization. Competitive moves concentrate on M&A for organic certification assets and geographic expansion into EU Green Deal-aligned supply chains.
Within the integrated leader tier, Garden of Life exemplifies supply-chain scale advantages through parent-company infrastructure. Sunwarrior and Promix Nutrition occupy specialist positions, with the former representing sprouted and fermented technology archetypes and the latter anchoring third-party testing protocol differentiation. These three companies illustrate how competitive positioning splits between scale-driven shelf dominance and premium-tier certification credibility.
| Leading Market Players |
|---|
| Garden of Life |
| Sunwarrior |
| Truvani |
| Sprout Living |
| Promix Nutrition |
| Transparent Labs |
| Ritual |
| Ora Organic |
| Organifi |
| Others |
Value Network & Pricing Analysis
Capacity utilization at certified organic pea protein fractionation facilities in Canada and Ukraine directly shapes both ingredient availability and floor pricing for finished powder formulations. USDA certification requirements lock in multi-year supply contracts that insulate premium tiers from commodity volatility while exposing standard-grade products to harvest-dependent cost swings.
Pricing Analysis
Geographic price spreads between North American and European shelf prices reflect divergent certification burdens and logistics costs rather than formulation differences. Subscription-based replenishment models dominate the pricing structure, with algorithm-driven personalization commanding 15-25% premiums over standard direct-to-consumer tiers. Price differentiation hinges on third-party testing protocols and organic certification grade, with NSF Sport validation sustaining the highest price points. Cost compression in the standard tier is intensifying as private-label entrants replicate base formulations, while fitness enthusiasts show lowest price sensitivity and institutional buyers exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for organic brown rice protein concentrate stretch to six months during Prairie harvest windows, forcing brands to pre-position working capital ahead of processing campaigns. Geographic supply concentration centers on Canada for pea protein, the United States for dairy-based whey isolates, and Ukraine for sunflower-derived alternatives. Raw material dependencies include certified organic yellow peas, sprouted brown rice, and hemp seed cake with THC compliance documentation. Single-source vulnerability runs through Arkansas and California rice protein processing facilities. Distribution runs through direct-to-consumer fulfillment centers in metropolitan United States clusters, with specialty retail chains anchoring premium-tier discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as fitness enthusiasts migrate toward algorithm-driven subscription platforms that aggregate demand and squeeze margin from fragmented suppliers. This consolidation among end users reshapes negotiation dynamics across ingredient procurement and shelf placement.
For Market Incumbents: Consolidate backward integration into certified organic pea protein fractionation capacity in Canada to lock in supply security against harvest volatility. Capture channel control through exclusive placement agreements with natural retail chains that Garden of Life already dominates, while investing in dual USDA-EU organic certification to preempt regulatory fragmentation threats from the EU Green Deal's Farm-to-Fork strategy.
For New Entrants and Emerging Players: Personalized flavor rotation and delivery timing optimization represent the service-layer gap where incumbents under-serve digestive-sensitive consumers seeking sprouted and fermented alternatives. Target clinical dietary supplementation for dysphagia patients and post-surgical recovery protocols as the most penetrable application, deploying third-party testing credentials as the primary go-to-market angle to bypass incumbent shelf dominance.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital-native subscription platforms with mobile-optimized reordering interfaces integrated into fitness tracking applications. Long-term viability across the analysis window favors acquisition targets with captive organic certification assets and established EU supply chain segregation capabilities. Watch for inflection signals in regenerative agriculture certificate adoption rates among North American exporters seeking Rotterdam and Hamburg processing hub access.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Parallel USDA-EU organic validation opens Rotterdam and Hamburg processing hub access for exporters. |
| Subscription Platform Integration | Algorithm-driven personalization captures lifetime value through flavor rotation and delivery timing optimization. |
| Backward Integration into Pea Fractionation | Captive supply of certified organic concentrate insulates margin from Prairie harvest yield volatility. |
| Clinical Channel Development | Hospital and long-term care procurement protocols favor texture-modified, high-protein additive suppliers. |
| Fermentation Technology Licensing | Enzymatic pre-digestion capabilities command 40-60% shelf price premiums in coastal United States specialty retail. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at organic protein powder manufacturers, category buyers at natural retail chains, supply planners at certified ingredient processors, and procurement leads at clinical nutrition distributors, then refined through secondary validation. Primary interviews triangulated with customs records, USDA National Organic Program certification databases, Nielsen retail audit data, and SEC filings from parent-company CPG conglomerates. Bottom-up demand modeling across end-user segments converged with top-down supply-side capacity assessments.
Variance decomposition across the projection horizon isolated volume drivers from price-mix effects within each segmentation dimension. The analytical framework modeled protein source type, form factor, end-user mission, and distribution channel, with regional regulatory clusters treated as scenario inputs. CAGRs derived from segment-level growth rate synthesis weighted by current revenue contribution. Industry-specific forecast inputs included strength training participation indices and organic commodity futures curves.
Underlying assumptions cover sustained home workout culture persistence and EU Green Deal implementation trajectory, with deviation risk concentrated in weather-dependent organic harvest yields and certification harmonization timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Algae Omega 3 Market
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Omega 3 Supplements Market
Nutritional Supplements
Mexico Collagen Peptides Market
Nutritional Supplements
Fat Powders Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
South Africa Nutraceuticals Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
High-Selenium Yeast Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Argentina Nutraceuticals Market