
 Nuts and Nutmeals Market | 2026-2036
Nuts and Nutmeals Market Size, Share, and Industry Trends Forecast 2026-2036
Nuts and Nutmeals Market Analytics
EU F-Gas Regulation is broadening compliance costs for nut processors reliant on controlled-atmosphere storage. Blue Diamond Growers leverages its cooperative structure to sustain long-term supply contracts with retail chains. Olam Group anchors its procurement network across multiple origin markets to secure year-round availability. Archer Daniels Midland Company dominates bulk ingredient channels for food manufacturing customers.
Nuts and nutmeals comprise shelled or processed tree nuts and their milled derivatives, typically retaining protein contents between 15% and 25% and oil contents from 50% to 70% by weight depending on species, with primary commercial applications spanning direct consumption, bakery inclusion, confectionery coating, and plant-based beverage bases. Almonds lead product type volumes due to dairy-alternative formulation demand, while ground forms capture expanding penetration in gluten-free flour substitution and protein fortification. Whole nuts retain premium positioning in gift and seasonal segments, though bulk packaging for industrial buyers concentrates margin pools in foodservice and manufacturing channels.
FDA food safety modernization rules and USDA organic certification standards shape product standards and market access for US-origin suppliers, while EU REACH and EFSA novel food assessments govern import compliance for nutmeal ingredients entering European formulations. Stakeholders must monitor evolving allergen labeling mandates and carbon accounting requirements across destination markets to preserve competitive positioning.
Market Dynamics
Almond supply concentration in California's Central Valley creates structural vulnerability as water scarcity intensifies and climate volatility accelerates orchard yield fluctuations, forcing processors to diversify procurement networks across Mediterranean and Australian origins.
Growth Catalysts
- Plant-based dairy formulation:Almond and cashew bases displace soy in premium beverage applications as clean-label preferences harden among North American and European consumers.
- EU F-Gas Regulation:Cold-chain infrastructure upgrades for controlled-atmosphere storage reduce post-harvest losses and extend shelled nut shelf life in transit.
- India:FSSAI fortification mandates in mid-day meal programs and bakery standards drive groundnut and almond meal inclusion in institutional procurement.
Market Restraints
- Input cost volatility:Bee colony rental fees for almond pollination have tripled since 2018 as hive availability tightens across California.
- Supply concentration risk:California's Central Valley accounts for over three-quarters of global almond output, exposing buyers to single-origin climate shocks.
- Regulatory friction:EFSA novel food assessments delay introduction of emerging nut species and processed meal formats into European formulations.
Strategic Opportunities
- Australian almond expansion:Riverina and Sunraysia plantings offer counter-seasonal supply and reduced water risk versus California origins.
- Precision fermentation convergence:Hybrid nut-protein and microbial biomass blends target complete amino acid profiles for sports nutrition applications.
- Direct-to-manufacturer channels:Bulk ingredient platforms bypass traditional wholesale tiers, capturing margin compression in industrial nutmeal sales.
Industry Challenges
- Allergen control protocols:Segregated processing lines and sanitation validation for peanut-free facilities demand capital-intensive facility reconfiguration.
- Carbon accounting implementation:Scope 3 measurement for orchard water use, bee transport, and fertilizer application lacks standardized methodology across supplier tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuts and Nutmeals Market |
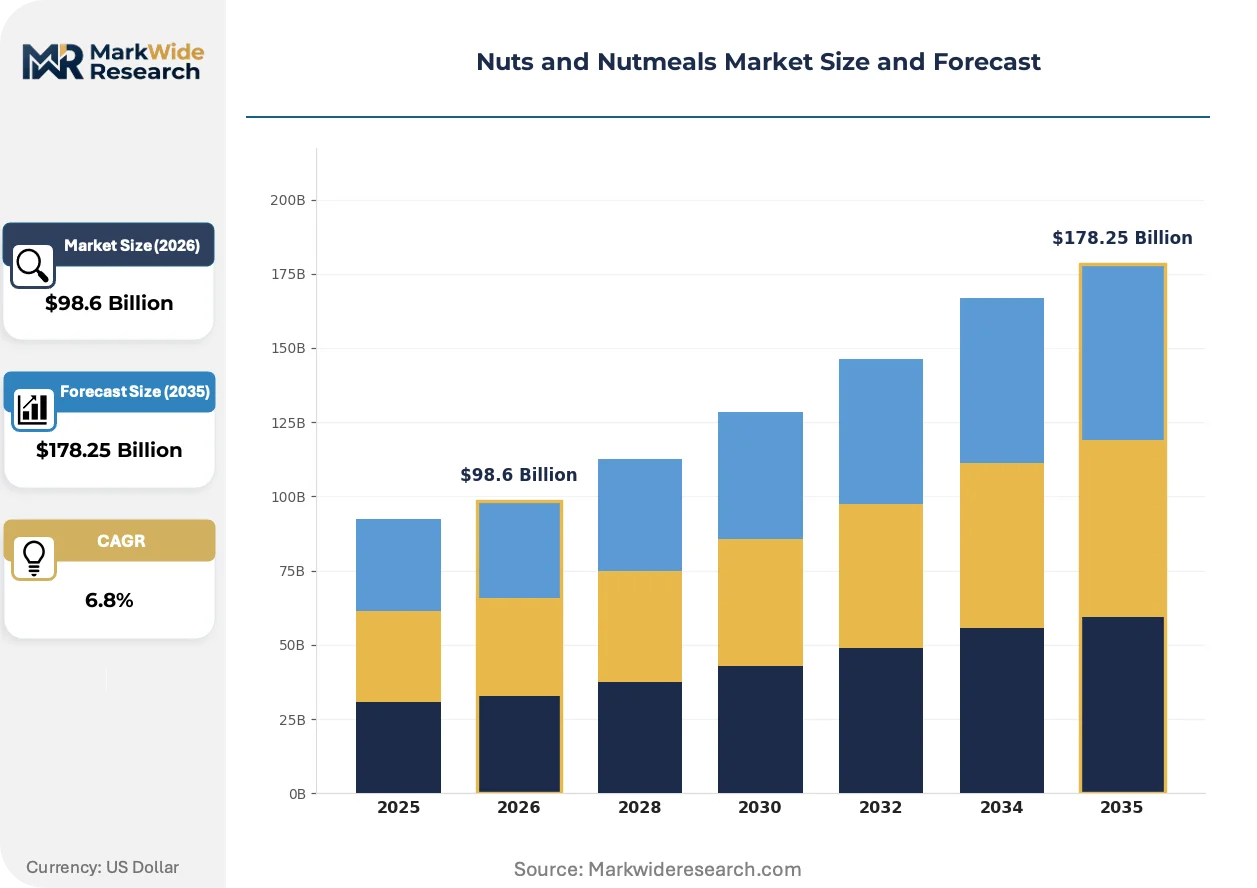
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walnuts, Almonds, Cashews, Hazelnuts Form: Whole, Sliced, Chopped, Ground Packaging Type: Bags, Jars, Boxes, Bulk Distribution Channel: Online, Supermarkets, Health Food Stores, Wholesale |
| Companies Covered | Blue Diamond Growers, Olam Group, Archer Daniels Midland Company, John B. Sanfilippo & Son, Hormel Foods, Barry Callebaut, The Wonderful Company, Mariani Nut Company, Select Harvests Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuts and Nutmeals Market Evolving Landscape
Processing technology and regulatory frameworks are compressing traditional supply timelines while fragmenting procurement patterns across multiple origin markets and certification tiers.
Optical sorting integrated with AI-driven defect detection is unifying quality grading across almond, cashew, and hazelnut streams. European confectionery manufacturers and plant-based dairy startups adopt these systems at replacement cycle pace. The technology is unifying previously separate premium and standard tier supply pools into continuous quality spectrums.
REACH registration requirements for processed nutmeal imports into the European Union tighten contaminant thresholds and documentation burdens. Nut processors serving bakery and nutraceutical formulators face reformulation costs and testing protocol investments. Almond meal and hydrolyzed protein concentrates encounter the steepest compliance ramps as novel food dossier preparation extends lead times.
Ingredient buyers are consolidating supplier rosters while demanding origin traceability down to orchard block and harvest date. Food manufacturers reduce approved vendor lists from twelve to four qualified sources per nut category. This concentration is most visible in German and Dutch processing hubs where private-label nut butter and dairy-alternative contracts specify single-origin documentation.
Nuts and Nutmeals Market Segmentation
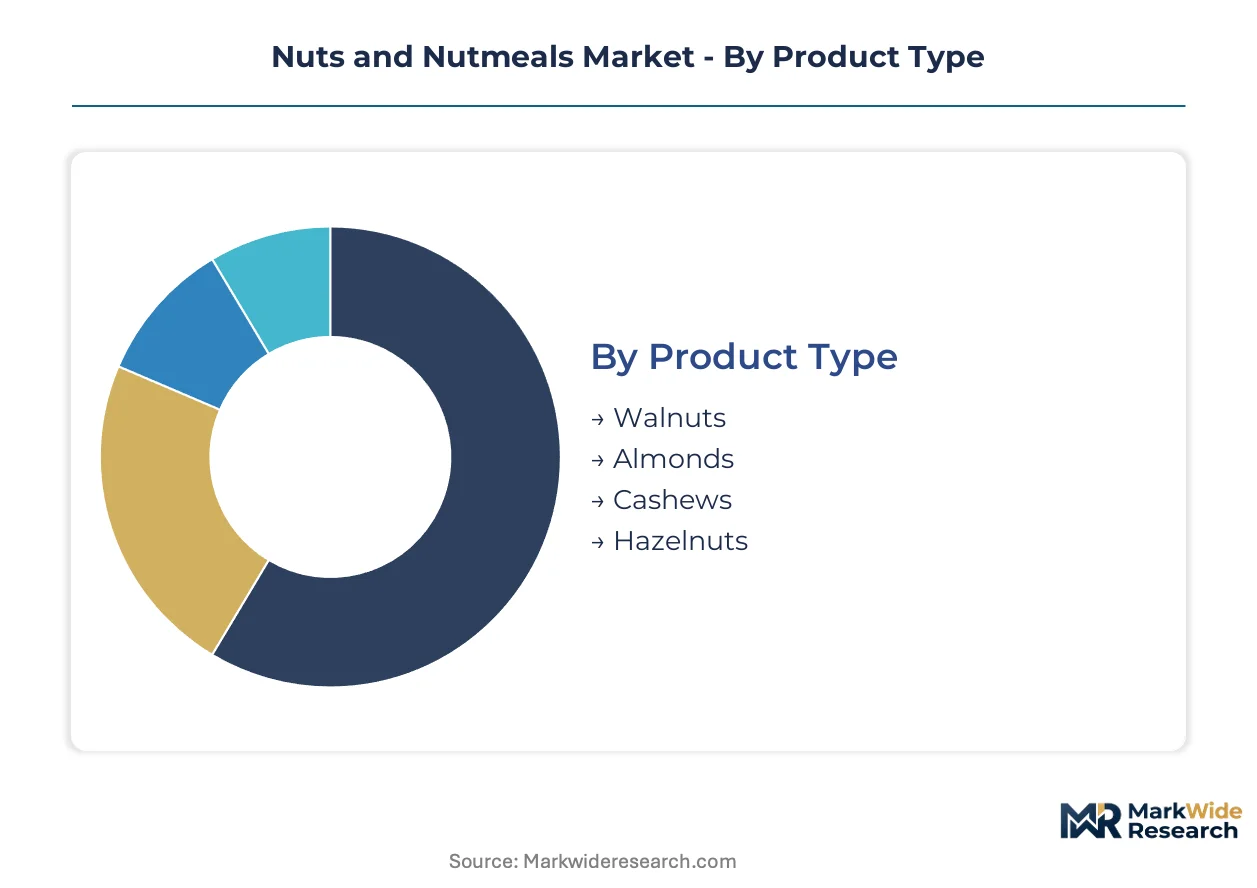
Nut processors configure production lines around certification tiers and end-use specifications. FDA food safety modernization rules and EU REACH requirements segment compliance costs unevenly across product formats, with ground nutmeals facing steeper documentation burdens than whole nuts.
Product Type:
Almonds and cashews carry the heaviest certification load for plant-based dairy applications, while walnuts and hazelnuts navigate distinct allergen labeling and novel food assessment pathways.
- Almonds:California's Central Valley orchards supply kernels with protein content near 21% and oil content approaching 54%, specifications that match beverage base requirements. Dairy-alternative manufacturers in Germany and the Netherlands specify pasteurized blanched forms with aflatoxin documentation meeting EFSA thresholds.
- Cashews:Indian and Vietnamese processors dominate raw kernel supply, with fat content ranging 46-48% enabling creamy texture profiles in premium beverage formulations. Clean-label positioning in North American retail chains favors steam-pasteurized over oil-roasted treatments.
- Walnuts:Omega-3 fatty acid concentrations near 2.5 grams per ounce drive bakery inclusion and nutraceutical extraction demand. California and Chilean origins compete on shell-free yield metrics.
- Hazelnuts:Turkish Black Sea region orchards supply confectionery-grade kernels with tight moisture specifications for chocolate praline applications. Italian processors specify calibrated sizing for automated enrobing lines.
Leading the category by volume: Almonds. Growing fastest: Cashews.
Form:
Processing intensity separates margin tiers, with ground forms commanding equipment investment for particle size uniformity while whole nuts retain value through sorting automation.
- Whole:Premium gift and seasonal segments specify intact kernels with zero surface blemish tolerance. Optical grading systems at Blue Diamond and Olam facilities separate jumbo sizing for Chinese New Year and Diwali packaging.
- Sliced:Bakery inclusion demand drives thickness calibration to 1.2-1.8mm for even browning in croissant laminations. Almond slices dominate commercial volumes for granola and cereal applications.
- Chopped:Ice cream and confectionery inclusions specify 4-6mm granulation for texture contrast without hardness perception. Cross-contamination protocols demand dedicated chopping lines for peanut-free facilities.
- Ground:Gluten-free flour substitution and protein fortification applications require 200-mesh fineness for suspension stability in batters. REACH registration for almond meal imports into the European Union extends lead times versus whole kernel shipments.
Highest volume concentration: Whole. Steepest expansion trajectory: Ground.
Packaging Type:
Channel destination determines barrier specifications, with retail-facing formats requiring oxygen scavenging and industrial bulk emphasizing throughput economics.
- Bags:Stand-up pouches with resealable zippers and nitrogen flush dominate snack nut retail in North American supermarkets. High-definition printing capabilities enable seasonal promotional versioning.
- Jars:Peanut butter and almond butter premium positioning relies on PET or glass clarity for visual texture confirmation. Tamper-evident induction sealing satisfies FDA food defense guidelines.
- Boxes:Gift assortments specify rigid board construction with partition inserts preventing kernel-to-kernel abrasion. European chocolate-nut combinations require humidity-controlled inner barriers.
- Bulk:Foodservice and manufacturing channels accept 25kg multi-wall paper sacks or 1000kg flexible intermediate bulk containers. Fumigation documentation for ocean container shipments adds compliance layers absent in retail formats.
Dominant by throughput: Bulk. Gaining share fastest: Bags.
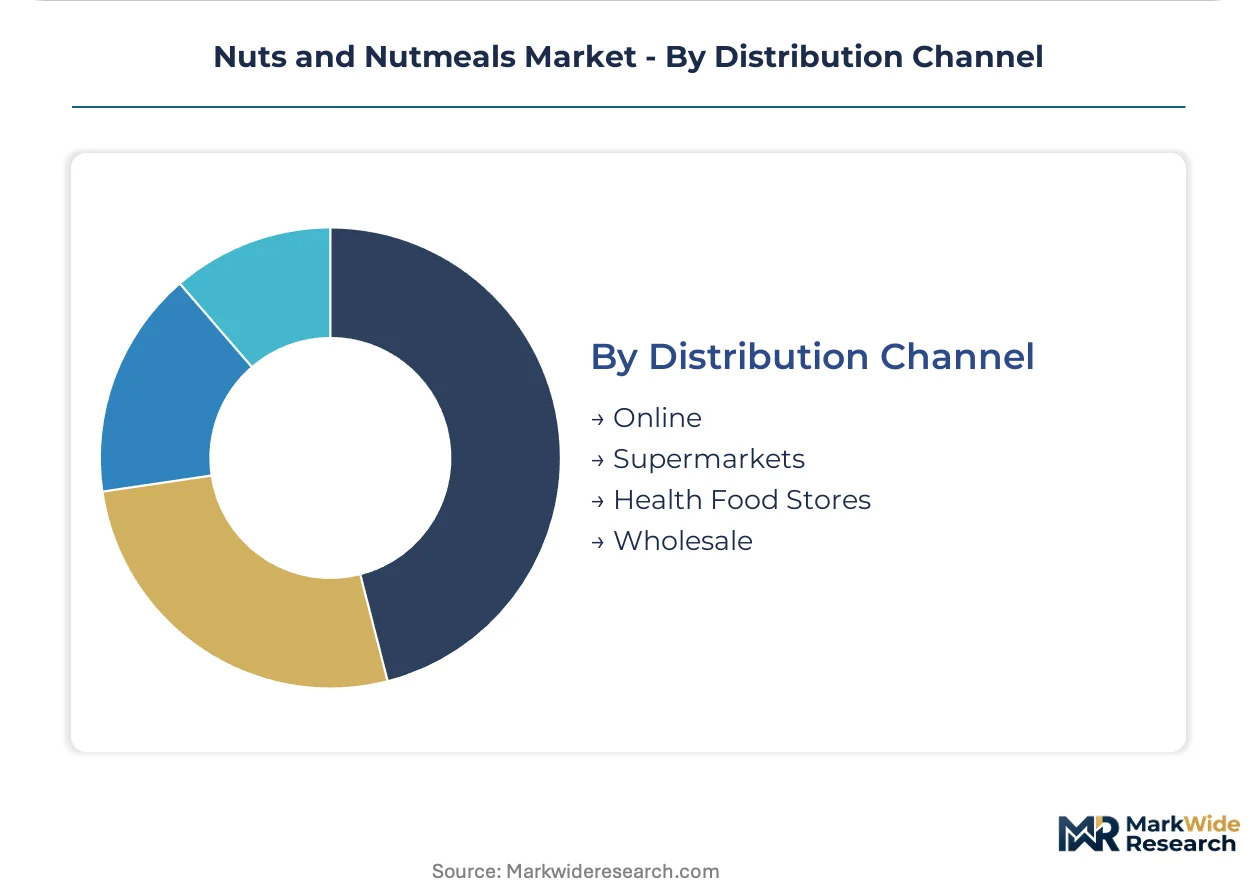
Distribution Channel:
Customer scale and order frequency fragment logistics requirements, with wholesale and online channels imposing opposite handling specifications on the same SKU base.
- Online:Direct-to-consumer fulfillment demands individual unit corrugated protection and parcel carrier dimensional weight optimization. Amazon and specialty nut retailers specify lot code traceability for recall readiness.
- Supermarkets:Slotting fees and promotional calendar alignment concentrate volume in national chain buyers. Private-label programs at Kroger and Albertsons require identical specification sheets across multiple co-manufacturers.
- Health Food Stores:Organic and raw positioning commands smaller case packs and bilingual labeling for independent retailers. Regional distributors like United Natural Foods consolidate fragmented demand.
- Wholesale:Restaurant supply and bakery manufacturing buyers negotiate annual contracts with origin documentation and crop year specifications. Sysco and US Foods specify pallet configuration for automated warehouse retrieval.
Largest volume channel: Wholesale. Expanding most quickly: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley special agricultural zones concentrate over three-quarters of global almond output, driving tax-incentive-driven processing infrastructure expansion across Sacramento, Fresno, and Kern counties.
United States
Plant-based dairy startups in California and Oregon accelerate almond and cashew procurement for beverage formulations. FDA food safety modernization rules mandate hazard analysis plans for all nut processors. Sacramento Valley hulling and shelling facilities expand controlled-atmosphere storage capacity to meet EU export cold-chain requirements.
Germany
Confectionery manufacturers in Hamburg and Cologne drive hazelnut and almond demand for praline and chocolate applications. EU REACH registration requirements tighten contaminant thresholds for imported nutmeal ingredients. The Port of Hamburg anchors continental distribution, with warehouse operators investing in optical sorting systems for quality grading.
India
FSSAI fortification mandates in mid-day meal programs institutionalize groundnut and almond meal procurement for bakery standards. The Food Safety and Standards Authority of India enforces aflatoxin limits on imported cashew kernels. Gujarat's Kutch district processing clusters expand steam-pasteurization capacity for clean-label export contracts.
Australia
Riverina and Sunraysia plantings offer counter-seasonal almond supply with reduced water risk versus California origins. The country's national agricultural regulator enforces biosecurity protocols for bee pollination services. Mildura-based processors invest in bulk ingredient platforms targeting direct-to-manufacturer channels across Southeast Asia.
Vietnam
Raw cashew kernel processing dominates export revenue, with fat content specifications matching premium beverage texture requirements. The Ministry of Agriculture and Rural Development enforces residue limits for export-bound consignments. Binh Phuoc province processing clusters upgrade from manual shelling to automated steam-cooking lines.
Nuts and Nutmeals Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement, processing, and distribution tiers. The vendor base organizes around three strategic archetypes: cooperative structures securing long-term supply contracts, multinational traders anchoring multi-origin procurement networks, and integrated processors controlling bulk ingredient channels. Competitive moves concentrate on backward integration into orchard assets and direct-to-manufacturer platform development.
Within the cooperative archetype, Blue Diamond Growers exemplifies member-owned supply security. Olam Group and Archer Daniels Midland Company occupy positions as diversified agribusiness traders with multi-commodity logistics infrastructure. These three entities represent distinct approaches to managing California supply concentration risk and European regulatory compliance burdens.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| Olam Group |
| Archer Daniels Midland Company |
| John B. Sanfilippo & Son |
| Hormel Foods |
| Barry Callebaut |
| The Wonderful Company |
| Mariani Nut Company |
| Select Harvests Limited |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap processors in California's Central Valley and Australia's Riverina basin anchor supply discipline through multi-generational orchard holdings, insulating spot-market volatility while compressing margin capture for traders lacking captive kernel supply.
Pricing Analysis
Premium pricing attaches to short lead-time contracts for pasteurized blanched almond forms destined for European dairy-alternative manufacturers, while spot inventory of standard-grade kernels trades at discounts reflecting aflatoxin retest burdens. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and origin documentation depth. Cost compression in economy-tier ground nutmeals is intensifying because REACH registration fees concentrate compliance burdens on smaller meal exporters. Industrial bakery buyers exhibit highest price sensitivity, while German confectionery houses prioritize specification adherence over unit cost.
Supply Chain Analysis
India's FSSAI fortification mandates and the EU F-Gas Regulation are reshaping sourcing patterns by demanding domestic-content verification for institutional procurement and cold-chain infrastructure localization. Geographic supply concentrates in California, Vietnam, and Turkey, with raw material flows drawing from bee pollination services, steam-cooking equipment, and controlled-atmosphere storage vessels. Single-source vulnerability runs through California's Central Valley water allocation. Distribution runs through Port of Hamburg consolidation for European formulation customers and direct-to-manufacturer platforms bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into orchard assets and captive processing infrastructure defines competitive positioning, with players racing to lock in kernel supply ahead of climate-driven yield volatility.
For Market Incumbents: Anchor procurement networks across Australian and Mediterranean origins to dilute California concentration exposure. Invest in optical sorting automation to unify quality grading across premium and standard tier supply pools. Precision fermentation convergence threatens traditional protein extraction margins, demanding R&D allocation to hybrid biomass blends. For New Entrants and Emerging Players: Launch via direct-to-manufacturer bulk ingredient platforms targeting Southeast Asian plant-based dairy startups. Australian almond expansion offers the most penetrable geography, with Riverina plantings providing counter-seasonal supply and reduced water risk versus California origins. Clean-label steam-pasteurization capabilities differentiate against oil-roasted incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor cooperative-structured processors with member-locked supply contracts in California's Sacramento Valley. Long-term viability hinges on water-rights security and pollination service access across the analysis window. Watch hive availability pricing as the inflection signal for almond production cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Captive supply from California and Australian plantings secures kernel access ahead of climate shocks. |
| Cold-Chain Infrastructure Expansion | Controlled-atmosphere storage capacity satisfies EU F-Gas Regulation compliance for export-bound consignments. |
| Optical Sorting Technology Deployment | AI-driven defect detection unifies quality grading across almond, cashew, and hazelnut processing streams. |
| Direct-to-Manufacturer Platform Launch | Bulk ingredient channels bypass wholesale tiers, capturing margin compression in industrial nutmeal sales. |
| Precision Fermentation R&D Partnership | Hybrid nut-protein and microbial biomass blends target complete amino acid profiles for sports nutrition. |
Research Methodology
Multi-period observation of almond orchard yields, bee colony rental pricing, and EU import certification timelines anchored the trend analysis, supplemented by interviews with hulling facility operators, procurement leads at German confectionery manufacturers, and FSSAI compliance officers. Secondary validation drew from USDA crop production reports, EFSA novel food assessment databases, Australian Bureau of Agricultural statistics, and customs records for processed nutmeal trade flows. Bottom-up kernel volume estimates triangulated against top-down market value reconstructions.
Input-output matrices mapped almond protein content specifications to dairy-alternative formulation demand across product type, form, packaging format, and distribution channel dimensions throughout the forecast period. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated water scarcity indices for California's Central Valley and FSSAI fortification mandate implementation trajectories.
The model assumes a particular technology adoption path for optical sorting and precision fermentation; alternative pathways for AI-driven quality grading would alter the outlook for processor capital allocation. Forecasts reflect documented assumptions regarding pollination service availability and REACH registration burden stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Macadamia Butter Market
Nuts and Seeds
Soy Nut Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Fox Nuts Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Asia-Pacific Hazelnut Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
North America Hazelnut Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
Macadamia Nut Market
Nuts and Seeds
Middle East and Africa Hazelnut Market