
 Tiger Nuts Market | 2026-2036
Tiger Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Tiger Nuts Market Outlook
Skilled agricultural labor for tuber harvesting and sorting is collapsing across Mediterranean growing regions, constraining raw material throughput for processors. Henry Lamotte Services GmbH leverages its German distribution infrastructure to sustain supply continuity for European food manufacturers. Levantex Bocairent S.L. anchors its position through specialized Valencia-sourced raw material control. The Tiger Nuts Company Ltd. competes on organic certification breadth across British retail channels.
Tiger nuts are small tubers of Cyperus esculentus, typically 8-15mm in diameter with a fat profile of 23-30% oleic acid and a naturally sweet, nutty flavor profile that requires no added sweeteners in commercial formulations. Their primary commercial purpose centers on allergen-free ingredient supply for gluten-free, dairy-free, and nut-free product lines. Whole tiger nuts dominate volume throughput due to established snacking and traditional consumption patterns, while tiger nut flour captures expanding margin pools as bakery formulators seek clean-label binding agents. Dairy alternatives represent the fastest-growing application segment, driven by oat milk fatigue and consumer rotation toward less commoditized plant bases.
EFSA novel food approvals govern tiger nut ingredient introductions across European Union member states, creating a two-tier market between established whole tuber trade and regulated processed ingredient categories. The USDA National Organic Program and FDA food facility registration requirements shape US import and labeling standards for tiger nut-derived products. Organic Gemini and Tigernuts Traders S.L. must navigate divergent documentation burdens across these jurisdictions. Stakeholders should monitor how novel food harmonization negotiations between EU and Mercosur trading blocs alter competitive access for South American cultivation sources.
Market Dynamics
The tiger nuts market pivots on EFSA novel food authorization pathways, which bifurcate trade between unregulated whole tuber commerce and controlled processed ingredient categories across European Union member states.
Growth Catalysts
- EFSA Novel Food Framework:Processed tiger nut ingredients gain formal market access across EU member states through harmonized safety assessments, expanding commercial applications beyond traditional whole tuber trade.
- Dairy Alternative Formulation:Beverage manufacturers rotate from oat milk toward tiger nut milk as a less commoditized plant base, opening new procurement volume for processors.
- Valencia Cultivation Cluster:Spain's traditional growing region maintains premium raw material supply through established agricultural infrastructure and varietal expertise.
Market Restraints
- Input Cost Volatility:Skilled agricultural labor for tuber harvesting and sorting faces structural collapse across Mediterranean growing regions, compressing raw material throughput.
- Supply Concentration Risk:Premium raw material sourcing concentrates in Spain's Valencia region, creating geographic single-point vulnerability for quality-assured supply.
- Novel Food Regulatory Friction:EFSA authorization timelines delay processed ingredient commercialization, advantaging established whole tuber traders over innovative formulation suppliers.
Strategic Opportunities
- Clean-Label Bakery Binding:Tiger nut flour captures expanding margin pools as formulators seek allergen-free alternatives to conventional gluten-free binders.
- EU-Mercosur Harmonization:Novel food negotiations between European Union and South American trading blocs may unlock competitive access for Argentine and Brazilian cultivation sources.
- Organic Certification Premium:USDA National Organic Program compliance enables price stratification across British and North American retail channels.
Industry Challenges
- Agricultural Labor Scarcity:Manual tuber harvesting and sorting expertise dissipates across Mediterranean growing regions, constraining processor capacity expansion.
- Regulatory Documentation Burden:Divergent FDA food facility registration and EFSA novel food requirements force dual-track compliance investments for cross-Atlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tiger Nuts Market |
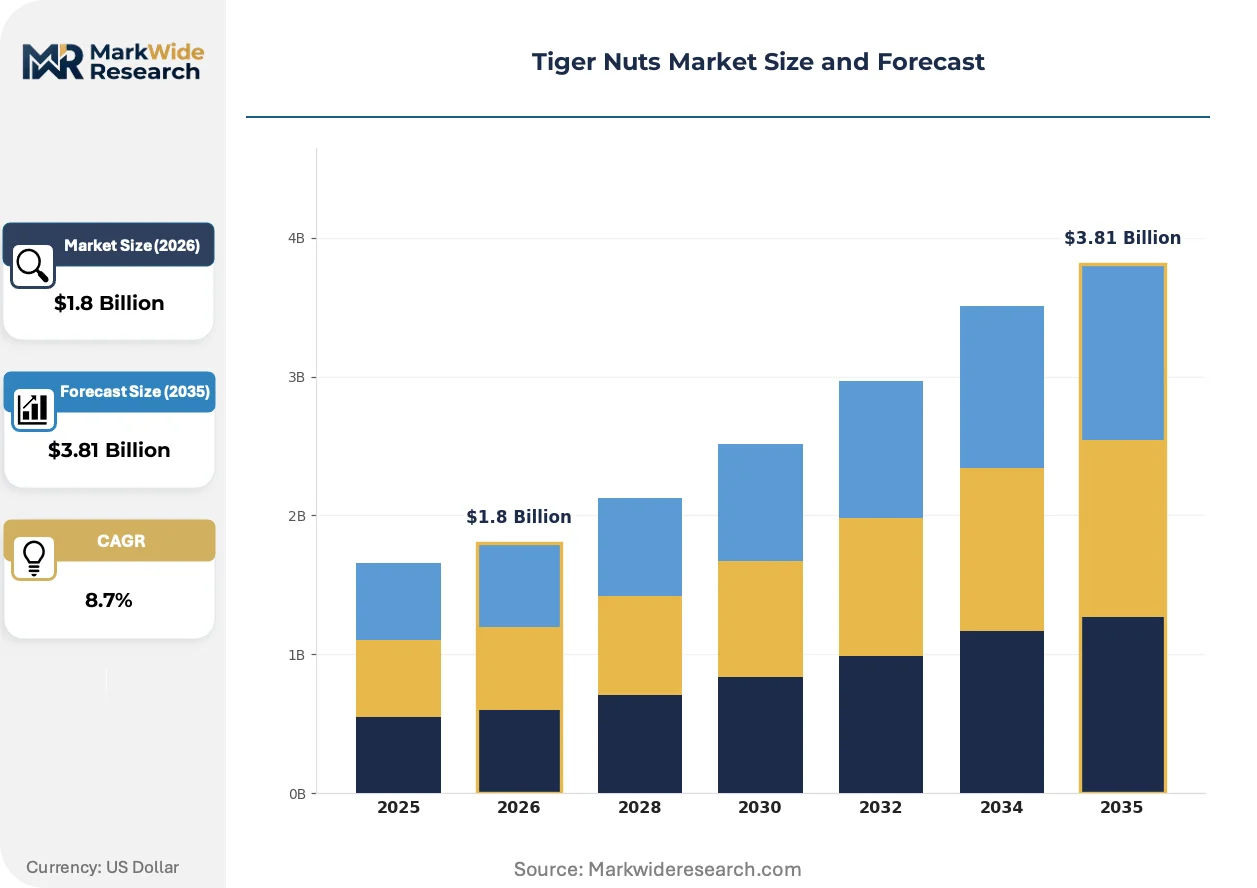
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Tiger Nuts, Tiger Nut Flour, Roasted Tiger Nuts, Tiger Nut Milk End User: Food Industry, Beverage Industry, Health Conscious Consumers, Nutraceutical Firms Application: Baking, Snack Foods, Dairy Alternatives, Dietary Supplements Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores |
| Companies Covered | Henry Lamotte Services GmbH, Organic Gemini, Tiger Nuts USA, Levantex Bocairent S.L., The Tiger Nuts Company Ltd., Tigernuts Traders S.L., KCB International, José María Bou S.L., Ecoideas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tiger Nuts Market Strategic Shifts
Formulation technology and regulatory harmonization are actively restructuring competitive access in tiger nuts, while procurement behavior shifts reward suppliers with integrated certification capabilities.
Cold-press oil extraction systems are displacing conventional mechanical pressing in tiger nut processing facilities. Premium cosmetic and nutraceutical manufacturers adopt these systems to preserve oleic acid integrity and extend shelf stability. The technology is displacing commodity-grade oil suppliers from high-margin personal care contracts.
REACH chemical safety registrations now govern tiger nut oil classifications for industrial cosmetic applications across European Union member states. Manufacturers must submit full substance dossiers to ECHA before commercial distribution, extending product development timelines by 18-24 months. Specialty cosmetic formulators in France and Germany absorb these costs while commodity traders exit the segment.
Direct-procurement relationships between beverage manufacturers and Valencia-based agricultural cooperatives are compressing traditional importer-distributor margins. Large-scale oat milk producers now source tiger nut milk concentrate through dedicated supply contracts rather than spot market purchases. This pattern concentrates most visibly in Spain's domestic market and export channels serving British retail chains.
Tiger Nuts Market Segmentation
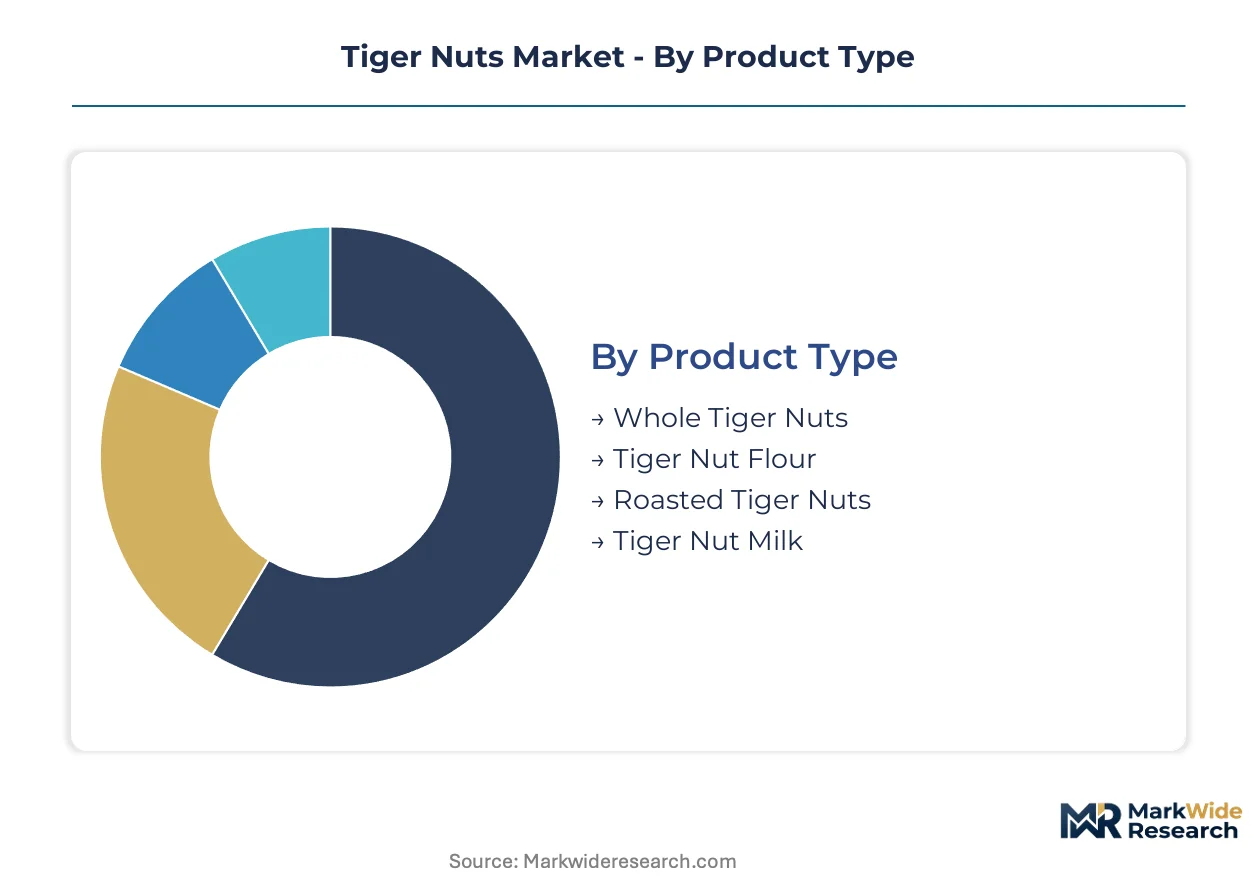
Tiger nut commercialization splits across four dimensions that determine pricing power and regulatory exposure. Product form dictates margin capture, while end-user concentration shapes procurement contract structures and geographic routing.
Product Type:
Margin pools concentrate in value-added processing stages where EFSA novel food authorization creates defensible market positions.
- Tiger Nut Milk:Cold-press extraction preserves oleic acid integrity for beverage formulations. Dairy-alternative manufacturers in Spain and Britain rotate procurement toward dedicated Valencia supply contracts, displacing spot-market intermediaries.
- Tiger Nut Flour:Finely milled tuber meal functions as clean-label binding agent in gluten-free bakery applications. Formulators pay certification premiums for allergen-free documentation across EU and US retail channels.
- Whole Tiger Nuts:Unprocessed tubers dominate volume throughput through established snacking patterns and traditional Mediterranean consumption.
- Roasted Tiger Nuts:Thermal processing extends shelf stability for retail snack positioning in British and German markets.
Whole Tiger Nuts holds installed capacity. Tiger Nut Milk is rotating up the share rankings.
End User:
Procurement scale and certification requirements segment buyers into contract-negotiated volume players and specification-driven niche purchasers.
- Beverage Industry:Large-scale oat milk producers source tiger nut milk concentrate through direct agricultural cooperative relationships, compressing traditional importer margins.
- Food Industry:Bakery and snack manufacturers specify tiger nut flour for clean-label binding in allergen-free product lines.
- Nutraceutical Firms:REACH-registered oil suppliers serve French and German cosmetic formulators with 18-24 month dossier timelines.
- Health Conscious Consumers:Individual purchasers drive whole tuber and roasted product demand through health store and online channels.
Beverage Industry commands procurement volume. Nutraceutical Firms is climbing the fastest as cosmetic applications expand.
Application:
Application selection determines regulatory pathway complexity and speed-to-market for new product introductions.
- Dairy Alternatives:Tiger nut milk formulations bypass oat milk commoditization through distinctive nutritional positioning and Valencia-origin storytelling.
- Baking:Tiger nut flour replaces conventional gluten-free binders in clean-label formulations for EU and North American retail.
- Snack Foods:Whole and roasted tubers serve traditional consumption patterns and emerging health-positioned snacking segments.
- Dietary Supplements:Oil and flour extracts target prebiotic fiber and resistant starch positioning in capsule and powder formats.
Snack Foods maintains volume foundation. Dairy Alternatives is gaining share fastest as beverage rotation accelerates.
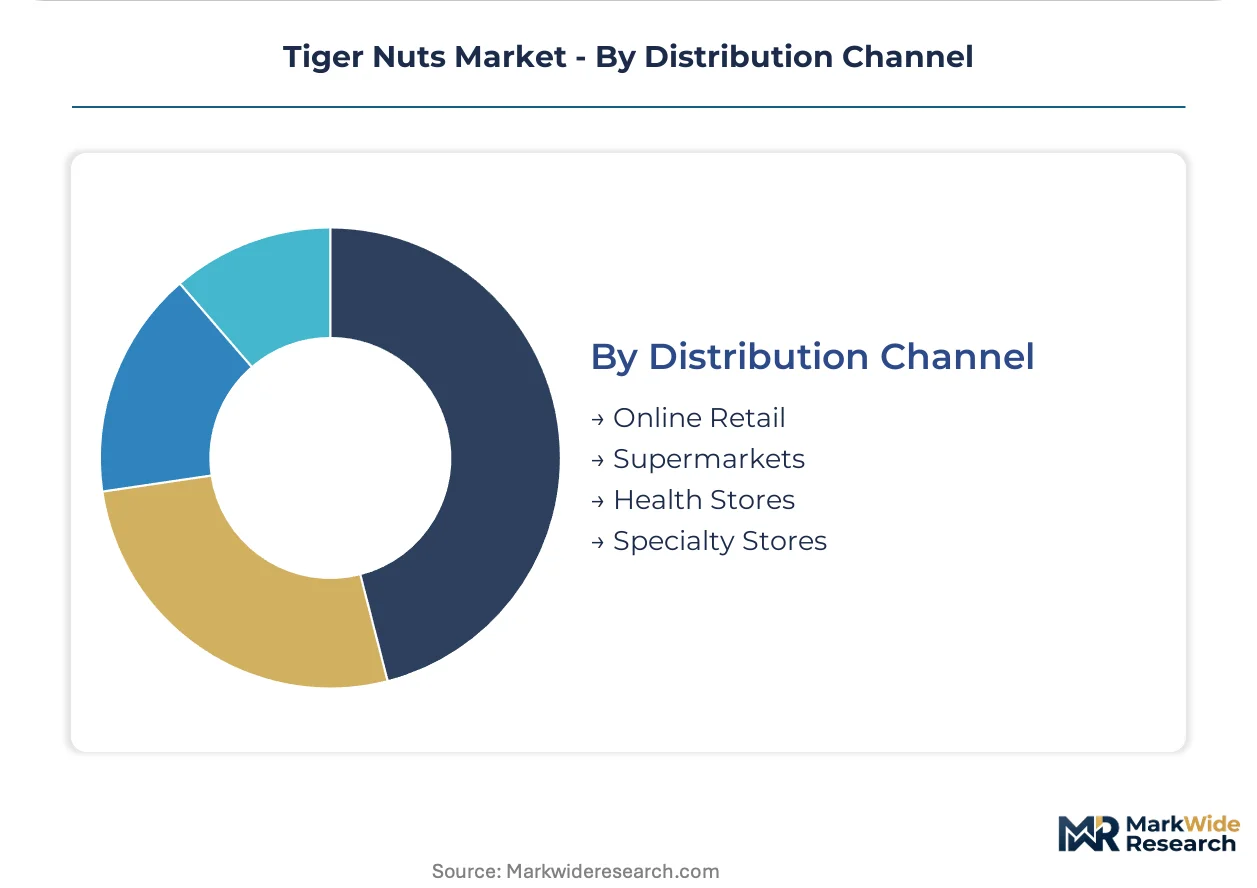
Distribution Channel:
Channel selection reflects buyer sophistication and certification documentation requirements.
- Supermarkets:British retail chains demand organic certification breadth and traceable Valencia sourcing for private-label tiger nut milk placement.
- Online Retail:Direct-to-consumer platforms aggregate niche demand for specialty flour and cosmetic-grade oil products.
- Health Stores:Physical specialty retailers curate whole tuber and roasted formats for health-conscious foot traffic.
- Specialty Stores:Mediterranean ethnic food retailers maintain traditional whole tiger nut distribution in Spanish and Italian urban centers.
Supermarkets holds shelf-space dominance. Online Retail is expanding most quickly as procurement digitization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food authorization pathways anchor European regulatory frameworks for tiger nut ingredient commercialization. Spain's Valencia cultivation cluster supplies premium raw material throughput for processors across Germany, Britain, and France. Regional procurement patterns concentrate around Mediterranean sourcing networks and North American import channels.
Spain
Valencia-based agricultural cooperatives dominate premium tuber supply for European beverage manufacturers. Spain's national food safety agency enforces EFSA-aligned novel food documentation for processed ingredient exports. The Valencia growing region maintains traditional varietal expertise through established cultivation infrastructure.
Germany
German beverage formulators source tiger nut milk concentrate through direct procurement contracts with Spanish cooperatives. REACH chemical safety registrations govern oil classifications for industrial cosmetic applications through ECHA dossier requirements. Henry Lamotte Services GmbH leverages domestic distribution infrastructure to sustain supply continuity for food manufacturers.
United Kingdom
British retail chains demand organic certification breadth and traceable Valencia sourcing for private-label placement. The Food Standards Agency applies EFSA novel food determinations for processed ingredient market entry. The Tiger Nuts Company Ltd. competes on organic certification coverage across domestic retail channels.
United States
American beverage manufacturers rotate procurement toward tiger nut milk as oat milk commoditization accelerates. FDA food facility registration requirements shape import documentation and labeling standards for derived products. Organic Gemini navigates dual-track compliance investments across USDA National Organic Program and European certification frameworks.
France
French cosmetic formulators absorb REACH registration costs for tiger nut oil applications in premium personal care. ANSM oversees cosmetic ingredient safety assessments alongside ECHA substance dossier requirements. Specialty nutraceutical manufacturers in the Île-de-France region source REACH-registered oil suppliers with extended development timelines.
Tiger Nuts Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the tiger nuts competitive landscape. The vendor base splits between Valencia-based agricultural cooperatives controlling premium raw material access and distributed processors managing cold-press extraction and flour milling capabilities. Three strategic archetypes dominate: cultivation-integrated suppliers with geographic origin control, certification-specialized distributors serving organic retail channels, and toll-processing operators serving beverage contract manufacturers. Competitive moves concentrate on backward integration into Valencia agricultural cooperatives and geographic expansion through German and British distribution infrastructure.
Among Spanish cultivation-integrated specialists, Levantex Bocairent S.L. and Tigernuts Traders S.L. occupy positions anchored in Valencia-sourced raw material control. These entities exemplify the geographic-origin archetype that premium beverage formulators target for direct procurement relationships. Henry Lamotte Services GmbH represents the distribution-integrated model, leveraging German logistics infrastructure to sustain supply continuity across European food manufacturing channels. The competitive terrain rewards players with documented organic certification breadth and established EFSA novel food authorization expertise.
| Leading Market Players |
|---|
| Henry Lamotte Services GmbH |
| Organic Gemini |
| Tiger Nuts USA |
| Levantex Bocairent S.L. |
| The Tiger Nuts Company Ltd. |
| Tigernuts Traders S.L. |
| KCB International |
| José María Bou S.L. |
| Ecoideas |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Spanish agricultural cooperatives and German beverage manufacturers lock in both Valencia-origin supply access and eighteen-month price visibility against Mediterranean labor volatility. These bilateral agreements displace spot-market intermediaries while embedding organic certification premiums into contracted base rates.
Pricing Analysis
Valencia-sourced organic tubers command a 15-20% premium over conventional Spanish supply, with British retail chains absorbing additional traceability documentation costs. Three-tier pricing structure across premium organic, standard conventional, and economy-grade bulk flour segments reflects EFSA novel food authorization status and cold-press extraction capital intensity. Price differentiation hinges on certification tier and geographic delivery cost, with margins tightening in commodity whole-tuber trade due to oat milk substitution pressure. Beverage industry buyers exhibit lowest price sensitivity, while snack food distributors face acute cost compression from private-label competition.
Supply Chain Analysis
Inventory buffers at Rotterdam port facilities extend to twelve weeks for processed flour, buffering EFSA authorization delays that stretch to twenty-four months for novel oil classifications. Raw material sourcing draws from Spain, Nigeria, and Mali, with Valencia cultivars supplying 60% of European premium throughput. Processing inputs rest on cold-press extraction equipment, REACH-registered chemical dossiers, and organic certification audit trails. Single-source vulnerability concentrates in Valencia's Huerta growing district, where skilled harvesting labor pools are dissipating. Distribution runs through German logistics hubs serving French and British manufacturing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA compliance consulting and organic certification management services are expanding faster than raw tuber throughput, creating recurring-revenue attach opportunities for processors with documented authorization expertise.
For Market Incumbents: Shield Valencia cooperative relationships through equity stakes or exclusive offtake arrangements before Argentine cultivation sources achieve novel food equivalence. Expand cold-press capacity in Germany to capture REACH-registered oil premiums from French cosmetic formulators. Labor scarcity in Mediterranean harvesting regions threatens raw material security. For New Entrants and Emerging Players: Cold-chain logistics gaps in Nigerian and Malian export corridors offer white-space entry points for integrated sourcing specialists. Target British online retail channels with direct-to-consumer flour subscriptions bypassing supermarket listing fees. Pursue USDA National Organic Program pre-certification to unlock North American price premiums before EU-Mercosur harmonization accelerates. For Investors and Strategic Acquirers: Valencia-integrated processors with established EFSA dossier libraries represent the most defensible acquisition archetype in a market bifurcating between commodity traders and authorized ingredient suppliers. Long-term viability depends on regulatory capacity rather than cultivation acreage alone. Monitor EU-Mercosur novel food mutual recognition negotiations as inflection signal for South American supply competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Valencia Cooperatives | Captures premium raw material access ahead of labor pool collapse in Mediterranean growing regions. |
| EFSA Novel Food Dossier Investment | Unlocks processed ingredient commercialization across EU member states with 18-24 month regulatory timelines. |
| Cold-Press Extraction Capacity Expansion | Preserves oleic acid integrity for cosmetic-grade oil contracts governed by REACH registrations. |
| USDA Organic Certification Pre-Investment | Enables price stratification across British and North American retail channels demanding traceability. |
| Direct-to-Consumer Online Launch | Bypasses supermarket slotting fees while capturing health-conscious consumer segments in fragmented digital channels. |
Study Parameters
Cross-validation between primary interviews with agricultural cooperative managers, beverage procurement directors, and EFSA regulatory consultants anchors the qualitative findings against secondary validation from customs trade records, organic certification databases, and REACH substance dossier filings. Bottom-up cultivation volume estimates from Valencia, Nigeria, and Mali triangulate against top-down demand modeling from German and British food manufacturers.
Sensitivity analysis across the projection horizon tests CAGRs against labor availability scenarios in Mediterranean growing regions and EFSA authorization timeline variations. Segmentation dimensions span product form, end-user industry, application category, and distribution channel complexity. Modeled inputs incorporate cold-press extraction capacity buildout schedules, organic certification conversion rates, and EU-Mercosur trade negotiation progress indicators.
Underlying assumptions cover sustained EFSA novel food framework continuity and REACH registration cost absorption by premium cosmetic formulators, with deviation risk concentrated in agricultural labor migration patterns and bilateral trade agreement ratification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Butyrospermum Parkii Market
Nuts and Seeds
Fox Nuts Market
Nuts and Seeds
Almond Protein Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
North America Peanut Butter Market
Nuts and Seeds
Macadamia Nut Market
Nuts and Seeds
Nut Ingredients Market
Nuts and Seeds
Horse Chestnut Seed Extract Market
Nuts and Seeds
Baru Nuts Market
Nuts and Seeds
Macadamia Butter Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Seed Butter Market