
 Fruit Kernel Products Market | 2026-2036
Fruit Kernel Products Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Kernel Products Market Foresight
Market Context
Food-grade kernel oil specifications are reorganizing procurement priorities across the value chain. Nutiva Inc. leverages its organic certification infrastructure to command premium shelf positioning in North American retail channels. Marico Limited anchors its South Asian operations through backward integration into mango kernel processing in Maharashtra and Tamil Nadu. NAMASHRAM INDUSTRIES competes on volume scale in solvent-extracted apricot kernel oil for industrial buyers.
Technical Definition and Segment Structure
Fruit kernel products comprise oils, flours, extracts, and bioactive compounds mechanically or chemically derived from the lignocellulosic endocarps and embryos of stone fruits and drupes, typically containing 15-45% lipid content by dry weight depending on species and extraction parameters. These materials serve as functional ingredients in cosmetic emulsions, pharmaceutical excipients, and renewable feedstock applications where virgin petroleum substitutes face sustainability scrutiny. Cold pressing claims the largest value share among extraction methods due to consumer preference for unrefined, nutrient-retentive oils in personal care formulations. Supercritical CO2 extraction is expanding fastest in pharmaceutical-grade amygdalin and tocopherol isolates where residual solvent limits under EMA and FDA monographs create premium pricing tiers. Cosmetics and pharmaceuticals together concentrate margin pools, while biofuel production occupies a commoditized, volume-driven position with thinner unit economics.
Regulatory Frame and Outlook
EMA guidelines on herbal medicinal products, FDA cosmetic labeling requirements under the Modernization of Cosmetics Regulation Act, and REACH Annex XVII restrictions on cyanogenic glycoside content in consumer goods collectively elevate analytical testing burdens for kernel-derived ingredients. BIS certification requirements in India and EFSA novel food opinions on emerging kernel applications further complicate multi-jurisdictional market access strategies. Stakeholders must monitor regulatory divergence between jurisdictions where amygdalin content thresholds differ by an order of magnitude, as compliance investments in one geography may not transfer to another without reformulation.

Market Dynamics
Cold-pressed extraction technology is reorganizing competitive economics by compressing solvent-based processing margins and forcing incumbents to recertify supply chains for cosmetic-grade purity. This shift elevates capital requirements while fragmenting procurement authority between industrial buyers and premium formulators.
Growth Catalysts
- REACH Annex XVII cyanogenic limits:European cosmetic brands are reformulating toward low-amygdalin kernel oils, creating certified supply scarcity that rewards early compliance investments.
- Supercritical CO2 extraction:Pharmaceutical isolators in Switzerland and Germany now specify tocopherol-rich fractions for dermal drug delivery systems, expanding addressable value per ton of raw kernel.
- Maharashtra-Tamil Nadu processing clusters:Backward-integrated oil mills in these Indian states capture mango kernel supply before it reaches commodity auction floors, securing volume for Ayurvedic nutraceutical exporters.
Market Restraints
- Stone fruit harvest volatility:Apricot kernel availability fluctuates with annual frost patterns in Central Asian growing regions, forcing long-term contract buyers to carry inventory risk or pay spot premiums.
- Solvent extraction cost structure:Hexane prices track petrochemical feedstock indices, eroding margin stability for industrial-grade oil producers who lack cold-press diversification.
- Substitution by algae-derived squalane:Cosmetic formulators in South Korea and Japan are piloting fermentation-based emollients that bypass kernel oil supply constraints entirely.
Strategic Opportunities
- Brazilian biofuel blending mandates:ANVISA's evolving stance on non-food agricultural inputs creates regulatory white space for kernel cake conversion to renewable diesel feedstock.
- Direct-to-formulator digital platforms:Specialty oil distributors are bypassing traditional commodity brokers to sell traceable, small-batch kernel oils to indie cosmetic brands via verified e-procurement channels.
- PLI scheme alignment:India's production-linked incentive framework for active pharmaceutical ingredients rewards domestic amygdalin extraction capacity, pulling investment toward integrated kernel processing parks.
Industry Challenges
- Multi-jurisdictional amygdalin testing:Laboratories must maintain separate GC-MS protocols for FDA, EMA, and BIS cyanogenic glycoside thresholds, extending batch release timelines by 3-6 weeks.
- Mechanical pressing equipment lead times:German and Italian cold-press manufacturers quote 14-18 month delivery windows, constraining capacity expansion for qualified organic oil producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Kernel Products Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peach Kernels, Apricot Seeds, Olive Stones, Mango Pits, Cherry Nuts Extraction Method: Cold Pressing, Solvent Extraction, Supercritical CO2, Steam Distillation, Enzymatic Extraction Application: Cosmetics, Pharmaceuticals, Animal Feed, Biofuel Production, Food Flavoring End User: Personal Care Manufacturers, Nutraceutical Firms, Agricultural Feed Companies, Energy Producers, Flavor Houses |
| Companies Covered | Nutiva Inc., Marico Limited, NAMASHRAM INDUSTRIES, Raasi Foods, The Herbs N Spices, Neo Fragrances, PT Agro Restu, India Aroma Oils And Company, Green Enviro Management Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Kernel Products Market Shifts & Advancements
Enzymatic pre-treatment protocols are disrupting conventional mechanical extraction by unlocking higher lipid yields without thermal degradation. These innovations intersect with tightening pharmaceutical purity standards and shifting procurement authority toward sustainability-certified buyers.
Cell-wall degrading enzyme cocktails are decomposing lignocellulosic kernel matrices at ambient temperatures, enabling oil recovery rates above 92% compared to 75-80% for traditional screw pressing. Swiss and French cosmetic laboratories are adopting these biocatalytic systems for premium tocopherol preservation. The technology is decomposing the historical tradeoff between yield and nutrient retention, forcing equipment suppliers to integrate bioreactor modules into standard processing lines.
EMA's 2023 revision to herbal medicinal product guidelines introduced specific monograph requirements for amygdalin content labeling in kernel-derived excipients. This creates analytical testing obligations that favor vertically integrated processors with in-house HPLC capabilities over toll manufacturers. German pharmaceutical contract manufacturers are consolidating supplier bases to three certified kernel oil sources to simplify audit trails.
Certification-driven preference shifts are concentrating purchasing power among buyers who require organic, kosher, and halal credentials simultaneously. Indie beauty brands in California and New York now specify triple-certified apricot kernel oil, displacing conventional grades from premium formulations. This behavior is most visible in direct-to-consumer skincare channels where ingredient storytelling drives conversion rates.
Fruit Kernel Products Market Segmentation
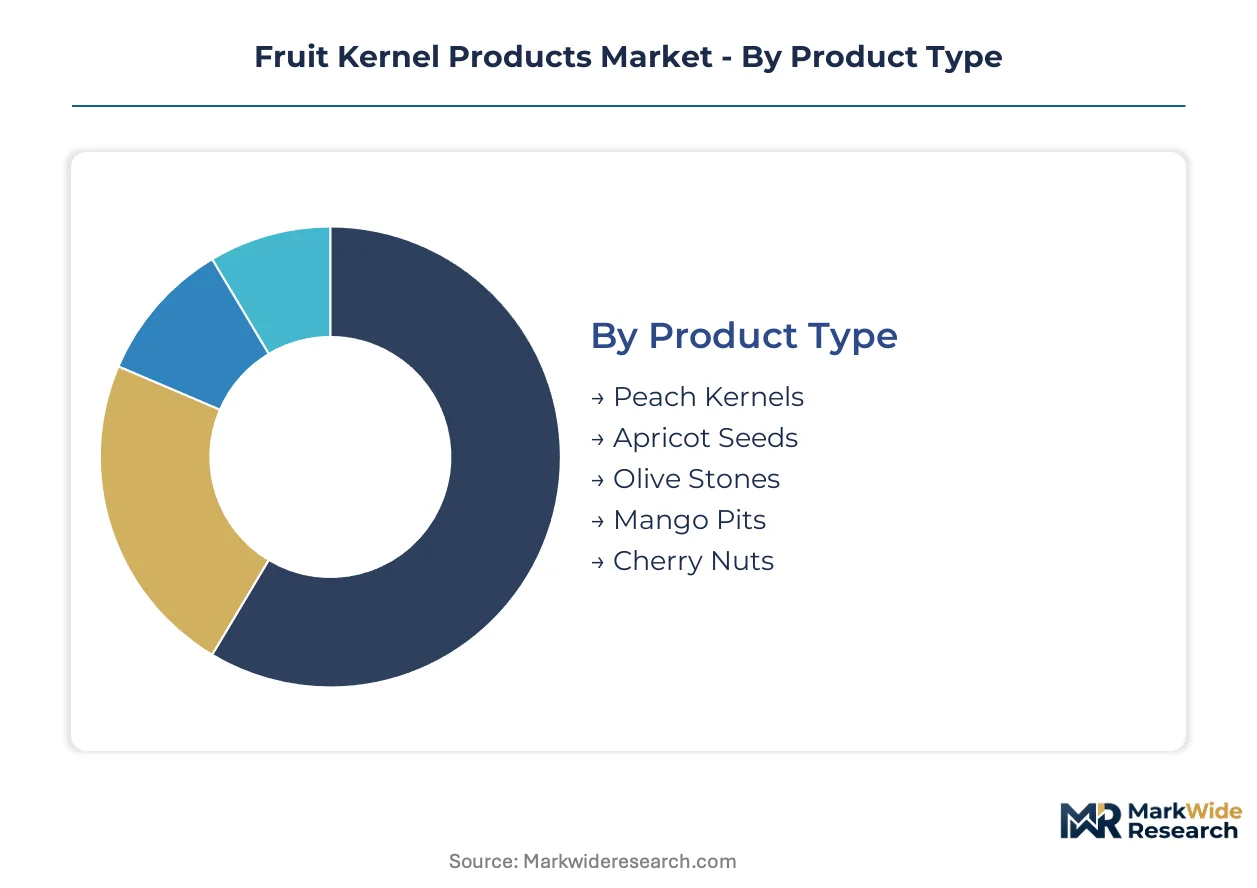
Kernel product differentiation hinges on amygdalin content thresholds and extraction purity grades. Procurement contracts increasingly specify segment-level certifications that fragment supplier bases and elevate testing costs.
Product Type:
Apricot seeds face the most acute substitution pressure from algae-derived squalane in premium cosmetic formulations, while mango pits benefit from captive supply arrangements in Indian processing clusters.
- Apricot Seeds:These kernels contain 20-40% oil by weight with variable amygdalin concentrations that determine pharmaceutical versus cosmetic grade classification. Demand concentrates in Swiss and German pharmaceutical isolators seeking tocopherol-rich fractions for dermal drug delivery systems, constrained by EMA cyanogenic glycoside limits that disqualify high-amygdalin batches from excipient use.
- Mango Pits:Lignocellulosic endocarps yielding 10-15% lipid content through mechanical pressing, favored in Ayurvedic nutraceutical formulations for their stearic acid profile. Maharashtra and Tamil Nadu oil mills capture supply through backward integration before commodity auction floors, securing volume for domestic nutraceutical exporters targeting BIS-certified markets.
- Peach Kernels:Lower amygdalin variants suitable for food-grade oil specifications in European markets.
- Olive Stones:Residual biomass from table olive processing, primarily valorized for biofuel feedstock in Mediterranean energy markets.
- Cherry Nuts:Niche cosmetic ingredient with limited commercial scale due to harvest fragmentation across Central European orchards.
Apricot seeds retain volume leadership; mango pits hold the steepest expansion curve.
Extraction Method:
Cost tier differentiation separates capital-intensive supercritical systems from solvent-based volume operations, with enzymatic pre-treatment disrupting yield-retention tradeoffs.
- Cold Pressing:Mechanical screw extraction at temperatures below 40°C preserves tocopherol and phytosterol integrity for cosmetic applications. California and New York indie beauty brands specify triple-certified organic oils, displacing conventional grades from premium direct-to-consumer channels where ingredient storytelling drives conversion.
- Supercritical CO2:Non-thermal extraction using pressurized carbon dioxide achieves pharmaceutical-grade purity without residual solvents. Swiss and French cosmetic laboratories specify these systems for premium tocopherol preservation, though equipment lead times from German and Italian manufacturers extend 14-18 months.
- Solvent Extraction:Hexane-based processing dominates industrial-grade oil production with thinner unit economics tracking petrochemical feedstock indices.
- Enzymatic Extraction:Cell-wall degrading cocktails unlock lipid yields above 92% at ambient temperatures, decomposing historical yield-retention tradeoffs.
- Steam Distillation:Limited to volatile compound recovery in flavor applications with constrained kernel oil relevance.
Cold pressing commands the revenue concentration; enzymatic methods are expanding most quickly.
Application:
Customer type stratification concentrates margin pools in pharmaceutical and cosmetic channels while biofuel production absorbs commoditized volume.
- Cosmetics:Emollient and carrier oil functions in premium skincare formulations requiring REACH-compliant amygdalin documentation. Formulators in South Korea and Japan pilot fermentation-based alternatives that threaten kernel oil demand in mass-market segments.
- Pharmaceuticals:Excipient and active ingredient applications governed by FDA and EMA monographs with specific cyanogenic glycoside labeling requirements. German contract manufacturers consolidate supplier bases to three certified sources to simplify audit trails under EMA's revised herbal medicinal product guidelines.
- Animal Feed:Defatted kernel cake valorization for protein supplementation in agricultural operations.
- Biofuel Production:Renewable diesel feedstock applications in Brazilian markets where ANVISA's evolving stance on non-food agricultural inputs creates regulatory white space.
- Food Flavoring:Limited amygdalin-exempt applications in traditional confectionery with restricted commercial scale.
Cosmetics retains margin leadership; pharmaceuticals are gaining share fastest.
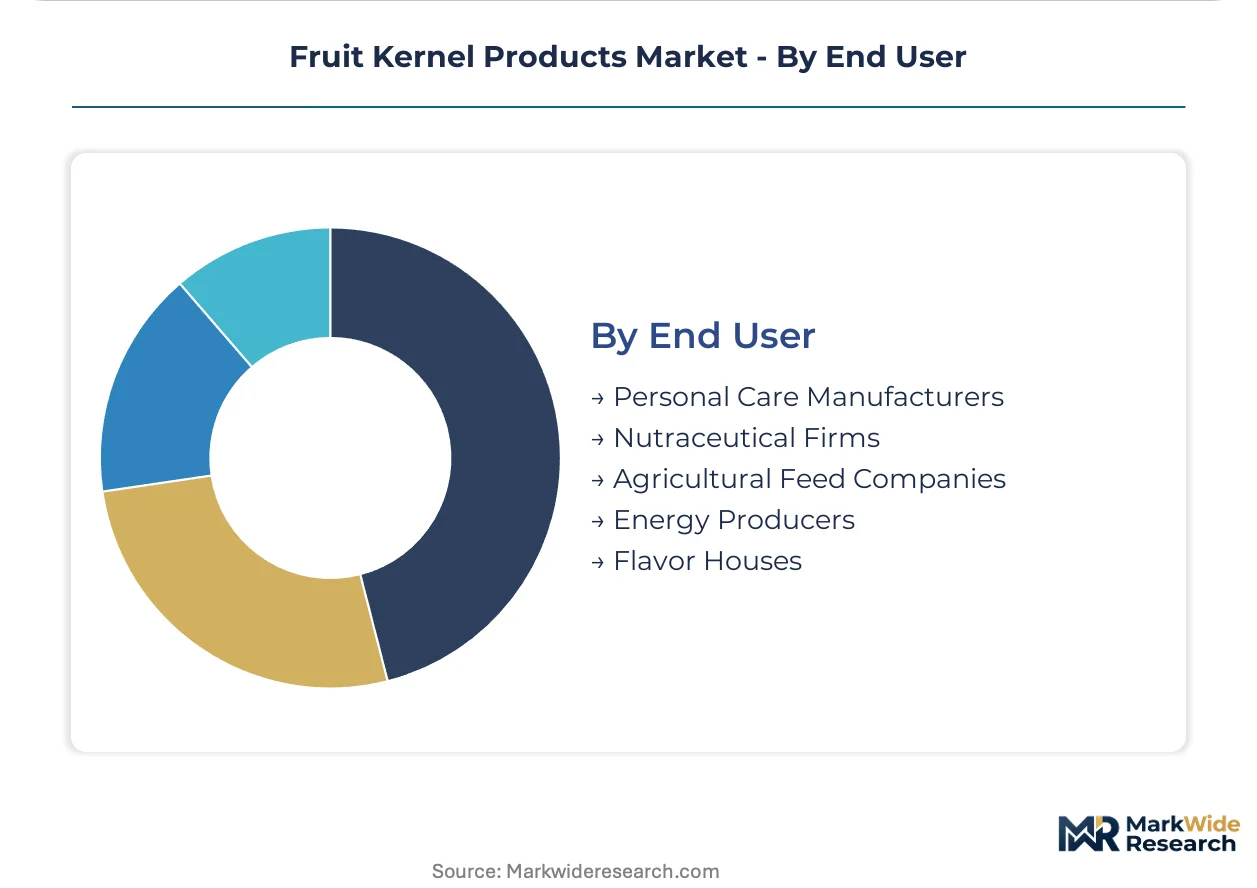
End User:
Supply concentration shapes procurement authority distribution between integrated multinationals and specialty distributors.
- Personal Care Manufacturers:Formulators specifying certified organic, kosher, and halal credentials simultaneously for premium positioning. Direct-to-formulator digital platforms now bypass traditional commodity brokers for traceable small-batch procurement.
- Nutraceutical Firms:Ayurvedic-inspired manufacturers in India sourcing mango and apricot kernel oils for BIS-certified export formulations.
- Agricultural Feed Companies:Volume buyers of defatted kernel cake byproducts with price-sensitive procurement patterns.
- Energy Producers:Biofuel blenders evaluating kernel cake conversion under Brazil's renewable diesel mandates.
- Flavor Houses:Niche demand for steam-distilled volatile compounds with limited kernel oil integration.
Personal care manufacturers anchor value capture; nutraceutical firms show the steepest procurement growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Indian nutraceutical channels absorb price premiums for certified kernel oils, while European cosmetic formulators face the steepest cost elasticity due to REACH compliance investments. Brazilian biofuel blenders operate at the commoditized end with thin margins, creating a demand gradient that rewards geographic arbitrage.
United States
FDA cosmetic labeling requirements under the Modernization of Cosmetics Regulation Act drive reformulation investments among California and New York indie beauty brands. These formulators specify triple-certified apricot kernel oil for direct-to-consumer channels where ingredient storytelling commands shelf price premiums. Cold-pressed oil distributors bypass traditional commodity brokers through verified e-procurement platforms serving traceability-conscious buyers.
Germany
EMA guidelines on herbal medicinal products concentrate pharmaceutical-grade kernel oil demand among Swiss and German contract manufacturers. German pharmaceutical isolators now specify tocopherol-rich fractions for dermal drug delivery systems, expanding value capture per ton of raw material. Equipment lead times from Italian cold-press manufacturers extend 14-18 months, constraining certified organic capacity expansion.
India
BIS certification requirements pull domestic nutraceutical manufacturers toward Maharashtra and Tamil Nadu processing clusters with backward-integrated supply. The PLI scheme for active pharmaceutical ingredients rewards domestic amygdalin extraction capacity, pulling investment toward integrated kernel processing parks. Ayurvedic-inspired exporters source mango kernel oils from captive supply arrangements before commodity auction floors.
Switzerland
Swissmedic oversight of pharmaceutical-grade extracts positions Swiss laboratories at the premium end of tocopherol isolate production. Supercritical CO2 extraction systems achieve pharmaceutical-grade purity without residual solvents, commanding pricing tiers above mechanical pressing. French cosmetic laboratories adjacent to Swiss processing hubs adopt these biocatalytic systems for premium nutrient preservation.
Brazil
ANVISA's evolving stance on non-food agricultural inputs creates regulatory white space for kernel cake conversion to renewable diesel feedstock. Biofuel blending mandates absorb commoditized volume with thinner unit economics than cosmetic or pharmaceutical channels. Kernel cake valorization for protein supplementation competes with agricultural feed applications for defatted byproduct streams.
Fruit Kernel Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with cold-press specialists commanding premium positioning while solvent-based processors compete on volume scale. The market structure fragments across certified organic suppliers, backward-integrated Indian conglomerates, and industrial-scale solvent extractors serving commodity buyers. Two dominant archetypes emerge: certification-heavy premium oil marketers and vertically integrated agricultural processors. Competitive moves concentrate on geographic expansion into processing clusters and portfolio diversification toward pharmaceutical-grade isolates.
Among North American certification specialists, Nutiva Inc. exemplifies the organic-infrastructure archetype leveraging premium shelf positioning. Marico Limited anchors the backward-integrated model through in-house production of mango kernel processing in Indian coastal states. NAMASHRAM INDUSTRIES occupies a position within the volume-driven solvent extraction tier serving industrial-grade buyers. These three representations illustrate the strategic divergence between margin capture through certification authority and scale capture through commodity throughput.
| Leading Market Players |
|---|
| Nutiva Inc. |
| Marico Limited |
| NAMASHRAM INDUSTRIES |
| Raasi Foods |
| The Herbs N Spices |
| Neo Fragrances |
| PT Agro Restu |
| India Aroma Oils And Company |
| Green Enviro Management Systems Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for cold-pressed apricot kernel oil lock in supply access for California indie beauty brands while anchoring price visibility against spot market volatility in Central Asian growing regions. These contractual structures concentrate procurement power among REACH-compliant European cosmetic formulators who can commit to multi-year volumes.
Pricing Analysis
REACH Annex XVII cyanogenic limits dictate the pricing tier structure across European cosmetic channels, separating pharmaceutical-grade isolates from industrial-grade solvent extracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with triple-certified organic oils commanding shelf price premiums in direct-to-consumer channels. Cost compression in solvent-extracted tiers is intensifying because hexane prices track petrochemical feedstock indices. Biofuel blenders in Brazil show highest price sensitivity, while Swiss pharmaceutical isolators accept premium positioning for tocopherol-rich fractions.
Supply Chain Analysis
India and Turkey anchor stone fruit kernel supply, with Maharashtra-Tamil Nadu processing clusters capturing mango kernel before commodity auction floors. Raw material flows draw from Central Asian apricot orchards, Mediterranean olive stone residuals, and Indian mango pit collection networks. Single-source vulnerability concentrates in German and Italian cold-press equipment manufacturers whose 14-18 month delivery windows constrain certified organic capacity expansion. Distribution runs through specialty oil distributors bypassing traditional commodity brokers via verified e-procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among triple-certification-seeking indie beauty brands and backward-integrated Indian nutraceutical exporters, fragmenting procurement authority away from traditional commodity brokers.
For Market Incumbents: Secure captive supply arrangements in Maharashtra and Tamil Nadu processing clusters before mango kernel reaches auction floors. Invest in in-house HPLC capabilities for amygdalin testing to compress batch release timelines against EMA and FDA protocol divergence. Algae-derived squalane substitution in South Korean and Japanese cosmetic channels threatens kernel oil demand in mass-market segments. For New Entrants and Emerging Players: Direct-to-formulator digital platforms represent the most penetrable service-layer gap, where incumbents under-serve traceability-conscious indie cosmetic brands with small-batch procurement needs. Target enzymatic pre-treatment technology licensing to unlock yield advantages above 92% lipid recovery. Lead with sustainability storytelling and verified supply chain documentation as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certification-heavy premium oil marketers with locked pharmaceutical contracts. Long-term viability over the five-to-ten year window favors processors with backward-integrated raw material access and multi-jurisdictional compliance infrastructure. Acquisition target archetype: mid-cap specialists with captive kernel supply and in-house analytical testing capabilities. Watch ANVISA's evolving stance on non-food agricultural inputs in Brazil as the inflection indicator for biofuel feedstock demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kernel Processing | Marico Limited's Maharashtra-Tamil Nadu clusters secure captive supply before commodity auctions. |
| Enzymatic Pre-treatment Technology Licensing | Swiss and French cosmetic laboratories adopt biocatalytic systems for premium tocopherol preservation. |
| Triple Certification Investment | California and New York indie beauty brands specify organic-kosher-halal credentials for premium positioning. |
| Direct-to-Formulator Digital Platform Launch | Specialty oil distributors bypass traditional commodity brokers for traceable small-batch procurement. |
| Pharmaceutical-Grade Amygdalin Extraction Capacity | India's PLI scheme for active pharmaceutical ingredients pulls investment toward integrated processing parks. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings in this study. Conversations with cosmetic formulators, pharmaceutical contract manufacturers, kernel oil mill operators, and specialty distributors informed supply chain and pricing dynamics. Secondary validation drew from EMA herbal medicinal product guidelines, FDA cosmetic labeling requirements under MoCRA, REACH Annex XVII restrictions, BIS certification standards, and ANVISA regulatory white papers. Bottom-up volume modeling triangulated against top-down market sizing across extraction method and application segments.
Sensitivity analysis around amygdalin content thresholds and extraction technology adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, extraction method, application, and end user, with geographic regulatory clusters as a cross-cutting variable. CAGRs were derived from trend extrapolation of certified supply scarcity and substitution dynamics. Industry-specific forecast inputs incorporated enzymatic pre-treatment yield improvements and supercritical CO2 equipment lead time constraints.
Material uncertainties — stone fruit harvest volatility from frost patterns, regulatory divergence in cyanogenic glycoside thresholds, and algae-derived squalane substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about certification-driven preference shifts and backward integration economics. Recalibration cycles align with material shifts in EMA guideline revisions, FDA enforcement patterns, and ANVISA biofuel mandate evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Rubus Fructicosus (Blackberry) Seed Market
Nuts and Seeds
Low Fat Nut Butter Market
Nuts and Seeds
Butyrospermum Parkii Market
Nuts and Seeds
Walnut-Based Spreads Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Hickory Nut Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Packaged Sunflower Seeds Market
Nuts and Seeds
Tree Nuts Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
Almond Market