
 Nut Butters Market | 2026-2036
Nut Butters Market Size, Share, and Industry Trends Forecast 2026-2036
Nut Butters Market Analysis
American peanut processing capacity is decoupling from legacy commodity contracts as specialty roasters and blender-packers build dedicated lines for premium nut butter grades. The J.M. Smucker Company sustains dominant shelf presence through its Jif franchise and controlled distribution into foodservice accounts. Ferrero International leverages its hazelnut procurement network anchored in Turkish orchards to secure cost-advantaged supply for Nutella and adjacent spreads. Nestle SA competes in the organic segment through specialized sourcing partnerships that emphasize traceability claims.
Nut butters are lipid-rich pastes produced by grinding roasted or raw oilseeds and tree nuts to particle sizes typically below 50 microns, with stabilizers or emulsifiers added to prevent oil separation during ambient storage. Industrial formulations serve baking, confectionery, and sauce applications where fat replacement, flavor delivery, and texture modification drive specification. Almond butter commands premium positioning in natural and organic retail sets, while peanut butter anchors volume in snacking and spreading applications. Creamy form dominates manufacturing throughput for foodservice and ingredient channels, though chunky variants retain loyal household penetration. Pouch packaging is gaining traction in on-the-go snacking formats where portion control and resealability shape purchase decisions.
FDA enforces allergen labeling under FALCPA, requiring explicit tree nut and peanut declarations that shape formulation choices and facility segregation protocols. USDA organic certification and Non-GMO Project verification create tiered market access thresholds that retailers increasingly mandate for shelf placement. Stakeholders must monitor evolving EU Green Deal import standards and emerging state-level extended producer responsibility rules for single-serve packaging formats.
Market Dynamics
Clean-label mandates from FDA and USDA are forcing processor investments in segregated allergen-free lines, while protein-forward snacking concentrates demand pull-through in North American fitness channels.
Growth Catalysts
- Protein-Forward Snacking:Fitness and wellness channels in the United States are accelerating category pull-through as consumers prioritize macronutrient density in portable formats.
- FALCPA Enforcement:FDA allergen labeling requirements are reshaping facility segregation protocols and creating competitive moats for processors with certified clean-room capabilities.
- Pouch Packaging Adoption:On-the-go consumption patterns are driving resealable portion-control formats that command shelf space in convenience retail sets.
Market Restraints
- Tree Nut Input Volatility:Almond and hazelnut harvest sensitivity to drought cycles in California and Turkey creates margin compression for premium grade formulations.
- Allergen Facility Segregation Costs:Dedicated line requirements for peanut-free processing impose capital barriers that favor scaled operators over regional blenders.
- Seed Butter Substitution:Sunflower and pumpkin seed spreads are capturing price-sensitive consumers with comparable fat profiles and reduced allergen risk.
Strategic Opportunities
- Extended Producer Responsibility:Emerging state-level rules for single-serve packaging create first-mover advantage for recyclable pouch formats in California and New York.
- EU Green Deal Alignment:Organic certification and carbon footprint verification open duty-advantaged export pathways for USDA-certified processors into German and Dutch retail.
- Foodservice Ingredient Channels:Industrial formulations for baking and confectionery applications remain underpenetrated relative to retail, offering volume contracts with longer tenors.
Industry Challenges
- Non-GMO Project Verification Timelines:Supply chain documentation requirements for third-party certification create 12-18 month product launch delays.
- Legacy Equipment Retrofit Costs:Particle size reduction below 50 microns for stabilized emulsions requires capital-intensive mill upgrades that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nut Butters Market |
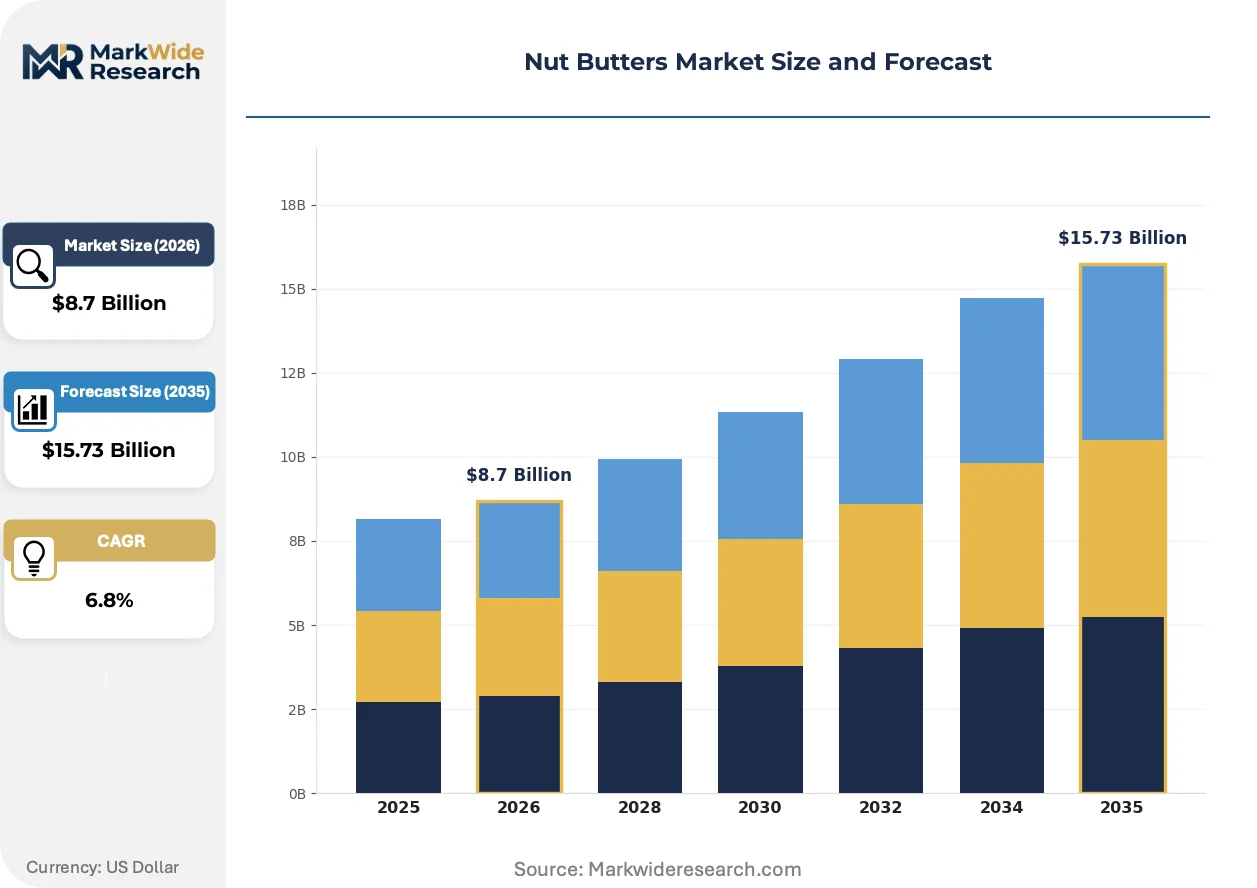
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond, Peanut, Cashew, Hazelnut Application: Snacking, Baking, Spreading, Cooking Form: Chunky, Creamy, Organic, Natural Packaging Type: Tubs, Pouches, Jars, Sachets |
| Companies Covered | Ferrero International, General Mills Inc., The J.M. Smucker Company, The Hershey Company, The Kraft Heinz Company, Hormel Foods Corporation, Nestle SA, Unilever Plc, Conagra Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nut Butters Market Emerging Trajectories
Processing technology and packaging formats are converging to address shelf stability and portability demands, while regulatory frameworks on both sides of the Atlantic reshape formulation protocols.
High-pressure processing is expanding into raw nut butter preservation, enabling ambient-stable products without thermal degradation of heat-sensitive micronutrients. Natural and organic retail sets are adopting this technology fastest, compressing the premium positioning window for conventional pasteurized alternatives as clean-label expectations harden.
EU Green Deal import standards are tightening carbon footprint documentation requirements for agricultural commodities entering Dutch and German ports. This industrial consequence is forcing Turkish hazelnut processors and California almond handlers to invest in scope-three emissions tracking. Organic-certified supply chains are responding fastest, leveraging existing traceability infrastructure to meet the new thresholds.
Sport nutrition buyers are consolidating procurement around single-source supplier contracts with verified allergen controls. This concentration is displacing fragmented spot purchasing through distributors, compressing margin layers for intermediaries. United States CrossFit and boutique fitness studio channels exhibit this pattern most visibly, with multi-year agreements now standard for private-label protein-enhanced spreads.
Nut Butters Market Segmentation
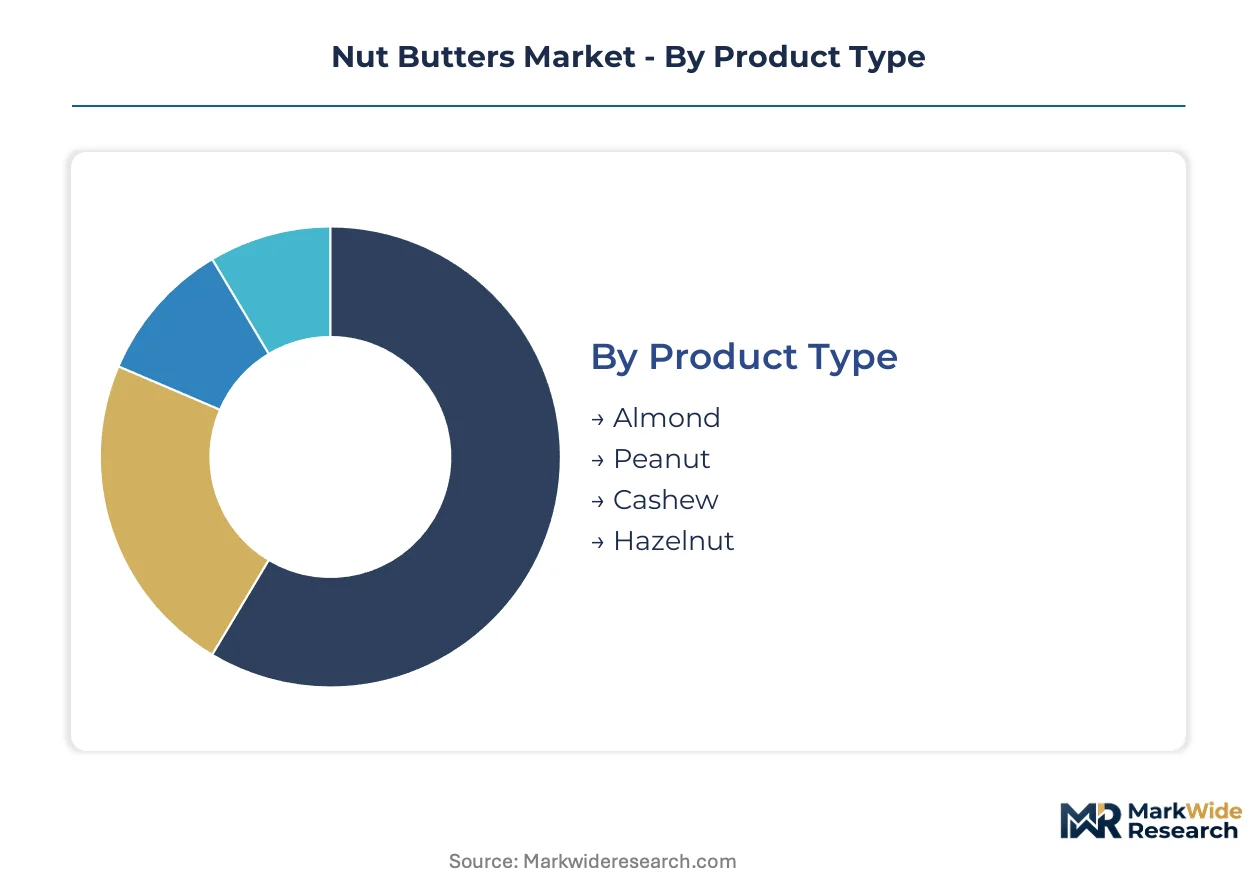
Nut butter segmentation reflects divergent buyer priorities across price sensitivity, health positioning, and usage occasion. Manufacturers configure product lines around these fault lines to capture shelf space in competing retail channels.
Product Type:
Buyers in this category separate by willingness to pay for tree nut premiums versus commodity peanut economics.
- Almond:Produced from California-grown kernels with higher monounsaturated fat content and protein density per serving. Natural and organic retail sets in the United States command price premiums for this segment as consumers prioritize heart-health claims and clean-label positioning.
- Peanut:Ground from runner and virginia varieties with established oil stabilization protocols and lower input costs. Volume concentrates in North American snacking and foodservice spreading applications where cost-per-ounce drives procurement decisions.
- Cashew:Creamier mouthfeel from higher native oil content suits premium dessert and confectionery applications. Brazilian and Vietnamese supply origins create traceability complexity for organic certification.
- Hazelnut:Turkish orchards supply the bulk of global raw material for this segment, with Ferrero's captive procurement setting benchmark pricing. European baking and chocolate compound applications absorb most industrial volume.
Peanut leads volumes today; almond is gaining share fastest.
Application:
End-use requirements dictate fat profile specifications, particle size tolerances, and stabilizer loading rates.
- Snacking:Portable single-serve formats dominate this segment, with protein-forward positioning driving pouch packaging adoption. Fitness channel buyers in the United States specify minimum protein thresholds and allergen-free processing protocols.
- Baking:Industrial formulations require consistent moisture binding and fat replacement functionality across temperature cycling. Commercial bakeries specify emulsion stability under mechanical shear during dough development.
- Spreading:Household consumption favors creamy textures with spreadability at refrigeration temperatures. Jif and private-label brands compete on price per ounce in this mature application.
- Cooking:Sauce and dressing applications demand neutral flavor profiles and high smoke-point tolerance. Foodservice accounts prioritize bulk formats with pump dispensing compatibility.
Spreading anchors current volumes; snacking shows the steepest expansion trajectory.
Form:
Processing intensity and ingredient declaration length separate price tiers in this category.
- Creamy:Particle size reduction below 50 microns creates stable emulsions without visual nut fragments. Manufacturing throughput favors this form for foodservice and ingredient channel contracts.
- Chunky:Retained nut pieces provide textural contrast for household spreading occasions. Loyal consumer base resists conversion to creamy alternatives despite manufacturing inefficiencies.
- Organic:USDA certification mandates segregated supply chains and prohibited substance lists. Retailers increasingly require this designation for shelf placement in natural channel sets.
- Natural:Elimination of hydrogenated oils and reduced stabilizer loads appeals to ingredient-conscious buyers. FDA labeling scrutiny on "natural" claims is intensifying formulation documentation requirements.
Creamy dominates manufacturing scale; organic is climbing the fastest.
Packaging Type:
Channel placement and consumption occasion determine format selection and unit economics.
- Pouches:Resealable flexible formats capture on-the-go snacking demand with portion control features. California and New York extended producer responsibility rules are accelerating recyclable material adoption.
- Jars:Traditional rigid containers retain household pantry penetration and private-label volume. Glass and PET formats compete on sustainability messaging and breakage risk.
- Tubs:Foodservice and industrial bulk applications favor this format for scoop dispensing and kitchen efficiency. Larger pack sizes reduce per-ounce logistics costs for high-velocity accounts.
- Sachets:Single-serve flexible packets serve hospitality and airline channels with portion precision. Waste generation concerns are prompting biodegradable film trials.
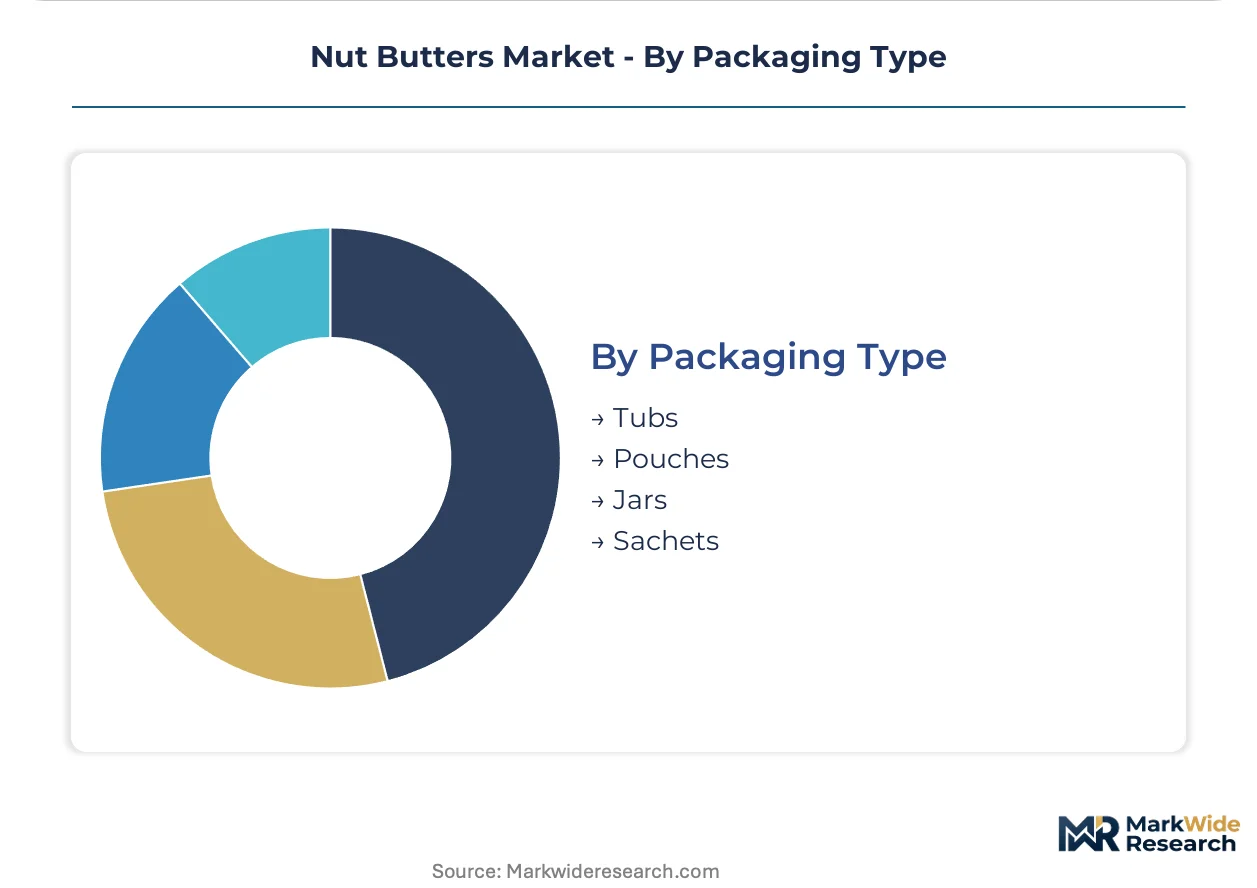
Jars maintain volume leadership; pouches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands per-capita consumption leadership while Turkey anchors hazelnut supply chains for European processing. Germany and the Netherlands function as regulatory gatekeepers for EU Green Deal compliance. Brazil and Vietnam compete for cashew origin dominance.
United States
Fitness channel procurement and private-label penetration drive volume concentration. FDA enforces FALCPA allergen labeling that mandates facility segregation protocols. California's Central Valley hosts almond processing clusters where specialty roasters build dedicated clean-room lines.
Germany
Organic retail channel expansion and industrial baking demand shape import requirements. EU Green Deal carbon footprint documentation rules tighten entry thresholds for Turkish and California suppliers. Hamburg port facilities handle bulk hazelnut shipments for confectionery compound manufacturers.
Turkey
Captive orchard networks and Ferrero-anchored procurement set global hazelnut pricing benchmarks. National agricultural extension programs support orchard modernization in Ordu and Giresun provinces. Black Sea coastal processing clusters export paste grades for European chocolate applications.
Brazil
Cashew kernel processing for premium butter grades competes with Indian subcontinent origins. Federal agricultural research agency Embrapa develops drought-resistant cultivars for Northeastern growing regions. Ceará state processing facilities specialize in organic-certified raw material streams.
Netherlands
Rotterdam port logistics and EU organic certification hubs attract third-party verification services. Dutch food safety authority NVWA enforces EU Green Deal import inspection protocols. Wageningen University research clusters advance high-pressure processing technology for raw nut butter preservation.
Nut Butters Market Vendor Landscape
United States producers anchor the mass-market tier; European specialists hold premium organic positioning. The vendor base stratifies across three archetypes: diversified food conglomerates with controlled distribution, orchard-integrated processors with captive raw material access, and regional blenders serving natural channel private-label contracts. Dominant competitive moves include backward integration into orchard assets and capacity expansion for allergen-segregated production lines.
Within the diversified conglomerate tier, Ferrero International exemplifies orchard-integrated supply control through Turkish hazelnut procurement networks. The J.M. Smucker Company occupies a position representing mass-market shelf presence and foodservice distribution scale. Nestle SA sits within the organic certification specialist archetype, leveraging traceability partnerships for natural channel placement.
| Leading Market Players |
|---|
| Ferrero International |
| General Mills Inc. |
| The J.M. Smucker Company |
| The Hershey Company |
| The Kraft Heinz Company |
| Hormel Foods Corporation |
| Nestle SA |
| Unilever Plc |
| Conagra Brands Inc. |
| Others |
Supply Flow & Price Mechanics
Fitness channel procurement concentration in the United States anchors contract-based long-term offtake agreements that stabilize price floors for premium almond and peanut butter grades. This buyer archetype's multi-year sourcing commitments create pricing power asymmetries favoring processors with certified allergen-segregated capacity.
Pricing Analysis
Capacity additions in California's Central Valley are reshaping price floors for almond butter as specialty roasters expand dedicated clean-room lines. Three-tier pricing structure across premium organic, standard natural, and economy conventional levels separates USDA-certified supply from mass-market private-label volumes. Cost compression in the standard tier intensifies because seed butter substitutes capture price-sensitive consumers with comparable fat profiles. Foodservice accounts exhibit highest price sensitivity due to volume procurement and pump-dispensing compatibility requirements, while organic retail channel buyers show least sensitivity when traceability claims are verified.
Supply Chain Analysis
Direct-to-foodservice channels handle institutional buyer demand through bulk tub formats with scoop dispensing compatibility. Raw material supply draws from California almonds, Turkish hazelnuts, and Brazilian cashews as primary geographic anchors. Processing dependencies rest on roasted kernel supplies, hydrogenated oil alternatives, and stabilizer emulsifiers for ambient shelf stability. Single-source vulnerability concentrates in Turkish hazelnut procurement networks where Ferrero-anchored orchard control sets benchmark pricing. Distribution runs through controlled retail shelf placement, natural channel private-label contracts, and industrial ingredient supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nut butters market functions as a stable compounder where protein-forward snacking applications in North American fitness channels generate predictable demand pull-through with limited cyclical exposure.
For Market Incumbents: Deploy backward integration into California almond orchard assets to secure cost-advantaged raw material supply. Expand certified allergen-segregated production lines to defend against seed butter substitution threats from sunflower and pumpkin spread processors. Channel control through Jif-scale foodservice distribution creates switching costs that regional blenders cannot replicate. For New Entrants and Emerging Players: Natural channel private-label contracts represent the most penetrable entry point given retailer mandates for USDA organic certification. Target underexploited industrial baking applications where fat replacement and texture modification specifications remain underserved relative to retail spreading volumes. Go-to-market leverage hinges on high-pressure processing technology adoption for raw nut butter preservation without thermal degradation. For Investors and Strategic Acquirers: Diversified food conglomerates are the most active acquirer in this space, seeking orchard-integrated processors with captive Turkish hazelnut or California almond supply. Long-term viability centers on carbon footprint verification infrastructure for EU Green Deal compliance. The inflection signal to monitor is state-level extended producer responsibility rule adoption for single-serve pouch formats in California and New York.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Captive California almond supply secures margin protection against input volatility from drought cycles. |
| Allergen-Segregated Line Expansion | FDA FALCPA enforcement creates competitive moats for processors with certified clean-room capabilities. |
| High-Pressure Processing Adoption | Wageningen University research clusters advance ambient-stable raw preservation without thermal degradation. |
| EU Green Deal Certification Investment | Carbon footprint documentation opens duty-advantaged export pathways into German and Dutch retail channels. |
| Recyclable Pouch Format Development | California and New York extended producer responsibility rules accelerate first-mover advantage in on-the-go formats. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and processing technology adoption patterns. Primary engagement included specialty roaster operations directors, natural channel category buyers at United States retailers, USDA organic certification auditors, and Turkish hazelnut procurement managers. Secondary validation drew from FDA FALCPA guidance documents, USDA organic handler databases, EU Green Deal import standard drafts, and customs trade records for almond and hazelnut paste shipments. Bottom-up processor capacity modeling and top-down retail channel revenue estimates were cross-referenced for triangulation.
Historical reference periods anchored volume and value outputs across the projection horizon to establish baseline growth trajectories. Segmentation dimensions modeled include product type, application, form, and packaging format alongside regional production hub clusters. CAGRs were derived from weighted average growth contributions across these segments. Industry-specific forecast inputs incorporated almond harvest yield sensitivity to California drought cycles and Turkish hazelnut orchard modernization rates in Ordu and Giresun provinces.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal carbon documentation enforcement timelines and state-level extended producer responsibility rule adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
North America Peanut Butter Market
Nuts and Seeds
Pecans Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
China Almond Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Europe Hazelnut Market
Nuts and Seeds
Processed Walnuts Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Macadamia Nut Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Walnut Oil Market