
 Global Almond Powder Market | 2026-2036
Global Almond Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Almond Powder Market Analysis
Specialty ingredient distribution is rewriting competitive access for almond powder suppliers across Europe and North America. Olam Group leverages its integrated origination network in California and Australia to control supply continuity for industrial buyers. Blue Diamond Growers anchors its position through captive orchards and vertical processing assets in the Central Valley. ADM competes by extending its plant-protein ingredient portfolio into bakery and beverage applications, bundling almond powder with pea and rice protein isolates.
Almond powder consists of ground blanched or natural almonds milled to particle sizes typically ranging from 40 to 200 microns, with fat content between 50-55% depending on defatting treatment; it functions as a gluten-free flour substitute, emulsifier, and protein fortificant in formulated foods. Fine powder dominates industrial bakery contracts where particle uniformity determines moisture binding and crumb structure, while organic powder captures premium shelf space in European supermarkets where EU organic certification commands price separation. The nutraceuticals end-user segment is pulling fastest growth as protein supplement manufacturers reformulate away from dairy and soy bases.
EU REACH and the FDA's Food Safety Modernization Act shape import compliance, allergen labeling, and processing facility audits for cross-border almond powder trade. The EU F-Gas Regulation and California's agricultural water restrictions are tightening environmental accountability across the orchard-to-powder value chain. Stakeholders must monitor how dual carbon goals in China and evolving organic equivalency agreements between the EU and third countries reroute sourcing decisions and certification investments.
Market Dynamics
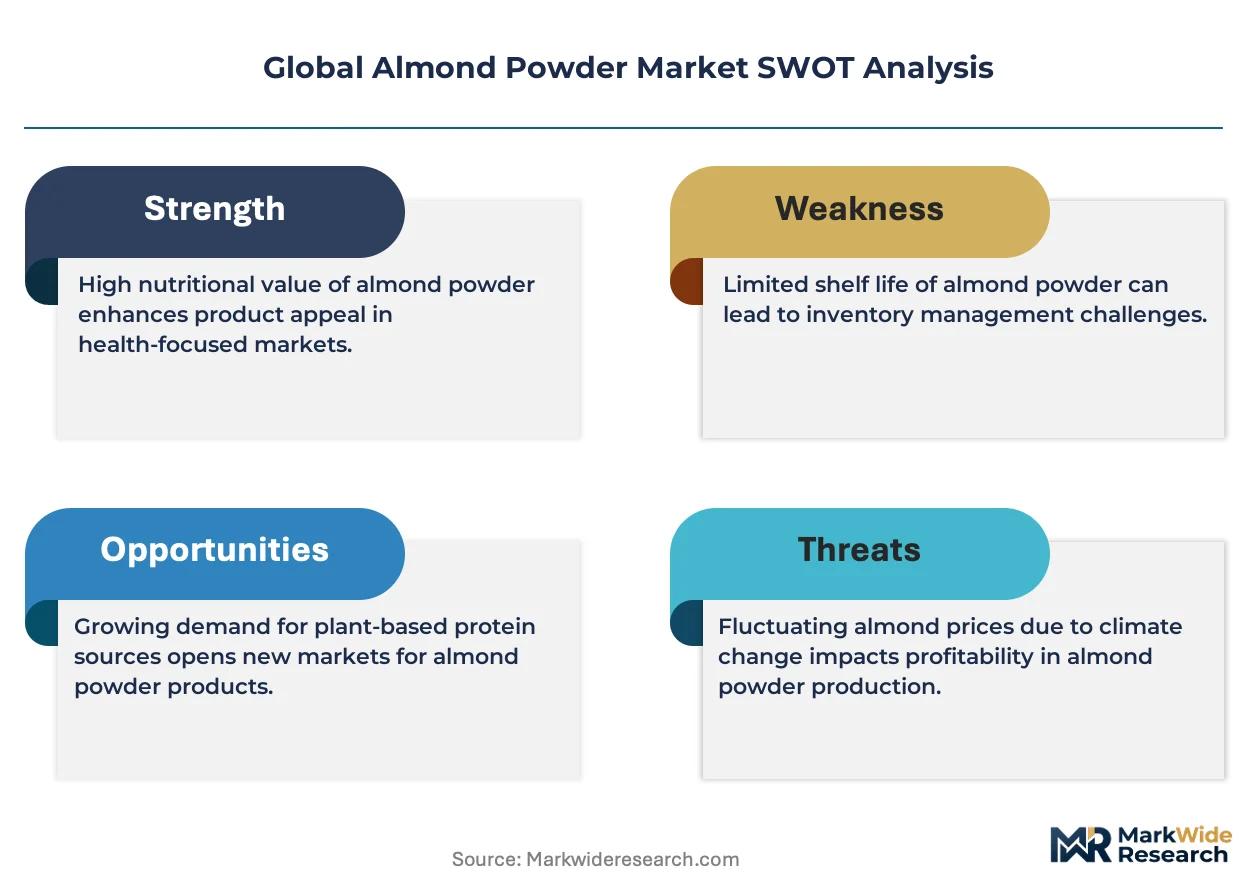
The EU F-Gas Regulation is forcing almond powder processors to retrofit solvent-based oil extraction systems with supercritical CO2 units, compressing margins for mid-tier suppliers while advantaging capital-rich operators with captive orchards.
Growth Catalysts
- Clean-label bakery reformulation:German and French industrial bakers are substituting almond powder for modified starches in gluten-free bread lines to meet EFSA guidance on additive reduction.
- EU Organic Certification:Third-country equivalency agreements with Australia and Argentina are expanding import pathways for certified organic powder into Netherlands and UK retail channels.
- Supercritical CO2 extraction:This technology is lowering residual solvent thresholds below FDA Food Safety Modernization Act limits, unlocking pharmaceutical-grade applications for defatted almond protein isolates.
Market Restraints
- California water allocation volatility:Central Valley irrigation restrictions under the Sustainable Groundwater Management Act are compressing raw almond supply predictability for powder manufacturers.
- Defatting equipment capex intensity:Cold-press and CO2 extraction systems require USD 4-8 million per production line, freezing out regional processors in India and Turkey.
- Peanut and tree-nut cross-contamination liability:FDA allergen labeling mandates and EU Regulation 1169/2011 create compliance friction for multi-nut processing facilities.
Strategic Opportunities
- Japan's FOSHU functional food pathway:Almond protein hydrolysates targeting blood pressure claims can access premium positioning through PMDA's Foods for Specified Health Uses framework.
- Direct-to-baker e-commerce channels:Artisan bakery clusters in Melbourne and São Paulo are bypassing ingredient distributors to source small-batch organic powder through specialized platforms.
- Dual carbon goals in China:NMPA green manufacturing incentives for low-carbon processing are pulling investment toward defatted almond powder as a plant-protein feedstock for domestic sports nutrition brands.
Industry Challenges
- Supercritical CO2 technician scarcity:Qualified operators for high-pressure extraction systems command 40% salary premiums above conventional oil-press technicians, constraining capacity expansion timelines.
- Organic equivalency audit backlogs:EU recognition procedures for third-country certifiers are stretching to 18-24 months, delaying market entry for new organic suppliers from Central Asia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Almond Powder Market |
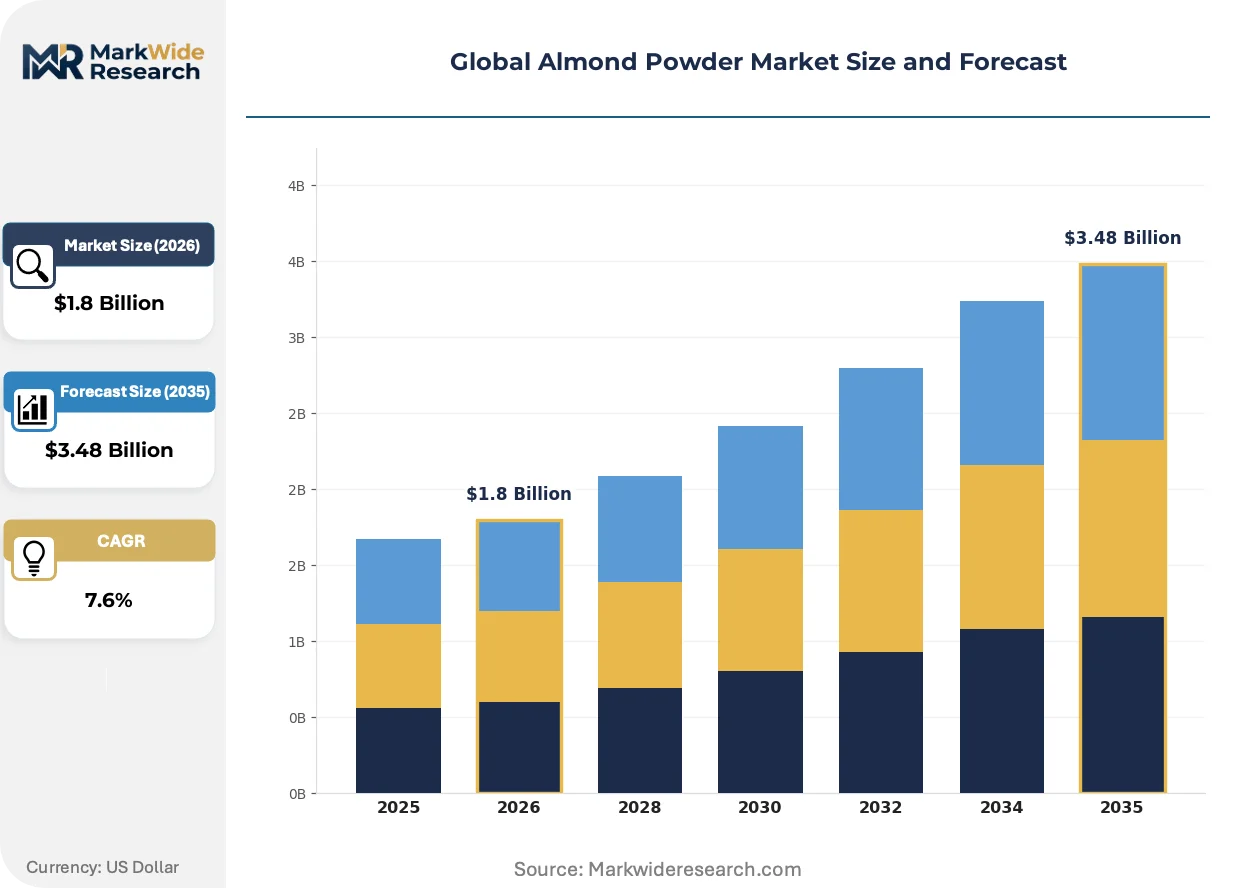
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fine Powder, Coarse Powder, Organic Powder, Blanched Powder Application: Baking, Smoothies, Protein Supplements, Confectionery End User: Food Industry, Nutraceuticals, Cosmetics, Retail Customers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Olam Group, Borges Agricultural & Industrial Nuts, ADM, Rolling Hills Nut Company, Almondco Australia, Blue Diamond Growers, Royal Nut Company, Anthony's Goods, Bob's Red Mill Natural Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Almond Powder Market Emerging Trajectories
Processing technology and procurement patterns are diverging sharply between premium organic supply chains and industrial commodity flows, with regulatory pressure acting as the wedge between the two pathways.
Supercritical CO2 extraction is hybridizing with ultrasonic-assisted milling to produce sub-50-micron almond powders with preserved heat-labile proteins. Sports nutrition formulators in Germany and California are specifying these grades for ready-to-mix protein beverages. The technology is hybridizing high-value pharmaceutical applications with commodity food-grade production, compressing the historical price spread between the two segments.
REACH authorization requirements for hexane-based oil extraction are tightening solvent residue thresholds across EU member states. Industrial almond processors are retrofitting facilities or exiting the defatted powder segment entirely. The bakery and confectionery sectors in France and Italy are absorbing pass-through costs while lobbying ECHA for extended transition timelines.
Ingredient sourcing contracts are compressing from multi-year frameworks to 6-12 month spot arrangements with price collars. North American contract manufacturers are disintermediating traditional distributors to secure direct relationships with Australian and Spanish orchard cooperatives. This pattern is most visible in the clean-label snack bar segment, where formulation flexibility demands rapid supplier switching.
Global Almond Powder Market Segmentation
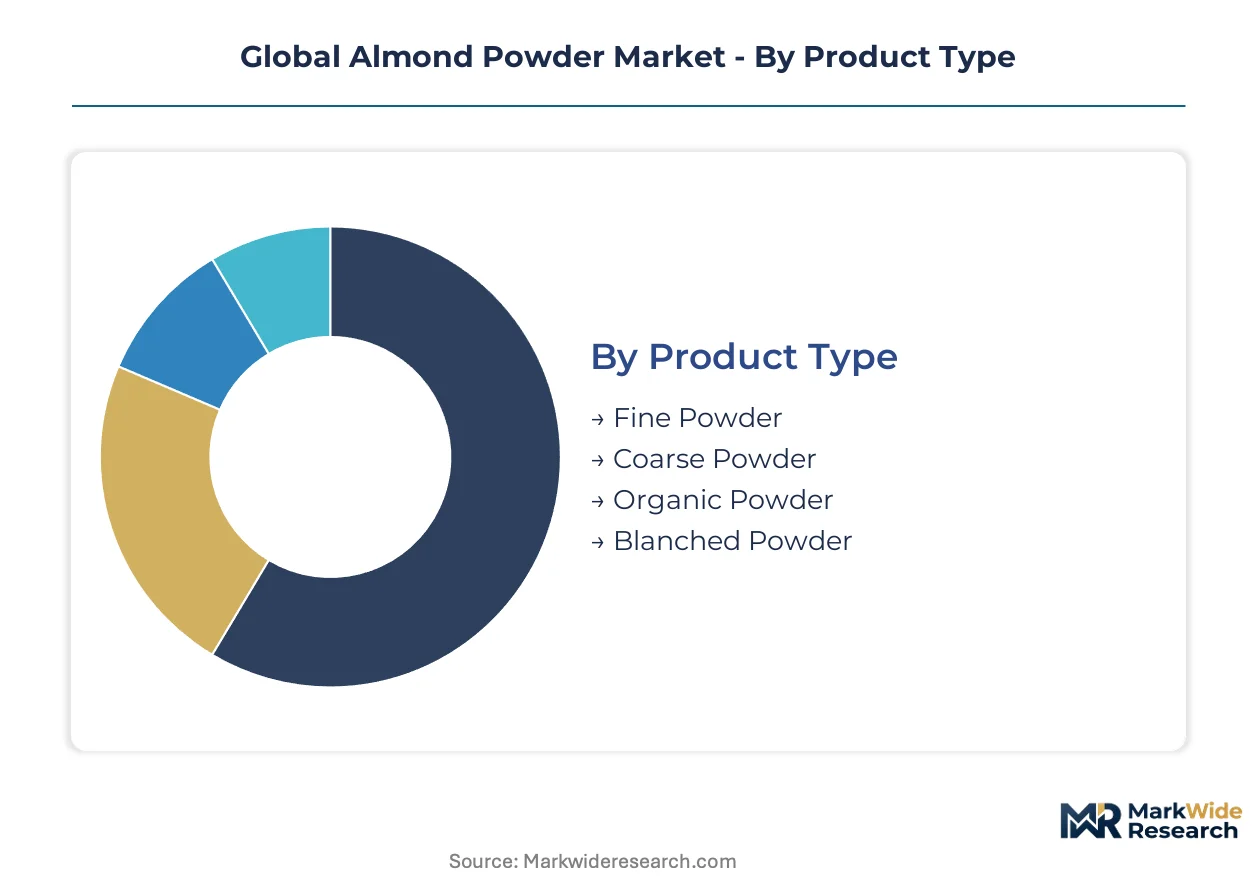
Almond powder segmentation reflects divergent processing intensities and compliance burdens across supply chains. Technical specifications around particle size, fat content, and certification status determine which segments command formulation partnerships versus commodity trading relationships.
Product Type:
After-sales service intensity varies sharply by powder grade, with defatted and organic variants requiring technical support for extraction parameter optimization and certification maintenance.
- Fine Powder:Milled to 40-80 micron particle size with narrow distribution curves, fine powder delivers predictable moisture binding in industrial bakery lines. German and French gluten-free bread manufacturers specify this grade under EFSA additive reduction guidance. By volume, fine powder leads. By growth pace, organic powder is ahead.
- Organic Powder:EU organic certification and third-country equivalency protocols with Australia and Argentina govern import eligibility. Netherlands and UK retail channels absorb rising volumes as clean-label shelf space expands. Organic powder commands the steepest expansion trajectory among all product grades.
- Coarse Powder:100-200 micron particle range suits textured applications like granola clusters and artisan bread crusts.
- Blanched Powder:Skin removal prior to milling reduces tannin content for delicate confectionery applications in Belgian and Swiss chocolate manufacturing.
Processing technology investments cluster around fine and organic grades, leaving coarse and blanched as margin-compressed commodity flows.
Application:
Cost tier stratification separates commodity bakery volume from premium nutraceutical formulations, with protein supplements absorbing the highest per-kilogram prices.
- Protein Supplements:Defatted almond protein isolates with sub-50 micron sizing target ready-to-mix beverage applications. Sports nutrition brands in California and Germany specify supercritical CO2 extracted grades to meet residual solvent thresholds below FDA Food Safety Modernization Act limits.
- Baking:Gluten-free bread reformulation drives industrial uptake, with almond powder substituting for modified starches in EFSA-compliant clean-label lines across Germany and France.
- Smoothies:Fine organic powder integrates into premium beverage bases for Melbourne and São Paulo direct-to-consumer channels.
- Confectionery:Blanched grades serve Belgian praline and Swiss chocolate manufacturers requiring neutral flavor profiles.
Baking generates the largest tonnage offtake. Protein supplements deliver the highest value-per-kilogram expansion.
End User:
Customer type determines contract structure, with food industry buyers demanding multi-year supply agreements and nutraceuticals accepting spot pricing with quality premiums.
- Nutraceuticals:Protein supplement manufacturers reformulate away from dairy and soy bases, pulling almond powder into pharmaceutical-grade applications. PMDA's Foods for Specified Health Uses framework in Japan enables premium positioning for blood pressure claim products.
- Food Industry:Industrial bakers and confectioners specify particle uniformity and lot consistency for automated production lines.
- Cosmetics:Fine-milled powder enters natural skincare formulations as an exfoliant and oil-absorbing agent.
- Retail Customers:Artisan bakers in Melbourne and São Paulo source small-batch organic powder through specialized e-commerce platforms.
Food industry contracts anchor volume stability. Nutraceuticals drive the fastest specification upgrading and price realization.
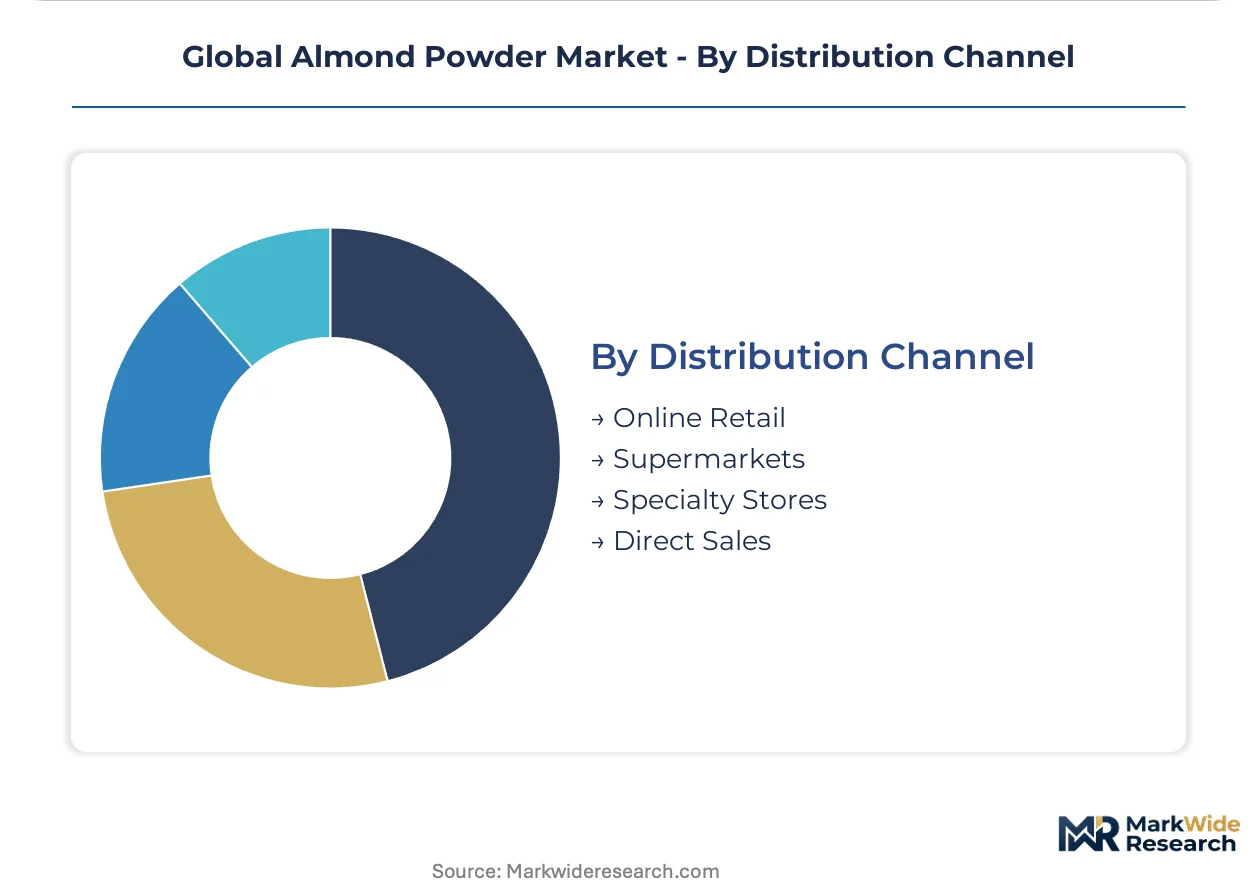
Distribution Channel:
Supply concentration in California and Australia shapes channel access, with direct sales bypassing traditional distributors for clean-label snack bar manufacturers seeking formulation flexibility.
- Direct Sales:North American contract manufacturers disintermediate distributors to secure relationships with Australian and Spanish orchard cooperatives. Six-to-twelve month spot arrangements with price collars replace multi-year frameworks.
- Online Retail:Specialized platforms serve artisan bakery clusters with small-batch organic powder and rapid supplier switching capabilities.
- Supermarkets:EU organic certification commands price separation in Netherlands and UK retail channels.
- Specialty Stores:Health food retailers stock premium grades for home bakers and protein supplement consumers.
Direct sales capture the largest volume flows. Online retail channels expand most quickly among emerging access routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's import dominance for almond powder, while California's Central Valley irrigation networks anchor North American supply security. Rail corridors linking Melbourne to Port Botany secure Australian export velocity into Asian markets.
United States
California's Central Valley hosts the densest concentration of almond orchards and powder processing facilities worldwide. The state's Sustainable Groundwater Management Act compresses irrigation allocations, forcing processors to secure alternative water sourcing contracts. Sacramento Valley clusters now specialize in defatted powder grades for protein supplement manufacturers.
Germany
Industrial bakers in Bavaria and North Rhine-Westphalia specify fine almond powder for gluten-free bread lines under EFSA additive reduction guidance. The EU F-Gas Regulation mandates retrofitting of solvent-based extraction systems, advantaging capital-rich operators with supercritical CO2 capacity. Hamburg's ingredient trading houses arbitrage price volatility between Australian and Spanish supply.
Australia
Riverina and Sunraysia orchard cooperatives supply certified organic powder through EU equivalency agreements. The country's national agricultural regulator enforces strict residue thresholds for export eligibility. Melbourne's direct-to-baker e-commerce platforms now bypass traditional distribution channels for artisan bakery clusters.
China
NMPA green manufacturing incentives pull investment toward defatted almond powder as plant-protein feedstock for domestic sports nutrition brands. The dual carbon goals framework prioritizes low-carbon processing technologies in Yangtze River Delta manufacturing zones. Shanghai-based contract manufacturers source directly from Australian orchard cooperatives.
Japan
PMDA's Foods for Specified Health Uses framework enables premium positioning for almond protein hydrolysates targeting blood pressure claims. METI's functional food regulations shape formulation standards for nutraceutical applications. Osaka and Tokyo metropolitan areas concentrate demand for pharmaceutical-grade defatted isolates.
Global Almond Powder Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in orchard origination and single-origin processing. The vendor base stratifies between capital-rich operators with captive orchard assets and regional toll processors dependent on spot almond supply. Three archetypes dominate: integrated agribusiness conglomerates with global origination networks, cooperative-backed processors with single-region concentration, and specialty ingredient distributors with formulation technical service capabilities. Competitive moves center on backward integration into orchard assets and supercritical CO2 extraction capacity expansion.
Among integrated agribusiness conglomerates, Olam Group and ADM exemplify platform-scale positioning through diversified origination networks. Blue Diamond Growers represents the cooperative-backed archetype with Central Valley concentration. Borges Agricultural & Industrial Nuts and Almondco Australia occupy positions as regional specialists with Mediterranean and Southern Hemisphere supply focus respectively.
| Leading Market Players |
|---|
| Olam Group |
| Borges Agricultural & Industrial Nuts |
| ADM |
| Rolling Hills Nut Company |
| Almondco Australia |
| Blue Diamond Growers |
| Royal Nut Company |
| Anthony's Goods |
| Bob's Red Mill Natural Foods |
| Others |
Supply Flow & Price Mechanics
California's Central Valley processing clusters anchor global almond powder pricing power through captive orchard assets and supercritical CO2 extraction capacity that mid-tier competitors cannot replicate. Water allocation volatility under the Sustainable Groundwater Management Act compresses raw supply predictability, forcing buyers into shorter contract cycles with price collars.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade defatted isolates from industrial bakery grades and commodity coarse powder. Price differentiation hinges on EU organic certification status and particle size uniformity below 80 microns. Cost compression in standard grades is intensifying because REACH-mandated hexane extraction retrofits burden regional processors. Industrial bakers in Germany exhibit highest price sensitivity, while nutraceutical formulators in Japan absorb premiums for PMDA-compliant hydrolysates.
Supply Chain Analysis
Extended payment terms from Australian orchard cooperatives to Hamburg trading houses illustrate how supplier financing lubricates cross-hemisphere flows. Geographic concentration centers on the United States, Australia, and Spain, with raw almond supply drawn from California's Central Valley and Riverina basin. The chain rests on water-stressed irrigation networks, cold-press equipment, and supercritical CO2 systems. Single-source vulnerability from California drought exposure threatens continuity. Distribution runs through Rotterdam's cold-chain infrastructure for European bakery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Almond powder markets reward service-attach capabilities, with technical support for extraction parameter optimization and certification maintenance expanding faster than commodity powder sales. Recurring revenue from organic equivalency audit preparation and supercritical CO2 operator training outpaces hardware margins.
For Market Incumbents:Harden supply continuity through backward integration into Australian orchard cooperatives under EU equivalency protocols. Expand in-house supercritical CO2 capacity before ECHA transition deadlines eliminate hexane-dependent competitors. Defend against emerging South American organic suppliers by locking multi-year offtake agreements with Netherlands retail distributors.
For New Entrants and Emerging Players:Direct-to-baker e-commerce channels in São Paulo and Melbourne represent the most penetrable entry point, bypassing entrenched distributor relationships. Small-batch organic powder with rapid supplier switching capabilities targets artisan bakery clusters. Go-to-market execution should lead with formulation technical service rather than price competition.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors capital-rich operators with captive orchard assets and supercritical CO2 extraction capacity. Long-term viability rests on regulatory compliance infrastructure rather than commodity trading relationships. Target acquisition archetype: Mediterranean or Southern Hemisphere processors with EU organic certification and underutilized defatting equipment. Watch for inflection when EU F-Gas Regulation enforcement accelerates hexane facility closures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Captive supply from Australian cooperatives secures EU organic certification pathways. |
| Supercritical CO2 Capacity Expansion | REACH compliance unlocks pharmaceutical-grade defatted isolate premiums in Germany. |
| Direct-to-Baker E-commerce Launch | Melbourne and São Paulo artisan clusters bypass traditional distribution markups. |
| Organic Equivalency Certification Investment | EU recognition procedures with Argentina expand Netherlands retail channel access. |
| Technical Service Capability Buildout | Extraction parameter optimization commands recurring revenue from nutraceutical formulators. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA Food Safety Modernization Act guidance documents, ECHA REACH authorization databases, and EU organic equivalency agreements. Primary interviews engaged almond powder plant managers, procurement leads at German industrial bakeries, sports nutrition formulators in California, and organic certification auditors. Secondary sources included customs trade data, EFSA additive reduction guidance, and SEC filings from integrated agribusiness conglomerates. Bottom-up volume modeling triangulated against top-down value estimates across product grades.
Forecast inputs span particle size tiers, fat content levels, certification status, and end-use applications across the projection horizon. Segmentation dimensions include product type, application category, end-user industry, and distribution channel. CAGRs were derived from demand elasticity modeling against regulatory compliance timelines and substitution patterns from dairy and soy proteins. Industry-specific inputs incorporated California groundwater allocation scenarios and EU F-Gas Regulation retrofit schedules.
Macroeconomic conditions sit as an overlay; deviation in irrigation water pricing, energy costs for CO2 compression, or organic feedstock premiums would shift the trajectory. Forecasts reflect documented assumptions on technology adoption curves and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Baru Nuts Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
Horse Chestnut Seed Extract Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Cashew Nut Butter Market
Nuts and Seeds
Almond Oil Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
Packaged Sunflower Seeds Market
Nuts and Seeds
North America Moringa Products Market
Nuts and Seeds
Rubus Idaeus (Raspberry) Seeds Market