
 Almond with Shell Snack Market | 2026-2036
Almond with Shell Snack Market Size, Share, and Industry Trends Forecast 2026-2036
Almond with Shell Snack Market Analytics
Asset-light contract farming arrangements is rewriting competitive entry barriers for almond processors without orchard holdings. Blue Diamond Growers leverages its cooperative structure to control upstream supply from thousands of California growers. John B. Sanfilippo & Son anchors its position through vertical integration spanning shelling, roasting, and private-label manufacturing. Three Squirrels dominates e-commerce channels with data-driven flavor development targeted at younger Chinese consumers.
Almond with Shell Snack denotes in-shell almonds retained in their natural hulls, typically air-dried to moisture content below six percent to prevent aflatoxin proliferation while preserving raw kernel integrity for roasting or flavoring applications. Roasted almonds command the largest revenue share due to established consumer preference for crunch texture and extended shelf stability. Flavored almonds represent the fastest-expanding product category as chili-lime, wasabi, and honey-glaze variants attract experimental snack buyers. Bags remain the dominant packaging format, though bulk containers gain traction in food service procurement where operators seek portion control flexibility.
USDA grading standards and FDA food safety modernization rules enforce strict aflatoxin thresholds and preventive controls across California processing facilities. China's SAMR implements GB national food safety standards that govern maximum residue limits and labeling requirements for imported nuts. Stakeholders must monitor evolving water rights allocations under California's SGMA and China's dual carbon goals, as irrigation restrictions and energy costs reshape orchard economics and processing location decisions.
Market Dynamics
California's Sustainable Groundwater Management Act is forcing almond orchard operators to retire acreage and adopt deficit irrigation, compressing kernel supply availability while Chinese e-commerce platforms accelerate flavor innovation cycles.
Growth Catalysts
- SGMA groundwater regulations:California's water accounting rules are accelerating orchard consolidation among capital-efficient operators who deploy precision drip systems.
- Chinese tier-one urbanization:Shanghai and Beijing snack buyers are driving premium in-shell almond adoption through live-streaming commerce channels.
- Aflatoxin detection automation:Near-infrared sorting technology is collapsing rejection rates at California huller-sheller facilities.
Market Restraints
- Input cost volatility:Bee pollination service fees and diesel irrigation pump costs swing with climate stress and energy markets.
- Supply concentration risk:Central Valley water districts control allocation priority, creating single-point vulnerability for uncontracted processors.
- Regulatory friction:China's GB national food safety standards impose extended customs inspection protocols for California shipments.
Strategic Opportunities
- Underpenetrated India snacking:Mumbai and Delhi convenience retail chains are adding imported nut sections without established domestic shelling infrastructure.
- Regulatory tailwind:China's dual carbon goals are incentivizing solar-powered roasting facilities in Shandong processing zones.
- Technology convergence:Blockchain lot-tracking combined with humidity sensor packaging is enabling origin-verified direct-to-consumer subscription models.
Industry Challenges
- Skill gap in predictive orchard management:Soil moisture telemetry interpretation and deficit irrigation timing require agronomists cross-trained in data analytics.
- Certification timeline compression:BRC and SQF audit backlogs at California shelling facilities are extending customer onboarding for private-label contracts.
- Legacy equipment integration:Robotic bin-handling systems must interface with decades-old drying floor infrastructure without operational shutdown.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Almond with Shell Snack Market |
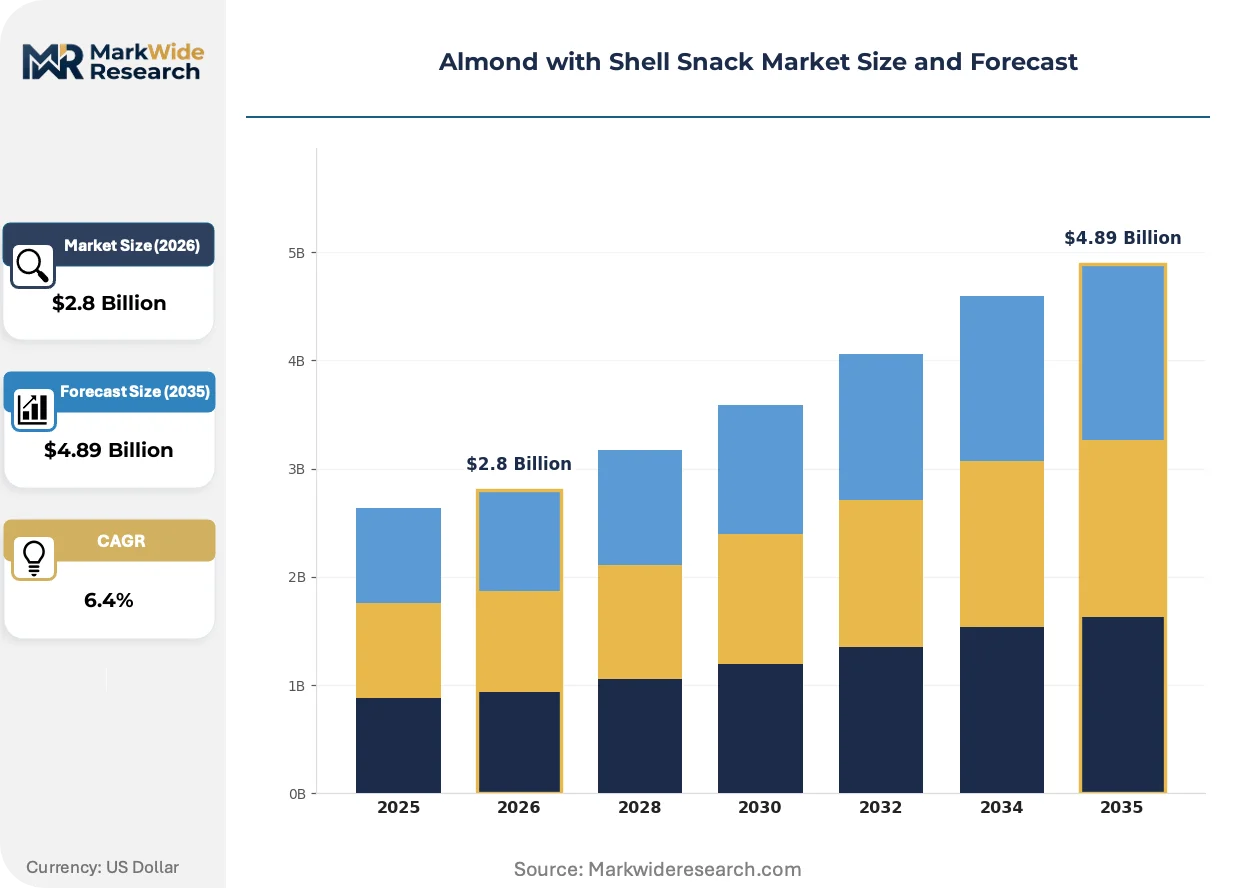
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Almonds, Roasted Almonds, Smoked Almonds, Flavored Almonds Packaging Type: Bags, Tubs, Boxes, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores Customer Type: Health-Conscious Consumers, Snack Enthusiasts, Retailers, Food Service Operators |
| Companies Covered | Blue Diamond Growers, John B. Sanfilippo & Son, Olam International Limited, Treehouse California Almonds, Harris Woolf California Almonds, Borges Agricultural & Industrial Nuts, Three Squirrels, Qia Qia, Liang Pin Pu Zi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Almond with Shell Snack Market Evolving Landscape
Electromagnetic sorting and blockchain provenance systems are collapsing quality assurance costs while regulatory water accounting and Chinese live-commerce are rewriting supply and demand formation.
Hyperspectral imaging is collapsing defect detection error rates at California huller-sheller facilities. Mid-sized cooperatives are adopting the technology to maintain processor status under tightening buyer specifications. The capital barrier between commodity handlers and premium-grade suppliers is compressing as lease-financed units reach secondhand markets.
REACH chemical registration requirements in Europe are extending coating additive approval timelines for flavored almond variants. Manufacturers are reformulating with pre-approved natural extracts rather than awaiting novel substance clearances. The chili-lime and wasabi flavor segments are most affected, with suppliers pivoting to turmeric and Sichuan peppercorn bases.
Chinese consumers are bypassing traditional wholesale layers through Douyin and Xiaohongshu live-streaming purchases. Younger buyers in Guangzhou and Chengdu are discovering regional California almond brands previously unavailable in brick-and-mortar retail. Direct fulfillment from bonded Shanghai warehouses is collapsing delivery latency to under 48 hours.
Almond with Shell Snack Market Segmentation
Segmentation in the almond with shell snack market reveals distinct demand patterns across preparation methods, packaging formats, and channel access. Each dimension carries implications for shelf stability requirements, price positioning, and regulatory compliance intensity.
Product Type:
Preparation intensity spans from untreated raw kernels through thermally processed and flavor-infused variants, with each tier commanding different margin structures and equipment investment thresholds.
- Raw Almonds:Air-dried kernels retained in natural hulls with moisture content below six percent to prevent aflatoxin proliferation. Demand concentrates among health food stores and clean-label buyers in California's Bay Area and China's tier-one cities where minimal processing aligns with ingredient transparency preferences.
- Roasted Almonds:Dry-heat treated kernels achieving crunch texture and extended shelf stability through Maillard reaction development. Volume concentrates in US supermarket chains and Chinese e-commerce platforms where established flavor profiles reduce consumer trial risk.
- Smoked Almonds:Cold-smoked or liquid-smoke infused variants targeting craft snack positioning. Niche adoption in specialty retail and food service applications where distinct flavor differentiation commands premium pricing.
- Flavored Almonds:Chili-lime, wasabi, honey-glaze, and emerging Sichuan peppercorn variants attracting experimental buyers. Fastest-expanding category driven by Douyin live-streaming discovery among younger Chinese consumers.
Established volume favors roasted variants; emerging adoption favors flavored innovation cycles.
Packaging Type:
Unit economics and handling requirements divide procurement patterns between consumer-facing retail formats and food service bulk operations.
- Bags:Flexible film pouches with reseal features and nitrogen flush for oxidation control. Dominant format in supermarket and convenience retail across the United States and China where grab-and-go consumption dominates.
- Tubs:Rigid plastic containers supporting club store multi-serve positioning and pantry storage visibility. Concentrated demand in Costco and Sam's Club locations where household stock-up trips drive volume.
- Boxes:Paperboard secondary packaging for gift sets and seasonal assortments. Premium positioning in Chinese New Year and Mid-Autumn Festival gifting in Shanghai and Beijing urban markets.
- Bulk Containers:Food-grade totes and supersacks for commercial roasting and private-label repackaging. Traction in food service procurement where operators seek portion control flexibility and ingredient cost transparency.
Retail velocity concentrates in bags and tubs; food service migration favors bulk flexibility.
Distribution Channel:
Channel selection determines regulatory touchpoint density, with cross-border e-commerce imposing distinct customs and labeling protocols versus domestic retail compliance.
- Online Retail:Direct-to-consumer and marketplace platforms including Tmall, JD.com, and Douyin live-streaming. Fastest-expanding channel in China where bonded Shanghai warehouses collapse delivery latency to under 48 hours.
- Supermarkets:Traditional grocery and hypermarket chains with established nut aisle placement. Volume anchor in the United States where Blue Diamond and private-label SKUs compete for shelf space.
- Convenience Stores:Small-format urban retail with limited assortment and immediate consumption positioning. Growing traction in India's Mumbai and Delhi chains adding imported nut sections.
- Health Food Stores:Specialty retailers emphasizing organic certification, non-GMO verification, and clean-label positioning. Concentrated demand in California and Pacific Northwest markets with strong natural products retail infrastructure.
Digital adoption climbs fastest; physical retail retains volume concentration.
Customer Type:
Purchasing authority and use-case specificity separate end consumers from intermediary buyers with distinct specification and contract requirements.
- Health-Conscious Consumers:Buyers prioritizing protein content, unsaturated fat profiles, and minimal ingredient lists. Concentrated in US coastal metros and Chinese tier-one cities where wellness positioning drives premium willingness.
- Snack Enthusiasts:Flavor-driven purchasers seeking novel taste experiences and texture variety. Core demographic for Three Squirrels' data-driven product development and limited-edition releases.
- Retailers:Supermarket chains, convenience operators, and e-commerce platforms with private-label and branded assortment requirements. Procurement governed by BRC and SQF audit standards with extended certification timelines.
- Food Service Operators:Restaurants, hotels, and catering services requiring consistent kernel sizing and supply reliability. Demand concentrates in bulk containers with specification sheets supporting menu cost engineering.
Consumer segments drive flavor innovation; institutional buyers enforce supply reliability standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious snack buyers cluster in coastal metros and tier-one Chinese cities, while agricultural water regulations reshape orchard economics in California's Central Valley.
United States
California's Central Valley dominates kernel supply through cooperative farming networks serving health-focused consumers in Los Angeles and San Francisco. The Sustainable Groundwater Management Act forces deficit irrigation adoption across Fresno and Kern counties, compressing yields among operators lacking precision drip infrastructure.
China
Shanghai and Beijing urban snack enthusiasts drive premium in-shell demand through Douyin live-streaming discovery channels. SAMR enforces GB national food safety standards with extended customs inspection protocols for California shipments. Bonded Shanghai warehouses now collapse delivery latency to under 48 hours for direct-to-consumer fulfillment.
India
Mumbai and Delhi convenience retail chains are expanding imported nut sections without established domestic shelling infrastructure. FSSAI governs maximum residue limits and labeling requirements for packaged snacks. Western Maharashtra's nascent roasting facilities face equipment financing constraints against established California supply chains.
Spain
Borges Agricultural & Industrial Nuts anchors Mediterranean processing capacity serving European clean-label buyers. EFSA aflatoxin thresholds and REACH chemical registration requirements extend coating additive approval timelines for flavored variants. Catalonia's roasting clusters pivot toward turmeric and Sichuan peppercorn bases to bypass novel substance clearances.
Australia
Riverina orchard operators in New South Wales supply raw kernels to Asian markets amid recurring drought cycles. Biosecurity protocols govern import substitution patterns when California shipments face inspection delays. Melbourne and Sydney health food retailers emphasize non-GMO verification for premium positioning against US cooperative brands.
Almond with Shell Snack Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented upstream supply and consolidating downstream distribution. The vendor base spans agricultural cooperatives, integrated processors, and e-commerce-native brands with divergent capital intensity requirements. Three strategic archetypes dominate: cooperative-backed volume handlers, vertically integrated roasting specialists, and data-driven flavor innovators. Competitive moves concentrate on backward integration into orchard assets and direct-to-consumer platform development.
Within the cooperative archetype, Blue Diamond Growers exemplifies upstream supply aggregation across thousands of California growers. John B. Sanfilippo & Son occupies a position spanning shelling, roasting, and private-label manufacturing. Three Squirrels anchors the e-commerce-native tier with platform-controlled flavor development cycles targeting younger Chinese consumers.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| John B. Sanfilippo & Son |
| Olam International Limited |
| Treehouse California Almonds |
| Harris Woolf California Almonds |
| Borges Agricultural & Industrial Nuts |
| Three Squirrels |
| Qia Qia |
| Liang Pin Pu Zi |
| Others |
Value Network & Pricing Analysis
Port of Long Beach container freight corridors transmit California water stress directly into landed cost spreads between premium and commodity-grade almond shipments. SGMA-driven deficit irrigation compresses kernel yields among uncontracted growers, forcing price stratification between precision-irrigated cooperative supply and spot-market procurement.
Pricing Analysis
Cost-plus contracts indexed to California Almond Objective Measurement reports dominate processor-buyer agreements. Three-tier pricing structure across premium, standard, and economy levels separates Blue Diamond's certified lots from private-label commodity grades and food-service bulk streams. Pricing pressure stems from bee pollination fee volatility and diesel pump cost swings. Food service operators exhibit highest price sensitivity; Chinese e-commerce platforms show lowest elasticity due to flavor-premium capture.
Supply Chain Analysis
Export-control regimes on hyperspectral sorting technology limit defect-detection equipment flows to secondhand markets outside California. Supply concentrates in the United States, Spain, and Australia. Raw material dependencies include bee pollination services, nitrogen flush packaging films, and liquid smoke flavoring inputs. Single-source vulnerability concentrates in Central Valley water district allocations. Distribution runs through cooperative huller-sheller networks into branded retail and private-label manufacturing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavor subscription services and origin-verified direct-to-consumer platforms expand faster than commodity kernel trading, repositioning almond snacks as recurring-revenue consumables rather than bulk ingredients.
For Market Incumbents: Harden cooperative supply contracts against SGMA groundwater curtailment by deploying precision drip infrastructure in Fresno and Kern counties. Deepen backward integration into controlled-atmosphere storage assets to buffer aflatoxin rejection volatility. Certification investment in BRC and SQF standards defends private-label contracts against audit backlog delays. For New Entrants and Emerging Players: Build out direct-to-consumer subscription models leveraging blockchain lot-tracking and humidity sensor packaging for provenance differentiation. India's convenience retail chains in Mumbai and Delhi offer the most penetrable white space without established domestic shelling infrastructure. Go-to-market execution should anchor Douyin live-streaming discovery campaigns targeting Guangzhou and Chengdu snack enthusiasts. For Investors and Strategic Acquirers: E-commerce-native flavor innovators with platform-controlled product development cycles represent the highest-conviction acquisition archetype. Long-term viability hinges on irrigation technology transfer and carbon-neutral roasting facility deployment. Watch for California water district allocation priority shifts as the inflection signal forcing portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Irrigation Infrastructure Deployment | SGMA compliance in Fresno County secures kernel supply access for cooperative processors. |
| Blockchain Provenance System Integration | Origin-verified subscription models capture premium willingness among Chinese tier-one consumers. |
| Flavor Innovation Platform Development | Data-driven release cycles through Douyin live-streaming accelerate adoption among younger buyers. |
| Solar-Powered Roasting Facility Buildout | Shandong processing zones leverage China's dual carbon goals for operational cost reduction. |
| Direct-to-Consumer Channel Expansion | Bonded Shanghai warehouses collapse delivery latency below 48 hours for urban snack enthusiasts. |
Research Methodology
Cross-validation between cooperative processor interviews and customs trade data anchors the qualitative findings in verifiable shipment patterns. Primary fieldwork engaged almond growers in California's Central Valley, huller-sheller operations managers, Chinese e-commerce platform category leads, and Indian convenience retail procurement heads. Secondary validation drew from USDA National Agricultural Statistics Service reports, China Customs import declarations, California Department of Water Resources allocations data, and FDA food safety modernization compliance records. Bottom-up kernel volume estimates triangulate against top-down retail value assessments.
Calibration against historical price spreads between premium and commodity grades shapes the analytical framework across the analysis window. Segmentation dimensions span preparation method, packaging format, distribution channel, and customer archetype. CAGRs derive from trend extrapolation in flavor adoption curves and irrigation technology penetration rates. Forecast inputs incorporate SGMA groundwater basin sustainability timelines and Chinese live-commerce penetration velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light contract farming entrants would shift outcomes. Material shifts in California water rights adjudication or China's GB standard inspection protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Walnut Market
Nuts and Seeds
Hickory Nut Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
Strawberry Seed Oil Market
Nuts and Seeds
North America Hazelnut Market
Nuts and Seeds
China Almond Market
Nuts and Seeds
Seed Butter Market