
 Global Edible Nuts Market | 2026-2036
Global Edible Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Edible Nuts Market Analysis
California's almond processing capacity is hardening as drought-resilient orchard investments mature across the Central Valley. Blue Diamond Growers leverages its cooperative structure to control supply from thousands of growers. Olam International sustains a vertically integrated sourcing network spanning multiple origins. Wonderful Pistachios dominates branded retail shelf space with its integrated farming and packaging operations.
Edible nuts comprise the shelled or shelled kernels of tree nuts and groundnuts, typically containing 45-75% lipid content, 15-25% protein, and significant dietary fiber, micronutrients, and bioactive compounds such as polyphenols and phytosterols; primary commercial applications span direct consumption, ingredient formulations, and oil extraction for food and cosmetic industries. Almonds lead product type volumes due to their versatility across bakery, dairy alternative, and snack applications, while pistachios command premium positioning in confectionery and gift segments. Snack food end use captures the largest margin pool as single-serve and flavored formats expand, though ingredient-grade supply to plant-based meat and beverage manufacturers represents the fastest-growing demand channel.
FDA nutrition labeling requirements and USDA organic certification standards shape product formulation and market access for U.S.-origin nuts, while EFSA health claim evaluations and EU MRL regulations for aflatoxins govern European import acceptance. China's GB food safety standards and SAMR import protocols increasingly determine access to the world's largest inbound nut market. Stakeholders must monitor water rights allocations in California, phytosanitary barriers in key import markets, and the pace of regenerative agriculture adoption across supplier orchards.
Market Dynamics
California's water rights adjudication is squeezing orchard expansion timelines while regenerative agriculture mandates from EFSA and China's SAMR simultaneously reshape cultivation protocols across supplier bases.
Growth Catalysts
- Plant-Based Protein Substitution:Bakery and dairy alternative manufacturers are reformulating with almond and cashew bases to meet clean-label requirements. This ingredient pivot pulls volume from traditional animal protein supply chains.
- FDA Nutrition Label Modernization:Updated serving size declarations and added sugars line-item disclosure are forcing processors to reduce coating weights and oil applications. Reformulated products now qualify for front-of-pack health claims.
- Drought-Resilient Rootstock Deployment:Central Valley growers are grafting onto hybrid rootstocks that reduce water draw by one-third. Mature orchards planted during the 2018-2022 investment wave are reaching commercial bearing.
Market Restraints
- Input Cost Volatility:Fertilizer and agricultural chemical pricing tied to natural gas feedstocks creates margin compression for non-integrated processors. Smaller cooperatives lack hedging infrastructure.
- Geographic Supply Concentration:California's Central Valley produces over four-fifths of global almond volume. Single-region climate exposure—drought, frost, or fire—threatens annual crop reliability.
- Aflatoxin Regulatory Friction:EU MRL thresholds for aflatoxin B1 and total aflatoxins block significant shipment volumes at European ports. Rejection rates spike during high-temperature harvest windows.
Strategic Opportunities
- India Processing Infrastructure:Domestic cashew shelling and grading capacity expansion near Kerala and Maharashtra reduces dependence on Vietnamese intermediaries. FSSAI harmonization with Codex standards accelerates import clearance.
- Precision Fermentation Convergence:Nut protein isolates combined with microbial biomass cultivation enable hybrid dairy alternatives with superior mouthfeel. Beverage manufacturers are piloting these co-formulations.
- EU Green Deal Agricultural Transition:Carbon farming certification and organic conversion subsidies incentivize Mediterranean almond and hazelnut orchard renovation. Spanish and Italian growers access green financing for irrigation efficiency.
Industry Challenges
- Regenerative Agriculture Verification:Soil carbon measurement and biodiversity corridor documentation require agronomist field teams that most mid-tier cooperatives cannot staff. Third-party audit backlogs extend certification timelines.
- Optical Sorting Capex Burden:Hyperspectral detection systems for aflatoxin and shell fragment elimination cost several million dollars per processing line. Smaller facilities face equipment financing gaps.
- Traceability System Integration:Blockchain and ERP platform deployment across dispersed grower networks demands IT infrastructure that legacy cooperative governance structures struggle to fund and deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Edible Nuts Market |
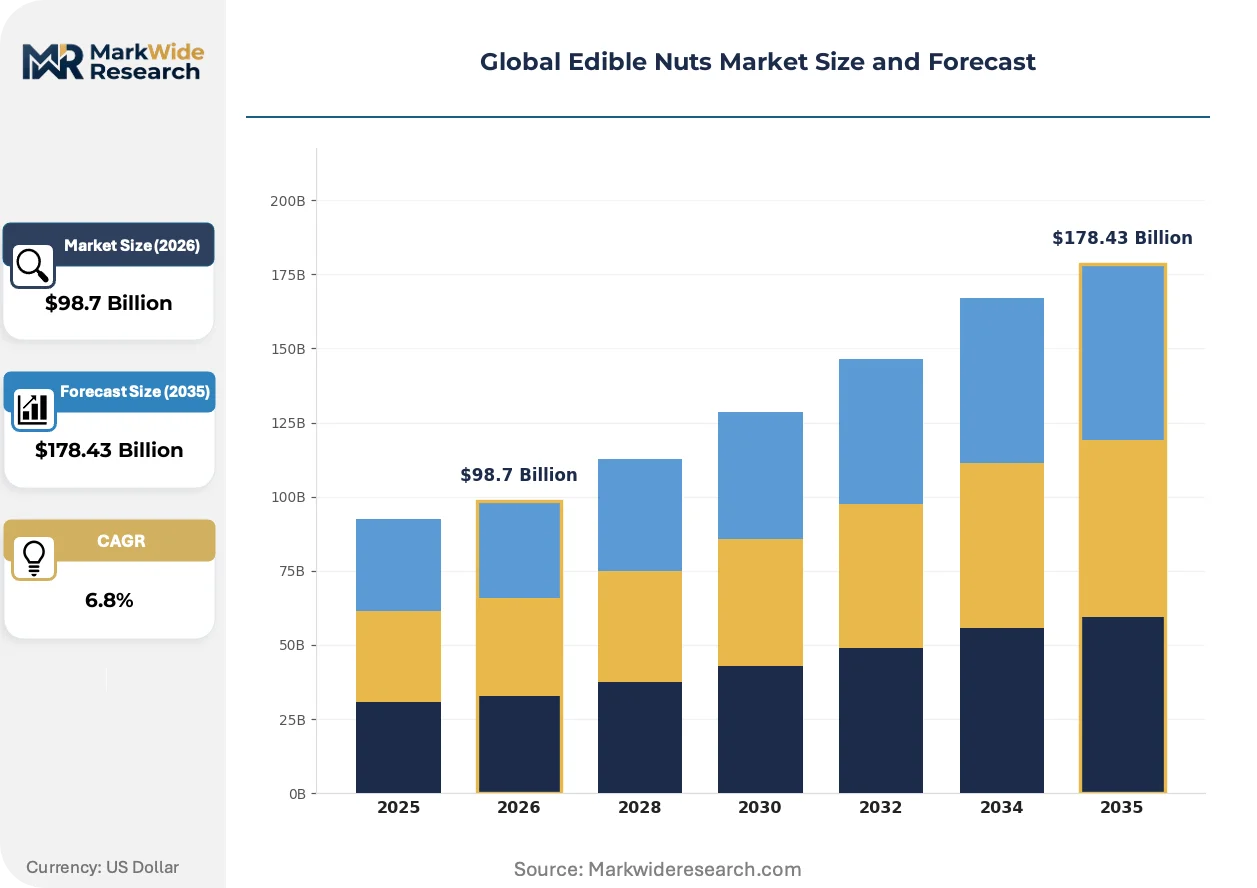
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almonds, Cashews, Walnuts, Pistachios End Use: Snack Food, Confectionery, Bakery, Ingredient Packaging Type: Bulk, Retail Packs, Vacuum Sealed, Eco-friendly Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Convenience Stores |
| Companies Covered | Blue Diamond Growers, Olam International, Archer Daniels Midland Company, Wonderful Pistachios, Mariani Nut Company, Select Harvests, Diamond Foods, Hormel Foods Corporation, The Wonderful Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Edible Nuts Market Emerging Trajectories
Processing technology and regulatory disclosure requirements are compressing supply chain tiers while reformulating product portfolios around protein density and clean-label positioning.
Hyperspectral imaging and AI-driven defect detection is unifying quality control across shelling, sorting, and packaging stages. Large-scale processors are retrofitting lines with integrated sensor arrays that simultaneously grade for size, color, and contamination. This convergence is compressing the gap between farm-gate and retail-ready specifications, reducing reprocessing and reject rates.
EFSA's updated health claim evaluation framework for tree nut cardiovascular benefits is forcing substantiation dossiers with human intervention trials. Processors must commission clinical studies to retain packaging claims. The snack and confectionery segments in Germany and France are reformulating to meet sodium and saturated fat thresholds that accompany permitted nut health messaging.
Direct-to-manufacturer contracting is displacing spot market purchases for ingredient-grade supply. Plant-based meat and beverage formulators in the Netherlands and California are signing multi-year offtake agreements with specified protein content and microbiological standards. This procurement consolidation is visible most acutely in almond butter and cashew cream supply channels.
Global Edible Nuts Market Segmentation
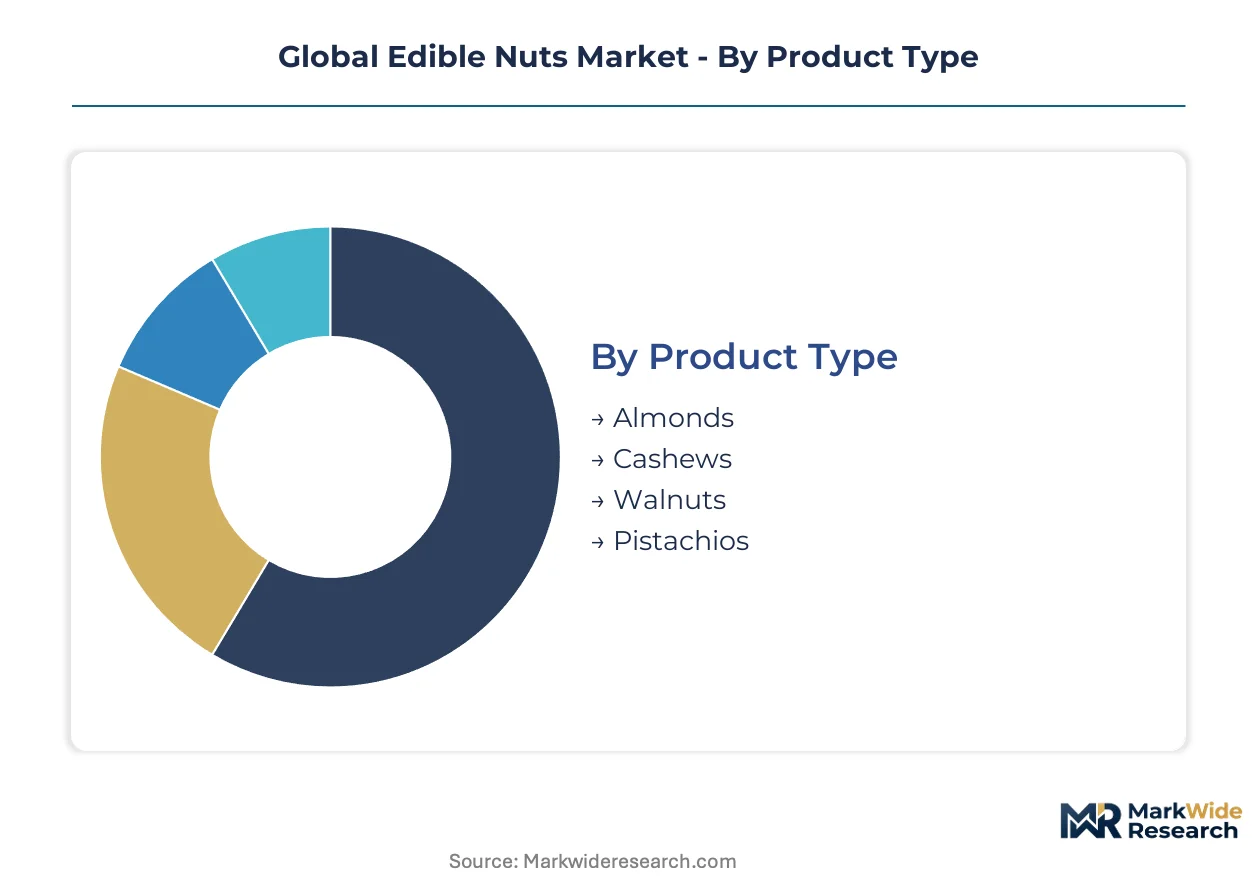
Segmentation in the edible nuts market exposes how processing specifications, packaging formats, and channel access determine margin capture. Each dimension reveals distinct competitive dynamics between commodity handlers and branded specialists.
Product Type:
Orchard investment cycles and rootstock maturation timelines create replacement-driven supply shifts across nut categories.
- Almonds:These kernels contain 45-55% lipid content and high protein density suited for dairy alternative formulations. California's Central Valley orchards supply the bulk of global volume, with plant-based beverage manufacturers in the Netherlands and California pulling ingredient-grade shipments.
- Cashews:Characterized by 46-50% fat content and creamy texture ideal for confectionery and vegan cheese applications. Processing capacity expansion near Kerala and Maharashtra is reducing dependence on Vietnamese intermediaries for European and North American buyers.
- Walnuts:Higher polyunsaturated fat ratios support cardiovascular health positioning in bakery and cereal segments.
- Pistachios:Premium shell-on formats dominate gift and seasonal confectionery channels with limited substitution elasticity.
Almonds sit at the top of the volume ranking, with cashews climbing the fastest.
End Use:
Application-specific microbiological standards and protein content thresholds split procurement between spot-market commodity buyers and contract-bound manufacturers.
- Snack Food:Single-serve and flavored formats command the widest margin pool as FDA serving size disclosures reshape coating formulations. Retail shelf space competition between Wonderful Pistachios and Blue Diamond Growers intensifies in US supermarkets.
- Ingredient:Almond butter and cashew cream supply channels face the steepest expansion trajectory as plant-based meat formulators in California and the Netherlands sign multi-year offtake agreements with specified protein content standards.
- Confectionery:Premium positioning in gift segments requires EFSA-compliant health claim substantiation for cardiovascular benefits.
- Bakery:Volume applications favor paste and meal formats with lower defect tolerance than whole-kernel specifications.
Snack food captures the largest margin pool, while ingredient-grade supply expands most quickly.
Packaging Type:
Cost-to-protection ratios and sustainability credentials determine format selection across supply chain tiers.
- Retail Packs:Stand-up pouches and resealable formats dominate branded shelf presence with front-of-pack health claim visibility. EPR regulations in France and Germany are mandating recyclable film structures that increase unit costs.
- Bulk:Foodservice and industrial ingredient channels favor 25-50 pound sacks with modified atmosphere preservation. Port consolidation near Oakland and Rotterdam handles the highest throughput volumes.
- Vacuum Sealed:Extended shelf life applications for export markets require oxygen barrier performance that justifies premium positioning.
- Eco-friendly:Compostable and fiber-based formats gain traction in EU Green Deal-aligned markets with carbon farming certification requirements.
Retail packs lead value capture, with eco-friendly formats gaining share fastest.
Distribution Channel:
Channel control determines access to consumer data and formulation feedback loops that shape product development.
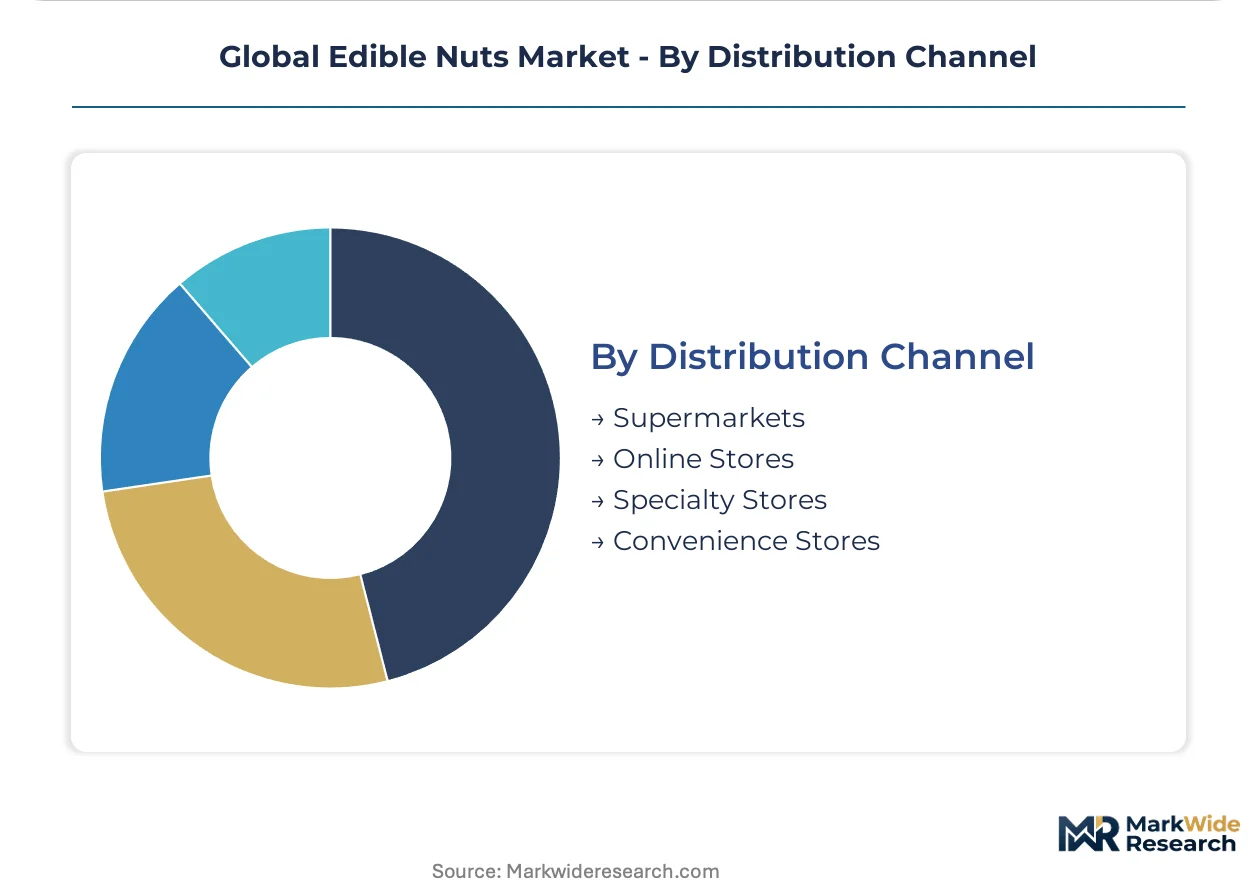
- Supermarkets:Category management agreements with Kroger, Walmart, and Tesco allocate shelf space based on velocity and promotional commitment. Private label expansion compresses branded margin structures.
- Online Stores:Direct-to-consumer subscription models and Amazon pantry fulfillment expose regional taste preferences that inform flavor innovation pipelines.
- Specialty Stores:Organic and gourmet positioning in Whole Foods and regional cooperatives commands certification premiums.
- Convenience Stores:Impulse-oriented single-serve formats with limited SKU depth prioritize grab-and-go packaging dimensions.
Supermarkets anchor volume throughput, with online stores expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping orchard investment flows as compliance cost gaps between California's water-adjudication regime and Australia's Murray-Darling Basin create divergent expansion incentives for almond and pistachio cultivation.
United States
Plant-based beverage manufacturers in California's Central Valley pull ingredient-grade almond shipments at specified protein thresholds. FDA nutrition labeling modernization forces coating-weight reductions on flavored nut processors. Fresno and Kern County orchards deploy drought-resilient rootstocks as water rights allocations tighten.
Spain
EU Green Deal agricultural transition subsidies accelerate almond and hazelnut orchard renovation across Andalusia. EFSA health claim substantiation requirements for cardiovascular benefits reshape confectionery formulation standards. Valencia and Catalonia processing clusters capture carbon farming certification premiums for Mediterranean-origin supply.
India
Domestic cashew shelling capacity expansion near Kerala and Maharashtra reduces dependence on Vietnamese intermediaries for European buyers. FSSAI harmonization with Codex standards accelerates import clearance timelines. Goa and Mangalore grading facilities scale optical sorting infrastructure to meet EU aflatoxin MRL thresholds.
China
SAMR import protocols and GB food safety standards increasingly determine access conditions for inbound almond and pistachio shipments. Plant-based meat formulators in Shanghai and Hangzhou sign multi-year offtake agreements with specified microbiological standards. Xinjiang walnut processing clusters expand paste and meal format output for bakery ingredient channels.
Australia
Murray-Darling Basin water trading schemes enable almond orchard expansion in South Australia and Victoria with lower compliance burdens than California counterparts. Precision fermentation convergence trials near Melbourne combine nut protein isolates with microbial biomass for hybrid dairy alternatives. Riverland processing facilities retrofit hyperspectral sorting lines to meet EFSA contamination standards.
Global Edible Nuts Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and regenerative agriculture certification vectors. Cooperative structures control upstream supply from dispersed grower bases while integrated farming operations capture branded retail shelf space. Three archetypes dominate: vertically integrated orchard-to-shelf operators, commodity traders with multi-origin sourcing networks, and specialty processors focused on ingredient-grade contract manufacturing. Capacity expansion and direct-to-manufacturer contracting represent the dominant competitive moves as spot market purchases decline.
Among cooperative-structured handlers, Blue Diamond Growers exemplifies grower-owned supply aggregation. Wonderful Pistachios anchors the integrated farming-to-retail archetype with in-house orchard and packaging operations. Olam International occupies the multi-origin sourcing tier with vertically controlled networks spanning multiple production regions. These three entities represent distinct strategic positions without implying specific market share or operational scale claims.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| Olam International |
| Archer Daniels Midland Company |
| Wonderful Pistachios |
| Mariani Nut Company |
| Select Harvests |
| Diamond Foods |
| Hormel Foods Corporation |
| The Wonderful Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap cooperatives across California's Central Valley anchor upstream supply aggregation, translating water rights scarcity into disciplined contract pricing that shields integrated processors from spot market volatility while squeezing non-integrated handlers.
Pricing Analysis
Distributor margin capture varies sharply by channel tier. Three-tier pricing structure across premium organic, standard commodity, and economy bulk grades reflects certification tier and volume scale. Pricing pressure stems from fertilizer cost volatility tied to natural gas feedstocks. Ingredient-grade buyers in plant-based manufacturing exhibit lowest price sensitivity due to protein content specifications, while conventional snack food channels face margin compression from private label expansion.
Supply Chain Analysis
Water access rests on adjudicated rights allocations in California's Central Valley, where almond production draws from hybrid rootstock deployments and precision irrigation infrastructure. Raw material dependencies include fertilizer inputs, agricultural chemicals, and pollinator services. Single-region climate exposure—drought, frost, or fire—creates annual crop reliability risk. Distribution runs through Oakland and Rotterdam port consolidation for export markets, with domestic U.S. flows direct to processor facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with FDA nutrition label modernization and EFSA health claim substantiation requirements continuously reshaping formulation standards and procurement specifications.
For Market Incumbents: Extend drought-resilient rootstock coverage across remaining legacy orchard acreage to defend against climate-driven supply disruption. Deepen backward integration into precision fermentation capabilities for hybrid dairy alternative formulations. Lock multi-year offtake agreements with plant-based meat manufacturers to secure ingredient-grade volume commitments before spot market liquidity erodes further. For New Entrants and Emerging Players: Specialty stores and direct-to-manufacturer channels offer the most penetrable entry vectors, bypassing supermarket category management barriers controlled by established brands. Target India's domestic cashew processing infrastructure expansion near Kerala and Maharashtra, where FSSAI harmonization reduces import clearance friction. Lead with carbon farming certification and regenerative agriculture verification to capture EU Green Deal subsidy-aligned procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier cooperatives lacking optical sorting infrastructure and blockchain traceability deployment. Five-to-ten year viability hinges on water rights security and phytosanitary compliance infrastructure. Monitor EU aflatoxin MRL rejection rate spikes as the clearest inflection signal for supply availability and pricing volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification | Carbon farming credentials unlock EU Green Deal subsidies and premium procurement contracts from EFSA-aligned buyers. |
| Precision Fermentation Integration | Nut protein isolate cultivation near Melbourne combines with microbial biomass for hybrid dairy alternatives with superior mouthfeel. |
| Hyperspectral Sorting Deployment | AI-driven defect detection reduces reprocessing rates and satisfies EFSA contamination standards for European export acceptance. |
| Direct-to-Manufacturer Contracting | Multi-year offtake agreements with Dutch and California plant-based formulators displace spot market purchases in ingredient channels. |
| India Processing Infrastructure Expansion | Domestic cashew shelling capacity near Kerala reduces Vietnamese intermediary dependence and accelerates FSSAI-clearance timelines. |
Methodological Framework
Multiple input streams — processor procurement records, orchard water rights filings, and retail velocity data — were reconciled through bottom-up and top-down triangulation. Primary interviews with cooperative board members, Central Valley farm managers, EFSA regulatory affairs specialists, and Dutch plant-based formulation R&D directors informed supply-side constraints and demand specifications. Secondary validation drew from USDA NASS crop reports, FDA labeling guidance documents, EU MRL enforcement data, and customs trade flow records.
Data-stream reconciliation across product type, end-use application, packaging format, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume and value build-ups. Forecast inputs incorporated water rights adjudication timelines, rootstock maturation curves, and regulatory compliance cost trajectories specific to aflatoxin detection and regenerative agriculture verification.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to California drought severity, EU MRL threshold adjustments, and China's SAMR import protocol evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
Macadamia Nut Market
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Walnut Market
Nuts and Seeds
Almond Protein Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Bambara Beans Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
Cashew Roasting Machine Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
North America Peanut Butter Market
Nuts and Seeds
Europe Nut-Based Spreads Market