
 Pecans Market | 2026-2036
Pecans Market Size, Share, and Industry Trends Forecast 2026-2036
Pecans Market Analysis
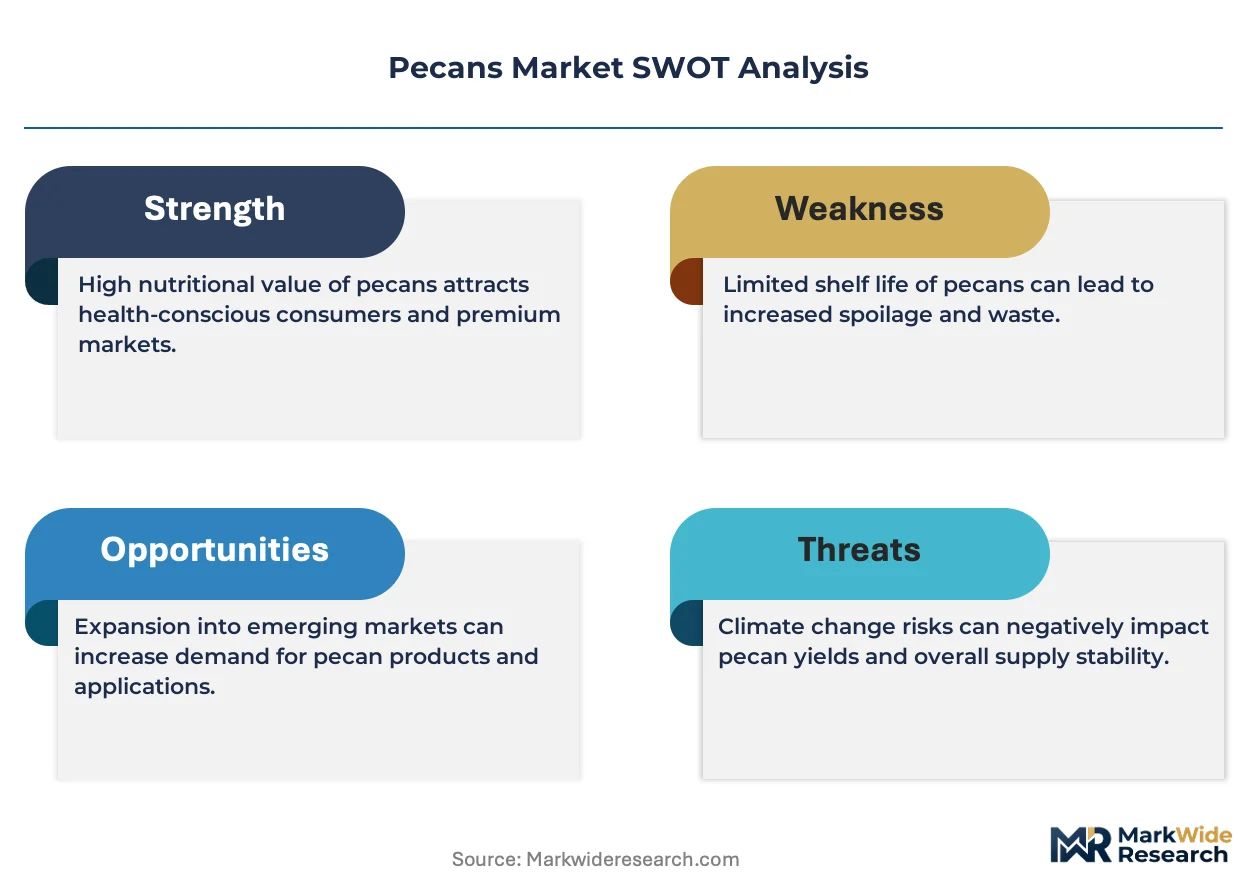
The pecan trade is pivoting between premium cultivar segments and commodity bulk supply as shellers and processors split pricing power along quality grades. John B. Sanfilippo & Son leverages its integrated roasting and packaging infrastructure to capture margin in branded snack channels. Diamond Foods sustains volume leadership through bulk supply contracts with national retailers. Royalty Pecan Farms differentiates via direct-to-consumer specialty sales of native and improved varieties.
Pecans are the edible seeds of Carya illinoinensis, a hardwood tree native to North America, containing approximately 70% oil and 9% protein by weight, with commercial harvest determined by kernel color, size, and moisture content below 6%. The nuts serve as a functional ingredient in baked goods, confections, and pressed oil applications where lipid stability and flavor profile matter. Raw pecans occupy the largest volume share across export and domestic channels, while pecan oil commands the fastest value expansion in specialty food and cosmetic formulations. Food industry buyers represent the deepest demand pool, though snack manufacturers are pulling increasing share as clean-label protein positioning intensifies.
The USDA Agricultural Marketing Service sets official standards for pecan grades, kernel sizes, and inspection protocols that shape export eligibility and domestic wholesale pricing. FDA food safety rules under FSMA govern preventive controls for pecan processing facilities, while state agriculture departments in Georgia and Texas administer additional sheller licensing and weights-and-measures enforcement. Stakeholders must monitor how climate volatility and water allocation disputes across southwestern growing regions reshape supply reliability and varietal planting decisions.
Market Dynamics
Snack manufacturers' clean-label protein positioning is pulling pecan demand away from traditional baking channels, while USDA grading standards tighten quality premiums across export and domestic wholesale tiers.
Growth Catalysts
- Clean-Label Snack Positioning:Protein-forward nut mixes in convenience retail channels are absorbing shelled pecan volumes previously directed to commodity baking applications.
- USDA AMS Grading Standards:Official kernel size and color classifications are creating export eligibility tiers that reward premium cultivar investment in Georgia and Texas orchards.
- Pecan Oil Extraction:Cold-press lipid recovery for cosmetic and specialty food formulations is expanding value capture beyond kernel sales.
Market Restraints
- Input Cost Volatility:Irrigation water allocation disputes across southwestern growing regions inflate per-acre production costs unpredictably.
- Supply Concentration Risk:Georgia and Texas together dominate commercial harvest, exposing buyers to localized climate volatility and freeze-loss events.
- Substitution Threat:Almonds and walnuts compete aggressively in snack mix and baking applications on price and protein-equivalence metrics.
Strategic Opportunities
- Direct-to-Consumer Specialty Channels:Native and improved variety differentiation through farm-branded e-commerce bypasses commodity sheller pricing.
- Cosmetic Formulation Expansion:Pecan oil's lipid stability profile aligns with clean beauty ingredient mandates in European and North American personal care markets.
- FSMA Preventive Controls Alignment:FDA food safety modernization creates competitive moats for processors with validated hazard analysis and critical control point systems.
Industry Challenges
- Skilled Orchard Labor Scarcity:Mechanical harvesting technology adoption lags behind wage inflation for hand-collection crews in mature tree zones.
- Multi-Year Cultivar Conversion Cycles:Grafting improved varieties onto native rootstock demands capital commitment with delayed yield recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pecans Market |
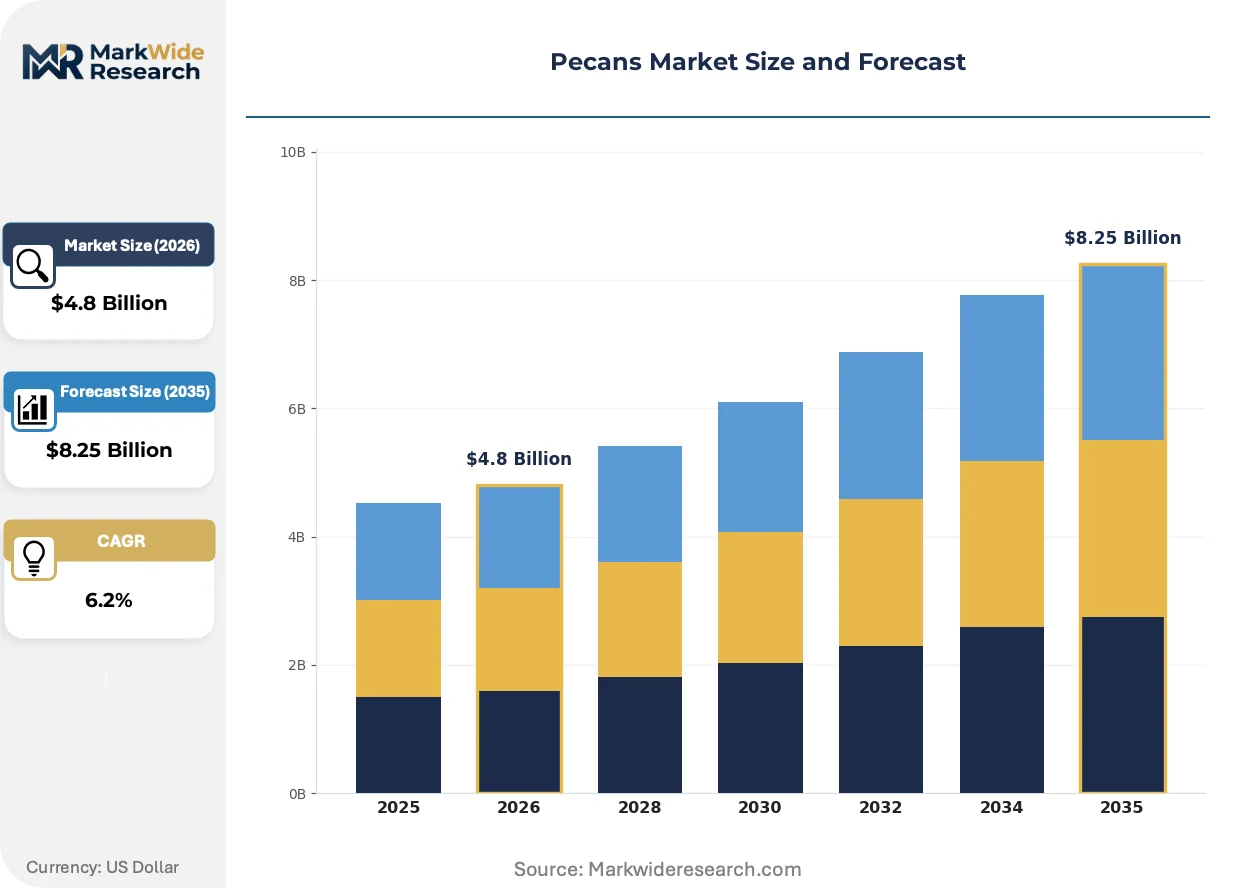
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Pecans, Roasted Pecans, Pecans Flour, Pecans Oil End User: Food Industry, Bakery Sector, Snack Manufacturers, Confectioneries Packaging Type: Bags, Bulk Containers, Sachets, Bottles Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | Royalty Pecan Farms, Merritt Pecan, Navarro Pecan Company, Lamar Pecan Company, Ellis Bros. Pecans, John B. Sanfilippo & Son, Diamond Foods, National Pecan Company, Shamrock Ranch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pecans Market Emerging Trajectories
Processing technology and regulatory alignment are reshaping how pecans move from orchard to end-use, with quality verification systems and extraction methods opening new value tiers.
Optical sorting systems using near-infrared spectroscopy are expanding into kernel defect detection and moisture verification at shelling facilities. Mid-scale processors in Texas and Georgia are adopting these units to reduce manual inspection labor and meet USDA export certification requirements. This technology diffusion is compressing price spreads between hand-sorted and machine-graded lots.
FSMA preventive controls for tree nut processing are mandating environmental monitoring and supply chain traceability systems across FDA-regulated facilities. Shellers must now validate kill-step effectiveness for Salmonella reduction in roasted product streams. Small-to-mid scale operations face disproportionate compliance costs relative to integrated processors with captive laboratory capacity.
Buyer consolidation among national snack brands is concentrating procurement decisions into fewer category managers demanding multi-year volume commitments. Direct orchard relationships are displacing spot market purchases for premium cultivar supply. This pattern is most visible in Georgia, where branded snack manufacturers now contract forward for specific kernel sizes and color grades.
Pecans Market Segmentation
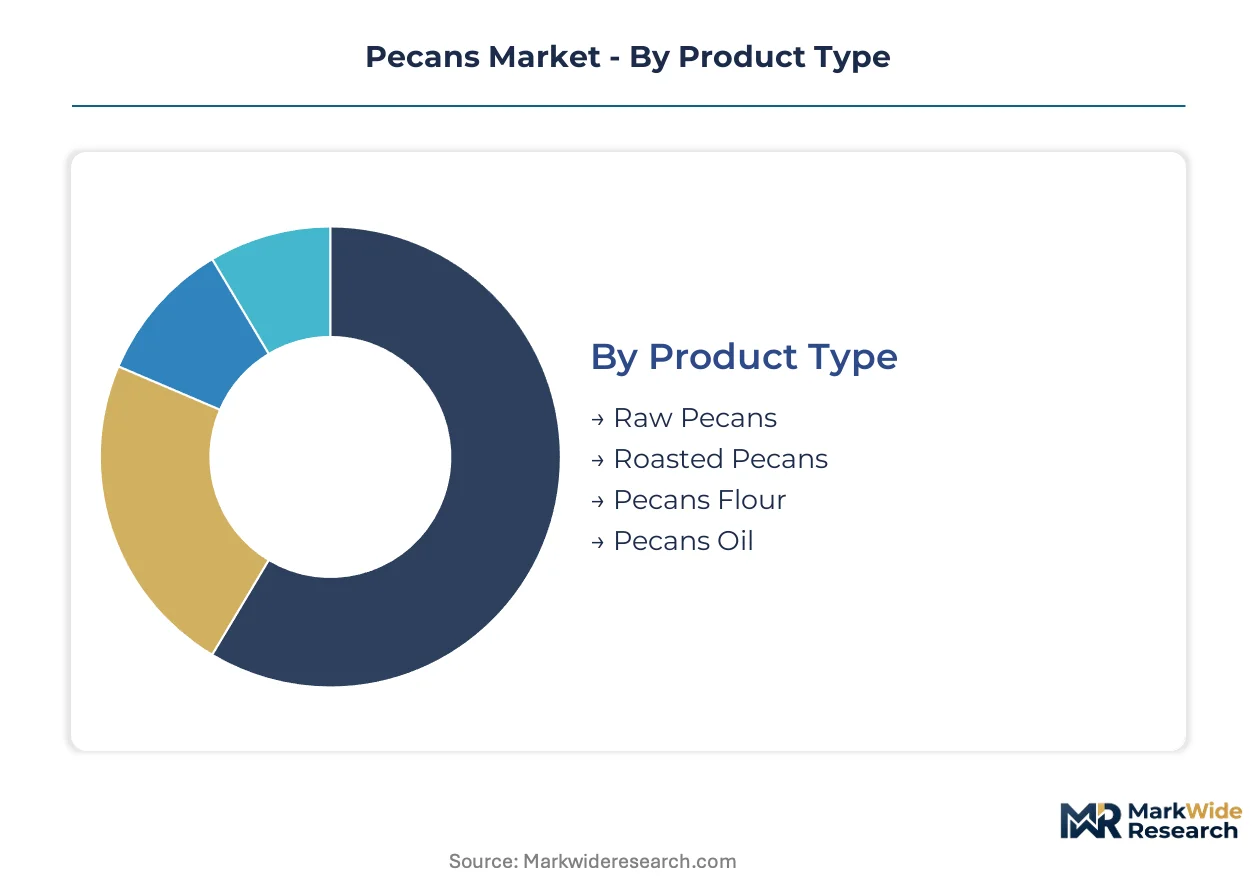
Pecan segmentation reflects divergent paths between commodity bulk supply and premium value-added formats. Kernel processing depth and packaging sophistication determine margin capture across distinct buyer workflows.
Product Type:
Customization spans minimally processed kernels through cold-pressed lipid extraction, with standardization concentrated in bulk sheller output grades.
- Raw Pecans:Shelled kernels with moisture content below 6% serve as the foundational input for baking, roasting, and oil extraction operations. Food manufacturers across Georgia and Texas absorb the largest volumes for internal processing lines, though price volatility in southwestern irrigation districts constrains contract reliability.
- Pecans Oil:Cold-pressed lipid recovery yields approximately 70% oil by kernel weight, prized in cosmetic formulations for oxidative stability and clean-label positioning. European personal care buyers and North American specialty food channels are pulling supply away from traditional kernel markets.
- Roasted Pecans:Dry-roasted or oil-roasted kernels with validated kill-step documentation for FSMA compliance.
- Pecans Flour:Finely milled defatted meal for gluten-free baking applications.
Most installed capacity flows through Raw Pecans. Expansion is steepest in Pecans Oil.
End User:
Volume concentration sits with industrial food processors, while margin expansion tracks toward branded snack positioning and direct-to-consumer specialty channels.
- Snack Manufacturers:Clean-label protein-forward nut mixes in convenience retail are absorbing shelled pecan volumes previously directed to commodity baking. National brands now contract forward for specific kernel sizes and color grades from Georgia orchards, displacing spot market purchases.
- Food Industry:Broad industrial demand spans pressed oil, dairy alternatives, and functional ingredient applications where lipid profile and protein content matter. USDA grading standards for kernel color and size create eligibility tiers that shape procurement decisions across domestic and export channels.
- Bakery Sector:Traditional pie fillings and pastry applications requiring consistent kernel integrity.
- Confectioneries:Praline and chocolate-enrobed applications demanding uniform piece sizing.
Procurement concentration is heaviest in Snack Manufacturers. Margin capture is climbing fastest in Food Industry specialty oil extraction.
Packaging Type:
Format selection tracks buyer scale and shelf-life requirements, from multi-ton bulk shipments to single-serve portion control.
- Bulk Containers:Fiber drums and supersacks dominate sheller-to-processor transfers, with nitrogen flushing extending storage stability for industrial buyers. Texas and Georgia distribution hubs handle the largest volumes for domestic food manufacturing and export consolidation.
- Bags:Retail-ready pillow packs and stand-up pouches with oxygen barrier films for branded snack channels. National retailers are consolidating procurement into fewer category managers demanding multi-year volume commitments with specific packaging specifications.
- Sachets:Single-serve portions for hospitality and airline catering channels.
- Bottles:Glass and PET formats for pecan oil in specialty food and cosmetic retail.
Throughput peaks in Bulk Containers. Value expansion is sharpest in Bags.
Distribution Channel:
Channel selection reflects buyer urgency, order scale, and quality verification requirements across spot and contract purchasing patterns.
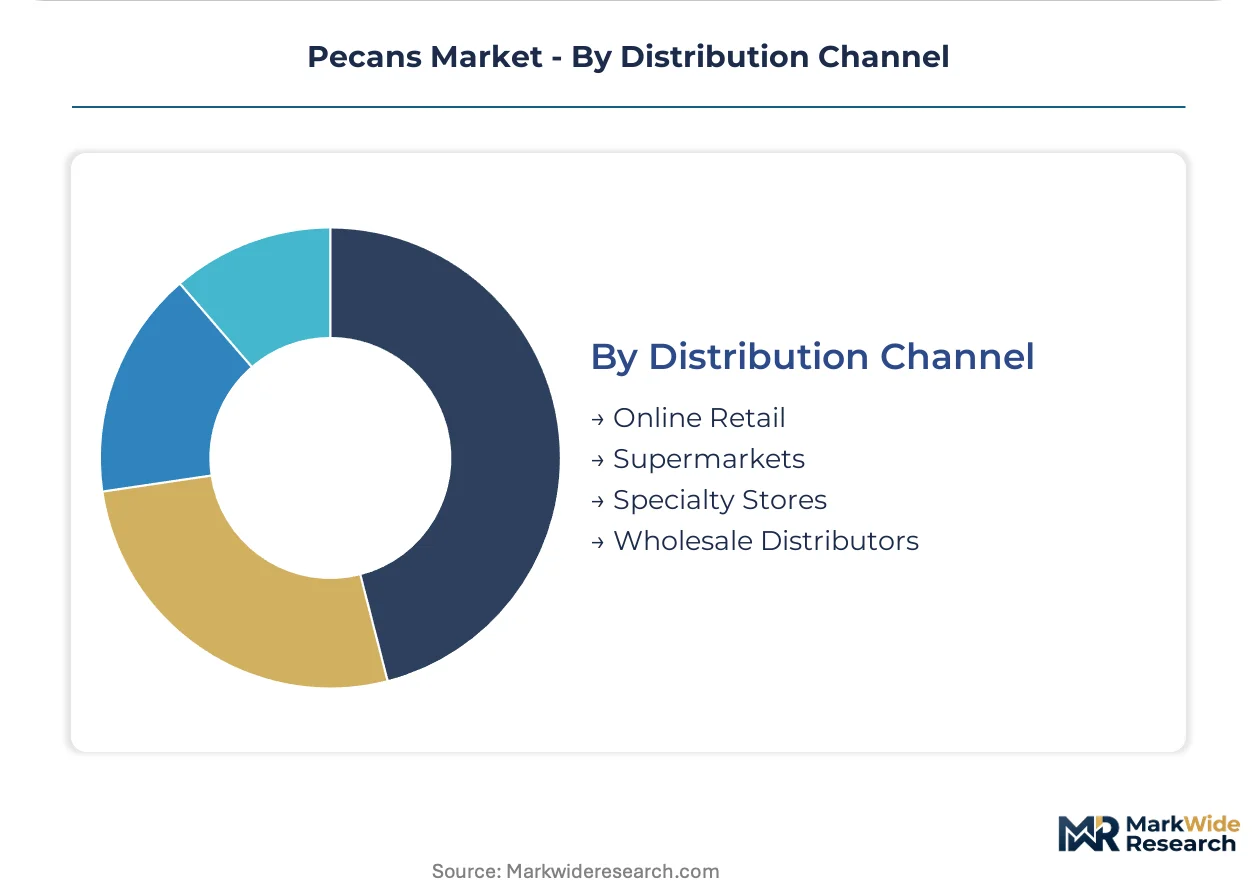
- Wholesale Distributors:Regional nut brokers and foodservice wholesalers aggregate sheller output for redistribution to mid-scale bakeries and confectioneries. Georgia-based distributors maintain the deepest relationships with improved variety orchards, while Texas operators specialize in native pecan sourcing.
- Online Retail:Farm-branded e-commerce channels enable direct-to-consumer specialty sales of native and improved varieties, bypassing commodity sheller pricing. Royalty Pecan Farms and similar operations capture premium margins through subscription and gift box formats.
- Supermarkets:National and regional grocery chains with private label and branded nut set placement.
- Specialty Stores:Gourmet food retailers and natural products channels emphasizing provenance and cultivar differentiation.
Volume concentration remains in Wholesale Distributors. Share gain is most rapid in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled orchard labor pools in the southeastern United States anchor commercial pecan production capacity, while mechanization adoption lags behind wage inflation across mature tree zones in southwestern growing belts.
United States
Georgia and Texas together dominate commercial harvest, with Albany and San Saba serving as distribution hubs for sheller-to-processor transfers. USDA Agricultural Marketing Service grading standards for kernel size and color create export eligibility tiers that reward premium cultivar investment. FDA FSMA preventive controls mandate environmental monitoring and supply chain traceability systems across processing facilities.
Mexico
Chihuahua and Sonora states are expanding irrigated orchard acreage to serve North American snack manufacturer demand. The country's national agriculture department administers phytosanitary certification protocols for cross-border kernel shipments. Ciudad Juárez processing clusters are adopting optical sorting systems to meet USDA export requirements.
Australia
New South Wales Riverina district pecan growers are targeting Asian cosmetic formulation channels with cold-pressed oil extraction capacity. Australian Quarantine and Inspection Service biosecurity protocols govern import eligibility for improved variety rootstock. Moree processing facilities are expanding nitrogen-flushed bulk container output for industrial food manufacturing buyers.
South Africa
Limpopo and Mpumalanga provinces are developing native pecan cultivar differentiation for European specialty food channels. The country's national agricultural product standards regulator enforces kernel moisture and defect tolerances for export consolidation. Tzaneen orchard clusters are experimenting with mechanical harvesting technology to offset skilled labor scarcity.
China
Yunnan and Sichuan provinces are trialing Carya illinoinensis cultivation for domestic snack and traditional medicine applications. SAMR food safety standards govern additive limits and labeling requirements for roasted nut products. Kunming processing cooperatives are importing US shelling equipment to upgrade kernel grading consistency.
Pecans Market Vendor Landscape
Top-tier vendors anchor integrated roasting and packaging infrastructure, while mid-scale shellers compete on bulk supply contracts and native variety sourcing. The competitive terrain splits between branded snack channel margin capture and commodity kernel volume leadership. Three archetypes dominate: vertically integrated processors with captive laboratory capacity, regional shellers with deep improved variety orchard relationships, and direct-to-consumer specialty farms with cultivar differentiation. M&A activity concentrates on sheller-processor consolidation in Georgia and Texas, while strategic partnerships between snack manufacturers and specific orchards displace spot market purchasing.
Within the integrated-processor tier, John B. Sanfilippo & Son and Diamond Foods occupy positions exemplifying divergent competitive vectors—one leveraging branded channel infrastructure, the other sustaining volume leadership through retail supply contracts. Royalty Pecan Farms represents the direct-to-consumer specialty archetype, bypassing commodity sheller pricing through farm-branded subscription formats. These three entities collectively illustrate how quality grade stratification and channel selection determine margin capture across the pecan value chain.
| Leading Market Players |
|---|
| Royalty Pecan Farms |
| Merritt Pecan |
| Navarro Pecan Company |
| Lamar Pecan Company |
| Ellis Bros. Pecans |
| John B. Sanfilippo & Son |
| Diamond Foods |
| National Pecan Company |
| Shamrock Ranch |
| Others |
Supply Flow & Price Mechanics
Optical sorting systems using near-infrared spectroscopy are compressing labor costs at shelling facilities while simultaneously concentrating procurement leverage among processors with capital to adopt USDA-compliant grading infrastructure. This technology diffusion redraws margin allocation between hand-sorted and machine-graded lots across Georgia and Texas distribution hubs.
Pricing Analysis
Sheller-to-processor transfers and farm-branded direct sales operate on divergent pricing models. Three-tier pricing structure across premium, standard, and economy levels reflects USDA kernel color grades, moisture verification, and organic certification status. Cost compression in commodity bulk channels is intensifying because snack manufacturers are consolidating procurement into multi-year volume commitments. Food industry buyers exhibit highest price sensitivity due to substitution-ready almond and walnut alternatives, while cosmetic formulation channels show lowest sensitivity given pecan oil's oxidative stability premium.
Supply Chain Analysis
Single-source vulnerability sits with Georgia and Texas orchards, which together anchor commercial harvest capacity for North American demand. The supply chain draws from native rootstock nurseries, irrigation equipment suppliers, and nitrogen-flushed bulk container manufacturers. Tariff exposure runs through cross-border kernel shipments from Chihuahua and Sonora processing clusters. Distribution runs through Albany and San Saba sheller-to-processor hubs, with forward contracting displacing spot market purchases among national snack brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pecan market positioning functions as a geographic-arbitrage play between southwestern US irrigation cost inflation and Mexican orchard expansion under lower water allocation pressures. This cost differential shapes varietal investment decisions across the value chain.
For Market Incumbents: Acquire cold-press oil extraction capacity to capture cosmetic formulation premiums before European personal care buyers consolidate supplier bases. Backward integration into improved variety orchards in Georgia defends against direct-to-consumer farm brands eroding sheller margins. FSMA-validated kill-step documentation creates regulatory moats that smaller processors cannot replicate.
For New Entrants and Emerging Players: A mid-tier price-point gap between commodity sheller output and farm-branded specialty channels enables white-space entry through subscription-format native pecan sales. Target online retail distribution with cultivar-differentiated gift box positioning. Bypass wholesale distributor markups by building direct orchard relationships in Texas native growing belts.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale shellers lacking branded channel infrastructure or oil extraction capabilities. Long-term viability hinges on climate adaptation investments and mechanical harvesting technology adoption. Watch freeze-loss frequency in southwestern growing regions as the inflection signal for supply reliability repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchards | Captive supply of improved varieties secures premium kernel grades for branded snack contracts. |
| Cold-Press Oil Extraction Capacity | Cosmetic formulation demand in European markets pulls supply away from commodity kernel channels. |
| FSMA Preventive Controls Certification | Validated Salmonella reduction systems create competitive barriers for FDA-regulated processing facilities. |
| Direct-to-Consumer Channel Launch | Farm-branded e-commerce bypasses sheller pricing and captures subscription revenue from specialty buyers. |
| Optical Sorting Technology Deployment | Near-infrared spectroscopy reduces manual inspection labor and meets USDA export certification requirements. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged sheller operations managers, snack manufacturer procurement directors, cosmetic formulation buyers, orchard owners in Georgia and Texas, and USDA Agricultural Marketing Service grading inspectors. Secondary validation drew from FDA FSMA guidance documents, USDA pecan grade standards, customs trade records for kernel shipments, and state agriculture department licensing databases. Bottom-up orchard yield estimates and top-down snack industry consumption patterns were triangulated against processing capacity surveys.
Historical reference periods anchored the projection horizon to documented harvest volumes, price spreads between native and improved varieties, and channel shift patterns from wholesale to direct-to-consumer sales. Segmentation modeling spanned product type, end-user industry, packaging format, and distribution channel, with kernel size and color grade as industry-specific dimensions. CAGRs were derived from trend extrapolation of varietal planting rates, mechanical harvesting adoption curves, and cosmetic oil extraction capacity expansion. Irrigation water allocation disputes and freeze-loss frequency served as scenario-weighting inputs.
Caveats apply where climate volatility, regulatory enforcement shifts, or substitution acceleration could materially shift the outlook. Forecasts reflect assumptions about sustained snack manufacturer demand and European cosmetic channel penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
Spain Fox Nuts Market
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Almond Kernels Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Rubus Idaeus (Raspberry) Seeds Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
Hickory Nut Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Asia-Pacific Hazelnut Market
Nuts and Seeds
Butyrospermum Parkii Market
Nuts and Seeds
Soy Nut Market
Nuts and Seeds
Seed Butter Market
Nuts and Seeds
Maca Market
Nuts and Seeds
Tree Nut Allergy Market
Nuts and Seeds
Bambara Beans Market