
 Horse Chestnut Seed Extract Market | 2026-2036
Horse Chestnut Seed Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Horse Chestnut Seed Extract Market Foresight
Skilled phytochemists with extraction-standardization expertise is reorganizing competitive dynamics in botanical extract manufacturing. Indena S.p.A. leverages decades of aescin fractionation know-how to dominate high-purity active pharmaceutical ingredient supply. Martin Bauer Group anchors European bulk extract output through backward integration into raw seed sourcing networks. Bio-Botanica Inc. competes on North American private-label contract manufacturing for supplement brands seeking domestic supply security.
Horse chestnut seed extract comprises triterpene saponins—principally aescin—typically standardized to 16-20% aescin content via ethanol-water extraction followed by liquid-liquid purification for venotonic and anti-edema applications. Standardized extracts command premium positioning in pharmaceutical channels where batch-to-batch consistency determines formulary acceptance, while whole herb formulations occupy price-sensitive direct-to-consumer segments. Liquid extracts lead hospital and clinic dispensing formats, whereas capsules dominate pharmacy and online retail velocity. Combination formulas pairing aescin with bioflavonoids represent the fastest-growing formulation category as formulators target enhanced vascular permeability outcomes.
EMA's Committee on Herbal Medicinal Products governs European market access through monograph compliance for well-established use indications, while FDA's dietary supplement Current Good Manufacturing Practice regulations enforce identity testing and contamination limits for US-bound products. Germany's Commission E approvals for oral and topical horse chestnut preparations create de facto demand anchors that other EU national regulators reference. Stakeholders must monitor evolving pharmacovigilance requirements for botanical cardiovascular agents as regulators tighten post-market surveillance frameworks.
Market Dynamics
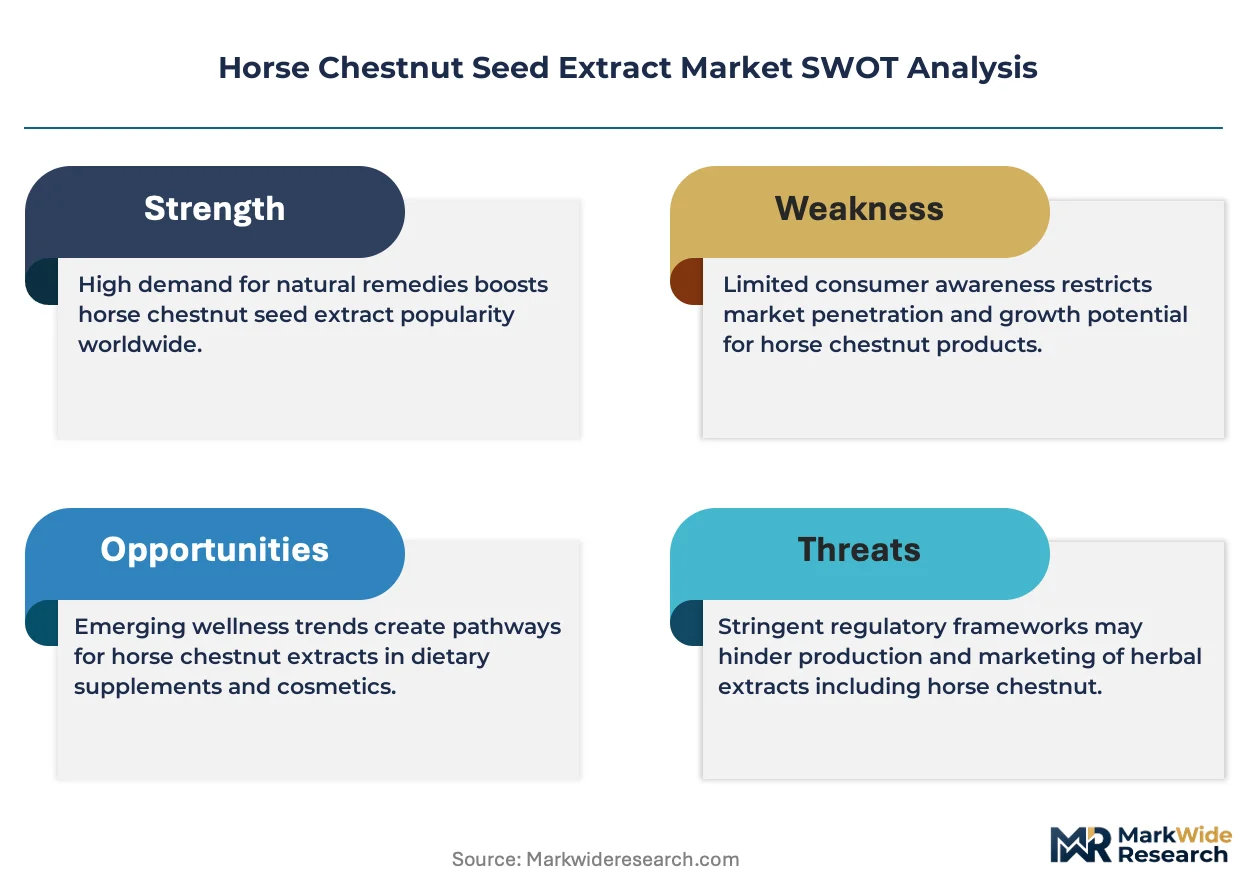
EMA's Committee on Herbal Medicinal Products is tightening monograph compliance requirements for aescin-containing preparations, forcing extractors to upgrade analytical capabilities and documentation protocols to maintain European market access.
Growth Catalysts
- Chronic venous insufficiency prevalence:Aging populations in Germany and Austria are expanding the addressable patient pool for venotonic therapies, with phytotherapy maintaining strong reimbursement positioning.
- EU Traditional Herbal Medicines Directive:Harmonized quality benchmarks are consolidating demand around certified suppliers capable of batch-to-batch aescin standardization.
- Ethanol-water extraction refinement:Advanced liquid-liquid purification methods are improving yield rates and reducing solvent residue concerns in pharmaceutical-grade output.
Market Restraints
- Raw seed supply concentration:Balkan and Eastern European sourcing regions face climate volatility and collection labor shortages, creating input price instability.
- Substitution by synthetic venotonics:Diosmin-hesperidin combinations and calcium dobesilate formulations compete on prescription familiarity and faster regulatory pathways.
- EMA pharmacovigilance burden:Post-market surveillance requirements for cardiovascular botanicals are extending compliance timelines and raising documentation costs.
Strategic Opportunities
- Topical formulation expansion:Cosmetic and dermocosmetic channels in France and Spain are absorbing lower-grade extracts for anti-cellulite and microcirculation products.
- Combination formula development:Pairing aescin with bioflavonoids targets enhanced vascular permeability outcomes in sports medicine and post-surgical recovery segments.
- North American private-label contract manufacturing:FDA dietary supplement CGMP compliance capabilities create captive supply relationships with domestic supplement brands seeking tariff insulation.
Industry Challenges
- Phytochemical standardization expertise scarcity:Fractionation know-how for achieving 16-20% aescin consistency resides with a limited pool of experienced chemists.
- Backward integration capital requirements:Securing controlled raw seed sourcing networks demands upfront investment in agricultural partnerships and collection infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horse Chestnut Seed Extract Market |
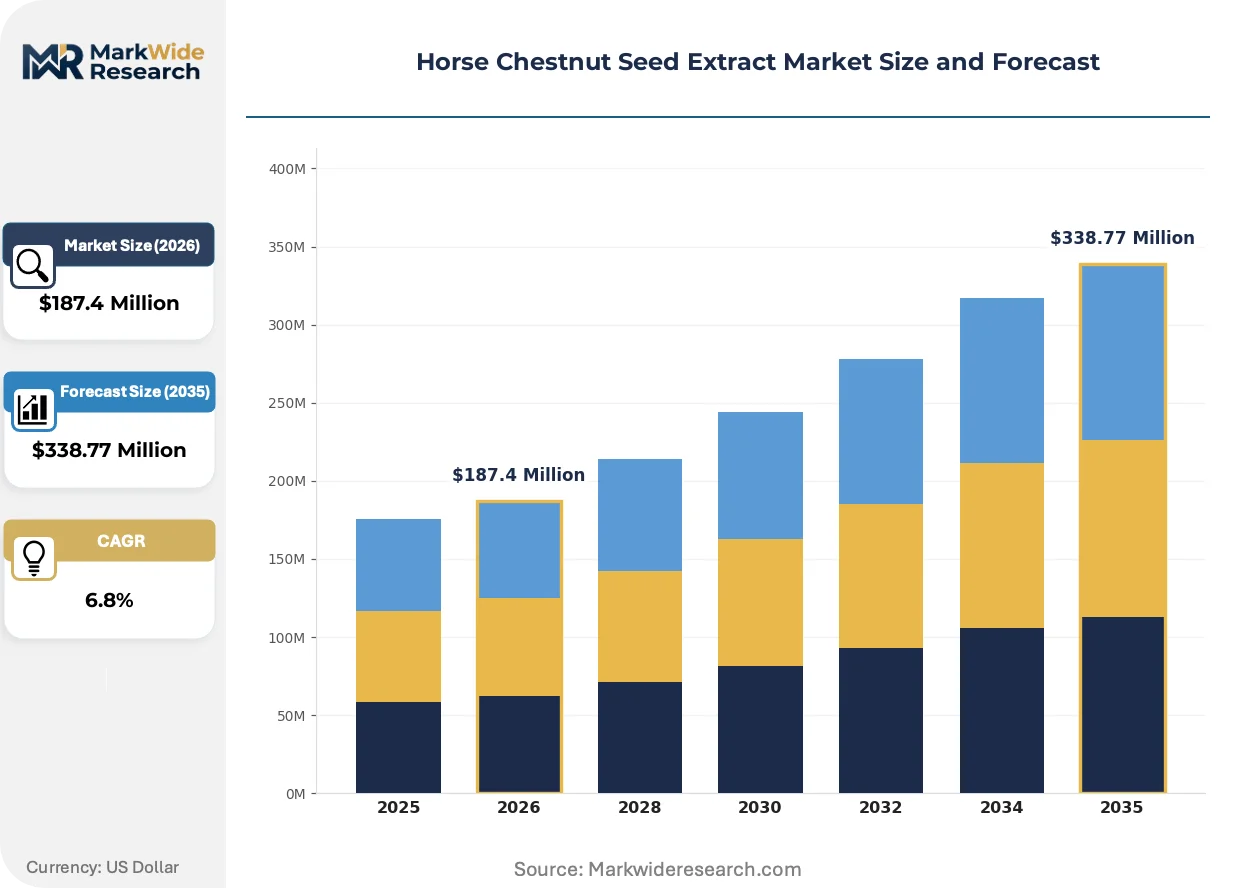
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Liquid Extracts, Powder Application: Healthcare, Cosmeceuticals, Nutraceuticals, Functional Foods End User: Pharmacies, Health Stores, Online Retailers, Hospitals Formulation: Standardized Extracts, Whole Herb, Combination Formulas, Others |
| Companies Covered | Indena S.p.A., Martin Bauer Group, Bio-Botanica Inc., Frutarom Ltd., Nature’s Way Products, Euromed S.A., Naturex, Cesra Arzneimittel GmbH & Co. KG, Plamed Green Science Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horse Chestnut Seed Extract Market Shifts & Advancements
Supercritical CO2 extraction methods are gaining traction among pharmaceutical-grade suppliers seeking to eliminate residual ethanol concerns and meet evolving purity specifications for injectable and high-dose oral applications.
Supercritical fluid extraction technology is supplanting conventional ethanol-water methods in premium pharmaceutical channels. German and Swiss formulators are adopting CO2-based systems to achieve solvent-free aescin isolation. This shift is compressing the supplier base toward capital-intensive operators capable of justifying seven-figure equipment investments.
REACH registration requirements for botanical substances are tightening substance identity documentation and impurity profiling obligations. Extractors must now generate comprehensive analytical datasets covering heavy metals, pesticides, and aflatoxins. Small-scale Balkan collectors are exiting the supply chain as compliance costs outstrip their operational scale.
Hospital procurement departments are consolidating venotonic purchasing around standardized liquid extract formats with verified bioequivalence data. This consolidation is displacing whole-herb capsules in institutional formularies. The pattern is most visible in German hospital networks where Commission E monograph alignment determines tender eligibility.
Horse Chestnut Seed Extract Market Segmentation
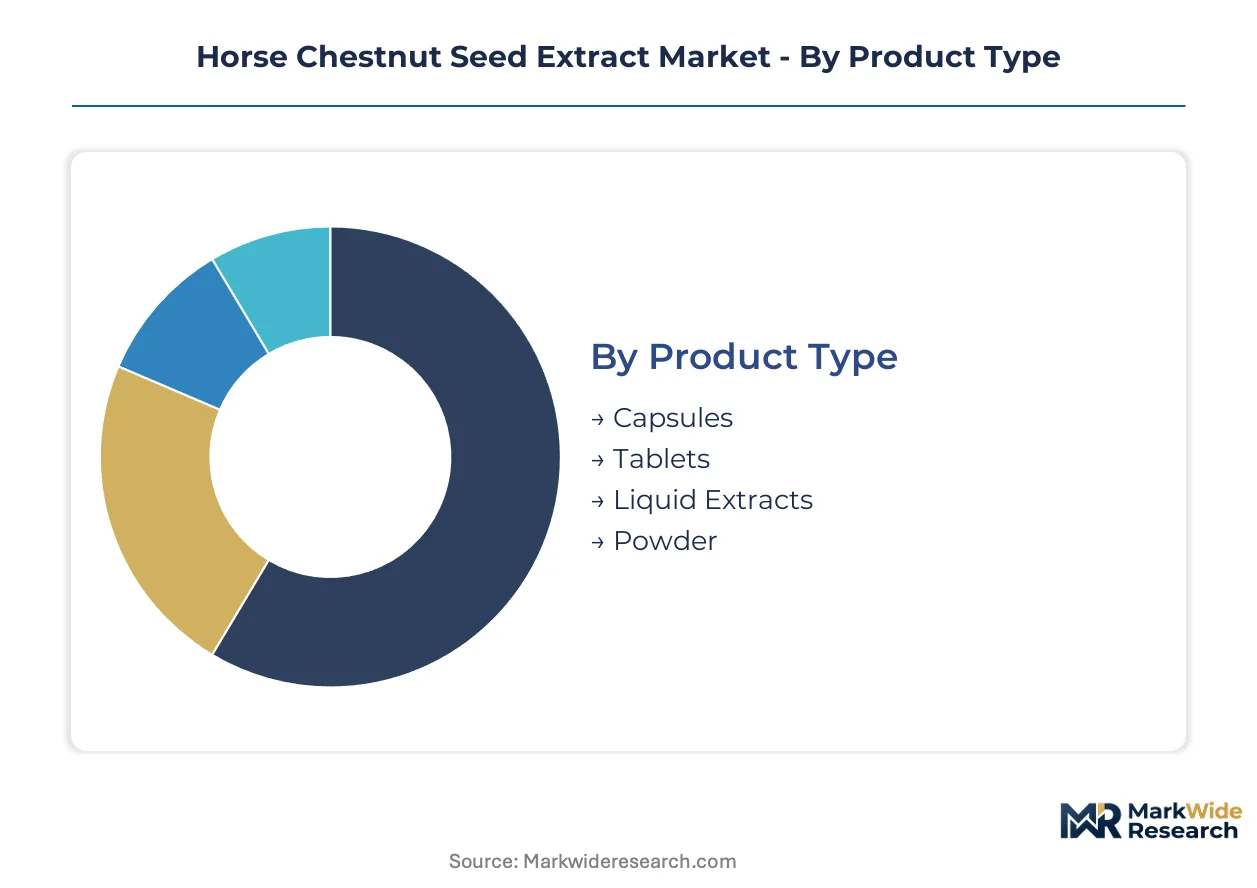
Segmentation in horse chestnut seed extract markets reveals how aescin standardization levels and dispensing formats determine channel access and pricing power. Pharmaceutical-grade standardized extracts command formulary placement through verified batch consistency, while whole-herb variants compete on accessibility in direct-to-consumer channels.
Product Type:
Liquid extracts dominate hospital procurement tenders in Germany, whereas capsules capture pharmacy and online retail velocity through convenience positioning.
- Liquid Extracts:Hospital-grade formulations with 16-20% aescin standardization require ethanol-water extraction followed by liquid-liquid purification. German hospital networks consolidate purchasing around bioequivalence-verified liquid formats that satisfy Commission E monograph alignment for tender eligibility.
- Capsules:Encapsulated powders with verified dissolution profiles target pharmacy shelf placement and subscription-based online retail. Austrian and German consumers seeking chronic venous insufficiency management drive recurring purchase patterns through this format.
- Tablets:Compressed formulations with excipient-stabilized aescin serve price-sensitive segments in Eastern European markets where reimbursement coverage varies.
- Powder:Bulk aescin concentrate supplies contract manufacturers and compounding pharmacies requiring formulation flexibility for custom blends.
By volume, capsules lead pharmacy and retail channels. By growth pace, liquid extracts are climbing the fastest as hospital procurement consolidates around standardized formats.
Application:
Margin structures diverge sharply between prescription pharmaceutical channels and cosmetic applications, with cosmeceuticals absorbing lower-grade extract output at compressed price points.
- Healthcare:Chronic venous insufficiency therapies represent the core revenue anchor, with EMA monograph compliance determining market access. German phytotherapy reimbursement codes sustain prescription volume for oral and topical preparations.
- Cosmeceuticals:Anti-cellulite and microcirculation products in France and Spain utilize lower-purity aescin fractions, expanding addressable demand beyond pharmaceutical specifications.
- Nutraceuticals:Dietary supplement positioning in North American markets operates under FDA CGMP identity testing requirements without formal disease claims.
- Functional Foods:Beverage and fortified food applications remain nascent due to aescin bitterness masking challenges and thermal stability concerns during processing.
Healthcare commands the highest unit economics. Cosmeceuticals are expanding most quickly as dermocosmetic channels in Southern Europe absorb surplus extraction capacity.
End User:
Procurement sophistication varies dramatically across channels, with hospital formularies demanding certificate-of-analysis documentation that health stores rarely require.
- Hospitals:Centralized purchasing departments in German hospital networks enforce Commission E monograph alignment and verified bioequivalence data as tender prerequisites, displacing whole-herb alternatives.
- Pharmacies:Community pharmacies in Austria and Germany maintain strong phytotherapy counseling traditions that sustain premium positioning for standardized extracts.
- Online Retailers:Direct-to-consumer platforms concentrate volume for capsule formats, with subscription models capturing recurring demand for chronic condition management.
- Health Stores:Independent retailers and natural product chains serve price-conscious consumers seeking whole-herb formulations without prescription requirements.
Hospitals drive standardization investments across the supply base. Online retailers are gaining share fastest as convenience positioning attracts younger demographics.
Formulation:
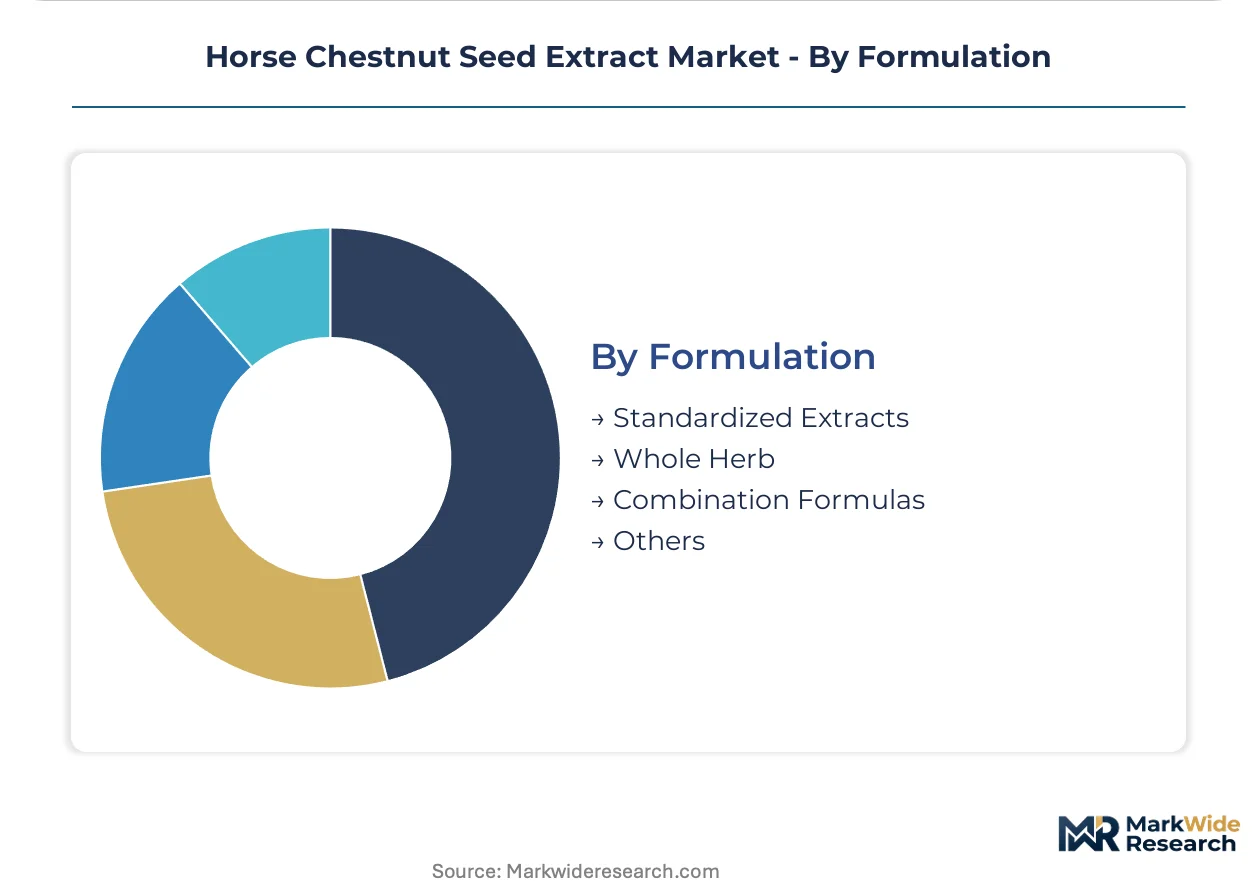
Standardization intensity directly determines regulatory pathway complexity and customer access, with combination formulas emerging as a strategic response to vascular permeability outcome demands.
- Standardized Extracts:Pharmaceutical-grade output with 16-20% aescin content via controlled ethanol-water extraction achieves formulary acceptance through batch-to-batch consistency that whole-herb alternatives cannot match.
- Combination Formulas:Aescin-bioflavonoid pairings target enhanced venotonic outcomes in sports medicine and post-surgical recovery segments, representing the steepest expansion trajectory as formulators seek differentiation.
- Whole Herb:Crude seed preparations without fractionation occupy price-sensitive direct-to-consumer segments where regulatory burden remains minimal.
- Others:Novel delivery systems including liposomal encapsulation and sustained-release matrices remain developmental, targeting improved bioavailability profiles.
Standardized extracts dominate pharmaceutical revenue. Combination formulas are climbing the fastest as clinical positioning shifts toward outcome-based vascular support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German pharmaceutical channels while North American supplement distributors absorb thinner margins. This asymmetry shapes where extractors invest standardization capacity versus commodity volume. Regulatory divergence between EMA monograph compliance and FDA dietary supplement CGMP enforcement widens the profitability gap.
Germany
Commission E approvals for oral and topical horse chestnut preparations anchor prescription demand through statutory health insurance reimbursement. EMA's Committee on Herbal Medicinal Products enforces well-established use monograph compliance that determines formulary access. Bavaria hosts concentrated extraction capacity serving hospital procurement networks across the German-speaking region.
United States
FDA dietary supplement Current Good Manufacturing Practice regulations enforce identity testing and contamination limits for aescin-containing products. Private-label contract manufacturing demand concentrates in the Northeast and California as domestic brands seek tariff insulation and supply security. Online retail velocity for capsule formats outpaces pharmacy channel growth.
France
ANSM oversight of traditional herbal medicines creates parallel regulatory pathways for well-established use claims. Cosmeceutical absorption of lower-grade extracts for anti-cellulite applications expands addressable demand beyond pharmaceutical specifications. The Provence-Alpes-Côte d'Azur region anchors dermocosmetic formulation activity targeting microcirculation positioning.
China
NMPA botanical drug registration requirements are tightening for imported aescin preparations entering hospital procurement. Domestic extraction capacity in Sichuan and Yunnan provinces serves both traditional medicine compound preparations and export raw material demand. Collection networks in these regions face climate volatility affecting seed supply consistency.
Switzerland
Swissmedic pharmaceutical-grade manufacturing standards attract premium positioning for solvent-free extraction outputs. Supercritical CO2 technology adoption concentrates near Basel's pharmaceutical cluster serving injectable and high-dose oral applications. This positioning commands price premiums from German and Austrian hospital networks seeking purity-verified supply.
Horse Chestnut Seed Extract Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Italian and German specialists dominate high-purity aescin fractionation through decades of phytochemical expertise, while Chinese and North American operators compete on volume scale and private-label agility. The market consolidates around three strategic archetypes: pharmaceutical-grade standardization specialists, bulk extract commodity suppliers, and contract manufacturing integrators. Dominant competitive moves include backward integration into raw seed sourcing networks and capacity expansion in supercritical CO2 extraction systems.
Among European standardization specialists, Indena S.p.A. and Martin Bauer Group occupy positions representing the technology-intensive tier, with Cesra Arzneimittel GmbH & Co. KG anchoring German pharmaceutical distribution channels. These firms exemplify archetypes built on extraction-standardization expertise and controlled raw material sourcing rather than scale-driven cost positioning.
| Leading Market Players |
|---|
| Indena S.p.A. |
| Martin Bauer Group |
| Bio-Botanica Inc. |
| Frutarom Ltd. |
| Nature's Way Products |
| Euromed S.A. |
| Naturex |
| Cesra Arzneimittel GmbH & Co. KG |
| Plamed Green Science Group |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Balkan seed collectors and German extraction facilities lock in both raw material access and price visibility for pharmaceutical-grade aescin output. These contractual structures insulate standardized extract manufacturers from climate-driven harvest volatility while compressing margins for spot-market dependent operators.
Pricing Analysis
The customization-premium spread separates pharmaceutical-grade standardized extracts from commodity whole-herb formulations. Three-tier pricing structure across premium, standard, and economy levels reflects aescin concentration, EMA monograph compliance, and verified bioequivalence documentation. Pricing pressure stems from synthetic venotonic substitution and REACH registration cost pass-through to smaller Balkan suppliers. Hospital procurement departments demonstrate lowest price sensitivity due to reimbursement coverage, while health store channels absorb maximum margin compression.
Supply Chain Analysis
Strategic stockpile preferences dominate among German and Swiss pharmaceutical extractors buffering against Balkan and Eastern European harvest volatility. Raw seed sourcing draws from Bulgaria, Romania, and Serbia where collection networks face labor shortages and climate instability. Supply chain risk centers on single-source vulnerability for high-purity aescin fractionation expertise concentrated among Italian and German specialists. Distribution runs through hospital procurement consortia in German-speaking markets, pharmacy chains in Austria, and private-label contract manufacturers in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is reshaping competitive positioning as EMA monograph compliance creates interoperability standards that consolidate demand around certified supplier networks. This ecosystem shift favors extraction-standardization specialists capable of cross-border documentation protocols.
For Market Incumbents: Secure controlled raw seed sourcing networks through agricultural partnerships in Bulgaria and Romania to defend against climate-driven input volatility. Invest in supercritical CO2 capacity near Basel to capture solvent-free purity premiums from German hospital networks. EMA pharmacovigilance burden extension represents the primary regulatory threat requiring enhanced analytical documentation capabilities. For New Entrants and Emerging Players: FDA dietary supplement CGMP certification fast-track enables private-label contract manufacturing entry serving North American supplement brands seeking domestic supply security. White-space targets include topical formulation expansion for French and Spanish dermocosmetic channels and combination formula development pairing aescin with bioflavonoids for sports medicine applications. Go-to-market positioning should emphasize tariff insulation and supply security rather than price competition. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated extraction specialists with captive seed sourcing and EMA monograph alignment. Long-term viability hinges on pharmacovigilance compliance capabilities and supercritical technology adoption rather than scale-driven cost positioning. The signal to watch is REACH registration completion rates among Balkan collectors as a supply base compression indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Seed Sourcing | Agricultural partnerships in Bulgaria and Romania secure climate-resilient input supply for pharmaceutical-grade extraction. |
| Supercritical CO2 Capacity Expansion | Solvent-free aescin isolation near Basel commands purity premiums from German hospital procurement networks. |
| EMA Monograph Compliance Investment | Enhanced analytical documentation and batch-to-batch standardization unlocks formulary placement in German-speaking markets. |
| Combination Formula Development | Aescin-bioflavonoid pairings target enhanced vascular permeability outcomes in sports medicine and post-surgical recovery segments. |
| North American Private-Label Manufacturing | FDA CGMP-compliant contract manufacturing captures domestic supplement brand demand seeking tariff insulation. |
Research Methodology
Operator-level perspectives from extraction plant managers, pharmaceutical formulators, hospital procurement directors, and Balkan seed collection network coordinators anchored the qualitative base. These primary interviews combined with secondary validation from EMA Committee on Herbal Medicinal Products submissions, German Commission E monograph databases, FDA dietary supplement CGMP guidance documents, and REACH registration filings. Bottom-up volume modeling and top-down value triangulation cross-verified segment outputs.
Sensitivity analysis tested forecast robustness across raw seed price volatility scenarios, regulatory compliance timeline variations, and synthetic venotonic substitution rates. Segmentation dimensions modeled include product type, application, end user, formulation standardization level, and regional regulatory cluster. CAGRs were derived from installed extraction capacity utilization trends and hospital procurement tender award patterns. Industry-specific inputs incorporated EMA pharmacovigilance burden trajectory and supercritical CO2 technology adoption rates.
Decision-makers should treat outputs as directional under assumptions of sustained German phytotherapy reimbursement and stable Balkan seed supply; material deviation would warrant model refresh. Revision becomes warranted when synthetic venotonic prescription penetration or REACH registration withdrawal rates cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Bambara Beans Market
Nuts and Seeds
Hazelnut Market
Nuts and Seeds
Almond Oil Market
Nuts and Seeds
Nut Ingredients Market
Nuts and Seeds
Europe Cashew Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Cashew Roasting Machine Market
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Japan Fox Nuts Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Almond with Shell Snack Market