
 Europe Tahini Market | 2026-2036
Europe Tahini Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tahini Market Foresight
A capital-intensity divergence between artisanal stone-mill operators and industrial solvent-extraction facilities is rotating competitive advantage toward scaled processors with certified organic supply chains. HAITOGLOU BROS S.A. leverages its integrated sesame sourcing from Greek and Sudanese origins to sustain price stability across Southern European markets. Dipasa Europe B.V. anchors its Netherlands-based operations with automated roasting and grinding infrastructure that dominates bulk supply to food manufacturers. Meridian Foods Limited differentiates through British Soil Association organic certification, occupying premium shelf space in UK specialty retailers.
Tahini is a sesame seed paste produced by roasting, hulling, and mechanically grinding sesame seeds into a smooth or coarse emulsion with typical fat content of 50-60% and minimal moisture below 1.5%, serving as a foundational ingredient in hummus, halva, dressings, and plant-based sauces. Paste formulations lead volume throughput across European food manufacturing channels, while organic tahini captures expanding margin pools in German and Scandinavian retail segments where certification premiums command sustained shelf price separation from conventional alternatives. Glass jar packaging retains dominance in Mediterranean export channels, though pouch formats are gaining traction in UK and Dutch online retail where logistics cost reduction shapes procurement decisions.
EFSA allergen labeling mandates and EU Organic Regulation 2018/848 shape formulation standards and import documentation burdens for sesame-derived products entering European distribution. REACH compliance for food-contact packaging materials adds testing overhead for glass jar and plastic tub suppliers serving tahini processors. Stakeholders must monitor evolving EU deforestation-free supply chain due diligence requirements, as sesame sourcing traceability from Sudan, Ethiopia, and India becomes a compliance threshold rather than a voluntary sustainability marker.
Market Dynamics
EFSA clean-label guidelines and EU Organic Regulation 2018/848 are compressing formulation flexibility while concentrating procurement power among scaled processors with certified supply chains. This regulatory pressure is rotating competitive advantage toward operators with backward integration into sesame sourcing and additive-free production capabilities.
Growth Catalysts
- EU Organic Regulation 2018/848:Certification mandates for imported sesame are pushing food manufacturers toward verified organic suppliers, expanding premium shelf space in German and Scandinavian retail.
- Mediterranean restaurant chains:Expansion of tahini-based menu applications across Germany and France is pulling industrial paste volumes through foodservice distribution channels.
- Sesame hulling automation:Advances in optical sorting and robotic dehulling are reducing labor intensity and improving batch consistency for European processors.
Market Restraints
- Sudanese supply concentration:Political instability in the White Nile sesame belt creates input volatility that European importers cannot easily hedge through alternative origins.
- REACH compliance overhead:Testing burdens for food-contact packaging materials add fixed costs that disproportionately burden small-batch artisanal producers.
- Sunflower seed paste substitution:Cost-sensitive food manufacturers in Southern Europe are reformulating with domestically sourced alternatives where tahini is not a labeled ingredient.
Strategic Opportunities
- UK online retail pouches:Logistics-optimized flexible packaging formats are capturing share in British e-commerce channels where glass jar shipping costs erode margins.
- Plant-based sauce convergence:Tahini is displacing dairy and egg emulsifiers in vegan dressings and mayonnaise alternatives, opening formulation partnerships with European clean-label brands.
- EU deforestation-free due diligence:Incoming supply chain traceability requirements will advantage early movers with blockchain-verified Ethiopian and Indian sesame sourcing.
Industry Challenges
- Organic certification timelines:Conversion periods for sesame farmland lock processors into multi-year supply commitments before premium pricing materializes.
- Roasting technician scarcity:Traditional stone-mill operation requires skilled temperature control that industrial automation has not fully replicated, constraining artisanal capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tahini Market |
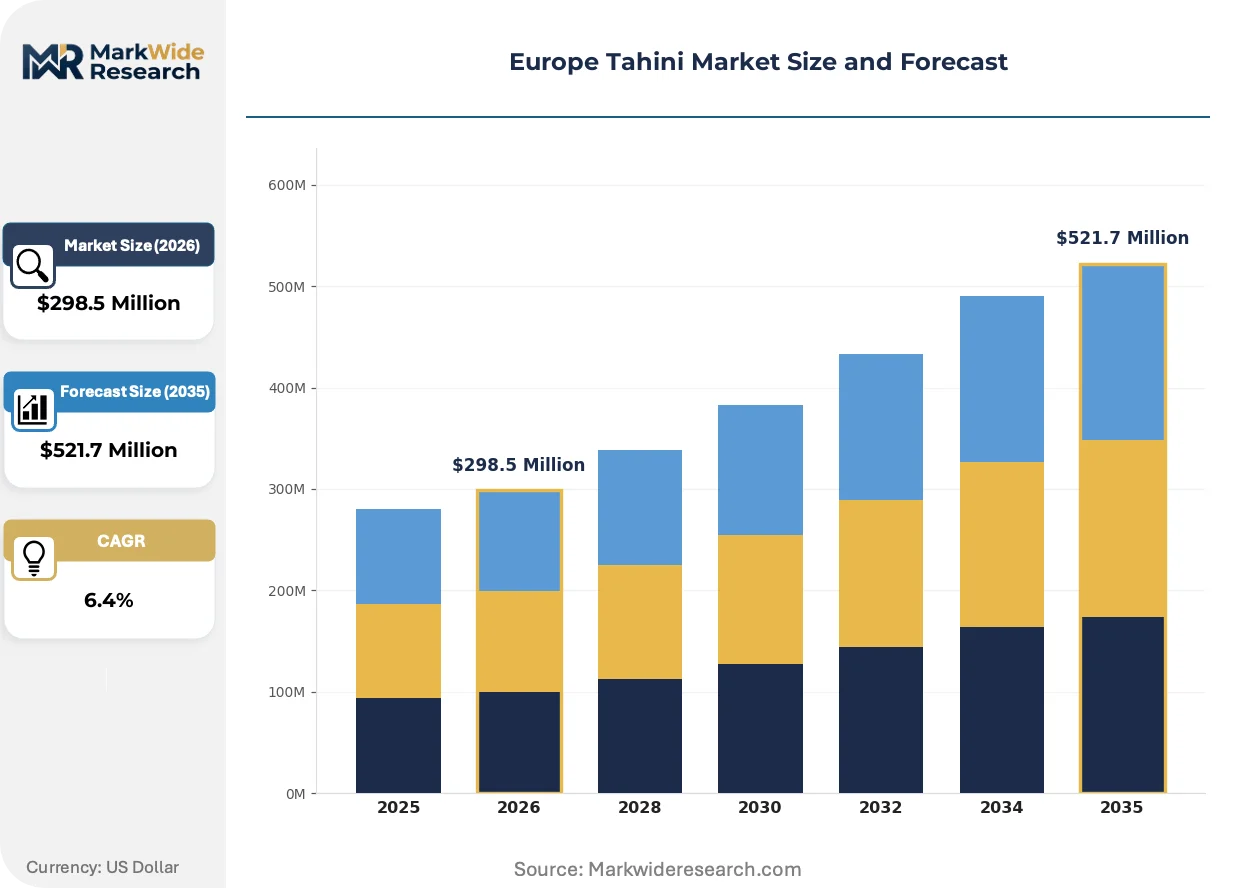
| Market Size in 2026 | $298.5 Million |
| Market Size in 2035 | $521.7 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paste, Organic Tahini, Flavored Tahini, Conventional Tahini Packaging Type: Glass Jar, Plastic Tub, Pouch, Bulk Container End User: Retail Consumers, Foodservice, Food Manufacturers, Exporters Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | HAITOGLOU BROS S.A., Prince Tahina Ltd., Sesame & Tahina Food Industries Ltd., Meridian Foods Limited, Dipasa Europe B.V., Al Wadi Al Akhdar, Mavrikos, Achva, Skoulikas Bedford Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tahini Market Shifts & Advancements
Processing technology and regulatory compliance requirements are compressing the viable operator base while opening white space for certified organic specialists with traceable supply chains. Three forces are actively restructuring how tahini moves from seed to shelf across European markets.
Automated optical sorting and AI-driven hulling systems are miniaturizing quality control infrastructure that previously required dedicated facilities. Mid-scale processors in the Netherlands and Belgium are deploying these systems to match large-plant consistency without capital-intensive greenfield investment. The technology is compressing the minimum efficient scale for premium tahini production.
REACH compliance for food-contact materials is tightening testing protocols for glass jar coatings and plastic tub additives. ECHA documentation burdens are forcing smaller processors to consolidate supplier relationships or exit branded retail entirely. German and French importers are responding by pre-qualifying packaging vendors against harmonized safety standards.
Certification-driven purchasing is displacing price-first procurement in Northern European retail. British Soil Association and German Bioland marks now command measurable shelf price separation that conventional products cannot match. This behavioral shift is most visible in Berlin and Hamburg organic food retail clusters where consumer willingness to pay for verified origin outpaces Southern European markets.
Europe Tahini Market Segmentation
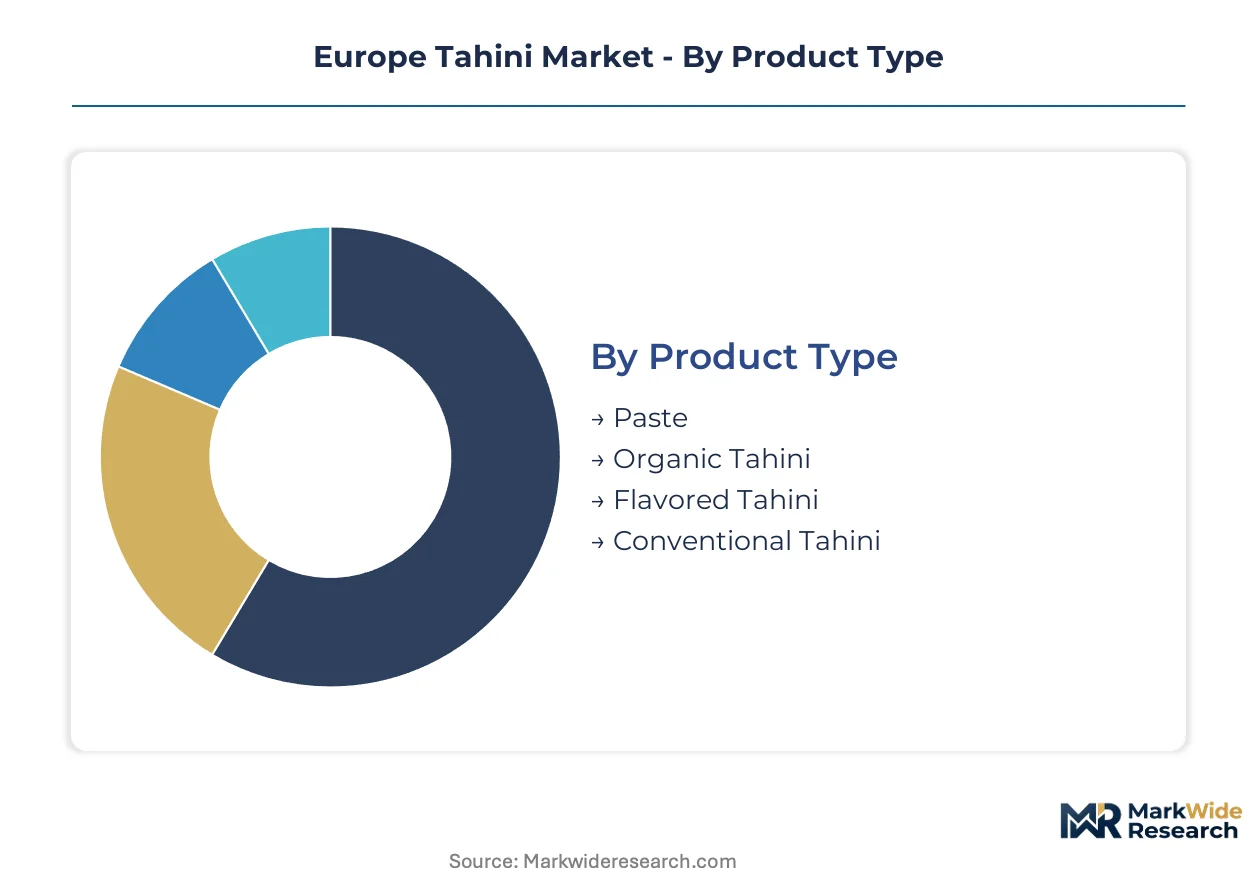
Tahini segmentation in Europe tracks divergent paths between industrial-scale paste production and certified organic retail positioning. Channel configuration determines margin capture, with foodservice and manufacturing channels prioritizing volume throughput while specialty retail extracts certification premiums.
Product Type:
Paste formulations dominate food manufacturing and foodservice procurement channels across Germany and France, while organic variants concentrate in certified retail networks.
- Paste:Standard emulsion with 50-60% fat content serves as the foundational input for hummus production and Mediterranean restaurant chains. German food manufacturers pull the largest industrial volumes through bulk supply agreements with Dutch and Greek processors.
- Organic Tahini:EU Organic Regulation 2018/848-compliant production with full seed-to-paste traceability commands shelf price separation in Berlin and Hamburg organic retail clusters. Conversion timelines for sesame farmland lock suppliers into multi-year commitments before premium pricing materializes.
- Flavored Tahini:Value-added formulations with herb, spice, or citrus infusions target UK and Scandinavian specialty retailers seeking differentiation.
- Conventional Tahini:Non-certified standard grade fills price-sensitive foodservice applications in Southern Europe where sunflower paste substitution pressure is strongest.
By volume, Paste leads. By growth pace, Organic Tahini is ahead.
Packaging Type:
Cost-to-serve economics separate premium glass formats from logistics-optimized flexible packaging, with channel selection driving format adoption.
- Glass Jar:Traditional format retains dominance in Mediterranean export channels and German organic retail where shelf aesthetics and reusability signal quality. REACH compliance for food-contact coatings adds testing overhead that burdens smaller processors.
- Pouch:Flexible format captures share in UK online retail where dimensional weight shipping costs erode glass jar margins. Dutch e-commerce operators are standardizing pouch specifications for direct-to-consumer fulfillment.
- Plastic Tub:Foodservice portion control format dominates bulk dispensing in French and Spanish restaurant chains.
- Bulk Container:Industrial totes and drums supply tahini to hummus manufacturers and sauce processors in Belgium and the Netherlands.
Glass Jar maintains revenue concentration. Pouch formats are expanding most quickly.
End User:
Application requirements segment procurement behavior, with manufacturers prioritizing consistency specifications and retailers demanding certification documentation.
- Food Manufacturers:Hummus and sauce processors in Germany and the Netherlands specify tight particle size distribution and oxidative stability metrics. Automated roasting infrastructure at scaled suppliers matches these requirements.
- Retail Consumers:Certified organic purchasing concentrates in German and Scandinavian markets where Bioland and Soil Association marks command measurable willingness-to-pay premiums.
- Foodservice:Mediterranean restaurant chains across France and Germany pull paste volumes through distribution intermediaries with refrigerated logistics capability.
- Exporters:Greek and Dutch processors ship packaged tahini to Middle Eastern and North African markets with origin labeling requirements.
Food Manufacturers dominate volume throughput. Retail Consumers show the steepest margin expansion.
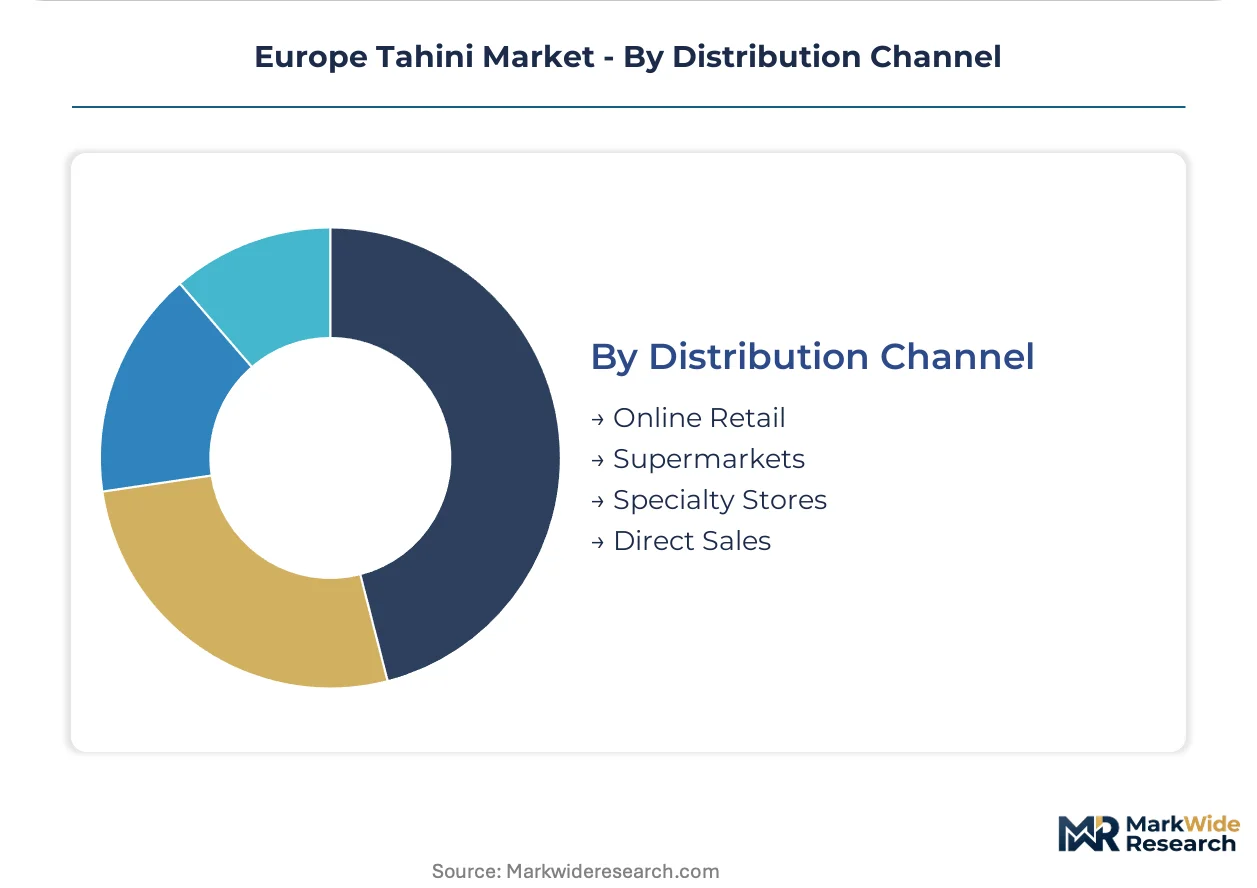
Distribution Channel:
Channel selection determines pricing architecture and working capital intensity, with direct and digital formats compressing intermediary margins.
- Supermarkets:German and UK multiples control mainstream volume placement, with listing fees and promotional calendars shaping supplier economics. Conventional tahini occupies standard shelf sets while organic variants secure dedicated natural food sections.
- Online Retail:British and Dutch e-commerce platforms are standardizing pouch formats and subscription models for repeat purchase convenience. Logistics cost reduction drives format innovation in this channel.
- Specialty Stores:Berlin and Hamburg organic food clusters concentrate premium pricing power for certified products with verified Sudanese or Ethiopian origin.
- Direct Sales:Foodservice and manufacturing accounts in France and Belgium procure through processor-direct relationships with contracted volume commitments.
Supermarkets anchor volume. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German organic retail clusters command shelf price premiums that Italian foodservice channels cannot replicate, creating a North-South asymmetry in margin capture across European tahini distribution.
Germany
Berlin and Hamburg organic food clusters concentrate certified tahini demand where Bioland marks command measurable willingness-to-pay premiums. EU Organic Regulation 2018/848 mandates full seed-to-paste traceability for imported sesame, compressing supplier flexibility. Bavarian food manufacturers pull industrial paste volumes through automated roasting infrastructure at scaled Dutch and Greek processors.
United Kingdom
British e-commerce platforms standardize pouch formats for direct-to-consumer fulfillment where dimensional weight shipping costs erode glass jar margins. REACH compliance for food-contact packaging materials adds testing overhead that burdens smaller artisanal producers. London specialty retailers anchor Soil Association-certified positioning in premium shelf sets.
France
Mediterranean restaurant chains across Paris and Lyon pull paste volumes through distribution intermediaries with refrigerated logistics capability. EFSA clean-label guidelines push reformulation toward additive-free formulations. Provence-Alpes-Côte d'Azur foodservice clusters concentrate tahini-based menu application expansion.
Netherlands
Rotterdam and Amsterdam logistics hubs dominate bulk supply to Belgian and German hummus manufacturers. Automated roasting and grinding infrastructure at scaled processors matches tight particle size distribution specifications. Dutch e-commerce operators standardize pouch specifications for subscription model deployment.
Greece
Integrated sesame sourcing from Sudanese and Ethiopian origins sustains price stability across Southern European markets. EFSA allergen labeling mandates shape export documentation for Middle Eastern and North African destination markets. Thessaloniki processing clusters anchor origin-labeled Mediterranean export channels.
Europe Tahini Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with automated optical sorting specialists commanding premium positioning while solvent-extraction facilities capture volume throughput. The vendor base organizes around three strategic groupings: integrated origin processors with captive sesame supply, automated mid-scale operators with AI-driven quality control, and certified organic specialists with Soil Association or Bioland accreditation. Consolidation pressure concentrates procurement power among scaled operators with backward integration into Sudanese and Ethiopian sourcing. Competitive moves center on pre-qualified packaging vendor relationships against harmonized REACH standards and blockchain-verified supply chain traceability for incoming EU deforestation-free due diligence requirements.
Among Greece-based integrated processors, HAITOGLOU BROS S.A. exemplifies the origin-anchored archetype with Sudanese supply chain control. Dipasa Europe B.V. occupies the automated scale position from Netherlands-based operations. Meridian Foods Limited represents the certified organic specialist tier with British Soil Association accreditation securing premium UK retail placement.
| Leading Market Players |
|---|
| HAITOGLOU BROS S.A. |
| Prince Tahina Ltd. |
| Sesame & Tahina Food Industries Ltd. |
| Meridian Foods Limited |
| Dipasa Europe B.V. |
| Al Wadi Al Akhdar |
| Mavrikos |
| Achva |
| Skoulikas Bedford Ltd |
| Others |
Supply & Pricing Matrix
Sunflower seed paste substitution in Southern European food manufacturing simultaneously redraws procurement geography toward domestic oilseed suppliers and compresses tahini pricing power in cost-sensitive segments. This displacement dynamic forces Sudanese-origin processors to defend premium positioning through certification rather than volume, while mid-tier suppliers absorb margin erosion from reformulation pressure.
Pricing Analysis
Price differentiation between Soil Association-certified organic and conventional paste tiers widens as Bioland-accredited products secure dedicated shelf sets in Berlin organic clusters. Three-tier pricing structure across premium certified, standard industrial, and economy conventional levels governs procurement contracts, with volume scale and certification grade as the primary levers. Pricing pressure stems from sunflower paste substitution in Spanish and Italian foodservice channels where tahini lacks label presence. Food manufacturers exhibit highest price sensitivity due to reformulation flexibility, while German specialty retailers show lowest sensitivity where origin verification commands sustained premiums.
Supply Chain Analysis
Port congestion at Rotterdam and Piraeus elevates inbound logistics costs for Sudanese and Ethiopian sesame shipments entering European processing hubs. Raw material sourcing draws from Sudan, Ethiopia, and India, with hulling and roasting equipment dependencies resting on Dutch and Greek automation suppliers. Single-source vulnerability concentrates in White Nile sesame belt political instability, which European importers cannot hedge through alternative origins. Distribution runs through Rotterdam-Amsterdam logistics clusters for bulk industrial supply, with Greek processors anchoring Mediterranean export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Tahini Market recovery tracks Mediterranean restaurant chain expansion across Germany and France, where tahini-based menu applications pull industrial paste volumes through normalized foodservice demand.
For Market Incumbents: Consolidate procurement relationships with pre-qualified REACH-compliant packaging vendors to deflect regulatory testing overhead that burdens smaller competitors. Deepen backward integration into Ethiopian sesame sourcing before EU deforestation-free due diligence mandates crystallize, securing blockchain-verified traceability as a compliance threshold. Automated roasting capacity expansion in Netherlands-based facilities matches tight particle size specifications from German hummus manufacturers. For New Entrants and Emerging Players: Lead with logistics-optimized pouch formats in UK online retail where dimensional weight shipping costs erode incumbent glass jar margins. British e-commerce platforms represent the most penetrable channel, with subscription models capturing repeat purchase convenience. Target Soil Association certification as the go-to-market angle for London specialty retailer placement. For Investors and Strategic Acquirers: EU deforestation-free supply chain due diligence reshapes the acquisition landscape toward processors with verified Ethiopian and Indian sesame traceability. Long-term viability favors automated mid-scale operators with AI-driven quality control infrastructure over artisanal stone-mill specialists facing technician scarcity constraints. Acquisition target archetype: Netherlands-based processors with integrated roasting infrastructure and pre-qualified organic certification pipelines. Signal to watch: EFSA allergen labeling mandate enforcement intensity as compliance cost discriminator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethiopian Sourcing | Blockchain-verified traceability secures deforestation-free compliance ahead of EU due diligence mandates. |
| Automated Optical Sorting Deployment | AI-driven hulling systems compress minimum efficient scale for premium tahini production in Belgian mid-scale facilities. |
| Pouch Format Standardization | Flexible packaging specifications capture UK e-commerce share where glass jar shipping costs erode margins. |
| Soil Association Certification Investment | British organic accreditation commands dedicated premium shelf sets in London specialty retail clusters. |
| REACH-Compliant Packaging Pre-Qualification | Harmonized safety standards with German and French importers deflect ECHA documentation burdens from smaller competitors. |
Research Methodology
Cross-validation between primary interviews with tahini processors, organic certification auditors, and Mediterranean restaurant chain procurement directors anchors the qualitative findings against secondary validation from EFSA guidance documents, EU Organic Regulation 2018/848 implementation records, and REACH compliance databases. Customs records for sesame seed imports into Rotterdam and Piraeus ports, combined with British Soil Association certification registries, provide volume and accreditation triangulation. Bottom-up facility capacity assessments and top-down retail audit data from German organic food clusters complete the analytical foundation.
Sensitivity analysis across Sudanese supply disruption scenarios and sunflower paste substitution rates tests forecast robustness throughout the projection horizon. Segmentation modeling covers product type, packaging format, end-user application, and distribution channel dimensions, with organic certification status as a cross-cutting qualifier. CAGRs derive from trend extrapolation adjusted for regulatory implementation timelines and foodservice channel recovery patterns. Sesame hulling automation adoption curves and EFSA clean-label reformulation pace serve as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EFSA allergen labeling and EU Organic Regulation enforcement; material policy shifts would require re-modeling. Sudanese political stability and Ethiopian origin verification system deployment represent specific risk factors that could revise volume and value trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Walnut Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Strawberry Seed Oil Market
Nuts and Seeds
Blackcurrant Seed Oil Market
Nuts and Seeds
Carob Market
Nuts and Seeds
Almond Kernels Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Japan Fox Nuts Market
Nuts and Seeds
Hazelnut Market