
 North America Freight Forwarding Market | 2026-2036
North America Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
North America Freight Forwarding Market Insights
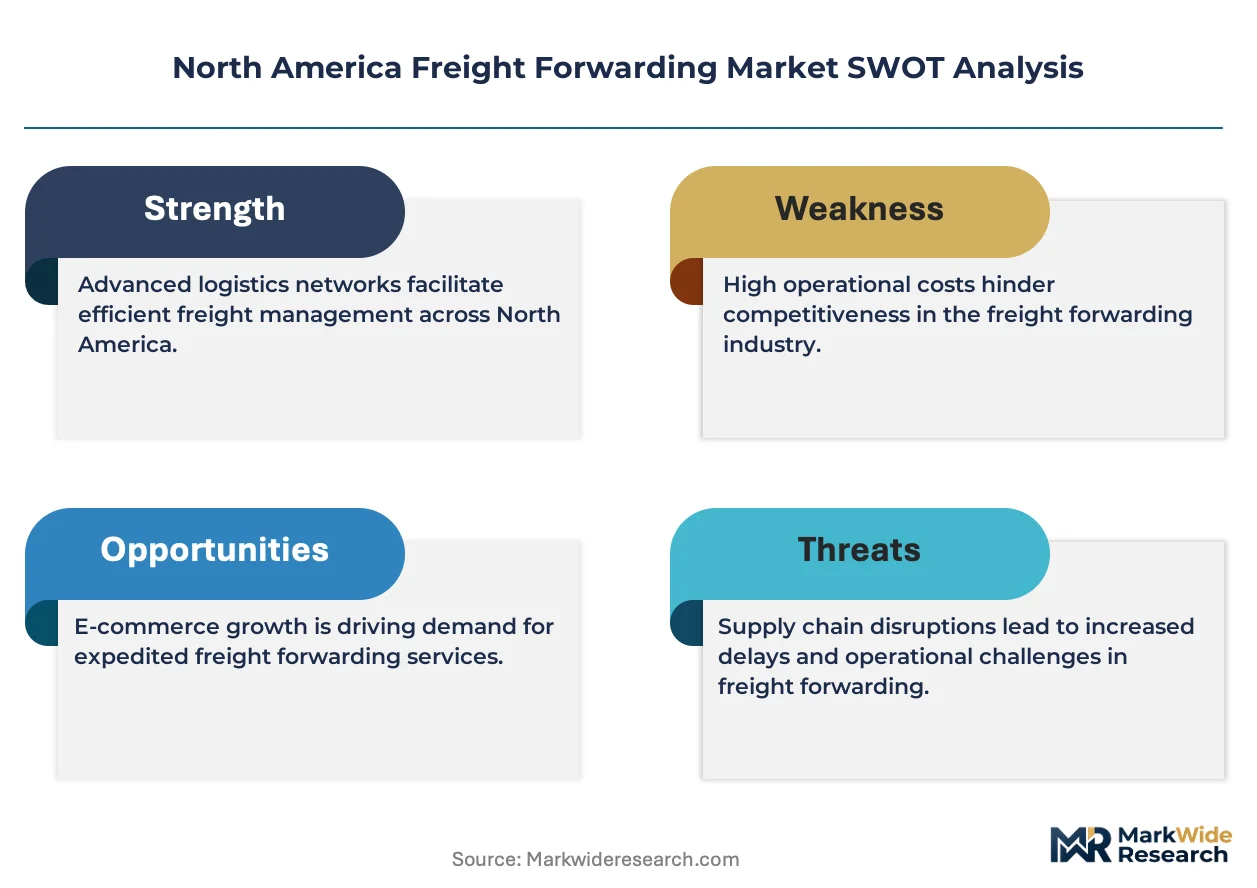
CTPAT certification is redrawing competitive boundaries in North America freight forwarding. C.H. Robinson leverages its digital freight platform to sustain volume leadership across the US-Canada lane. DSV AS anchors its position through specialized pharmaceutical cold-chain capabilities. FedEx Corp differentiates via integrated express and customs brokerage services.
Freight forwarding encompasses the coordination and shipment of goods across international borders through multimodal transport arrangements, requiring precise documentation, customs clearance, and cargo insurance management. The process demands real-time tracking systems, harmonized tariff code expertise, and compliance with bilateral trade agreements to ensure efficient supply chain execution. Air freight commands premium margins on time-sensitive pharmaceutical and electronics cargo, while ocean freight handles bulk manufacturing volumes at lower unit economics. Ground transportation absorbs the largest volume share through cross-border trucking, and customs brokerage generates recurring revenue from regulatory complexity.
The US CBP enforces CTPAT and ACE requirements that determine market access for freight forwarders operating US border crossings. Transport Canada and the CBSA administer parallel security programs that shape cross-border operational standards. Mexico's SAT customs authority implements the VUCEM platform for electronic documentation. Stakeholders must monitor evolving USMCA rules of origin enforcement and invest in trade compliance technology to maintain clearance velocity.
Market Dynamics
USMCA rules of origin enforcement is compressing clearance timelines and forcing freight forwarders to reconfigure documentation workflows across the Texas-Mexico manufacturing corridor. This regulatory pressure is redrawing operational capabilities and technology investments.
Growth Catalysts
- Nearshoring acceleration:Automotive and electronics manufacturers are relocating assembly operations to Mexico, generating cross-border freight volumes that require specialized customs brokerage and multimodal coordination.
- CTPAT certification requirements:US CBP security mandates are creating tiered market access where certified forwarders capture premium lanes and non-certified operators face exclusion from major shipper RFPs.
- Pharmaceutical cold-chain expansion:Temperature-controlled biologics shipments between US and Canadian distribution hubs are driving demand for validated thermal packaging and real-time monitoring infrastructure.
Market Restraints
- Chassis and container scarcity:Port congestion at Long Beach and Savannah is creating equipment imbalances that inflate drayage costs and extend transit variability.
- Driver labor constraints:Cross-border trucking capacity faces structural shortages as Mexican carrier certification under US DOT standards creates bottlenecks at Laredo and Otay Mesa crossings.
- Fuel cost volatility:Diesel price swings directly compress margins on ground transportation, which absorbs the largest volume share in North American freight forwarding.
Strategic Opportunities
- Canadian Arctic shipping lanes:Melting ice conditions are opening seasonal routes through Hudson Bay and the Northwest Passage for bulk commodities moving between Manitoba ports and European markets.
- ACE and VUCEM integration:Automated customs platforms are enabling forwarders to offer pre-arrival clearance as a premium service, differentiating on velocity rather than price.
- Reverse logistics for e-commerce returns:Cross-border return flows from Canadian and Mexican consumers to US fulfillment centers represent underdeveloped white space requiring specialized brokerage expertise.
Industry Challenges
- Harmonized tariff code expertise:USMCA origin verification demands specialized classification knowledge that outstrips current workforce training pipelines.
- Legacy TMS integration:Forwarders operating acquired regional networks face costly system consolidation to achieve unified visibility across truck, rail, and ocean modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Freight Forwarding Market |
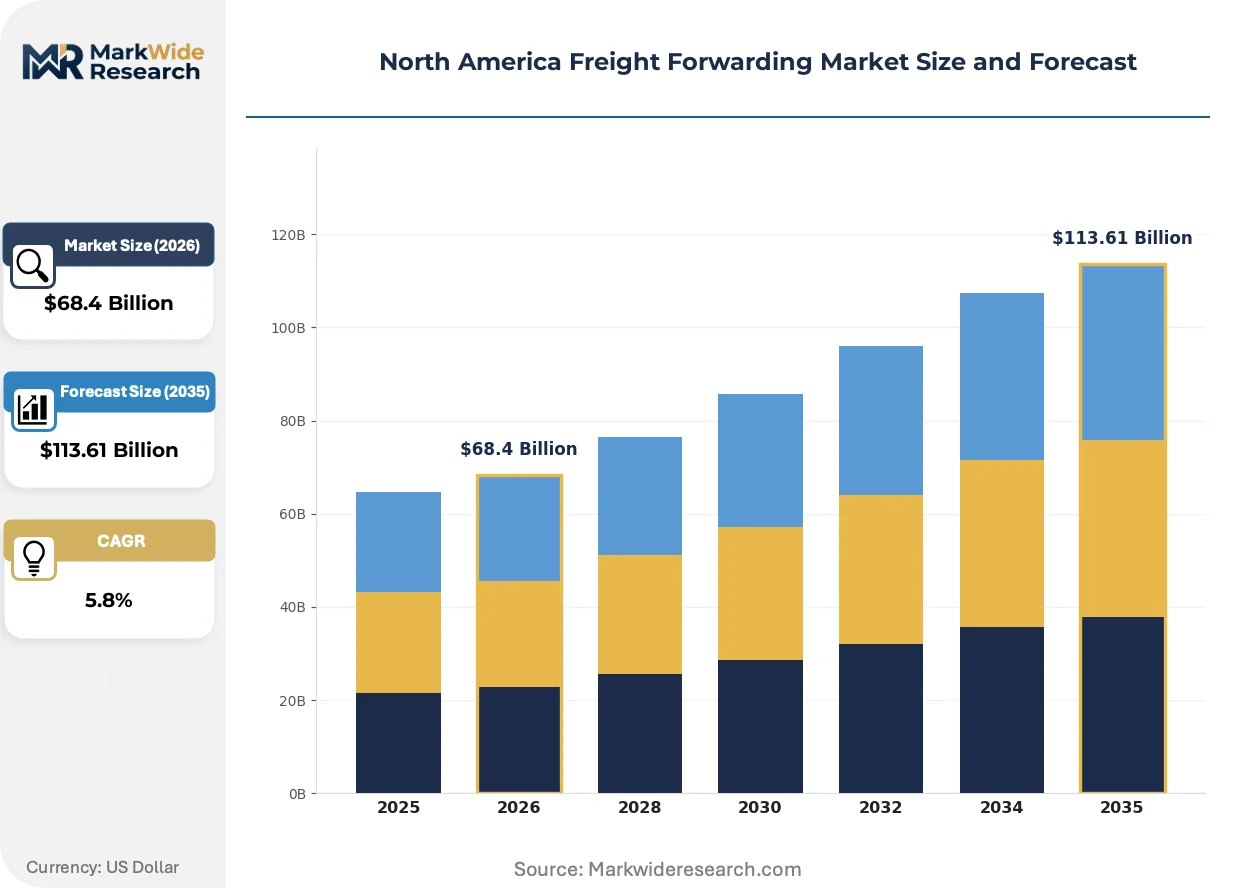
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Ground Transportation, Customs Brokerage End User: Retail, Manufacturing, Automotive, Pharmaceuticals Shipping Method: Full Container Load (FCL), Less than Container Load (LCL), Intermodal, Break Bulk Delivery Speed: Standard Shipping, Expedited Shipping, Same-Day Delivery, Time-Definite Services |
| Companies Covered | Expeditors International of Washington Inc, C.H. Robinson, DHL Group, Kuehne + Nagel International AG, DB Schenker, DSV AS, CEVA Inc, FedEx Corp, United Parcel Service Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Freight Forwarding Market Trends and Innovations
Digital freight platforms are compressing traditional brokerage margins while enabling new service bundling around customs compliance and cargo insurance. This technological shift is forcing established operators to reconfigure their value propositions.
Blockchain-enabled documentation is displacing paper-based bills of lading and customs filings. Pharmaceutical and automotive shippers are adopting distributed ledger verification for USMCA origin claims. This technology is displacing manual audit processes and compressing dispute resolution timelines from weeks to hours.
Transport Canada's CBSA security harmonization with US CBP is creating unified clearance standards across the Detroit-Windsor and Buffalo-Fort Erie corridors. Forwarders must now maintain dual-certification to operate efficiently on the continent's busiest land border. The integrated automotive supply chain spanning Ontario and Michigan is most affected, with just-in-time manufacturers demanding synchronized release protocols.
Shippers are consolidating forwarder relationships around end-to-end liability coverage rather than transactional lane pricing. Large retailers and industrial manufacturers are reducing vendor counts from fifteen-plus providers to three or four strategic partners. This concentration is most visible in the Texas-Mexico corridor, where automotive OEMs now require single-contract accountability for cross-border ground, rail, and customs services.
North America Freight Forwarding Market Segmentation
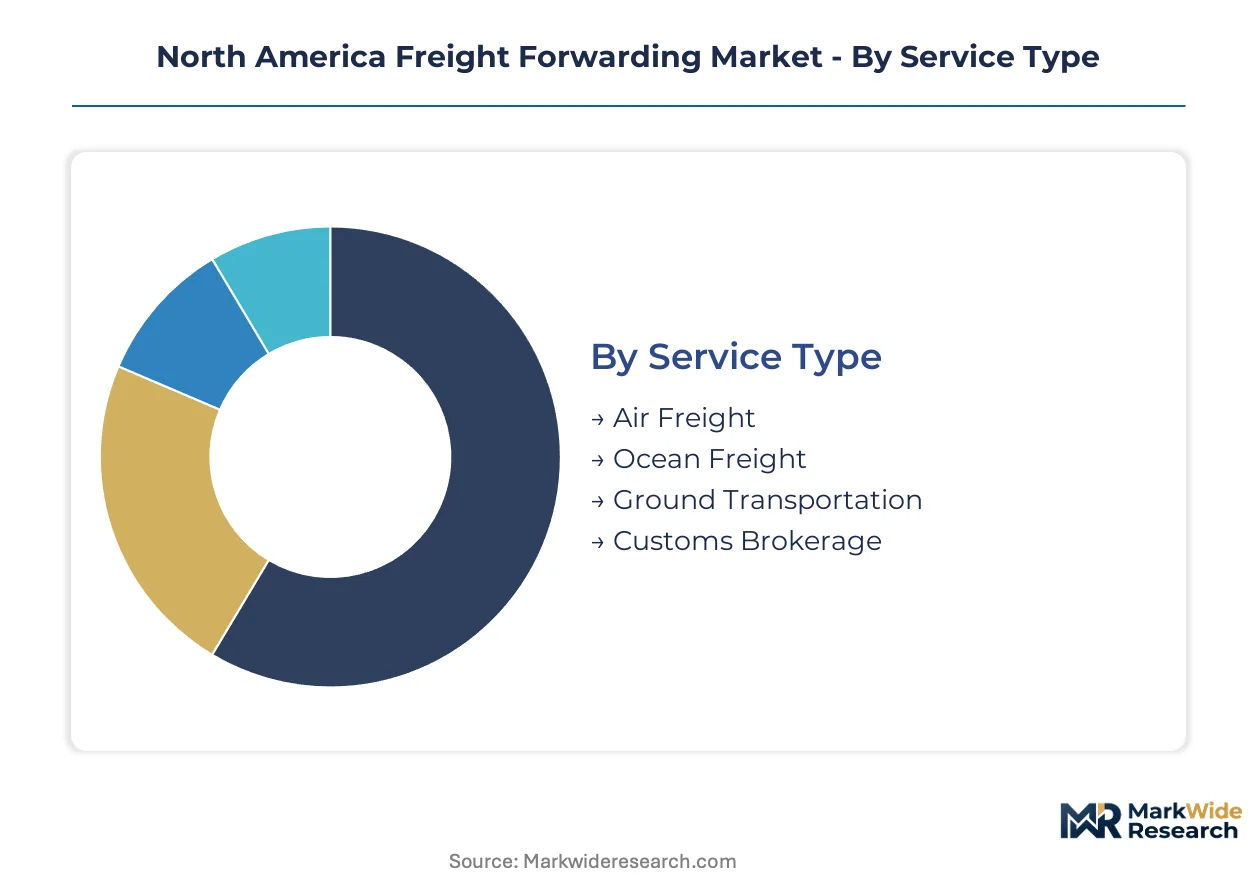
Freight forwarding segmentation in North America reflects divergent cost-service tradeoffs across modal alternatives. Each category captures distinct operational capabilities that determine competitive positioning in cross-border corridors.
Service Type:
Ground transportation faces the most acute substitution pressure as intermodal rail and nearshored air freight erode its dominance on time-sensitive lanes.
- Air Freight:Temperature-controlled cargo holds and express networks handle pharmaceutical biologics and electronics with validated chain-of-custody protocols. Demand concentrates in Detroit-Windsor and Dallas-Fort Worth corridors where automotive and aerospace manufacturers require just-in-time replenishment cycles.
- Ocean Freight:Containerized vessel operations and NVOCC arrangements manage bulk manufacturing volumes through Long Beach, Savannah, and Vancouver gateways. Automotive OEMs expanding Mexican assembly operations are driving FCL bookings through Lázaro Cárdenas and Veracruz.
- Ground Transportation:Cross-border trucking absorbs the largest volume share through USMCA-certified carrier networks. Chassis scarcity at Laredo and Otay Mesa creates persistent capacity constraints that inflate spot rates.
- Customs Brokerage:ACE and VUCEM documentation expertise generates recurring revenue from USMCA origin verification complexity. CTPAT-certified providers capture premium RFP participation from major shippers.
Ground transportation retains volume leadership; air freight holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive manufacturing verticals from inventory-light retail operations.
- Automotive:Tiered supplier networks and sequenced parts delivery demand synchronized multimodal coordination across Ontario-Michigan and Texas-Mexico production belts. OEM consolidation of forwarder relationships around single-contract liability coverage is reshaping procurement patterns.
- Pharmaceuticals:Cold-chain validation and GDP compliance requirements drive specification intensity for temperature excursions and real-time monitoring. Biologics distribution between US and Canadian hubs sustains premium pricing.
- Manufacturing:Industrial machinery and electronics shipments require harmonized tariff classification for USMCA origin claims. Blockchain-enabled documentation is displacing manual audit processes.
- Retail:E-commerce fulfillment and reverse logistics flows generate cross-border return volumes with underdeveloped brokerage infrastructure. Canadian and Mexican consumer returns to US fulfillment centers represent white space opportunity.
Automotive commands the highest service premium; pharmaceuticals posts the most rapid capability investment cycle.
Shipping Method:
Volume concentration patterns favor containerized standardization over project cargo fragmentation.
- Full Container Load (FCL):Dedicated twenty-foot and forty-foot equipment assignments eliminate consolidation complexity for high-volume shippers. Nearshored automotive and electronics manufacturing in Mexico drives consistent FCL demand through Gulf and Pacific coast ports.
- Intermodal:Rail-truck combinations optimize cost-velocity tradeoffs on Chicago-Mexico City and Memphis-Monterrey corridors. Union Pacific and BNSF investments in cross-border infrastructure expand scheduled service reliability.
- Less than Container Load (LCL):Consolidation services aggregate multiple shipper cargoes into shared container space. Freight forwarders differentiate through CFS network density and deconsolidation velocity.
- Break Bulk:Non-containerized project cargo and heavy-lift equipment movements serve energy and infrastructure sectors. Canadian Arctic shipping lanes through Hudson Bay create seasonal bulk commodity opportunities.
FCL maintains modal dominance; intermodal captures the fastest share gains on inland corridors.
Delivery Speed:
Customer type stratification separates enterprise procurement from consumer expectation thresholds.
- Expedited Shipping:Guaranteed two-to-three-day cross-border transit with proactive exception management commands 40-60% rate premiums over standard service. Automotive production lines and pharmaceutical distribution networks absorb this cost tier.
- Time-Definite Services:Appointment-scheduled delivery windows with financial penalties for non-performance support lean inventory strategies. Retail distribution centers and medical device manufacturers specify morning or afternoon arrival commitments.
- Standard Shipping:Five-to-seven-day transit expectations with flexible delivery windows minimize transportation expenditure. Bulk manufacturing inputs and non-critical maintenance parts tolerate this service level.
- Same-Day Delivery:Emergency and critical shipment protocols leverage charter air and dedicated ground assets. Aircraft-on-ground parts and clinical trial materials justify extreme cost premiums.
Expedited shipping holds revenue concentration; time-definite services demonstrate the most rapid adoption curve among enterprise accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Laredo-Colombia Solidarity International Bridge anchors North American cross-border freight capacity, processing over four million commercial truck crossings annually between Texas and Nuevo León.
United States
Automotive OEMs in Michigan and Ohio drive demand for synchronized multimodal coordination across the Detroit-Windsor corridor. US CBP enforces CTPAT and ACE requirements that determine market access for freight forwarders operating US border crossings. The Texas-Mexico manufacturing belt concentrates nearshored electronics and automotive assembly operations requiring specialized customs brokerage.
Canada
Pharmaceutical cold-chain shipments between Toronto and US distribution hubs sustain premium pricing for temperature-controlled biologics. Transport Canada and the CBSA administer parallel security programs that shape cross-border operational standards. The Ontario-Michigan automotive supply chain demands synchronized release protocols at the Buffalo-Fort Erie crossing.
Mexico
Nuevo León and Baja California anchor expanded assembly operations serving US automotive and electronics manufacturers. Mexico's SAT customs authority implements the VUCEM platform for electronic documentation. The Lázaro Cárdenas and Veracruz ports handle rising FCL volumes from nearshored manufacturing in the Bajío Region.
North America Freight Forwarding Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and corridor-specific capabilities. The market exhibits consolidated volume leadership alongside fragmented regional specialists serving single-border lanes. Three archetypes dominate: integrated express-couriers with customs brokerage arms, asset-light digital platforms aggregating carrier capacity, and specialized cold-chain operators with pharmaceutical validation. Competitive moves concentrate on CTPAT certification acquisition and ACE-VUCEM technology integration.
Within the integrated logistics tier, C.H. Robinson and FedEx Corp exemplify scale-driven operators combining digital freight platforms with customs brokerage infrastructure. DSV AS occupies a position among specialized cold-chain providers with validated pharmaceutical capabilities. These three entities represent distinct competitive vectors: platform aggregation, express-customs integration, and temperature-controlled compliance expertise.
| Leading Market Players |
|---|
| Expeditors International of Washington Inc |
| C.H. Robinson |
| DHL Group |
| Kuehne + Nagel International AG |
| DB Schenker |
| DSV AS |
| CEVA Inc |
| FedEx Corp |
| United Parcel Service Inc |
| Others |
Pricing and Supply Chain Analysis
CTPAT certification gates both supply qualification and price differentiation simultaneously, creating tiered market access where certified forwarders capture premium RFP participation while non-certified operators face exclusion from major shipper procurement cycles across the Texas-Mexico corridor.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations between automotive OEMs and forwarders, with FCL commitments above defined thresholds unlocking preferential per-unit rates. Pricing stratifies across CTPAT-certified premium, standard certified, and non-certified economy tiers based on clearance velocity guarantees and liability coverage depth. Cost compression in ground transportation is intensifying because diesel volatility and chassis scarcity at Laredo inflate operational overhead. Retail e-commerce shippers exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize cold-chain validation over rate minimization.
Supply Chain Analysis
Laredo-Colombia Solidarity Bridge transit underwrites continental cross-border capacity, processing commercial truck volumes that determine spot rate dynamics across the USMCA manufacturing belt. Equipment manufacturing draws from Mexico, the United States, and Canada, with chassis production concentrated in Mexican industrial parks and telematics hardware sourced from Canadian technology clusters. Single-source vulnerability persists at Otay Mesa and Laredo crossings where Mexican carrier certification bottlenecks constrain driver availability. Distribution runs through CTPAT-certified carrier networks with ACE pre-arrival clearance integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Customs brokerage and compliance technology represent the fastest-expanding service-attach layers, outpacing core freight margins as shippers consolidate around single-contract liability coverage requiring integrated documentation expertise.
For Market Incumbents: Secure CTPAT certification renewals and ACE-VUCEM platform integration ahead of USMCA rules of origin enforcement tightening. Vertical integration into cold-chain validation infrastructure defends pharmaceutical segment share against specialized temperature-control entrants. Channel control through exclusive chassis pool partnerships at Laredo and Otay Mesa locks in capacity access during equipment scarcity cycles. For New Entrants and Emerging Players: CTPAT fast-track programs enable rapid qualification for cross-border RFP participation previously closed to uncertified operators. White space concentrates in Canadian Arctic seasonal shipping lanes through Hudson Bay and reverse logistics brokerage for e-commerce returns from Canadian and Mexican consumers to US fulfillment centers. Go-to-market positioning should emphasize pre-arrival clearance velocity as a premium service differentiator rather than rate competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical cold-chain infrastructure as biologics distribution demands validated thermal packaging and real-time monitoring systems. Long-term viability favors asset-light digital platforms with customs brokerage attach rates over pure-play carrier operators. Acquisition targets should display ACE-VUCEM integration completion and CTPAT certification with cross-border corridor density. The signal to watch is USMCA origin verification complexity driving shipper consolidation toward integrated single-contract providers.| Strategic Initiative | Industry Significance |
|---|---|
| CTPAT Certification Acquisition | Unlocks premium RFP participation from automotive OEMs requiring security-compliant lane access. |
| ACE-VUCEM Platform Integration | Enables pre-arrival clearance services that differentiate on velocity across Texas-Mexico corridors. |
| Cold-Chain Infrastructure Investment | Captures pharmaceutical biologics volumes between Toronto and US distribution hubs. |
| Chassis Pool Partnership Expansion | Secures equipment access at Laredo and Otay Mesa during persistent scarcity cycles. |
| Reverse Logistics Capability Buildout | Addresses underdeveloped brokerage infrastructure for cross-border e-commerce returns. |
Research Methodology
A standing panel of customs brokerage directors, cross-border carrier operations managers, automotive supply chain planners, and pharmaceutical logistics coordinators provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation through US CBP enforcement data, Transport Canada security program disclosures, SAT VUCEM platform statistics, and USMCA rules of origin guidance documents. Bottom-up volume modeling across modal segments triangulated with top-down trade flow analysis.
Consistency checks validated segment-level outputs against external benchmarks including cross-border truck crossing volumes at major ports of entry, containerized freight flows through Pacific and Atlantic gateways, and pharmaceutical cold-chain shipment tracking data. The analytical framework modeled service type, end-user vertical, shipping method, and delivery speed dimensions across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and infrastructure investment cycles.
Decision-makers should treat outputs as directional under assumptions of sustained USMCA implementation and nearshoring momentum; material deviation in trade policy or carrier certification timelines would warrant model refresh. Practitioners should keep alternative scenarios live as US CBP enforcement priorities and diesel cost trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
South America Freight and Logistics Market
Logistics and Shipping
ASEAN Domestic Courier Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
China Freight Forwarding Market