
 Hungary Freight and Logistics Market | 2026-2036
Hungary Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Hungary Freight and Logistics Market Foresight
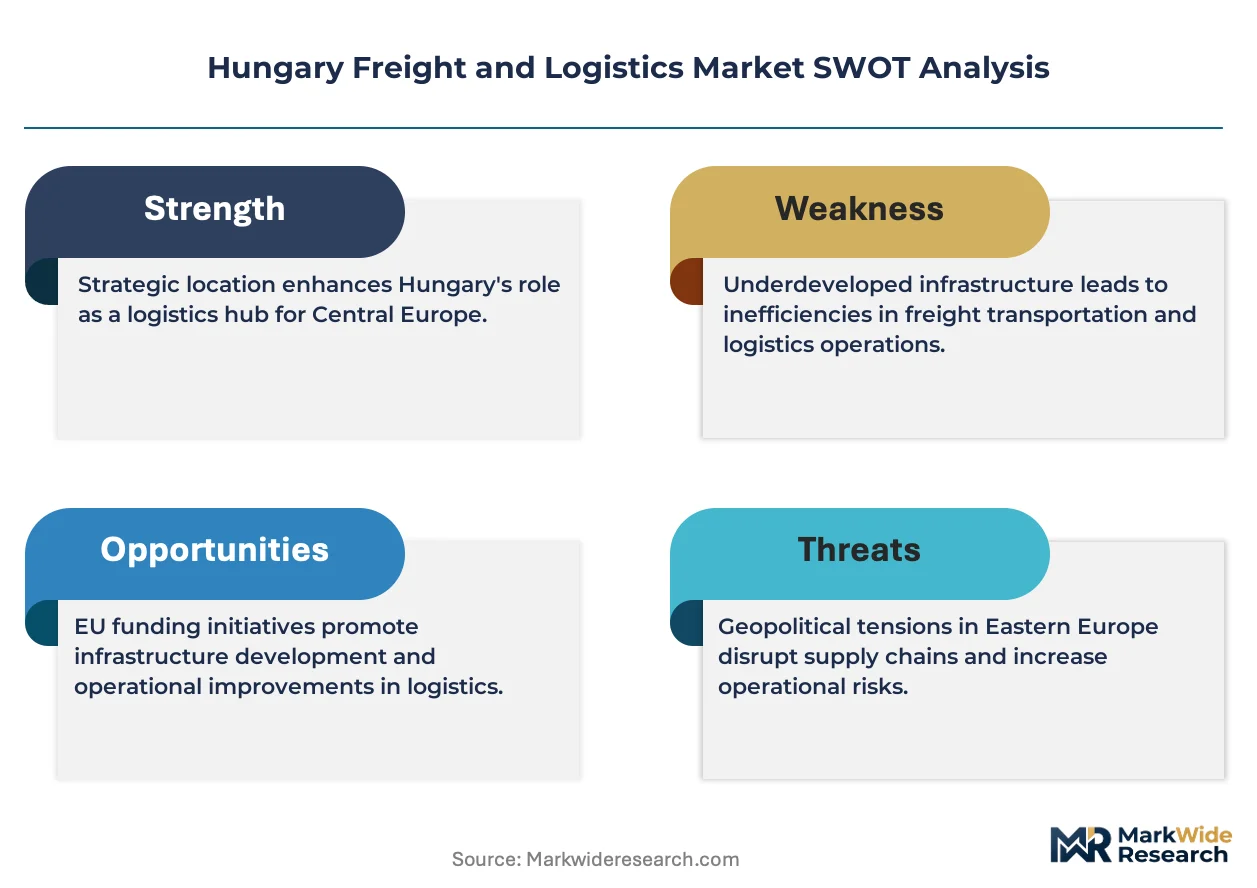
EU 561/2006 driver certification and tachograph compliance is bifurcating the Hungarian road freight sector into compliant fleet operators and non-compliant marginal players. Waberer's International Nyrt. leverages its scale to maintain tachograph-equipped fleets across European corridors. Rail Cargo Hungaria Zrt. anchors intermodal capacity through its terminal network linking Budapest to Adriatic ports. DSV Solutions Kft. differentiates via integrated warehousing and customs brokerage services at strategic M0 corridor locations.
Hungary freight and logistics encompasses the planning, execution, and management of goods movement across road, rail, air, and sea modes, typically involving cargo consolidation, cross-dock operations, and last-mile distribution within temperature-controlled or ambient parameters. The sector serves industrial supply chains by reducing inventory carrying costs and enabling just-in-time manufacturing deliveries for automotive and electronics producers. Freight forwarding commands the largest service revenue pool due to cross-border trade facilitation, while warehousing segments are gaining structural margin as e-commerce fulfillment demands higher inventory velocity and same-day processing capabilities. Road transportation dominates modal volume but faces margin compression from EU Mobility Package wage and rest-period rules, whereas rail freight is expanding share on Budapest-Koper and Budapest-Rijeka corridors for containerized automotive parts.
Hungarian operators must comply with EU Mobility Package regulations enforced through national transport authority oversight, alongside REACH and RoHS standards for hazardous materials handling in warehousing facilities. BIS-equivalent Hungarian Standards Institution certification governs cold-chain equipment specifications for pharmaceutical logistics serving regional distribution hubs. Stakeholders must monitor EU ETS carbon pricing expansion into road transport and its impact on fleet replacement decisions.
Market Dynamics
The EU Mobility Package wage and rest-period mandates are restructuring Hungarian road freight economics, forcing fleet operators to absorb higher labor costs or exit cabotage-intensive routes entirely.
Growth Catalysts
- E-commerce fulfillment velocity:Same-day delivery commitments from Budapest-based distribution centers are pulling automated sortation systems and micro-fulfillment nodes into M0 corridor warehousing clusters.
- REACH compliance infrastructure:Chemical manufacturers serving EU markets require certified hazmat handling facilities, expanding specialized storage revenue pools at Győr and Debrecen logistics parks.
- Intermodal rail corridors:Containerized automotive parts moving via Budapest-Koper and Budapest-Rijeka routes are displacing long-haul trucking for OEM supply chains.
Market Restraints
- Diesel price volatility:Fleet operators face margin erosion from fuel cost swings that cannot be fully passed through to contract customers on annual rate structures.
- Driver labor pool concentration:EU Mobility Package posting rules limit access to lower-wage non-EU drivers, tightening available hours for Hungarian-registered fleets.
- Terminal handling bottlenecks:Budapest-BILK and Csepel container terminals lack sufficient crane capacity to absorb modal shift volumes without dwell time penalties.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:BIS-equivalent cold storage certification for temperature-sensitive biologics is creating defensible margin niches for qualified warehouse operators.
- EU ETS road transport inclusion:Carbon pricing mechanisms will accelerate fleet electrification tenders, favoring early movers with charging infrastructure at Szigetszentmiklós and Vecsés hubs.
- Adriatic port connectivity:Koper and Rijeka rail links offer Hungarian freight forwarders alternative routing that bypasses Austrian toll corridors and congestion nodes.
Industry Challenges
- Tachograph compliance enforcement gaps:Fragmented inspection regimes across EU member states create competitive distortions between fully compliant Hungarian operators and marginal players exploiting detection weaknesses.
- Warehouse automation capex cycles:E-commerce fulfillment demands for same-day processing require robotic goods-to-person systems that strain mid-cap operator balance sheets.
- Legacy WMS integration:Custom brokerage and inventory platforms built for batch processing face replacement costs as real-time API-driven customer visibility becomes mandatory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hungary Freight and Logistics Market |
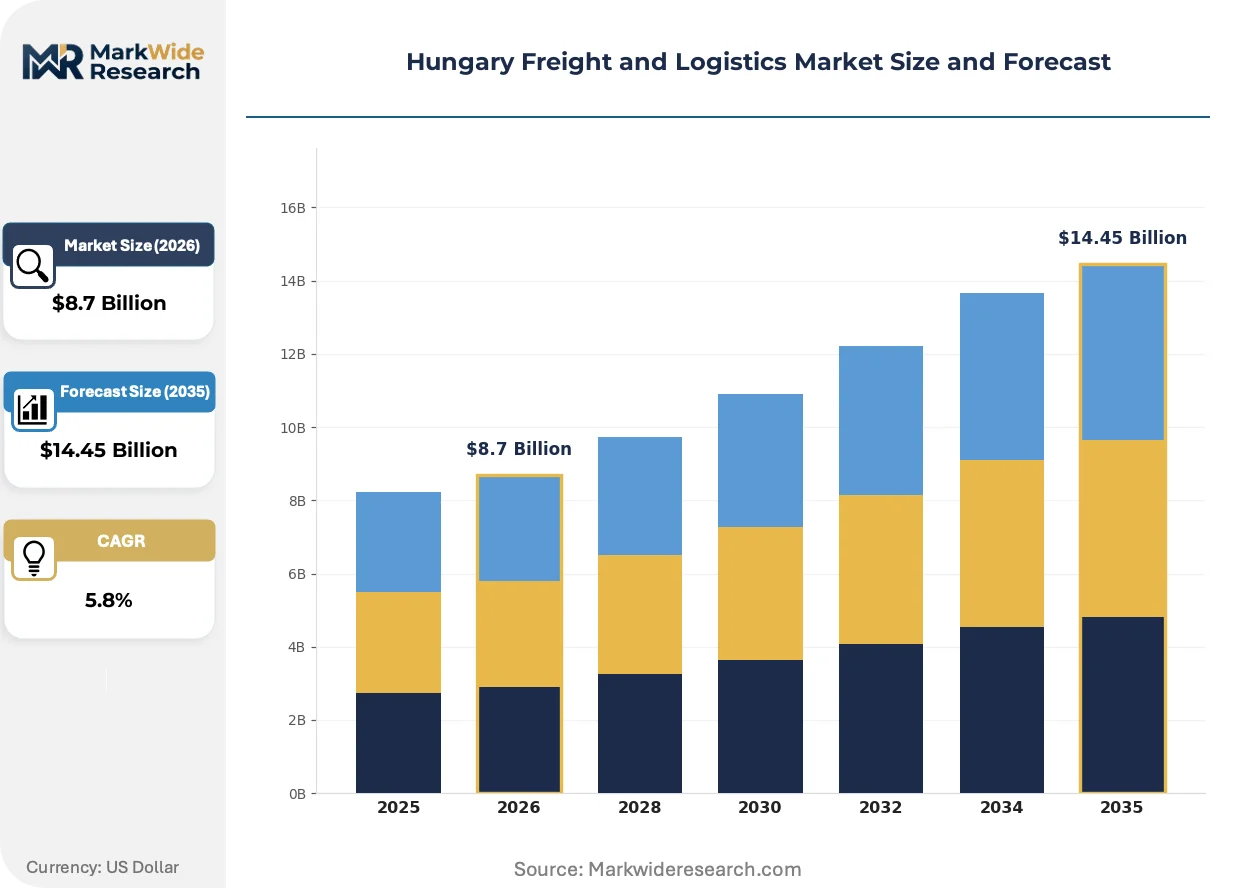
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Warehousing, Transportation, Customs Brokerage Transportation Mode: Road, Rail, Air, Sea End User: E-Commerce, Retail, Manufacturing, Automotive Technology: GPS Tracking, TMS, RFID, Blockchain |
| Companies Covered | DHL Logistics Hungary, DB Schenker, Waberer's International Nyrt., Rhenus Hungary, Kuehne+Nagel, Magyar Posta Zrt., DSV Solutions Kft., BI-KA Logisztika Kft., Rail Cargo Hungaria Zrt., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hungary Freight and Logistics Market Shifts & Advancements
Telematics and warehouse automation are compressing decision cycles across Hungarian logistics networks, shifting competitive advantage toward data-integrated operators capable of dynamic routing and inventory positioning.
Sensor-based cargo monitoring is miniaturizing. Battery-powered Bluetooth low-energy tags now track location, temperature, and shock events for pharmaceutical and electronics shipments. Automotive suppliers adopting these devices are reducing insurance claims and customs inspection delays. Real-time visibility is compressing safety stock requirements and enabling just-in-sequence delivery windows that were previously unachievable.
EU Mobility Package enforcement through Hungary's national transport authority is tightening driver posting and rest-period documentation. Fleet operators must now maintain digital records accessible to roadside inspection units across all member states. Long-haul road freight segments are responding by consolidating onto fewer, higher-utilized routes or shifting volume to rail intermodal where driver hour constraints do not apply.
Shippers are unbundling transportation management from asset ownership, contracting with 4PL providers for network optimization rather than discrete lane rates. This procurement evolution displaces traditional freight brokerage margins in favor of outcome-based logistics contracts. Hungarian automotive and electronics manufacturers are piloting these arrangements, transferring inventory carrying risk to logistics partners in exchange for guaranteed service levels.
Hungary Freight and Logistics Market Segmentation
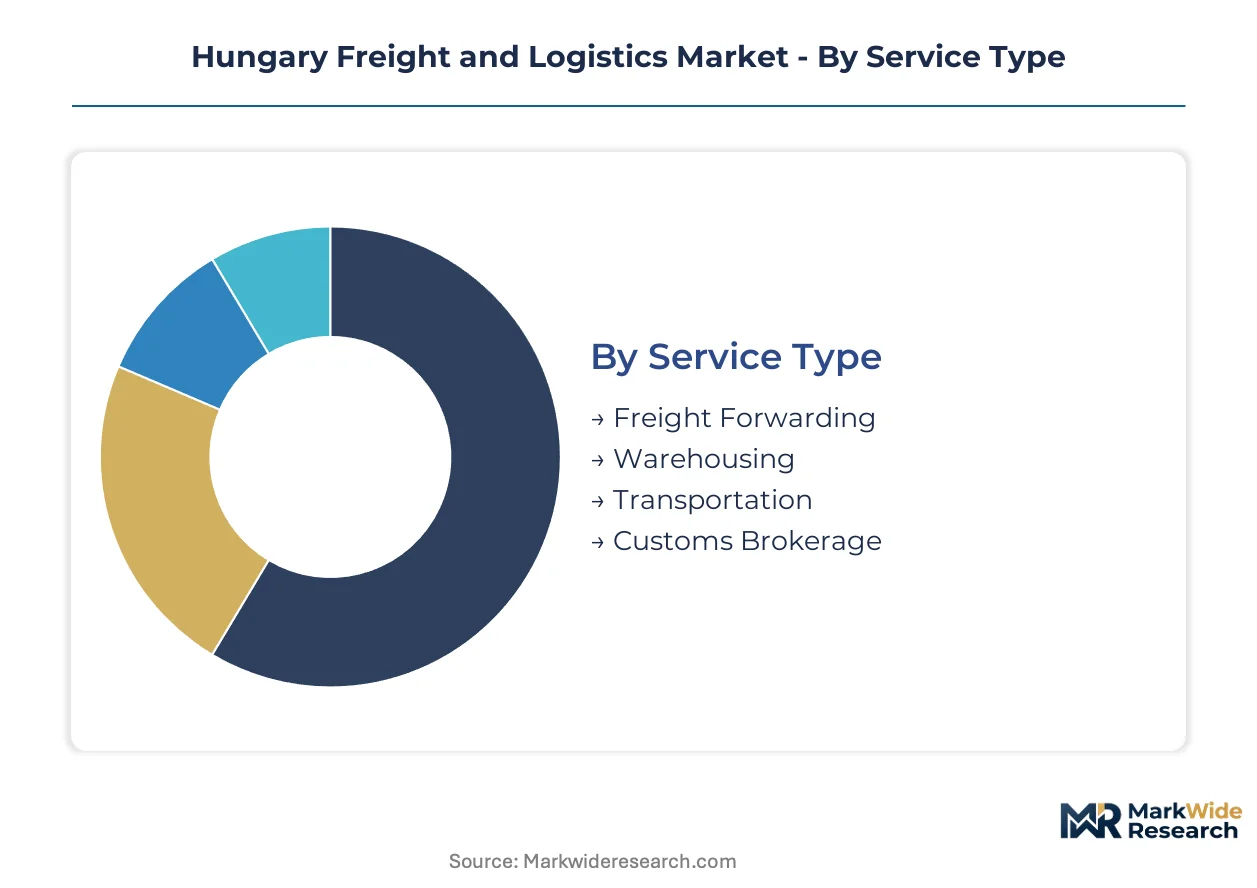
Service configuration in Hungary's freight and logistics sector determines margin capture and capital intensity. Modal choices and technology adoption separate asset-heavy operators from network orchestrators.
Service Type:
Road carriers and warehouse operators access demand through distinct channel configurations, with integrated providers commanding premium positioning.
- Freight Forwarding:Non-asset-based coordination of cross-border cargo movements through carrier networks and customs interfaces. Demand concentrates among Budapest-headquartered electronics exporters seeking Adriatic port routing alternatives to Austrian toll corridors. EU Mobility Package documentation requirements are elevating compliance costs for smaller forwarders lacking digital systems.
- Warehousing:Temperature-controlled and ambient storage facilities with value-added services including pick-pack operations and returns processing. E-commerce fulfillment networks around M0 motorway corridors are pulling automated sortation investments into Szigetszentmiklós and Vecsés logistics parks. Same-day delivery commitments from Budapest distribution centers are compressing inventory velocity requirements.
- Transportation:Asset-based fleet operations spanning FTL, LTL, and dedicated contract carriage. Hungarian-registered fleets face driver hour constraints under EU Mobility Package posting rules.
- Customs Brokerage:Documentation and duty management services for EU and non-EU trade flows. REACH and RoHS compliance verification adds specialized revenue layers for chemical and electronics shipments.
By volume, Transportation leads. By growth pace, Warehousing is expanding most quickly.
Transportation Mode:
Modal economics in Hungary diverge sharply on labor regulation exposure and infrastructure access, with rail gaining share on specific corridors.
- Road:Dominant modal volume through Hungarian-registered fleets and cabotage operations across EU member states. Diesel price volatility and EU Mobility Package wage mandates are compressing margins on long-haul segments.
- Rail:Intermodal container movements via Budapest-Koper and Budapest-Rijeka corridors for automotive parts and bulk chemicals. Rail Cargo Hungaria Zrt. anchors terminal capacity at BILK and Csepel facilities.
- Air:Time-critical shipments through Budapest Ferenc Liszt International Airport for pharmaceutical and electronics components. Limited domestic cargo infrastructure constrains scale.
- Sea:Indirect access via Adriatic port rail links, with freight forwarders coordinating maritime legs through Koper and Rijeka terminal operators.
Road retains volume leadership. Rail is gaining share fastest on containerized automotive corridors.
End User:
Customer segmentation reveals diverging service requirements, with automotive and e-commerce setting opposing poles of precision versus velocity.
- E-Commerce:Fulfillment networks demanding same-day processing and last-mile density around Budapest metropolitan area. Micro-fulfillment nodes are proliferating in M0 corridor warehousing clusters.
- Retail:Seasonal inventory positioning and returns management for multi-channel distribution. Győr and Debrecen logistics parks serve regional distribution hub functions.
- Manufacturing:Just-in-time and just-in-sequence delivery windows for electronics and industrial equipment producers. Sensor-based cargo monitoring is compressing safety stock requirements.
- Automotive:OEM and tier supplier supply chains with zero-defect tolerance and precise sequencing constraints. Containerized parts movements via Adriatic rail corridors are displacing long-haul trucking.
Automotive commands premium pricing. E-commerce is climbing the fastest on fulfillment infrastructure investment.
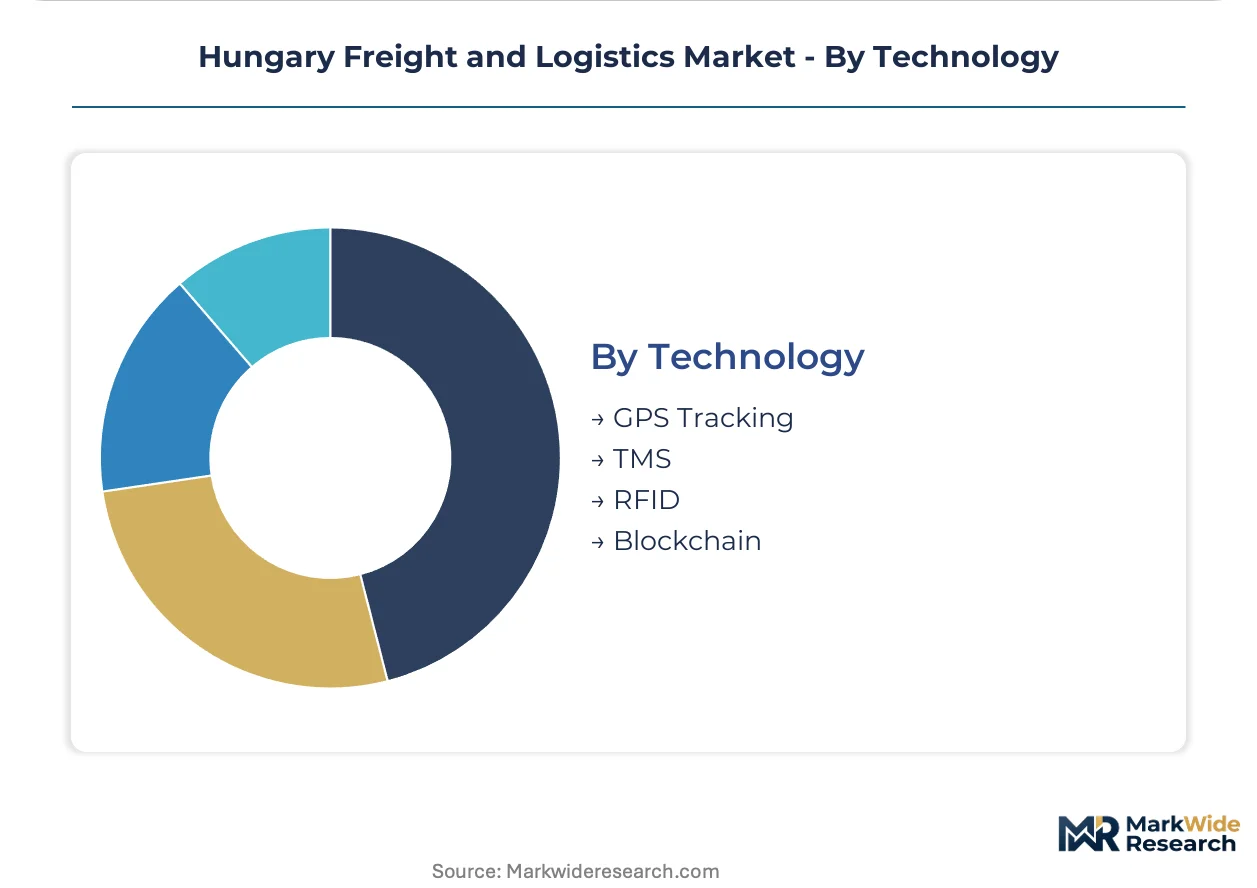
Technology:
Technology adoption stratifies operators by data integration depth, with legacy systems facing replacement pressure.
- GPS Tracking:Real-time fleet visibility and dynamic routing optimization for road transport operators. Telematics data feeds EU Mobility Package compliance documentation.
- TMS:Transportation management systems enabling carrier selection, freight audit, and network optimization. Shippers are unbundling transportation management from asset ownership.
- RFID:Automated inventory tracking and yard management for warehousing operations. Battery-powered Bluetooth low-energy tags now track location, temperature, and shock events.
- Blockchain:Pilot implementations for customs documentation and supply chain provenance. Adoption remains constrained by interoperability standards and implementation costs.
GPS Tracking holds widest deployment. TMS is on the steepest expansion trajectory as procurement shifts toward outcome-based contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration in Hungary's freight and logistics sector clusters around automotive OEMs, electronics exporters, and e-commerce fulfillment networks seeking Adriatic port connectivity and M0 corridor warehousing access.
Central Hungary
Budapest metropolitan demand concentrates on same-day e-commerce fulfillment and just-in-sequence automotive deliveries. National transport authority enforcement of EU Mobility Package posting rules tightens driver documentation requirements for fleets operating from Szigetszentmiklós and Vecsés logistics parks. M0 motorway corridor warehousing clusters are absorbing automated sortation investments to meet inventory velocity targets.
Western Hungary
Győr-based automotive suppliers drive containerized parts movements via Budapest-Koper rail corridors to bypass Austrian toll congestion. REACH compliance infrastructure for chemical manufacturers expands specialized hazmat storage revenue pools at regional logistics parks. Intermodal terminal capacity at BILK anchors cross-border freight consolidation for electronics exporters.
Eastern Hungary
Debrecen logistics parks serve retail distribution hub functions for multi-channel networks penetrating eastern EU markets. EU ETS carbon pricing anticipation accelerates fleet electrification planning among road operators serving the region. Temperature-controlled warehousing investments target pharmaceutical cold-chain certification for biologics distribution.
Southern Hungary
Csepel container terminal throughput constraints create dwell time penalties for bulk chemical shippers relying on Adriatic port rail links. Rail Cargo Hungaria Zrt. terminal network expansion aims to absorb modal shift volumes from long-haul trucking segments facing EU Mobility Package wage mandate compression.
Hungary Freight and Logistics Market Competitive Landscape
Player mix skews toward integrated asset-heavy operators with cross-border fleet networks and specialized warehousing capabilities. Market structure concentrates around pan-European logistics groups with Hungarian subsidiaries and domestic champions with regional rail terminal control. Three archetypes dominate: EU-integrated forwarders with customs brokerage depth, domestic road fleet operators with tachograph-compliant scale, and rail-intermodal specialists with Adriatic corridor access. Competitive moves center on M&A consolidation of mid-cap warehousing assets and strategic partnerships for charging infrastructure deployment.
Among integrated forwarders, DHL Logistics Hungary and Kuehne+Nagel represent the EU-integrated archetype with customs brokerage and network optimization capabilities. Waberer's International Nyrt. anchors the domestic fleet operator tier with tachograph-equipped scale across European corridors. Rail Cargo Hungaria Zrt. occupies the rail-intermodal specialist position through its terminal network linking Budapest to Adriatic ports.
| Leading Market Players |
|---|
| DHL Logistics Hungary |
| DB Schenker |
| Waberer's International Nyrt. |
| Rhenus Hungary |
| Kuehne+Nagel |
| Magyar Posta Zrt. |
| DSV Solutions Kft. |
| BI-KA Logisztika Kft. |
| Rail Cargo Hungaria Zrt. |
| Others |
Supply & Pricing Matrix
Rail containerization displacing long-haul trucking on Budapest-Koper and Budapest-Rijeka corridors simultaneously redraws supply geography toward Adriatic ports and compresses road freight pricing power through modal competition. EU Mobility Package wage mandates feed directly into contract rate indexation clauses, forcing Hungarian fleet operators to absorb labor cost escalations or surrender cabotage-intensive lanes to lower-cost rail intermodal.
Pricing Analysis
Cost-plus contracts with diesel indexation dominate annual rate structures between Hungarian road carriers and automotive OEMs, embedding fuel volatility into margin risk rather than customer pricing. Price differentiation separates tachograph-compliant fleet operators from marginal players through EU Mobility Package documentation premiums, with certified carriers commanding standard-tier rates while non-compliant competitors compete on economy pricing. Pricing pressure stems from driver wage floor harmonization across EU member states, eroding Hungary's historical labor cost advantage on international routes. E-commerce fulfillment networks exhibit highest price sensitivity due to same-day delivery commitments compressing logistics budgets, whereas pharmaceutical cold-chain shippers accept premium tiers for BIS-equivalent temperature certification.
Supply Chain Analysis
Just-in-sequence delivery preferences among Győr-based automotive OEMs minimize buffer inventory, tethering Hungarian assembly plants to precise rail and road arrival windows from German, Czech, and Slovak component suppliers. Raw material dependencies center on containerized automotive parts, diesel fuel for road fleets, and specialized cold-chain equipment for pharmaceutical warehousing. Supply chain risk concentrates on terminal handling bottlenecks at Budapest-BILK and Csepel facilities, where crane capacity constraints create dwell time penalties that cascade through just-in-time schedules. Distribution runs through M0 corridor warehousing clusters at Szigetszentmiklós and Vecsés, with last-mile density concentrated around Budapest metropolitan fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hungary's freight and logistics sector sits at a platform-economics inflection where 4PL network orchestration displaces discrete lane contracting, rewarding operators with API-driven visibility and outcome-based pricing interoperability.
For Market Incumbents: Fortify tachograph-compliant fleet scale through selective acquisition of mid-cap operators facing EU Mobility Package documentation cost pressure, while deepening Adriatic corridor rail intermodal partnerships to offset driver hour constraints on long-haul segments. Anchor M0 corridor warehousing positions with automated sortation capex at Szigetszentmiklós and Vecsés logistics parks before e-commerce fulfillment velocity requirements harden infrastructure lock-in. For New Entrants and Emerging Players: Lead with pharmaceutical cold-chain certification as the most penetrable white-space segment, where BIS-equivalent temperature compliance creates defensible margin niches underserved by generalist warehouse operators. Target Debrecen logistics parks for temperature-controlled biologics distribution infrastructure, exploiting eastern Hungary's underinvestment relative to Budapest-centric fulfillment networks. Position through specialized hazmat handling credentials for REACH-compliant chemical manufacturers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated operators with cross-border fleet networks and rail terminal control over pure-play road carriers facing structural margin compression. Long-term viability over the next decade hinges on electrification readiness and charging infrastructure deployment at strategic hubs. The signal to watch is EU ETS carbon pricing expansion into road transport, which would accelerate fleet replacement cycles and favor early movers with charging assets at Szigetszentmiklós and Vecsés.| Strategic Initiative | Industry Significance |
|---|---|
| Rail Intermodal Expansion | Budapest-Koper corridor investments bypass Austrian toll congestion for automotive OEM supply chains. |
| Charging Infrastructure Partnership | Hub electrification at M0 corridor logistics parks positions operators for EU ETS road transport inclusion. |
| Cold-Chain Certification Investment | BIS-equivalent temperature compliance captures pharmaceutical biologics distribution premium tiers. |
| Automated Sortation Deployment | Robotic goods-to-person systems at Vecsés warehousing clusters meet e-commerce same-day velocity targets. |
| 4PL Platform Integration | API-driven network orchestration displaces traditional freight brokerage through outcome-based contracting. |
Research Methodology
The analysis maps road transportation, rail intermodal, warehousing, and customs brokerage sub-sectors, each validated through fleet operations directors, terminal managers, e-commerce fulfillment planners, and pharmaceutical logistics specialists. Primary interviews with Hungarian road carriers, rail terminal operators, and M0 corridor warehouse developers combined with secondary validation from EU transport authority enforcement data, REACH compliance filings, and customs trade statistics. Bottom-up service segment sizing and top-down modal volume triangulation anchored market estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated service type, transportation mode, end-user industry, and technology adoption dimensions. CAGRs derived from trend extrapolation of e-commerce fulfillment velocity, EU Mobility Package enforcement intensity, and rail corridor capacity expansion timelines. Industry-specific forecast inputs included driver hour constraint elasticity and terminal handling capacity utilization curves.
Forecasts assume regulatory continuity in EU Mobility Package posting rules and EU ETS carbon pricing frameworks; material policy shifts would require re-modeling labor cost pass-through assumptions and fleet electrification timelines. Revision becomes warranted when Adriatic port rail corridor dwell times or Budapest terminal crane capacity constraints cross thresholds that trigger modal shift acceleration beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
Australia Mining Logistics Market
Logistics and Shipping
Iraq Air Freight Transport Market
Logistics and Shipping
Last-Mile Delivery Market
Logistics and Shipping
Thailand Cold Chain Logistics Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
US Dangerous-Hazardous Goods Logistics Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
US Air Freight Transport Market
Logistics and Shipping
Fine Art Logistics Market