
 Hong Kong Container Transshipment Market | 2026-2036
Hong Kong Container Transshipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Container Transshipment Market Insights
Market Context
Terminal operators across the Pearl River Delta are rebalancing berth allocations to accommodate ultra-large container vessels. Hutchison Ports HIT leverages its deep-water infrastructure to sustain throughput leadership at Kwai Tsing. China Merchants Port anchors cross-border feeder connectivity with Shenzhen ports. Modern Terminals differentiates through automated yard operations and refrigerated cargo specialization.
Technical Definition and Segment Structure
Hong Kong Container Transshipment involves the transfer of standardized ISO containers between mainline vessels and feeder services without customs clearance, requiring gantry cranes with outreach exceeding 22 container rows and yard stacking densities above 7 high. Full Container Load services dominate revenue contribution due to direct shipping line contracts, while Less than Container Load segments are expanding fastest among freight forwarders consolidating SME cargo. Digital Platforms within the Technology segment are capturing disproportionate investment as terminal operators deploy port community systems to reduce documentation friction.
Regulatory Framework
The Hong Kong Maritime and Port Board coordinates with China's Ministry of Transport on vessel emission control area compliance, while the Marine Department enforces the International Maritime Organization's sulphur cap regulations through local ordinances. Terminal operators must align with the Hong Kong Green Seaport Policy's shore power mandates and the Greater Bay Area's unified customs clearance protocols. Stakeholders should monitor how the region's carbon intensity benchmarks reshape vessel routing decisions and terminal energy infrastructure requirements.
Market Dynamics
The Hong Kong Maritime and Port Board's smart port initiatives are compressing terminal automation timelines while berth reallocation for ultra-large vessels concentrates throughput at deep-water facilities. This structural tension between physical capacity constraints and digital upgrade imperatives defines current market motion.
Growth Catalysts
- Shore Power Mandates:The Hong Kong Green Seaport Policy's shore power requirements are accelerating terminal electrification investments. Kwai Tsing operators retrofit berth infrastructure to capture compliance-driven service premiums.
- E-commerce Velocity Demands:Cross-border retailers require inventory positioning within 48-hour delivery radii of Pearl River Delta consumers. Transshipment hubs enable rapid restocking without mainland customs delays.
- Greater Bay Area Integration:Unified customs clearance protocols between Hong Kong and Shenzhen reduce container dwell times. Feeder connectivity investments unlock cross-border cargo pooling efficiencies.
Market Restraints
- Bunker Fuel Volatility:Vessel operators face margin compression from IMO 2020 sulphur cap compliance costs. Low-sulphur fuel oil price swings distort transshipment routing economics.
- Land Scarcity Premium:Container yard expansion at Kwai Tsing encounters hard physical limits. Stacking density gains require automation capex that smaller terminals cannot absorb.
- Feeder Service Concentration:Cross-border barge capacity depends on Shenzhen port operators. Route scheduling inflexibility constrains Hong Kong's hub-and-spoke optimization.
Strategic Opportunities
- Reefer Specialization:Pharmaceutical cold chain and fresh produce segments remain underpenetrated. Automated yard systems enable temperature-traceable transshipment services.
- Digital Platform Convergence:Port community systems integrating blockchain documentation with customs pre-clearance reduce friction. Shipping lines prioritize terminals with API-ready data exchange.
- Carbon Intensity Benchmarking:The Greater Bay Area's emerging emissions trading mechanisms reward low-carbon routing. Early shore power adopters capture preference from ESG-mandated cargo owners.
Industry Challenges
- Cyber-Physical Integration:Automated gantry systems require real-time coordination between terminal operating systems and vessel stowage planners. Legacy equipment retrofit timelines stretch 18-24 months.
- Specialized Technician Scarcity:Remote crane operation and predictive maintenance analytics demand hybrid maritime-IT skill sets. Training pipelines lag automation deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Container Transshipment Market |
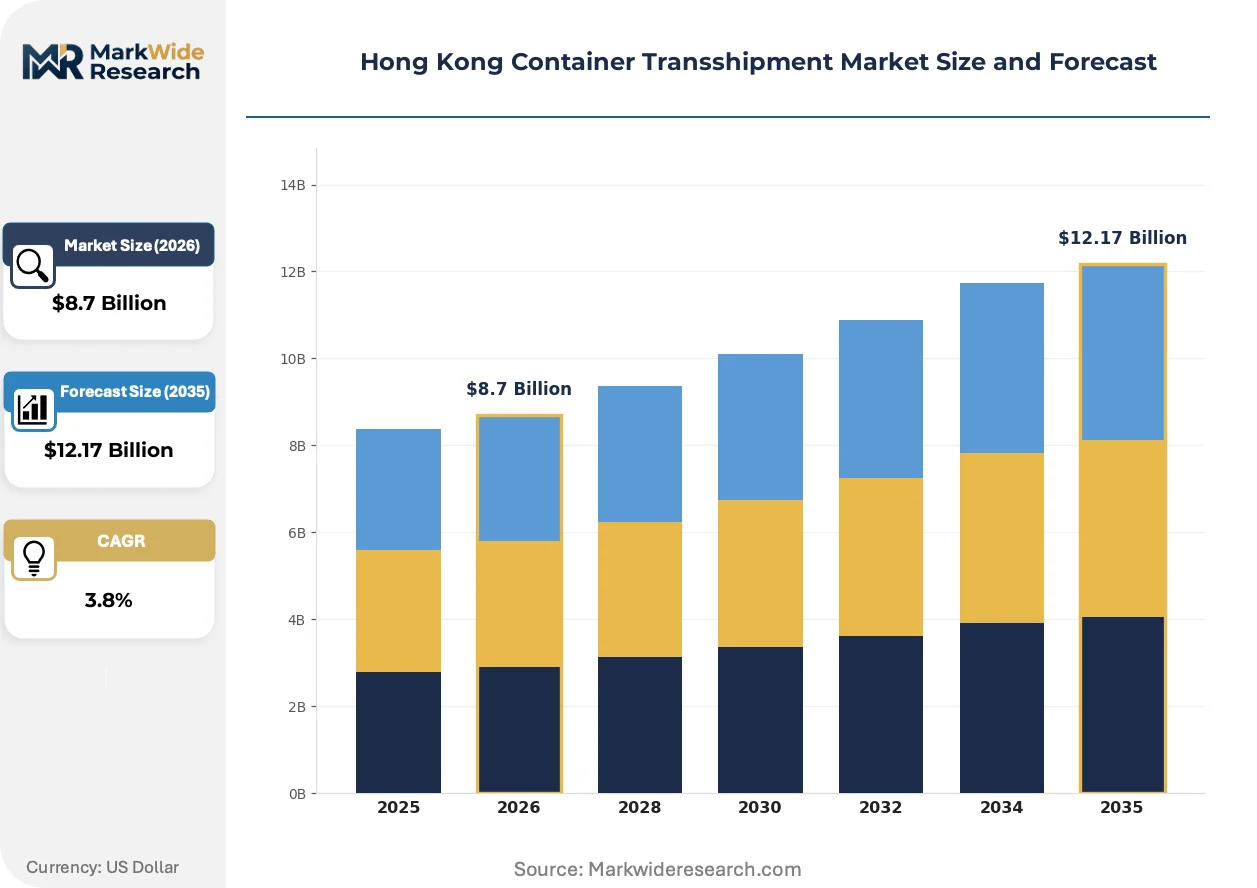
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Container Load, Less than Container Load, Intermodal, Bulk Cargo Client Type: Shipping Lines, Freight Forwarders, Logistics Providers, Importers Technology: Automated Systems, Digital Platforms, Tracking Solutions, Container Management End User: Manufacturers, Retailers, Wholesalers, E-commerce |
| Companies Covered | Asia Container Terminals, China Merchants Port, Hutchison Ports HIT, Evergreen Marine (Hong Kong) Limited, DP World Hong Kong, Modern Terminals, Hongkong International Terminals, APM Terminals, COSCO-HIT Terminals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Container Transshipment Market Trends and Innovations
Terminal digitization is compressing documentation cycles while vessel size escalation forces berth productivity reinvention. These intersecting pressures favor operators with capital depth for simultaneous physical and software upgrades.
Port community systems are unifying previously fragmented customs, terminal, and carrier data streams. Mid-size shipping lines now mandate API connectivity for transshipment contracts, excluding non-compliant facilities from routing algorithms. This unifying infrastructure is compressing competitive differentiation around data transparency rather than physical location alone.
The Hong Kong Maritime and Port Board's smart port roadmap mandates interoperable data standards across Kwai Tsing terminals. Terminal operators must reconfigure legacy terminal operating systems to comply with standardized container event messaging. Reefer cargo segments face the steepest adaptation costs given temperature monitoring integration requirements.
Cargo owners now specify routing through emission-intensity metrics rather than transit time alone. Pharmaceutical and electronics verticals embed carbon accounting into procurement scorecards, displacing pure cost-based carrier selection. This preference shift concentrates volume at terminals with verified shore power utilization and renewable energy procurement.
Hong Kong Container Transshipment Market Segmentation
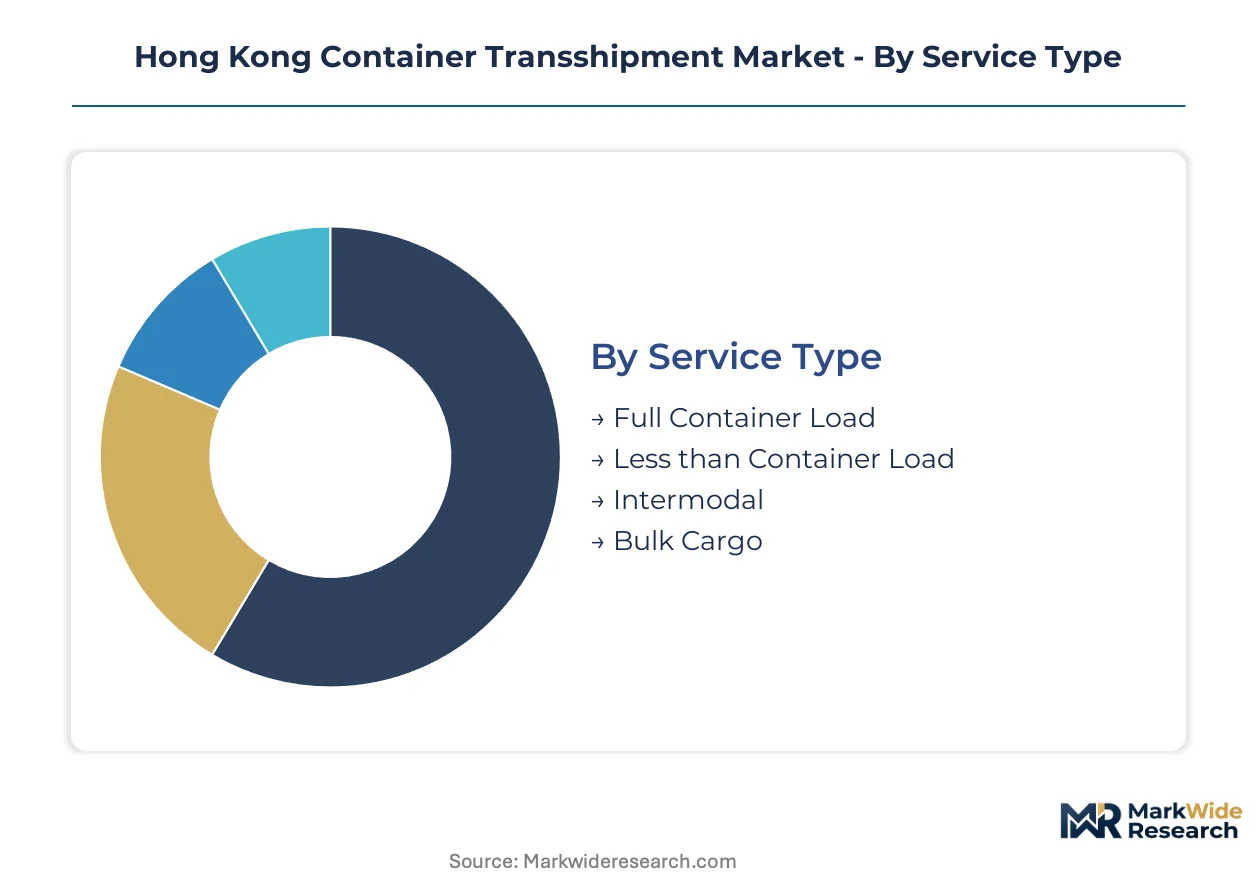
Container transshipment economics hinge on service differentiation across cargo consolidation patterns and client procurement structures. Segment boundaries reflect terminal operator specialization investments and the Greater Bay Area's cross-border logistics integration.
Service Type:
Supply concentration at Kwai Tsing deep-water berths favors operators with dedicated gantry crane fleets and automated yard systems serving high-volume cargo categories.
- Full Container Load:Direct shipping line contracts for standardized ISO container movements between mainline vessels and feeder services. Hutchison Ports HIT and Modern Terminals capture dominant throughput share through long-term vessel alliance agreements at Kwai Tsing.
- Less than Container Load:Freight forwarder-consolidated cargo requiring deconsolidation and reconsolidation within terminal yards. SME cargo volumes from Pearl River Delta manufacturers are climbing fastest as e-commerce platforms fragment shipment sizes.
- Intermodal:Seamless container transfers connecting maritime terminals with cross-border barge and rail networks. China Merchants Port anchors feeder connectivity with Shenzhen's Yantian and Shekou terminals.
- Bulk Cargo:Non-containerized breakbulk and project cargo requiring specialized berth configurations. Limited yard space at Kwai Tsing constrains expansion beyond niche industrial equipment segments.
Today's leader: Full Container Load. Tomorrow's challenger: Less than Container Load.
Client Type:
Procurement authority concentrates with vessel operators controlling berth allocation priorities, while freight intermediaries gain influence through cargo consolidation scale.
- Shipping Lines:Ocean carriers with direct terminal service contracts specifying crane productivity rates and vessel turnaround windows. Alliance structures concentrate bargaining power among top-tier operators.
- Freight Forwarders:Third-party logistics intermediaries aggregating shipper cargo for consolidation efficiency. NVOCC licensing requirements from the Hong Kong Marine Department shape competitive entry barriers.
- Logistics Providers:Integrated supply chain operators offering warehousing, distribution, and customs brokerage alongside transshipment coordination. Greater Bay Area warehouse networks extend terminal value chains into mainland distribution.
- Importers:Direct cargo owners negotiating terminal handling agreements for high-volume commodity flows. Electronics and pharmaceutical verticals drive reefer infrastructure requirements.
Contract concentration favors shipping lines presently. Freight forwarders are gaining procurement leverage fastest.
Technology:
Capital deployment patterns reveal automation maturity gaps between legacy terminal operating systems and API-ready port community infrastructure.
- Automated Systems:Gantry crane remote operation and automated guided vehicle yard management reducing labor dependency. Predictive maintenance analytics demand hybrid maritime-IT technician pipelines.
- Digital Platforms:Port community systems integrating blockchain documentation with customs pre-clearance protocols. The Hong Kong Maritime and Port Board's smart port roadmap mandates interoperable data standards.
- Tracking Solutions:Real-time container location and condition monitoring through IoT sensor networks. Reefer cargo segments require temperature-traceable chain-of-custody verification.
- Container Management:Yard optimization software balancing stacking density against vessel stowage planner coordination. Legacy equipment retrofit timelines stretch across 18-24 month deployment cycles.
Automated Systems currently absorb the largest capital allocation. Digital Platforms are expanding most quickly through regulatory compliance mandates.
End User:
Cargo velocity requirements diverge between production-linked manufacturers and consumption-facing retailers across the Pearl River Delta economic corridor.
- Manufacturers:Production-scheduled inbound raw material and outbound finished goods container flows. Electronics and automotive verticals dominate volume contribution through just-in-time inventory protocols.
- Retailers:Seasonal inventory positioning requiring rapid restocking within 48-hour delivery radii. Cross-border e-commerce platforms are driving fastest growth in small-lot consolidation demand.
- Wholesalers:Bulk commodity distribution intermediaries with lower velocity tolerance but higher volume concentration. Food and beverage categories sustain reefer infrastructure utilization.
- E-commerce:Direct-to-consumer fulfillment platforms fragmenting shipment sizes and compressing dwell time requirements. Inventory positioning without mainland customs delays anchors transshipment hub value.
Manufacturers retain volume leadership. E-commerce represents the steepest expansion trajectory through inventory velocity mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping container transshipment flows as vessel operators seek cost-of-compliance advantages across Greater Bay Area ports. Hong Kong's shore power mandates and emission control protocols create divergent operating economics against Shenzhen's Yantian and Shekou terminals.
Kwai Tsing Container Terminals
Kwai Tsing's deep-water berths handle ultra-large container vessels requiring gantry crane outreach exceeding 22 rows. The Hong Kong Maritime and Port Board enforces shore power connection mandates under the Green Seaport Policy. Hutchison Ports HIT and Modern Terminals anchor throughput leadership through automated yard systems.
Shenzhen Port Cluster
Yantian and Shekou terminals capture feeder traffic through China's Ministry of Transport emission control area flexibilities. Cross-border barge services reduce dwell times via unified customs clearance protocols with Hong Kong. China Merchants Port anchors this corridor through dedicated feeder vessel allocations.
Guangzhou Nansha
Nansha's expanding berth infrastructure attracts transshipment volume from Pearl River Delta manufacturers. The Guangdong provincial government funds intermodal rail connections under Greater Bay Area integration plans. Automotive and electronics clusters in Foshan and Dongguan drive container feedering demand.
Macau Outer Harbor
Macau's limited container infrastructure specializes in high-value reefer cargo for pharmaceutical cold chains. The Macau SAR government maintains simplified customs protocols for transshipment cargo. Small-lot consolidation services support regional food and beverage distribution networks.
Hong Kong Container Transshipment Market Competitive Landscape
Established terminal operators occupy the standard tier through deep-water berth control and long-term vessel alliance contracts; emerging entrants pursue digital platform differentiation and reefer specialization. The market structure concentrates around three to four major terminal operating companies controlling Kwai Tsing capacity. Strategic archetypes include scale-driven alliance anchor terminals, automation-first specialists, and cross-border feeder integrators. Dominant competitive moves involve berth automation retrofits and shore power infrastructure investments.
Within the scale-driven tier, Hutchison Ports HIT and China Merchants Port occupy positions defined by vessel alliance anchorage and cross-border feeder connectivity. Modern Terminals exemplifies the automation-specialist archetype through automated yard operations. DP World Hong Kong represents international terminal operator participation in the Greater Bay Area corridor.
| Leading Market Players |
|---|
| Asia Container Terminals |
| China Merchants Port |
| Hutchison Ports HIT |
| Evergreen Marine (Hong Kong) Limited |
| DP World Hong Kong |
| Modern Terminals |
| Hongkong International Terminals |
| APM Terminals |
| COSCO-HIT Terminals |
| Others |
Pricing and Supply Chain Analysis
Shore power compliance tiering separates Kwai Tsing's electrified berths from Shenzhen's conventional alternatives, compressing margins at automated terminals while amplifying rate premiums for emission-verified services. This divergence channels vessel alliance contracts toward facilities with verified shore power utilization and API-ready data exchange capabilities.
Pricing Analysis
Terminal handling charges flow through vessel alliance contract structures with volume-scaled rebates and crane productivity guarantees. Price differentiation rests on shore power compliance certification and automated yard system integration, with Kwai Tsing operators capturing service premiums against Shenzhen alternatives. Pricing pressure stems from low-sulphur fuel oil volatility distorting transshipment routing economics. Freight forwarders consolidating SME cargo exhibit highest price sensitivity; shipping lines with long-term berth agreements demonstrate lowest.
Supply Chain Analysis
Empty container repositioning and reefer equipment refurbishment cycles create secondary logistics flows between Pearl River Delta manufacturing clusters and Hong Kong terminals. Manufacturing concentration draws from Dongguan electronics corridors, Foshan automotive plants, and Shenzhen consumer technology zones. Supply chain risk centers on cross-border barge capacity bottlenecks at Shenzhen port operators. Distribution runs through vessel alliance networks with dedicated feeder vessel allocations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hong Kong Container Transshipment Market functions as a regulatory compounder where the Hong Kong Green Seaport Policy's shore power mandates and IMO sulphur cap enforcement create compliance-driven demand concentration at electrified facilities.
For Market Incumbents: Anchor throughput leadership through accelerated berth automation retrofits and shore power infrastructure completion before Shenzhen competitors capture ESG-mandated cargo. Defend against feeder service concentration risk by securing dedicated cross-border barge allocations with China Merchants Port. Vertical integration into reefer cold chain services captures pharmaceutical and fresh produce premiums. For New Entrants and Emerging Players: Capture digital platform white space through blockchain-enabled port community systems integrating customs pre-clearance with vessel stowage planners. The most penetrable segment lies with mid-size shipping lines mandating API connectivity for transshipment contracts. Go-to-market leverage rests on interoperability certifications under the Hong Kong Maritime and Port Board's smart port roadmap. For Investors and Strategic Acquirers: Consolidation pressure builds where automation capex requirements exceed smaller terminal operators' balance sheet capacity. Long-term viability favors facilities with simultaneous deep-water berth control and shore power compliance. Acquisition targets include automation-specialist terminals with reefer infrastructure and API-ready operating systems. Monitor carbon intensity benchmark adoption across Greater Bay Area emissions trading mechanisms as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Shore Power Infrastructure Expansion | Kwai Tsing operators capture compliance premiums under Hong Kong Green Seaport Policy mandates. |
| Port Community System Integration | Blockchain documentation reduces customs friction for shipping lines prioritizing API-ready terminals. |
| Reefer Specialization Investment | Automated yard systems enable temperature-traceable services for pharmaceutical cold chains. |
| Cross-Border Feeder Alliance | China Merchants Port anchors Shenzhen connectivity through dedicated barge vessel allocations. |
| Terminal Operating System Retrofit | Legacy equipment upgrades comply with Hong Kong Maritime and Port Board interoperability standards. |
Research Methodology
Multiple input streams — terminal operator financial disclosures, vessel alliance contract structures, and customs throughput statistics — were reconciled across primary interviews with terminal operations directors, shipping line network planners, freight forwarder consolidation specialists, and Marine Department regulatory officials. Secondary validation drew from Hong Kong Maritime and Port Board smart port roadmaps, IMO emission control area filings, and Greater Bay Area customs integration protocols. Bottom-up container volume modeling and top-down market sizing triangulation anchored value estimates.
Data-stream reconciliation across the projection horizon applied service type, client category, technology tier, and end-user industry segmentation. CAGRs derived from berth productivity trends, automation deployment timelines, and cross-border logistics integration trajectories. Forecast inputs incorporated vessel size escalation patterns and shore power adoption curves across Pearl River Delta terminals.
Regulatory enforcement delays, bunker fuel price volatility, and cyber-physical integration failures are the dominant revision risks to throughput and value projections. Practitioners should monitor IMO sulphur cap compliance cost trajectories and Greater Bay Area emissions trading mechanism launches for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Nigeria Freight and Logistics Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asean Freight Forwarding Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Smart Container Market