
 North America Logistics Automation Market | 2026-2036
North America Logistics Automation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Logistics Automation Market Analytics
Asset-light leasing models for autonomous mobile robots are rewriting capital deployment patterns across the sector. Honeywell Intelligrated leverages its controls heritage to dominate high-throughput distribution installations. Daifuku Co. Limited anchors its North American position through captive manufacturing of conveyor and sortation subsystems. Dematic Corp competes on software-integrated fulfillment architectures that compress commissioning timelines.
North America logistics automation encompasses the electromechanical and software systems that execute material handling, storage, retrieval, and transportation coordination with minimal human intervention, typically operating at throughput velocities exceeding 150 cartons per minute in high-density configurations. The primary purpose centers on labor cost arbitrage, inventory accuracy improvement, and order cycle time compression in multi-channel distribution environments. Warehouse Management Systems command the largest installed base but face margin compression from cloud-native entrants, while Robotic Process Automation captures disproportionate capital allocation due to labor substitution economics in e-commerce picking. AI-Powered Analytics remains nascent in revenue contribution yet attracts venture funding for predictive demand-forecasting applications.
FAA regulations governing beyond-visual-line-of-sight drone delivery are constraining last-mile automation pilots in suburban US corridors, while OSHA standards for collaborative robot safeguarding shape workstation design specifications. The EPA's Phase 3 greenhouse gas rules for heavy-duty trucks are forcing fleet management providers to integrate electric vehicle charge optimization into their platforms. Stakeholders must track NHTSA autonomous trucking rulemakings and CSA scores to anticipate driverless corridor openings.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing order cycle times from days to hours, forcing distributors to reconfigure warehouse layouts around robotic picking density rather than traditional aisle-based storage economics.
Growth Catalysts
- FAA Beyond-Visual-Line-of-Sight Framework:The regulator's evolving drone delivery guidelines are unlocking pilot programs for automated last-mile distribution in suburban corridors.
- Great Lakes Manufacturing Corridor:Concentrated automotive and industrial equipment production across Michigan, Ohio, and Illinois is generating sustained demand for automated material handling systems.
- Cloud-Native Warehouse Management Systems:These platforms are displacing legacy on-premise installations through faster deployment timelines and subscription-based cost structures.
Market Restraints
- Steel and Aluminum Input Volatility:Conveyor and racking manufacturers face margin pressure from commodity price swings in structural metals.
- OSHA Collaborative Robot Safeguarding:Compliance with workstation force-limiting and speed-monitoring specifications extends system commissioning timelines.
- Fixed-Battery Electric Forklifts:These systems compete with hydrogen fuel cell alternatives for heavy-load, multi-shift operations in cold storage environments.
Strategic Opportunities
- Mexican Nearshoring Expansion:Manufacturing relocation from Asia is creating greenfield automation demand in Monterrey and Tijuana industrial zones.
- AI-Powered Predictive Maintenance:Integration of machine learning with fleet telematics is enabling condition-based servicing of automated guided vehicles.
- US Department of Transportation Infrastructure Mandates:Federal telematics deployment requirements are accelerating fleet management platform upgrades.
Industry Challenges
- Controls Engineering Talent Scarcity:Shortages in PLC programming and industrial network configuration are extending system integration timelines.
- Multi-Vendor System Interoperability:Proprietary communication protocols between robotic subsystems from different suppliers create integration friction.
- Legacy WMS Data Migration:Decades of accumulated inventory records in outdated formats complicate cloud platform transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Logistics Automation Market |
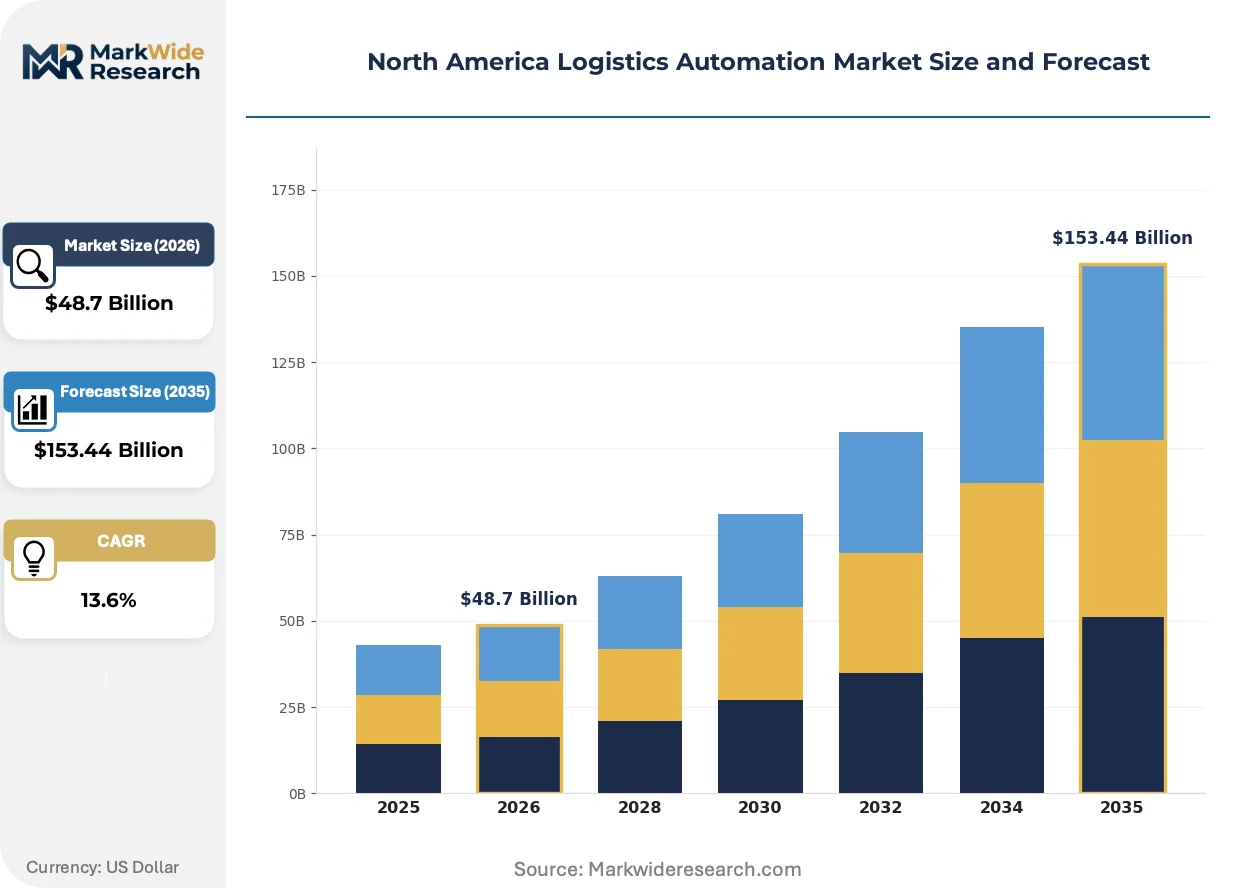
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $153.44 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Robotic Process Automation, Warehouse Management Systems, Fleet Management Solutions, AI-Powered Analytics Application: E-commerce, Manufacturing, Retail, Transportation End User: Third-Party Logistics Providers, Manufacturers, Retailers, Freight Forwarders Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Honeywell Intelligrated, Daifuku Co. Limited, SSI Schaefer AG, Swisslog Holdings AG, Dematic Corp, Beumer Group GmbH & Co. KG, Kardex Group, TGW Logistics Group GmbH, Mecalux SA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Logistics Automation Market Evolving Landscape
Automation architectures are pivoting from centralized control hierarchies to distributed edge-computing nodes that process sensor data locally and coordinate through standardized middleware protocols.
Autonomous mobile robots are migrating from fixed-route tape-guided systems to vision-based dynamic path planning. Third-party logistics providers operating seasonal peak operations are adopting these units through short-term leasing arrangements rather than capital purchase. The technology is migrating from high-volume e-commerce installations into mid-market food and beverage distribution centers seeking labor flexibility without permanent infrastructure commitment.
OSHA's pending updates to powered industrial truck standards are mandating pedestrian detection and automatic braking capabilities on new forklift deployments. Equipment manufacturers are redesigning mast assemblies to accommodate sensor arrays and redundant control systems. Cold storage operators in the upper Midwest are front-loading replacement cycles to secure compliant units before enforcement windows tighten.
Asset-light procurement models are displacing traditional capital expenditure approval processes for automation projects. Regional grocery chains and specialty retailers are accessing robotic systems through equipment-as-a-service contracts that bundle maintenance, software updates, and performance guarantees. This shift is most pronounced among mid-market distributors in the southeastern United States seeking to match Amazon-scale fulfillment speeds without comparable balance sheet capacity.
North America Logistics Automation Market Segmentation
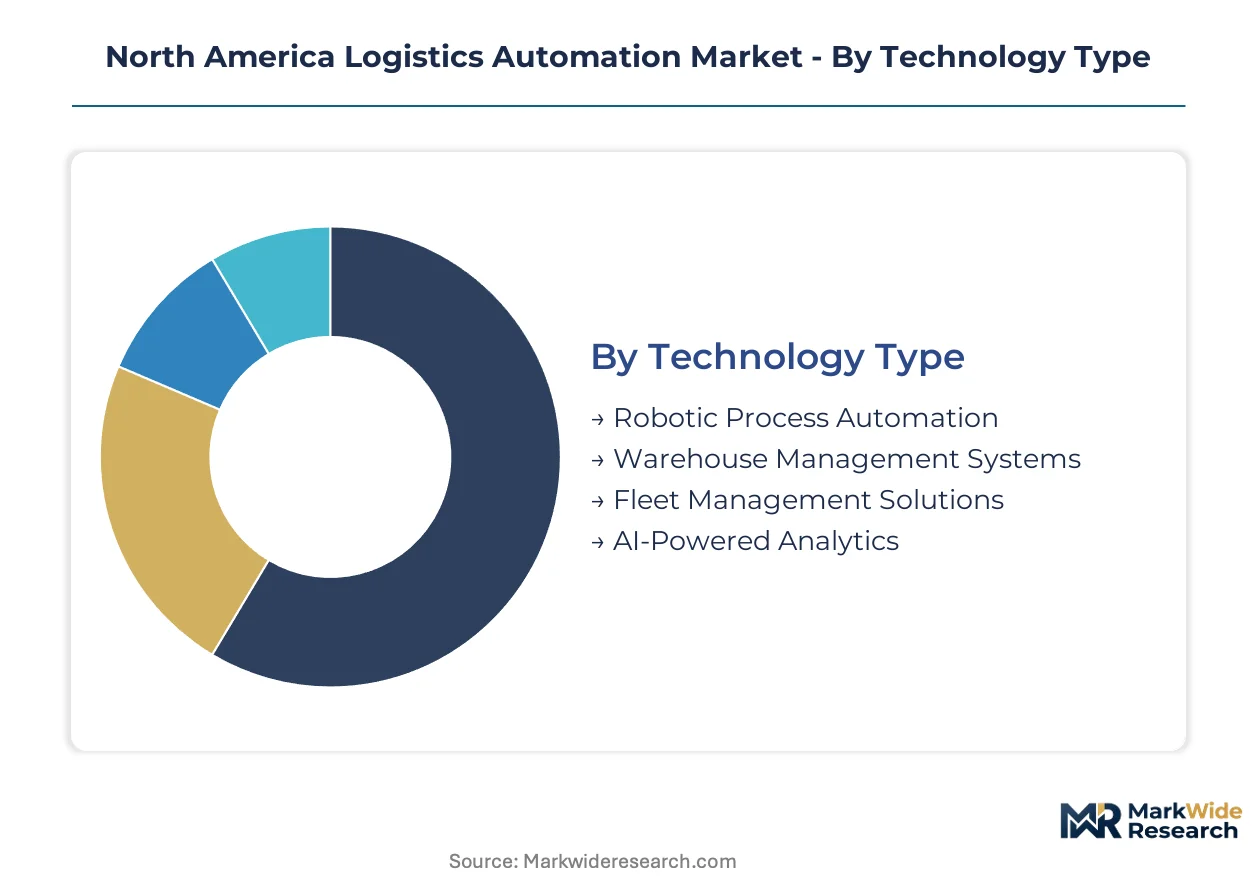
Technology selection in logistics automation follows a maturity curve where established systems defend installed bases while emerging platforms capture capital reallocation. Deployment decisions increasingly hinge on labor substitution economics and integration complexity rather than standalone feature comparisons.
Technology Type:
The maturity spectrum spans decades-old warehouse software to experimental AI inference engines still seeking production validation.
- Warehouse Management Systems:These platforms coordinate inventory tracking, order fulfillment workflows, and labor allocation across distribution networks. Cloud-native architectures are displacing legacy on-premise installations in the Great Lakes manufacturing corridor as distributors seek faster deployment timelines and reduced IT overhead.
- Robotic Process Automation:Articulated arms and autonomous mobile robots execute picking, packing, and sortation tasks in e-commerce fulfillment centers. Amazon-scale velocity requirements are forcing mid-market distributors in the southeastern United States toward short-term leasing arrangements that preserve balance sheet flexibility.
- Fleet Management Solutions:Telematics platforms integrate GPS tracking, driver behavior monitoring, and route optimization for trucking operations. The US Department of Transportation's infrastructure modernization mandates are accelerating platform upgrades among regional carriers.
- AI-Powered Analytics:Machine learning models process historical demand patterns and real-time sensor feeds to forecast inventory requirements. These systems remain nascent in revenue contribution but attract venture funding for predictive demand-forecasting applications in multi-channel retail environments.
Warehouse Management Systems retain volume leadership; AI-Powered Analytics holds the steepest expansion curve.
Application:
Cost tier segmentation separates high-velocity consumer-facing operations from capital-intensive industrial workflows with longer payback horizons.
- E-commerce:Same-day and next-day fulfillment commitments are compressing order cycle times from days to hours. Distributors across Michigan, Ohio, and Illinois are reconfiguring warehouse layouts around robotic picking density rather than traditional aisle-based storage economics.
- Manufacturing:Automated material handling systems synchronize component flow with production schedules in automotive and industrial equipment plants. The Great Lakes corridor generates sustained demand as OEMs pursue just-in-sequence delivery models.
- Retail:Store replenishment and direct-to-consumer hybrid models require flexible automation that adapts to seasonal demand swings. Regional grocery chains are accessing robotic systems through equipment-as-a-service contracts.
- Transportation:Yard management and cross-dock automation coordinate freight handoffs between long-haul and last-mile carriers. Mexican nearshoring expansion is creating greenfield demand in Monterrey and Tijuana industrial zones.
E-commerce commands the premium deployment tier; Transportation is climbing fastest on nearshoring tailwinds.
End User:
Customer type determines procurement modality, with asset-heavy manufacturers favoring ownership and variable-cost operators preferring subscription structures.
- Third-Party Logistics Providers:These operators manage fulfillment infrastructure on behalf of multiple clients with divergent seasonal patterns. Short-term leasing of autonomous mobile robots enables capacity scaling without permanent infrastructure commitment.
- Manufacturers:Captive distribution networks in automotive and industrial equipment sectors require deep integration with enterprise resource planning systems. PLC programming talent scarcity is extending system commissioning timelines across the Great Lakes corridor.
- Retailers:Multi-channel operators balancing store replenishment against direct-to-consumer fulfillment face complex automation requirements. Asset-light procurement models are displacing traditional capital expenditure approval processes.
- Freight Forwarders:These intermediaries coordinate international shipment consolidation and customs clearance with limited physical infrastructure. Telematics integration with ocean and air cargo tracking systems is becoming a competitive necessity.
Third-Party Logistics Providers drive the leasing model transition; Retailers are expanding most quickly through equipment-as-a-service adoption.
Deployment Model:
Supply concentration in cloud infrastructure is reshaping vendor economics and customer lock-in dynamics.
- Cloud-Based:Subscription pricing and automatic software updates reduce upfront capital requirements and internal IT burden. Mid-market distributors lacking comparable balance sheet capacity to Amazon are migrating fastest to these platforms.
- On-Premise:Legacy installations persist in defense and pharmaceutical verticals with stringent data sovereignty requirements. Decades of accumulated inventory records in outdated formats complicate migration timelines.
- Hybrid:Split architectures keep sensitive transaction processing local while leveraging cloud analytics for demand forecasting. This model addresses latency constraints in high-throughput sortation environments.
- Managed Services:Outsourced operations bundles bundle automation hardware, software, and labor management under performance-based contracts. Cold storage operators in the upper Midwest are front-loading replacement cycles to secure OSHA-compliant units before enforcement windows tighten.
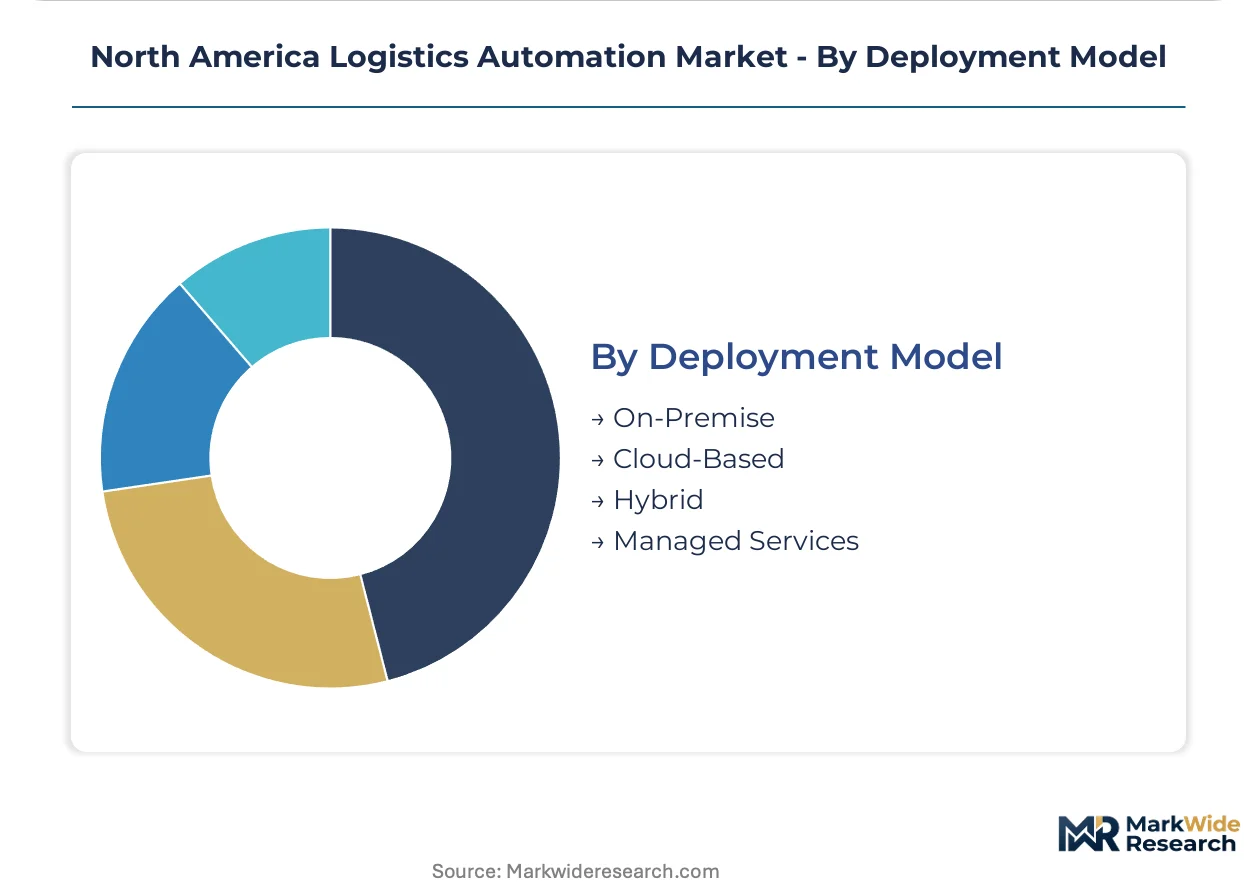
On-Premise retains the largest installed base; Cloud-Based deployment is gaining share fastest on subscription economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Transportation's infrastructure modernization mandates are accelerating fleet telematics deployment across North American corridors. E-commerce fulfillment velocity requirements are compressing order cycle times from days to hours, forcing distributors to reconfigure warehouse layouts around robotic picking density. Demand concentrates in the Great Lakes manufacturing corridor spanning Michigan, Ohio, and Illinois.
United States
E-commerce fulfillment centers are driving accelerated adoption of automated sortation and robotic picking systems across the Southeast and Midwest. FAA regulations governing beyond-visual-line-of-sight drone delivery are constraining last-mile automation pilots in suburban corridors. The Great Lakes manufacturing corridor spanning Michigan, Ohio, and Illinois generates sustained demand for automated material handling systems from automotive OEMs pursuing just-in-sequence delivery models.
Canada
Cold storage operators in Ontario and Quebec are front-loading replacement cycles to secure OSHA-compliant forklift units before enforcement windows tighten. Transport Canada harmonizes vehicle telematics standards with US DOT mandates, accelerating cross-border fleet management platform integration. The Toronto-Waterloo corridor anchors software development for warehouse management systems serving North American distribution networks.
Mexico
Manufacturing relocation from Asia is creating greenfield automation demand in Monterrey and Tijuana industrial zones. Mexican nearshoring expansion is driving yard management and cross-dock automation to coordinate freight handoffs between long-haul and last-mile carriers. The Bajío Region and Nuevo León are attracting captive conveyor and sortation subsystem manufacturing to serve US distribution networks.
North America Logistics Automation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered competitive structure. The vendor base clusters around three strategic archetypes: controls-heritage conglomerates leveraging integrated hardware-software stacks, captive manufacturing specialists producing conveyor and sortation subsystems, and cloud-native entrants compressing deployment timelines through subscription pricing. Dominant competitive moves include strategic partnerships for multi-vendor system interoperability and geographic expansion into Mexican nearshoring corridors.
Among US-based controls specialists, Honeywell Intelligrated occupies a position exemplifying high-throughput distribution installation dominance. Daifuku Co. Limited represents the captive manufacturing archetype through its North American conveyor and sortation subsystem production. Dematic Corp sits within the software-integrated fulfillment tier, anchoring compressed commissioning timeline offerings.
| Leading Market Players |
|---|
| Honeywell Intelligrated |
| Daifuku Co. Limited |
| SSI Schaefer AG |
| Swisslog Holdings AG |
| Dematic Corp |
| Beumer Group GmbH & Co. KG |
| Kardex Group |
| TGW Logistics Group GmbH |
| Mecalux SA |
| Others |
Value Network & Pricing Analysis
Steel and aluminum input volatility determines both pricing tier spreads and supply chain shape across North American logistics automation, forcing conveyor and racking manufacturers to absorb commodity swings through contract renegotiation or geographic sourcing shifts.
Pricing Analysis
Certification level creates the primary spread between OSHA-compliant collaborative robot workstations and uncertified legacy installations. Three-tier pricing structure across premium, standard, and economy levels reflects UL-listed safety systems, CE-marked European imports, and unverified domestic alternatives. Pricing pressure stems from cloud-native Warehouse Management Systems compressing subscription economics. Mid-market distributors in the southeastern United States exhibit highest price sensitivity; automotive OEMs in the Great Lakes corridor demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for structural steel components and servo motor assemblies. Manufacturing concentrates in Mexico, Germany, and Japan for precision conveyor subsystems. Raw material dependencies span cold-rolled steel, lithium-ion battery cells, and industrial-grade semiconductors. Single-source vulnerability persists in programmable logic controller chipsets. Distribution runs through regional system integrators serving the Great Lakes manufacturing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America logistics automation is entering a cyclical recovery phase as e-commerce fulfillment velocity requirements force capital redeployment from traditional storage economics toward robotic picking density.
For Market Incumbents: Harden software-integrated fulfillment architectures against cloud-native entrants compressing commissioning timelines. Deepen captive manufacturing of conveyor subsystems to offset steel input volatility. Prioritize PLC programming talent acquisition to address controls engineering scarcity extending system integration timelines across Michigan, Ohio, and Illinois. For New Entrants and Emerging Players: Establish a beachhead in mid-market food and beverage distribution centers seeking labor flexibility without permanent infrastructure commitment. Target equipment-as-a-service contracts with regional grocery chains lacking Amazon-scale balance sheet capacity. Lead with short-term autonomous mobile robot leasing arrangements that preserve customer capital deployment flexibility. For Investors and Strategic Acquirers: FAA beyond-visual-line-of-sight rulemaking reshapes the acquisition landscape for last-mile automation specialists. Position for five-to-ten year viability through software-integrated fulfillment platforms rather than hardware-only component suppliers. Monitor NHTSA autonomous trucking corridor openings as the critical inflection signal for driverless logistics infrastructure deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conveyor Subsystems | Captive manufacturing of sortation components insulates margins from steel price volatility. |
| Cloud-Native Platform Migration | Subscription pricing models displace legacy on-premise Warehouse Management System installations. |
| Mexican Nearshoring Footprint Expansion | Monterrey and Tijuana facilities capture greenfield automation demand from Asia relocation. |
| AI-Powered Predictive Maintenance Integration | Machine learning with fleet telematics enables condition-based servicing of automated guided vehicles. |
| OSHA Compliance Pre-Positioning | Front-loaded forklift replacement cycles secure pedestrian detection capabilities before enforcement tightens. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with warehouse operations directors, system integration engineers, procurement leads at third-party logistics providers, and fleet telematics managers; and secondary validation through US Department of Transportation filings, FAA regulatory dockets, OSHA enforcement databases, and SEC disclosures from publicly traded automation vendors. Bottom-up and top-down triangulation cross-checked installation counts against capital expenditure patterns.
Forecast inputs span technology type, application, end user, and deployment model across the projection horizon. Modeled dimensions include e-commerce versus manufacturing velocity requirements, asset-heavy versus subscription procurement modalities, and cloud-native versus on-premise architectural choices. CAGRs derive from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific inputs incorporate e-commerce order cycle compression metrics and fleet telematics mandate compliance timelines.
Stress conditions across steel commodity pricing, FAA regulatory approval velocity, and PLC engineering labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about infrastructure modernization continuity and nearshoring relocation momentum. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
UK Logistics Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
Japan Freight Forwarding Market
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Singapore Chemical Logistics Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
Sri Lanka Freight and Logistics Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market