
 Genetic Testing Market | 2026-2036
Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Testing Market Analysis
Next-generation sequencing platforms is rewriting how genetic diagnostics move from research benches into clinical workflows. Illumina leverages its installed base of sequencing instruments to dominate the upstream reagent supply chain. Thermo Fisher Scientific anchors its position through integrated sample-to-answer systems spanning extraction, amplification, and analysis. Hoffmann-La Roche differentiates via its embedded diagnostics franchise within centralized hospital laboratories.
Genetic testing encompasses molecular assays that analyze DNA, RNA, chromosomes, or proteins to detect heritable mutations, somatic alterations, or pharmacogenomic variants, typically requiring nucleic acid extraction, amplification, and detection with turnaround times ranging from hours for PCR-based panels to weeks for whole genome sequencing. Its primary commercial purpose is to inform clinical decision-making across prevention, diagnosis, treatment selection, and monitoring. Panel tests currently occupy the largest revenue share among product types due to their balanced coverage and reimbursement accessibility, while whole genome sequencing represents the fastest-growing segment as costs decline and clinical interpretation tools mature. Among applications, pharmacogenomics is gaining traction fastest as health systems pursue personalized prescribing protocols to reduce adverse drug reactions and trial-and-error dosing.
FDA oversight of laboratory-developed tests, CLIA certification requirements for clinical laboratories, and HIPAA privacy protections collectively shape market access, product validation timelines, and data governance obligations for test developers and service providers. The Centers for Medicare & Medicaid Services determines reimbursement codes that directly influence commercial viability of new genetic tests. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled variant interpretation tools, as algorithm-based diagnostic outputs will trigger novel premarket review pathways and reshape competitive requirements for analytical validation.
Market Dynamics
Pharmacogenomic integration into routine prescribing workflows is restructuring demand patterns across health systems, forcing laboratories to reconfigure test menus and turnaround protocols.
Growth Catalysts
- FDA Pre-Certification Pilot:Streamlined review pathways for validated algorithms accelerate clinical adoption of AI-enabled variant interpretation tools in US hospital networks.
- Oncology Precision Protocols:Tumor profiling mandates at major cancer centers drive panel test volumes through embedded diagnostic pathways.
- Polygenic Risk Scores:Cardiovascular and diabetes risk stratification tools expand addressable populations beyond rare disease testing.
Market Restraints
- Reagent Supply Concentration:Sequencing chemistry production clusters in California and Massachusetts create geographic vulnerability for clinical laboratories.
- Variant Interpretation Bottleneck:Shortage of board-certified molecular geneticists limits report generation capacity regardless of instrument throughput.
- HIPAA-GDPR Data Friction:Cross-border sample transfers face consent architecture conflicts between US privacy frameworks and European data localization requirements.
Strategic Opportunities
- Direct-to-Consumer Pharmacogenomics:Employer wellness programs in Germany and the United Kingdom subsidize preemptive genotyping for drug-gene interaction screening.
- CRISPR-Diagnostic Convergence:SHERLOCK and DETECTR platforms enable point-of-care nucleic acid detection without thermal cycling infrastructure.
- Saudi Vision 2030 Genomics:National biobank initiatives and mandatory premarital screening expansion create captive demand for carrier testing services.
Industry Challenges
- Bioinformatics Pipeline Integration:Legacy laboratory information systems require middleware development to ingest variant call format outputs from cloud-based analysis platforms.
- CLIA Proficiency Testing:Complex validation requirements for new gene-drug pairs delay test launch timelines despite analytical performance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Testing Market |
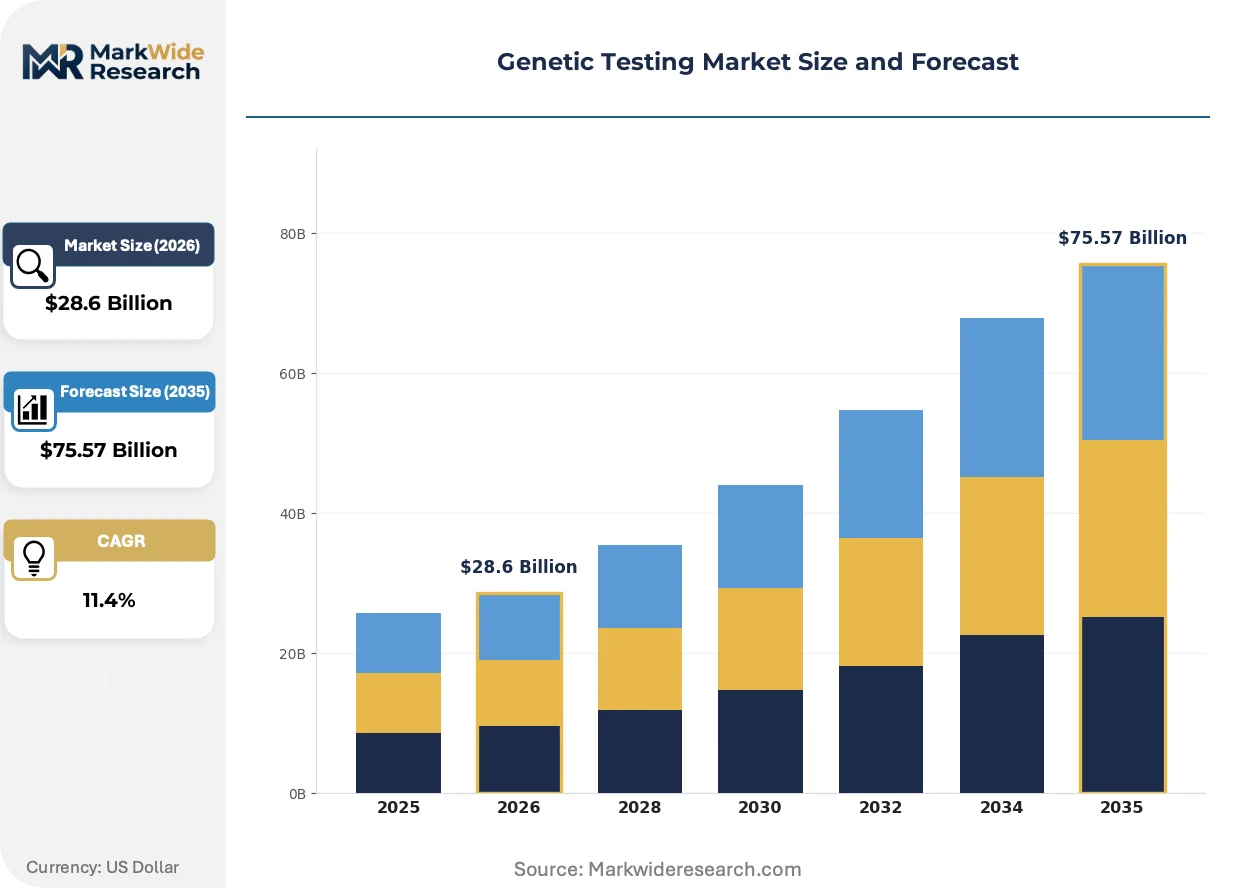
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Gene Tests, Panel Tests, Whole Exome Sequencing, Whole Genome Sequencing Application: Disease Diagnosis, Carrier Testing, Pharmacogenomics, Newborn Screening End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Testing Services Technology: Polymerase Chain Reaction, Next-Generation Sequencing, Sanger Sequencing, Microarray Analysis |
| Companies Covered | Illumina, Thermo Fisher Scientific, Hoffmann-La Roche, QIAGEN, Myriad Genetics, Abbott Laboratories, Danaher Corporation, Quest Diagnostics, Laboratory Corporation of America Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Testing Market Emerging Trajectories
Long-read sequencing platforms are compressing the gap between research-grade discovery and clinically actionable reports, enabling structural variant detection that short-read technologies miss entirely.
Nanopore sequencing is collapsing the capital barrier for whole-genome analysis in community hospital laboratories. Regional health systems in Texas and Florida deploy portable devices for same-day neonatal intensive care decisions. The technology is collapsing the traditional send-out model for urgent genetic diagnosis.
The EU AI Act's risk classification system subjects high-stakes diagnostic algorithms to conformity assessment procedures mirroring medical device regulations. Clinical decision support tools for variant pathogenicity scoring face new documentation burdens. European reference laboratories are consolidating algorithm development in-house to maintain CE marking control.
Hospital procurement departments now mandate API connectivity between genetic testing vendors and electronic health record systems as a threshold qualification. Health systems in the US Northeast favor laboratories offering bidirectional data exchange over price-competitive alternatives lacking interoperability. This technical requirement is displacing standalone genetic testing boutiques from health system contracts.
Genetic Testing Market Segmentation
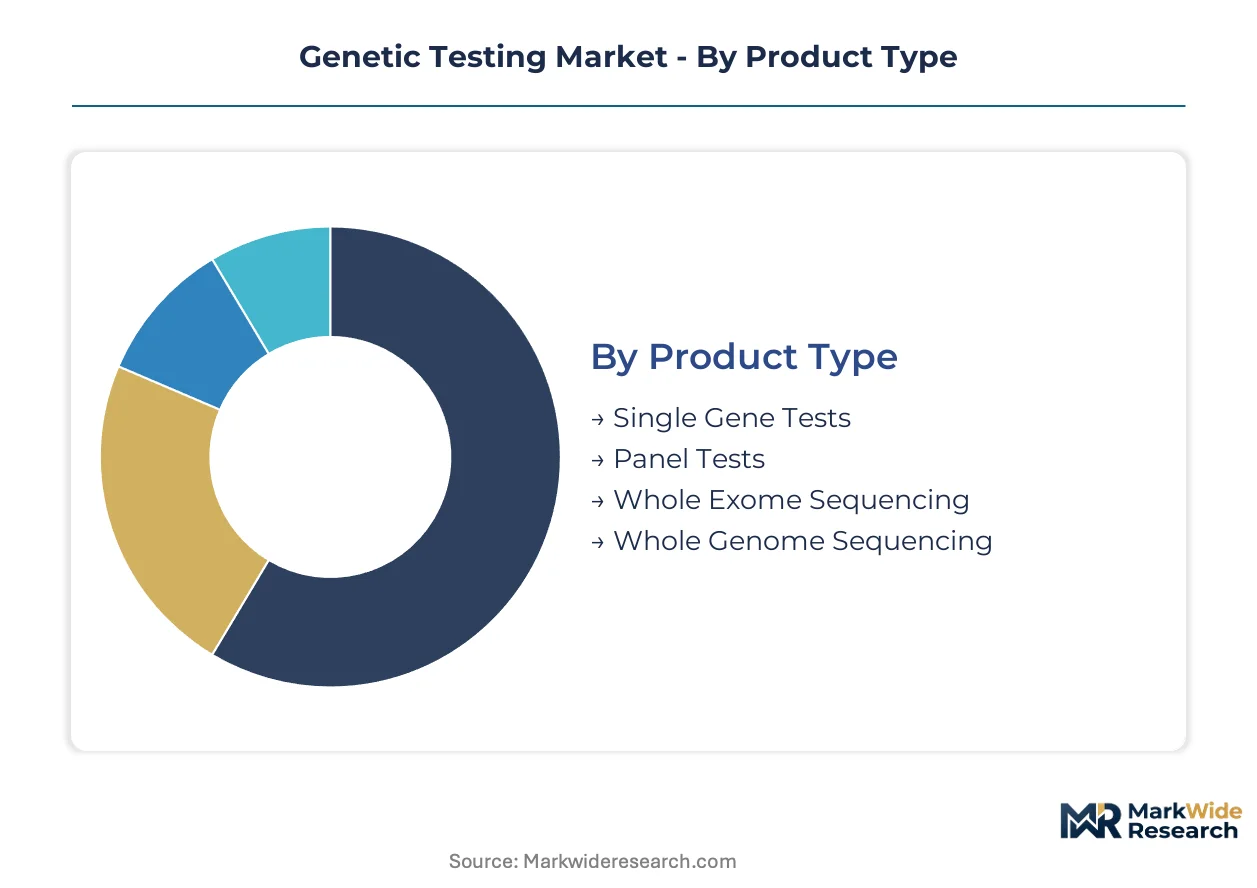
Genetic testing segments slice across technical capability, clinical setting, and reimbursement architecture. Each dimension carries distinct margin profiles, regulatory pathways, and competitive intensity that shape vendor positioning.
Product Type:
Clinical utility spans from targeted mutation confirmation to undifferentiated genomic exploration, with reimbursement codes and turnaround requirements determining commercial viability across the spectrum.
- Panel Tests:Multi-gene assays balance diagnostic yield against interpretability, typically covering 20-500 genes with curated variant lists. Oncology departments at US academic medical centers drive procurement volume through tumor-agnostic profiling protocols. Payer coverage for hereditary cancer panels anchors revenue stability despite price compression.
- Whole Genome Sequencing:Comprehensive nucleotide resolution captures coding, non-coding, and structural variants in a single workflow. Neonatal intensive care units in California and Texas health systems adopt rapid turnaround protocols for critically ill infants. Declining instrument costs and automated interpretation pipelines compress the gap between research and clinical deployment.
- Single Gene Tests:Targeted assays for Mendelian disorders with well-established clinical actionability.
- Whole Exome Sequencing:Protein-coding region focus offers intermediate coverage for undiagnosed disease programs.
Established volume favors Panel Tests; emerging adoption favors Whole Genome Sequencing.
Application:
Reimbursement pathways diverge sharply between preventive screening mandates and diagnostic confirmation workflows.
- Pharmacogenomics:Preemptive genotyping for drug-metabolizing enzyme variants guides prescribing decisions before adverse events occur. Veterans Health Administration and Kaiser Permanente embed CYP2C19 and SLCO1B1 testing into cardiovascular care pathways. FDA table of pharmacogenomic biomarkers expands eligible test claims quarterly.
- Disease Diagnosis:Symptom-driven testing confirms or rule out hereditary conditions with established treatment implications. Neurology and cardiology subspecialists at Cleveland Clinic and Mayo Clinic order panels for unexplained phenotypes. Molecular diagnostic laboratories compete on variant classification expertise and clinical report clarity.
- Carrier Testing:Preconception screening for autosomal recessive conditions in family planning contexts.
- Newborn Screening:State-mandated biochemical and genetic panels for early-onset treatable disorders.
Diagnostic confirmation commands premium pricing; preventive pharmacogenomic screening climbs the fastest.
End User:
Procurement authority concentrates in consolidated health systems and reference laboratory networks with sophisticated bioinformatics infrastructure.
- Diagnostic Laboratories:High-throughput processing centers aggregate samples from multiple health systems under single CLIA certifications. Quest Diagnostics and LabCorp operate national networks with centralized variant interpretation pipelines. Scale economies in reagent purchasing and automated sample handling defend margin structure against hospital laboratory competition.
- Hospitals:Integrated delivery networks pursue in-house testing to capture margin and reduce send-out turnaround. Johns Hopkins Medicine and Mass General Brigham build molecular pathology divisions with embedded genetic counselors. Point-of-care deployment in emergency departments drives demand for rapid PCR-based panels.
- Research Institutions:Academic medical centers with investigator-initiated protocol requirements.
- Home Testing Services:Direct-to-consumer collection kits with telemedicine-ordered interpretation.
Consolidated laboratory networks capture routine volume; hospital in-sourcing gains share in complex cases.
Technology:
Platform selection trades capital intensity, per-sample reagent cost, and analytical resolution against clinical question requirements.
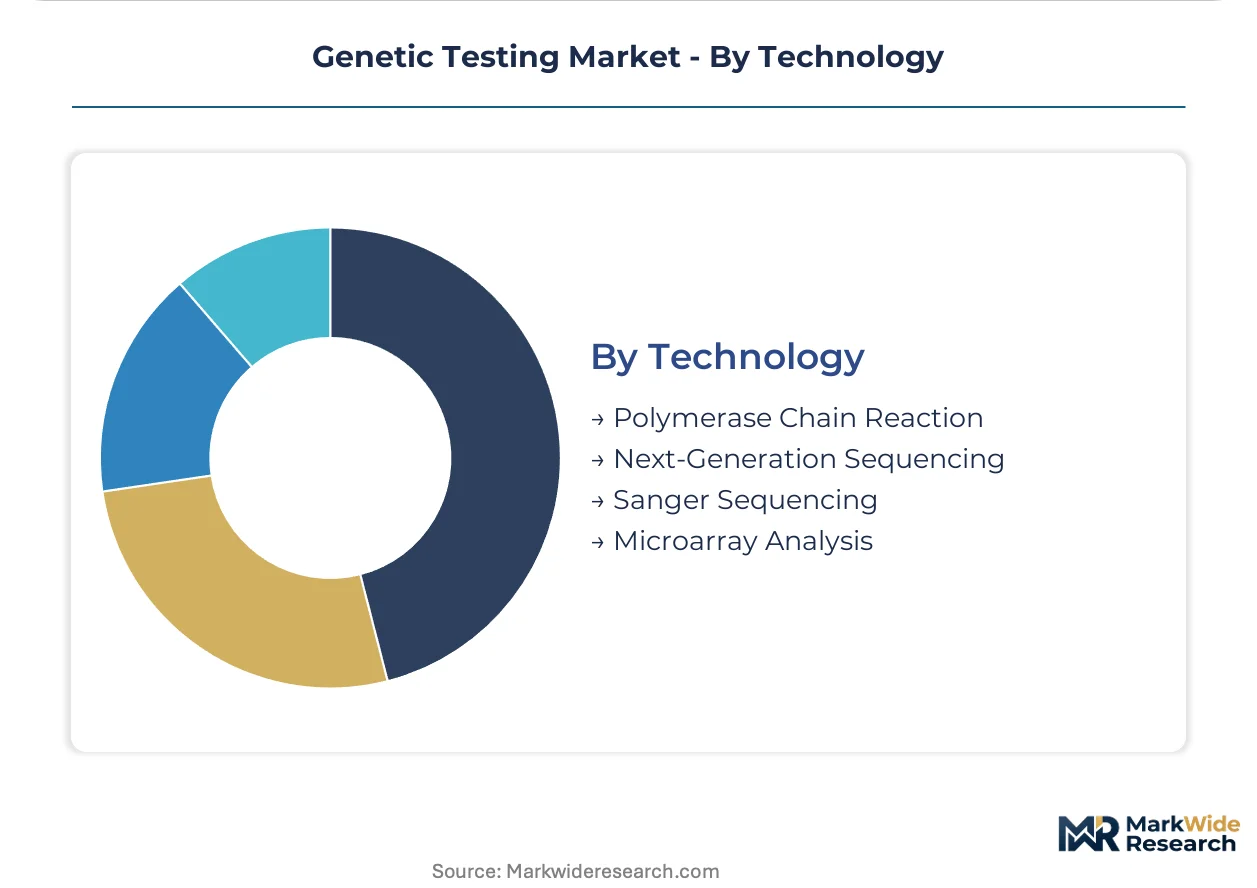
- Next-Generation Sequencing:Massively parallel read generation enables simultaneous interrogation of thousands of loci. Illumina NovaSeq instruments at Broad Institute and Baylor College of Medicine process thousands of exomes monthly. Short-read chemistry dominates clinical adoption despite structural variant blind spots.
- Polymerase Chain Reaction:Thermal cycling amplification delivers rapid, low-cost detection of known variants. Cepheid GeneXpert and Abbott ID NOW platforms deploy in pharmacy clinics and urgent care settings. FDA-cleared assays for pharmacogenomic and infectious targets anchor reimbursement accessibility.
- Sanger Sequencing:First-generation capillary electrophoresis for targeted confirmation of NGS findings.
- Microarray Analysis:Comparative genomic hybridization for copy number variation detection in developmental disorders.
PCR retains cost advantage for targeted applications; NGS platforms expand into routine diagnostic workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports sequencing reagents and diagnostic instruments to hospital networks across France, Italy, and the Netherlands, establishing a north-south trade corridor that dominates European procurement flows for molecular diagnostics.
United States
Oncology clinics at MD Anderson and Memorial Sloan Kettering drive panel test consumption through embedded tumor profiling protocols. FDA pre-certification pathways for AI-enabled variant interpretation accelerate hospital adoption of automated reporting tools. The San Francisco Bay Area and Boston-Cambridge corridor concentrate sequencing instrument manufacturing and cloud-based bioinformatics development.
Germany
Employer wellness programs in Bavaria and North Rhine-Westphalia subsidize preemptive pharmacogenomic screening for cardiovascular drug-gene interactions. The EU AI Act's conformity assessment requirements reshape algorithm validation protocols for clinical decision support tools. The Munich biotech cluster houses reference laboratories consolidating CE-marked interpretation pipelines.
China
Neonatal intensive care units in Shanghai and Guangzhou health systems adopt rapid whole-genome sequencing for critically ill infants. NMPA tightened validation requirements for laboratory-developed tests entering clinical use in 2024. The Yangtze River Delta region concentrates domestic sequencing platform manufacturing and reagent production capacity.
Saudi Arabia
Mandatory premarital screening expansion and national biobank initiatives under Vision 2030 create captive demand for carrier testing services. SFDA alignment with Gulf Cooperation Council harmonized standards streamlines multi-country test registration. The Riyadh-Eastern Province corridor anchors centralized laboratory infrastructure for population-scale genomic programs.
United Kingdom
NHS England's genomic medicine service mandates standardized tumor profiling for cancer patients across integrated care systems. GDPR consent architecture conflicts with US HIPAA frameworks complicate cross-border sample transfers for research collaborations. The Cambridge-London corridor concentrates academic medical center laboratories developing polygenic risk score applications.
Genetic Testing Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidated instrument manufacturers dominate upstream reagent supply chains through installed base lock-in effects. Fragmented service laboratories compete on turnaround time and clinical interpretation expertise. Strategic archetypes include platform-integrated conglomerates, high-throughput reference networks, and point-of-care specialists. Capacity expansion in cloud-based bioinformatics and strategic partnerships for EHR interoperability represent dominant competitive moves.
Among platform-integrated conglomerates, Illumina anchors the sequencing chemistry segment through instrument-reagent bundling. Thermo Fisher Scientific exemplifies the sample-to-answer systems archetype with integrated extraction-to-analysis workflows. Hoffmann-La Roche occupies a position within centralized hospital laboratory diagnostics through embedded analyzer placements. These three entities represent contrasting approaches to channel control: reagent pull-through, workflow integration, and installed base leverage.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| Hoffmann-La Roche |
| QIAGEN |
| Myriad Genetics |
| Abbott Laboratories |
| Danaher Corporation |
| Quest Diagnostics |
| Laboratory Corporation of America Holdings |
| Others |
Supply Flow & Price Mechanics
The San Francisco Bay Area sequencing chemistry manufacturing cluster anchors global reagent supply capacity, concentrating pricing leverage among instrument-reagent bundling leaders while downstream laboratories face margin compression from locked-in consumable dependencies.
Pricing Analysis
Short-read NGS platforms command premium pricing against Sanger confirmation workflows, while nanopore devices undercut both on capital deployment. Three-tier pricing structure across premium, standard, and economy levels separates CLIA-certified hospital laboratories from research-grade service providers and direct-to-consumer collection kits. Price differentiation rests on turnaround guarantees and clinical interpretation depth. Cost compression in panel testing is intensifying because automated variant classification tools reduce manual review hours. Reference laboratories exhibit lowest price sensitivity due to scale economies; community hospital laboratories face acute budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for sequencing instrument components and specialty reagents. Manufacturing concentrates in California, Massachusetts, and the Yangtze River Delta region. Raw material dependencies include semiconductor-grade silicon for flow cells, fluorophore-conjugated nucleotides, and synthetic oligonucleotide libraries. Single-source vulnerability persists for Illumina-patterned nanoarray substrates. Distribution runs through consolidated diagnostic laboratory networks with centralized CLIA certifications and direct-to-hospital point-of-care deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA pre-certification pathways and CLIA proficiency requirements creates formidable switching costs for locked-in health system customers.
For Market Incumbents: Entrench position through backward integration into cloud-based bioinformatics pipelines and API connectivity mandates for electronic health record interoperability. CRISPR-diagnostic point-of-care platforms threaten segment share in urgent care settings. Channel control via embedded analyzer placements at major cancer centers remains the critical defensive lever. For New Entrants and Emerging Players: Pursue white-space opportunities in employer-sponsored pharmacogenomic wellness programs across Germany and the United Kingdom where reimbursement architecture remains unsettled. Direct-to-consumer genotyping with telemedicine-ordered interpretation offers the most penetrable entry vector. Go-to-market positioning should emphasize preemptive CYP2C19 and SLCO1B1 screening protocols. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-agnostic bioinformatics specialists with automated variant interpretation capabilities. Long-term viability hinges on algorithm validation infrastructure rather than instrument hardware. Acquisition targets should demonstrate CE marking progress under EU AI Act conformity assessment timelines. Watch FDA guidance on artificial intelligence-enabled diagnostic outputs as the definitive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Proficiency Expansion | Accelerates test launch timelines for pharmacogenomic gene-drug pairs under CMS oversight. |
| API Interoperability Development | Meets hospital procurement mandates for bidirectional electronic health record data exchange. |
| Polygenic Risk Score Validation | Unlocks cardiovascular and diabetes screening reimbursement beyond rare disease testing. |
| Point-of-Care CRISPR Deployment | Enables SHERLOCK-based nucleic acid detection without thermal cycling infrastructure. |
| EU AI Act Conformity Pathway | Secures CE marking for automated variant pathogenicity scoring algorithms. |
Methodological Framework
Desk research of FDA 510(k) filings, CMS reimbursement code determinations, and CLIA certification databases preceded structured interviews with molecular pathology laboratory directors, hospital procurement officers, genetic counselors, and bioinformatics pipeline architects. Primary fieldwork with diagnostic laboratory executives and health system contracting managers cross-validated secondary data on instrument placement volumes and reagent consumption patterns. Bottom-up aggregation of test volume by application and technology platform triangulated against top-down market sizing from instrument manufacturer revenue disclosures.
Assumptions held fixed across the modeling period include FDA oversight tightening trajectory for laboratory-developed tests and continued CLIA certification requirements for clinical use. Segmentation dimensions modeled encompass product type, application, end user, and technology platform with regional regulatory cluster variations. CAGRs were computed from annualized growth rate derivation across the projection horizon. Forecast inputs incorporated NMPA validation requirement changes for China market entry and SFDA-GCC harmonization progress for Saudi Arabia.
Sensitivities concentrate around FDA artificial intelligence guidance timing, EU AI Act enforcement intensity, and reagent supply disruption scenarios. Forecasts embody documented assumptions on regulatory pathway stability and health system integration pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Lab Automation in Genomics Market
Genomics
Retail Genomics Market
Genomics
Rare Disease Genetic Testing Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Prenatal Genetic Testing Market
Genomics
United States DNA Sequencing Products Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
Global Genomics Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Global Gene Amplification Technologies Market
Genomics
Latin America Gene Expression Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Next-Generation Sequencing Data Analysis Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
Digital Genome Market
Genomics
Global Nucleic Acid Labeling Market