
 BCL-2 (B-Cell Lymphoma 2) Inhibitors Market | 2026-2036
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market Outlook
Small-molecule chemistry is decoupling from traditional cytotoxic economics as targeted BCL-2 inhibition commands premium positioning. AbbVie Inc. leverages its venetoclax franchise to anchor hematologic oncology portfolios across major markets. Roche competes through diagnostic-companion integration that sustains biomarker-driven patient selection. BeiGene Ltd. specializes in bridging Western regulatory standards with Asia-Pacific manufacturing scale.
BCL-2 (B-Cell Lymphoma 2) inhibitors constitute a class of targeted oncology therapeutics that bind the BCL-2 protein to restore apoptotic signaling in malignant cells, with venetoclax representing the benchmark small-molecule achieving nanomolar affinity through BH3-mimetic mechanism. These agents serve the primary commercial purpose of treating hematologic malignancies where BCL-2 overexpression drives therapeutic resistance. Small molecule inhibitors occupy the dominant value share given venetoclax's established reimbursement and line-extension strategy into combination regimens. Monoclonal antibodies represent the fastest-growing product category as developers pursue orthogonal mechanisms to address resistance mutations. Hematologic malignancies concentrate the deepest margin pools, though multiple myeloma applications are expanding through clinical trial pipelines.
FDA breakthrough therapy designation and EMA conditional marketing authorization collectively compress development timelines while elevating evidence requirements for BCL-2 inhibitors entering competitive hematology markets. The EU's MDR framework tightens clinical evidence standards for companion diagnostics that co-determine patient eligibility. Stakeholders must monitor evolving CMS coverage determination processes for combination therapy billing codes as these will dictate real-world utilization velocity independent of label expansion.
Market Dynamics
FDA breakthrough therapy designations and EMA conditional marketing authorizations compress BCL-2 inhibitor development timelines while simultaneously elevating evidence requirements for hematologic oncology approvals.
Growth Catalysts
- Accelerated Approval Pathways:FDA's breakthrough therapy designation reduces clinical trial duration for BCL-2 inhibitors targeting relapsed acute myeloid leukemia. This regulatory mechanism enables earlier patient access to novel BH3-mimetics.
- Combination Therapy Expansion:Oncology clinics integrate BCL-2 inhibitors with hypomethylating agents and monoclonal antibodies across frontline and salvage settings. These protocols address therapeutic resistance in chronic lymphocytic leukemia.
- Companion Diagnostic Integration:Biomarker-driven patient selection via BCL-2 expression profiling concentrates treatment in responsive populations. Diagnostic-companion bundling improves payer reimbursement velocity.
Market Restraints
- API Manufacturing Concentration:Active pharmaceutical ingredient synthesis for venetoclax analogs concentrates among contract manufacturers in India and China. Single-source dependencies create supply vulnerability during regulatory inspections.
- Resistance Mutation Emergence:BCL-2 G101V and D103Y mutations reduce binding affinity for first-generation BH3-mimetics. These genetic alterations necessitate next-generation compound development with altered pharmacophores.
- Reimbursement Compression:Medicare coverage determination processes for combination therapy billing codes create utilization friction. CMS National Coverage Determination reviews delay real-world adoption independent of FDA label expansion.
Strategic Opportunities
- Solid Tumor Penetration:BCL-2 inhibitor trials in small cell lung cancer and estrogen receptor-positive breast cancer represent untapped oncology segments. These indications expand addressable populations beyond hematologic malignancies.
- Asia-Pacific Regulatory Harmonization:China's NMPA priority review pathways and Japan's PMDA sakigake designation accelerate market entry. These frameworks reward developers with Asia-Pacific manufacturing scale.
- Next-Generation MCL-1 Targeting:Dual BCL-2/MCL-1 inhibition addresses resistance mechanisms orthogonal to single-agent approaches. These compounds target myeloma and acute myeloid leukemia with BCL-2 family co-dependency.
Industry Challenges
- Clinical Trial Patient Recruitment:Competing studies for relapsed/refractory hematologic malignancies fragment eligible patient pools. Academic medical centers face enrollment bottlenecks across simultaneous BCL-2 inhibitor protocols.
- Pharmacovigilance Infrastructure:Tumor lysis syndrome monitoring requirements for venetoclax ramp-up dosing necessitate specialized nursing protocols. Community oncology practices lack capacity for inpatient observation mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BCL-2 (B-Cell Lymphoma 2) Inhibitors Market |
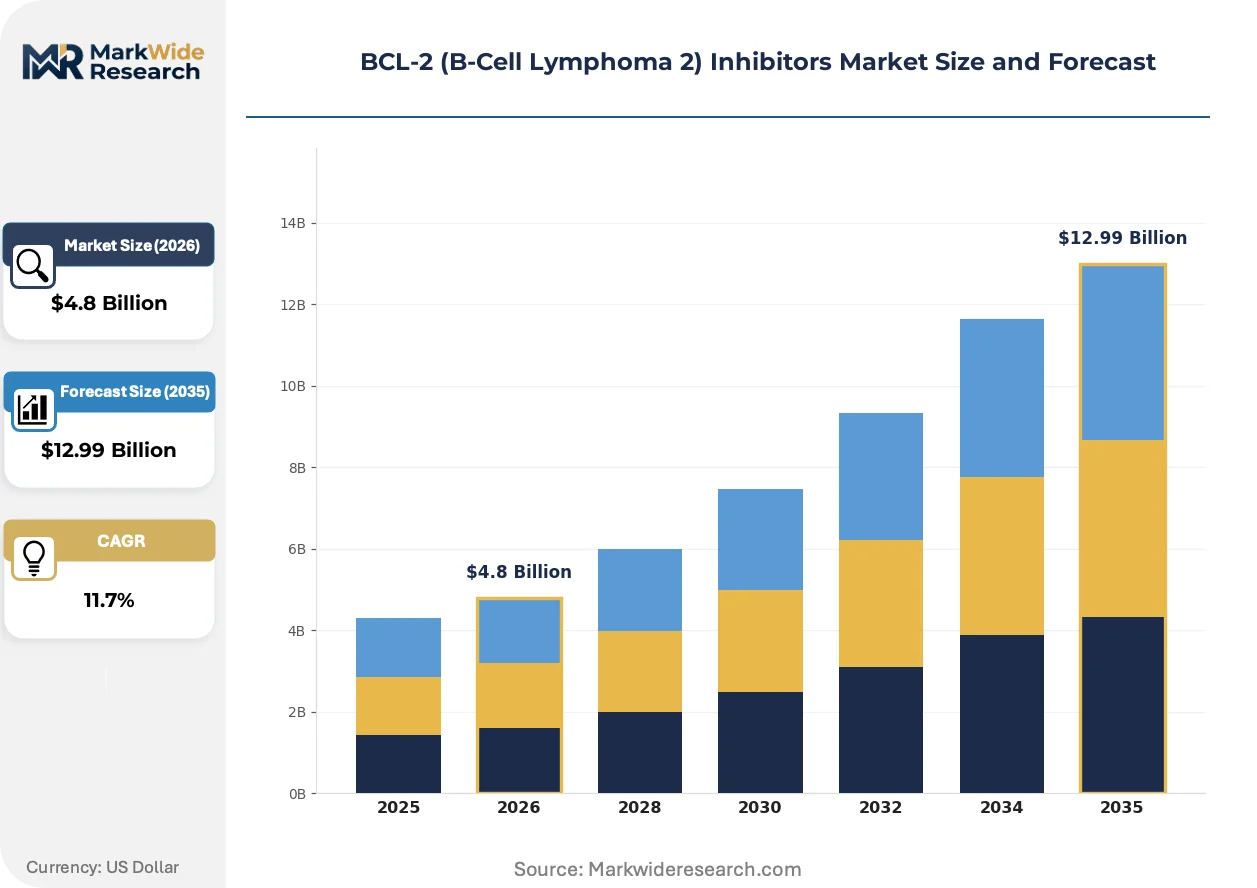
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecule Inhibitors, Monoclonal Antibodies, Combination Therapies, Biosimilars Therapy Area: Hematologic Malignancies, Multiple Myeloma, Chronic Lymphocytic Leukemia, Non-Hodgkin Lymphoma End User: Hospitals, Oncology Clinics, Research Institutes, Specialty Pharmacies Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular |
| Companies Covered | AbbVie Inc., F. Hoffmann-La Roche Ltd., Novartis AG, AstraZeneca Plc, Amgen Inc., BeiGene Ltd., Bristol Myers Squibb Co., Merck & Co., Inc., Ascentage Pharma Group International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market Strategic Shifts
Computational chemistry platforms and real-world evidence generation are restructuring how BCL-2 inhibitors advance from discovery through commercialization.
Artificial intelligence-driven molecular dynamics simulations are automating lead optimization for novel BH3-mimetics with improved selectivity profiles. Large pharmaceutical developers deploy these platforms to predict off-target binding before synthesis. This computational approach compresses preclinical timelines while reducing attrition in resistance-prone solid tumor indications.
EMA's Medical Device Regulation framework tightens clinical evidence standards for companion diagnostics that co-determine BCL-2 inhibitor eligibility. In vitro diagnostic manufacturers must generate prospective validation data linking biomarker status to treatment response. Hematology-oncology practices in Germany and France face delayed test availability as laboratories navigate notified body conformity assessments.
Academic medical centers increasingly consolidate procurement decisions through integrated pharmacy and therapeutics committees. These centralized review bodies evaluate BCL-2 inhibitors alongside competing targeted therapies using total cost-of-care models rather than drug acquisition cost alone. The United States exhibits the most pronounced concentration, with NCCN-member institutions standardizing protocols across multi-hospital systems.
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market Segmentation
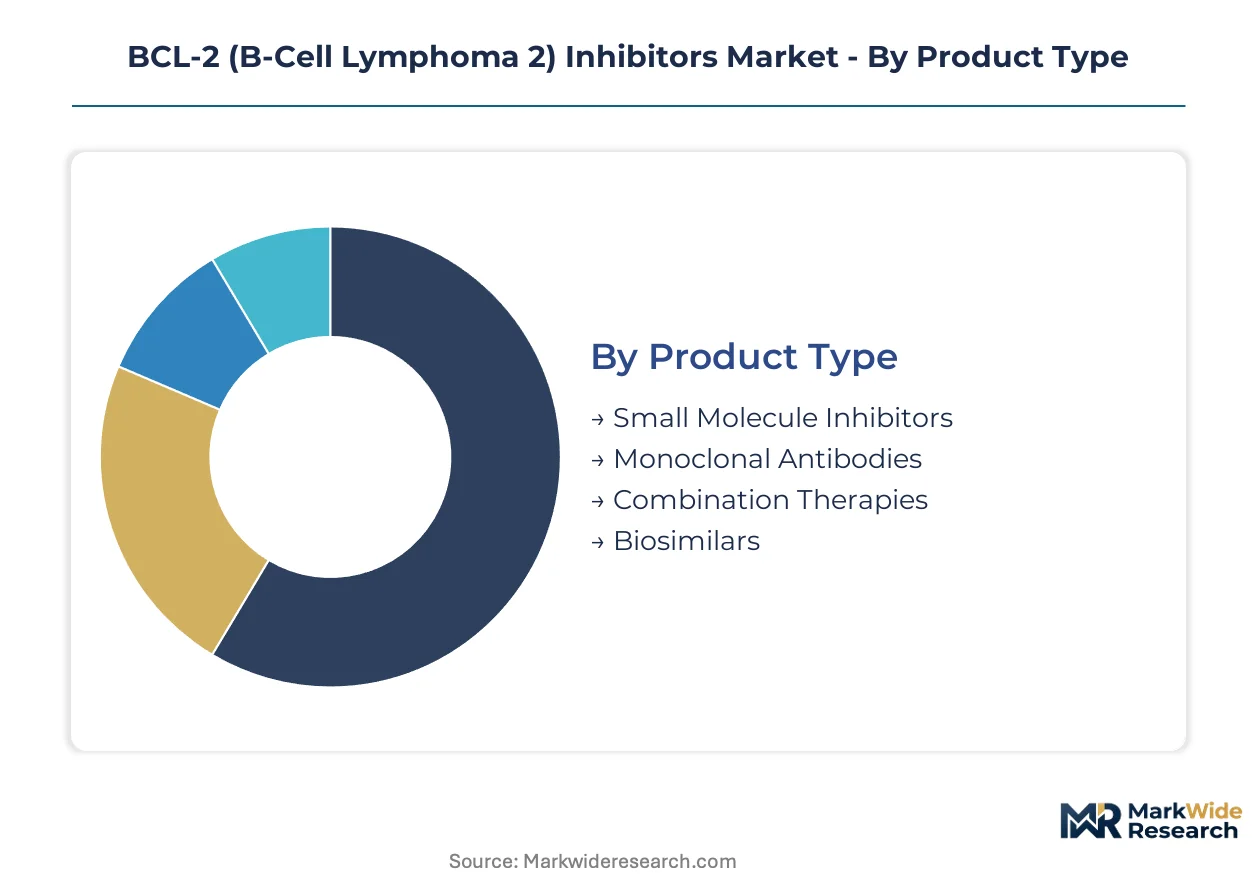
BCL-2 inhibitor commercialization strategies diverge sharply across product architectures and care settings. Therapy area concentration and delivery mode accessibility dictate pricing power and reimbursement velocity in distinct patient populations.
Product Type:
Upgrade cycles in oncology therapeutics favor mechanism-differentiated portfolios over single-agent dominance.
- Small Molecule Inhibitors:BH3-mimetic compounds achieve nanomolar binding affinity through allosteric pocket occupation. Academic medical centers in the United States prioritize these agents for frontline chronic lymphocytic leukemia protocols given established venetoclax reimbursement pathways.
- Monoclonal Antibodies:These biologics engage extracellular BCL-2 epitopes through Fc-enhanced effector functions. Development pipelines concentrate in Boston and San Francisco biotech clusters pursuing orthogonal resistance mechanisms.
- Combination Therapies:Fixed-dose regimens pairing BCL-2 inhibitors with hypomethylating agents or anti-CD20 antibodies.
- Biosimilars:Follow-on biologics referencing innovator monoclonal antibody structures.
Small Molecule Inhibitors sits at the top of the volume ranking, with Monoclonal Antibodies climbing the fastest.
Therapy Area:
Margin pools concentrate where diagnostic-companion integration enables precise patient stratification.
- Hematologic Malignancies:Acute myeloid leukemia and myelodysplastic syndromes constitute the anchor indications with deepest therapeutic penetration. Medicare coverage determinations in the United States prioritize these populations for accelerated access pathways.
- Chronic Lymphocytic Leukemia:BCL-2 overexpression drives 17p deletion and TP53-mutant disease segments where chemotherapy intolerance demands targeted alternatives. European reference pricing in Germany and France shapes commercial strategy for this indication.
- Multiple Myeloma:BCL-2 family co-dependency with MCL-1 creates combination therapy opportunities in relapsed/refractory settings.
- Non-Hodgkin Lymphoma:Diffuse large B-cell lymphoma subpopulations with high BCL-2 expression by immunohistochemistry.
Hematologic Malignancies commands the largest revenue share, while Multiple Myeloma shows the steepest expansion trajectory.
End User:
Site-of-care economics fragment procurement authority across integrated delivery networks and independent specialists.
- Hospitals:Inpatient administration of BCL-2 inhibitors requiring tumor lysis syndrome monitoring and ramp-up dosing protocols. NCCN-member institutions in the United States consolidate formulary decisions through pharmacy and therapeutics committees.
- Oncology Clinics:Outpatient infusion centers managing oral venetoclax regimens with laboratory surveillance. These settings capture margin through buy-and-bill reimbursement for physician-administered drugs.
- Research Institutes:Early-phase clinical trial sites conducting biomarker-driven patient selection studies.
- Specialty Pharmacies:Mail-order and hub services coordinating prior authorization and patient assistance programs.
Hospitals retain the dominant patient volume, with Oncology Clinics gaining share fastest.
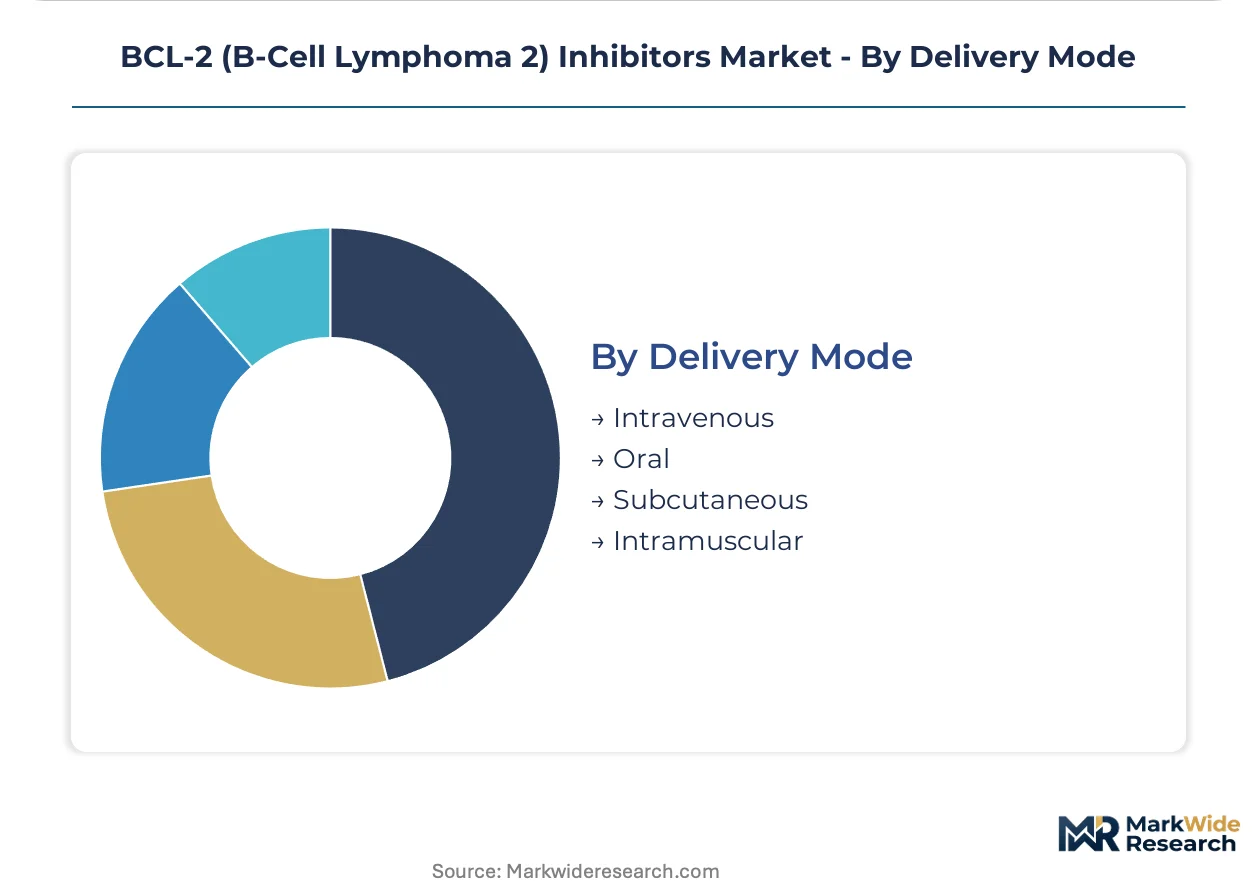
Delivery Mode:
Patient convenience and nursing intensity requirements drive divergence between institutional and home-based administration.
- Oral:Once-daily venetoclax tablets enable outpatient chronic lymphocytic leukemia management without infusion capacity constraints. United States specialty pharmacy networks prioritize oral regimens for their lower total cost-of-care profiles.
- Intravenous:Infusion-dependent monoclonal antibodies requiring healthcare facility administration and cold-chain logistics.
- Subcutaneous:Emerging formulations reducing administration time and healthcare professional exposure.
- Intramuscular:Depot formulations in early development for prolonged pharmacokinetic coverage.
Oral administration leads by prescription volume, with Subcutaneous delivery expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States anchor BCL-2 inhibitor commercialization through Medicare reimbursement pathways and concentrated hematology-oncology networks. FDA breakthrough therapy designations compress development timelines for venetoclax combinations in acute myeloid leukemia. The analysis spans five countries where regulatory frameworks and clinical infrastructure shape market access velocity.
United States
NCCN-member institutions consolidate formulary decisions through pharmacy and therapeutics committees using total cost-of-care models. CMS National Coverage Determination processes for combination therapy billing codes create utilization friction independent of FDA label expansion. The Greater Boston and San Francisco biotech clusters concentrate early-phase clinical trial sites for biomarker-driven patient selection studies.
Germany
Reference pricing mechanisms for chronic lymphocytic leukemia therapies shape commercial strategy across the statutory health insurance system. EMA conditional marketing authorization elevates evidence requirements for hematologic oncology approvals entering the EU market. Heidelberg and Munich academic medical centers coordinate multicenter protocols for BCL-2 inhibitor resistance mutation monitoring.
China
NMPA priority review pathways accelerate market entry for developers with Asia-Pacific manufacturing scale. Domestic contract manufacturers concentrate active pharmaceutical ingredient synthesis for venetoclax analogs. Shanghai and Suzhou biotech clusters host BeiGene Ltd. and Ascentage Pharma Group International facilities bridging Western regulatory standards with regional production capacity.
Japan
PMDA sakigake designation rewards developers with expedited review timelines for novel hematology treatments. Tumor lysis syndrome monitoring requirements for venetoclax ramp-up dosing necessitate specialized nursing protocols in inpatient settings. Tokyo and Osaka academic medical centers lead enrollment in combination therapy trials for relapsed/refractory acute myeloid leukemia.
Switzerland
Swissmedic marketing authorization processes align with EMA standards while maintaining independent assessment of companion diagnostic integration. Roche's diagnostic-companion bundling sustains biomarker-driven patient selection for BCL-2 expression profiling. Basel anchors the European headquarters for hematology-oncology commercial operations and pharmacovigilance infrastructure.
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market Competitive Environment
Portfolio diversification dominates the current landscape as developers extend venetoclax franchises into combination regimens and orthogonal resistance mechanisms. The market structure concentrates around large-cap pharmaceutical incumbents with established hematology-oncology infrastructure and emerging biotech specialists pursuing next-generation BH3-mimetics. Two strategic archetypes prevail: diagnostic-integrated platform builders and Asia-Pacific manufacturing-scale bridgers. Competitive moves center on companion diagnostic partnerships and Asia-Pacific regulatory harmonization.
Within the diagnostic-integrated tier, F. Hoffmann-La Roche Ltd. exemplifies biomarker-driven patient selection through companion bundling, while AbbVie Inc. anchors small-molecule dominance via established venetoclax reimbursement pathways. BeiGene Ltd. occupies a position bridging Western regulatory standards with Asia-Pacific production scale, representing the manufacturing-efficiency archetype.
| Leading Market Players |
|---|
| AbbVie Inc. |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| AstraZeneca Plc |
| Amgen Inc. |
| BeiGene Ltd. |
| Bristol Myers Squibb Co. |
| Merck & Co., Inc. |
| Ascentage Pharma Group International |
| Others |
Value Chain & Pricing Dynamics
Large-cap pharmaceutical incumbents with vertically integrated manufacturing footprints anchor pricing discipline through captive API production and formulary control at NCCN-member institutions. Their ownership structures enable sustained premium positioning for venetoclax combinations despite reimbursement compression from Medicare coverage determination processes.
Pricing Analysis
Input-cost pass-through from concentrated API synthesis in India and China feeds into list-price maintenance for oral BH3-mimetics despite payer pressure. Value-based pricing with outcomes guarantees dominates chronic lymphocytic leukemia, while per-unit transactional models persist in acute myeloid leukemia salvage settings. Price differentiation hinges on companion diagnostic bundling and line-of-therapy positioning, with frontline regimens commanding lowest sensitivity and relapsed/refractory segments facing steepest compression from biosimilar anticipation.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive monoclonal antibodies remain underdeveloped, creating write-off exposure for infusion-center inventory. Active pharmaceutical ingredient synthesis concentrates in India, China, and Switzerland, with key starting materials drawing from specialized chemical manufacturers in Germany and Japan. Single-source dependencies for venetoclax intermediates create vulnerability during FDA inspections of contract manufacturers. Distribution runs through specialty pharmacy networks for oral formulations and direct-to-hospital channels for intravenous biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
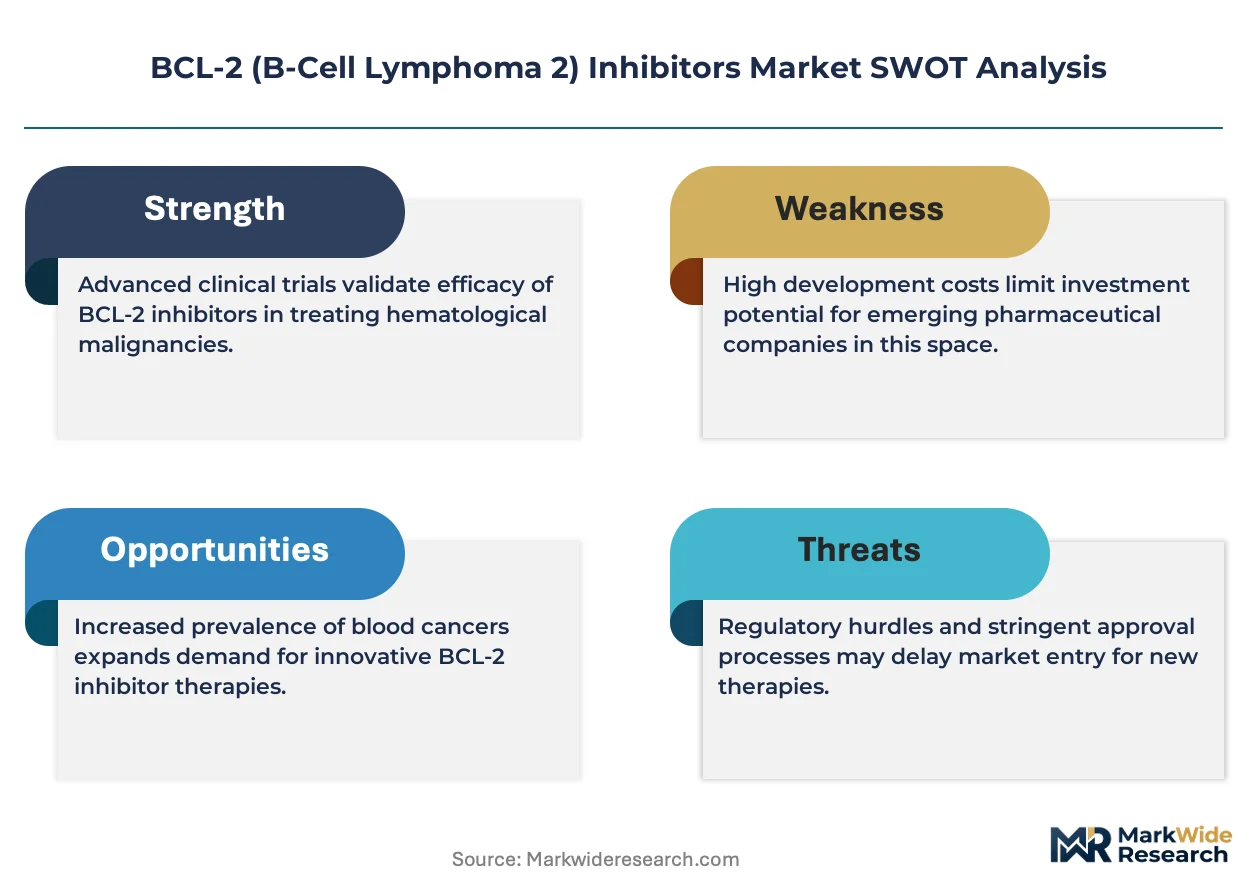
This market reads as a late-cycle quality story where demand is concentrating in biomarker-selected patient populations requiring diagnostic-companion integration. The shift toward precision hematology elevates specifications for BCL-2 expression profiling and resistance mutation monitoring.
For Market Incumbents: Deploy diagnostic-companion bundling as the anchor lever to defend formulary positioning against emerging BH3-mimetics with improved resistance profiles. Deepen backward integration into API synthesis to offset single-source vulnerabilities from Indian and Chinese contract manufacturers. Prioritize investment in next-generation MCL-1 targeting combinations to address G101V and D103Y mutation escape. For New Entrants and Emerging Players: Digital-channel partnerships with tele-oncology platforms offer the lowest-friction route to patient access outside NCCN-member institution gatekeeping. White-space opportunities concentrate in community oncology practices lacking tumor lysis syndrome monitoring infrastructure for venetoclax ramp-up protocols. Target Asia-Pacific regulatory harmonization through NMPA priority review pathways as the most penetrable geography for manufacturing-scale bridgers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap biotechs with clinical-stage dual BCL-2/MCL-1 inhibitors and established Asia-Pacific manufacturing partnerships. Long-term viability hinges on successful solid tumor indication expansion beyond hematologic malignancies. Monitor FDA breakthrough therapy designation velocity for acute myeloid leukemia combinations as the inflection signal for portfolio rebalancing toward mechanism-differentiated assets.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Roche's diagnostic bundling with venetoclax sustains biomarker-driven patient selection and accelerates payer reimbursement. |
| Regulatory Harmonization | BeiGene's bridging of FDA standards with NMPA pathways enables faster market entry for Asia-Pacific manufacturing scale. |
| Resistance Mechanism Diversification | Next-generation MCL-1 targeting addresses orthogonal escape mutations that reduce binding affinity for first-generation BH3-mimetics. |
| Community Oncology Infrastructure | Specialized nursing protocols for tumor lysis syndrome monitoring expand addressable sites beyond academic medical centers. |
| Real-World Evidence Generation | Post-marketing studies linking BCL-2 expression to treatment response support label expansion and CMS coverage determinations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down market sizing triangulated across manufacturer reported sales and channel inventory data.
Comparable-period anchoring established baseline penetration rates for venetoclax across treatment lines before projecting expansion into combination regimens and solid tumor indications. The analytical framework segmented by product architecture, therapy area, end-user site of care, and regional regulatory cluster, with CAGRs derived from patient population epidemiology and pricing trajectory assumptions. Forecast inputs incorporated biomarker testing adoption curves and resistance mutation surveillance patterns from academic medical center networks.
The model assumes a particular technology adoption path for companion diagnostic integration; alternative pathways for liquid biopsy-based BCL-2 expression profiling would alter the outlook for patient selection velocity. Forecasts reflect assumptions regarding FDA breakthrough therapy designation persistence and EMA conditional marketing authorization standards. Practitioners should monitor CMS National Coverage Determination timelines and API manufacturing inspection outcomes for early signals of utilization friction or supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Galculus Bovis and Metronidazole Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Middle-East and Africa Diabetes Drugs Market
Pharmaceuticals
Norway Pharmaceutical Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Soft Capsules Drugs Market