
 Global Dermal Filler Market | 2026-2036
Global Dermal Filler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dermal Filler Market Analysis
The gap between premium biostimulatory fillers and commodity hyaluronic acid syringes is realigning procurement patterns across aesthetic practices. Galderma leverages its integrated manufacturing network to sustain supply consistency for high-viscosity formulations. Merz Pharma anchors its position through specialized R&D in calcium hydroxylapatite microsphere technology. AbbVie Inc. competes by extending its channel control across dermatology clinics and plastic surgery centers in North America and Europe.
Dermal fillers are injectable gel or suspension formulations, typically composed of cross-linked hyaluronic acid, calcium hydroxylapatite microspheres, or poly-L-lactic acid particles suspended in biocompatible carriers, designed to restore facial volume, correct contour defects, or stimulate neocollagenesis through subdermal or deep dermal implantation. Hyaluronic acid products dominate current volume due to established reversibility with hyaluronidase and broad practitioner familiarity, while poly-L-lactic acid segments capture expanding margin pools as biostimulatory protocols lengthen treatment intervals and raise per-patient lifetime value. Application demand skews toward wrinkle reduction and volume restoration where patient education is lowest and repeat purchase rates are highest.
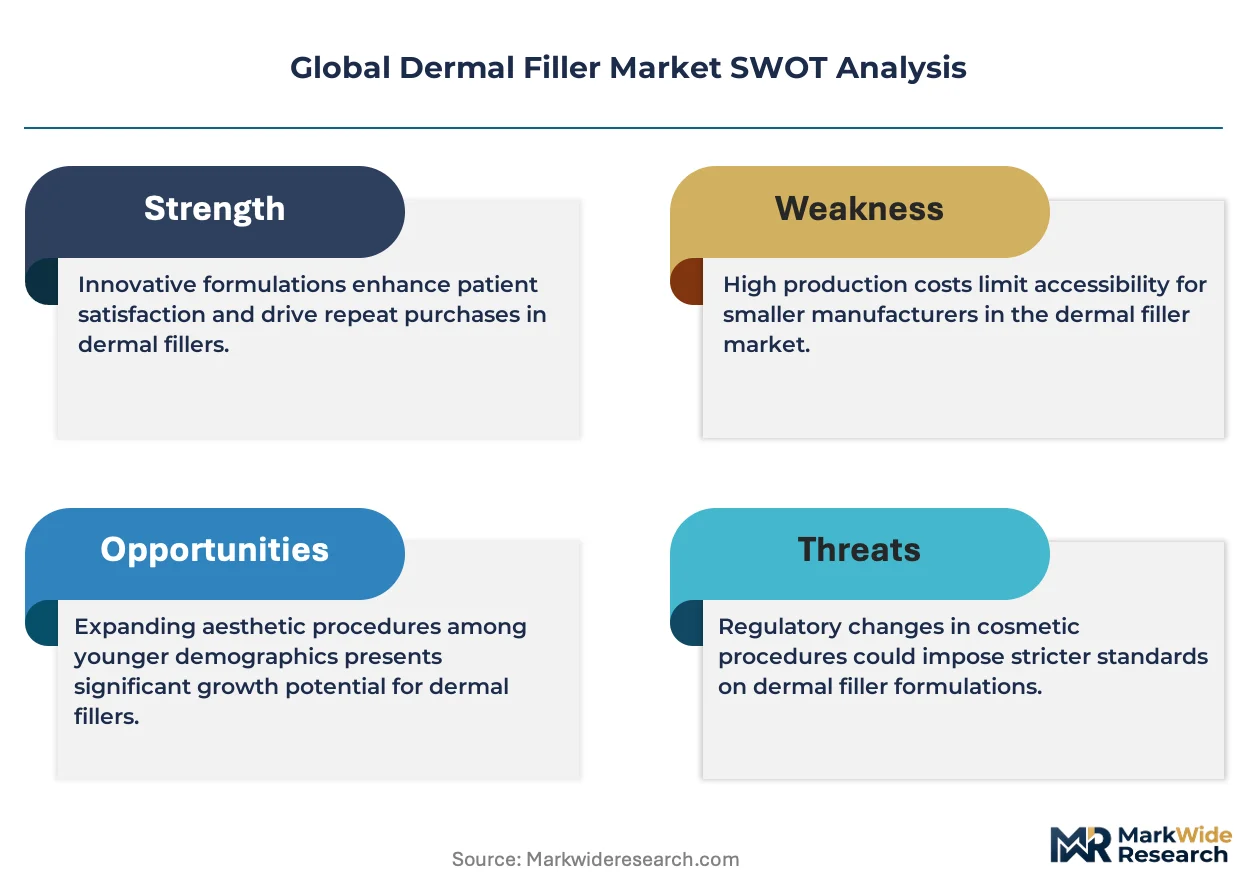
FDA clearance requirements and EMA MDR compliance obligations shape formulation development timelines and clinical trial investment thresholds for all manufacturers seeking market access. ISO 13485 quality management standards and country-specific medical device registration protocols in Brazil through ANVISA and in South Korea through MFDS further fragment go-to-market complexity. Stakeholders must monitor evolving biostimulatory filler classification debates and reimbursement policy shifts for functional indications across major national regulators.
Market Dynamics
Biostimulatory filler protocols are compressing treatment intervals and elevating per-patient lifetime value, forcing manufacturers to reconfigure R&D roadmaps around neocollagenesis mechanisms rather than immediate volumetric correction.
Growth Catalysts
- MFDS accelerated review pathways:South Korea's streamlined medical device registration for novel biostimulatory formulations reduces time-to-market for hyaluronic acid innovators targeting the Seoul aesthetic cluster.
- Physician training density:Brazil's concentration of board-certified dermatologists and plastic surgeons in São Paulo and Rio de Janeiro sustains premium pricing power for calcium hydroxylapatite protocols.
- Reversibility infrastructure:Widespread hyaluronidase availability in United States medical aesthetic practices lowers patient risk perception and expands first-time filler adoption.
Market Restraints
- Fermentation-derived hyaluronic acid supply:Concentration of pharmaceutical-grade raw material production in Chinese bioreactor facilities creates input cost volatility and geographic supply risk.
- EMA MDR clinical evidence thresholds:Expanded requirements for biostimulatory filler PMA-equivalent submissions extend development timelines and inflate trial investment for European market access.
- Non-surgical facial rejuvenation alternatives:Energy-based devices and thread lift procedures capture budget-conscious segments seeking lower-commitment aesthetic interventions.
Strategic Opportunities
- Middle East medical tourism corridors:Dubai's positioning as a regional aesthetic hub attracts patients from Saudi Arabia, Kuwait, and Egypt seeking combination filler-laser protocols unavailable domestically.
- Functional indication expansion:HIV-associated lipoatrophy and post-oncology facial reconstruction represent reimbursable pathways beyond cosmetic applications in select European markets.
- Direct-to-clinic digital procurement:Specialized B2B platforms bypass traditional distributor markups for high-volume United States dermatology groups and surgery centers.
Industry Challenges
- Injection technique specialization:Cannula-based volumization and layered plane-specific placement require advanced training that outpaces current fellowship program capacity.
- Adverse event documentation:Vascular occlusion recognition and hyaluronidase emergency protocols demand standardized competency certification that varies across state medical boards.
- Cross-linked gel characterization:Rheological property standardization for G-prime and cohesivity metrics remains inconsistent between manufacturer specifications and independent testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dermal Filler Market |
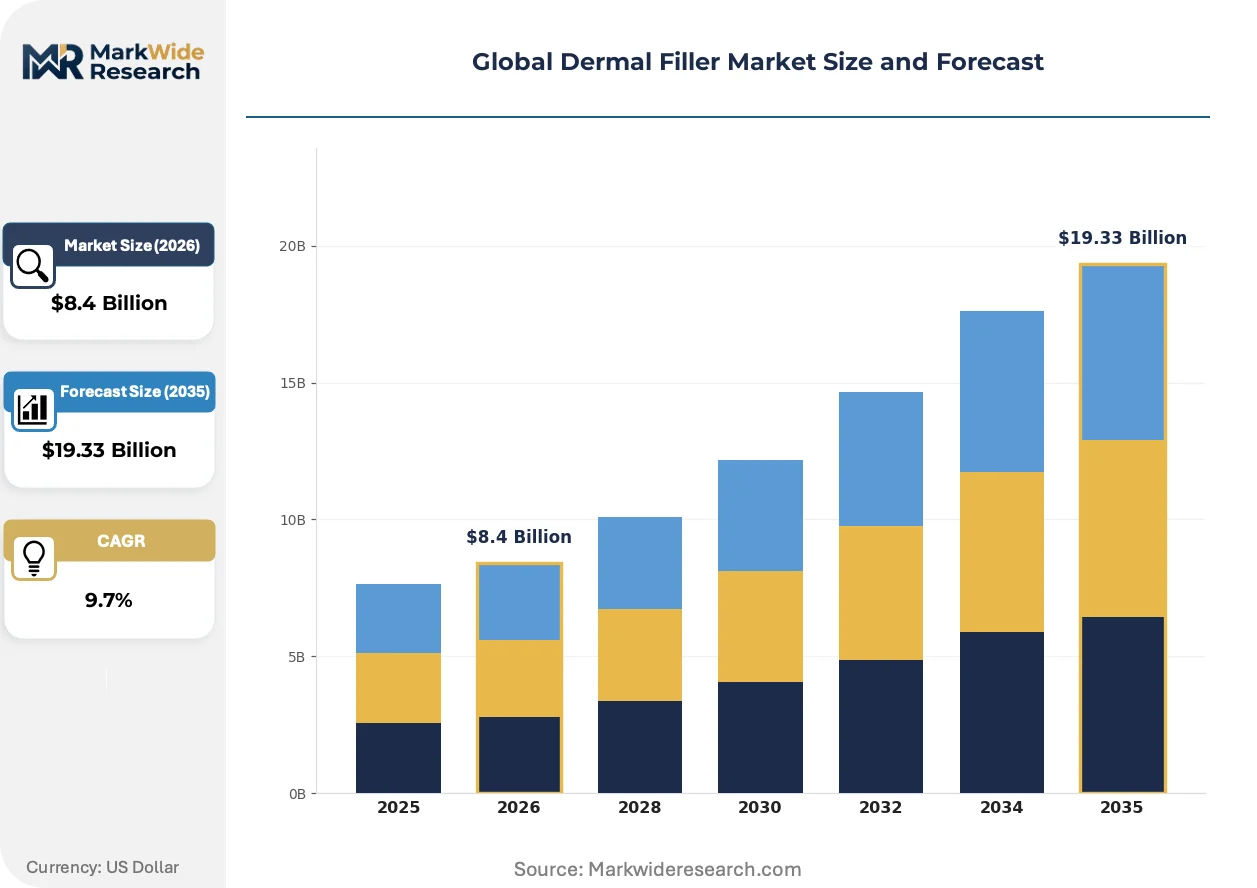
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-Lactic Acid, Collagen Application: Facial Contouring, Wrinkle Reduction, Lip Enhancement, Volume Restoration End User: Dermatology Clinics, Plastic Surgery Centers, Beauty Salons, Hospitals Distribution Channel: Direct Sales, Online Platforms, Distributors, Medical Supply Stores |
| Companies Covered | AbbVie Inc., Galderma, Merz Pharma, Sinclair Pharma, Revance Therapeutics, Inc., Teoxane Laboratories, Zimmer Aesthetics, Croma Pharma, Prollenium Medical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dermal Filler Market Emerging Trajectories
Cross-linked polymer engineering and real-time imaging guidance are converging to redefine precision delivery, while regulatory classification debates around biostimulatory mechanisms create uncertainty for formulation developers.
Hybrid cohesive polydensified matrix technology is integrating lidocaine pre-incorporation and variable cross-linking density to enable single-product versatility across superficial and deep dermal planes. Aesthetic practitioners in South Korea and Brazil are adopting these formulations at accelerating rates for combined tear trough and midface protocols. The technology is integrating previously separate product lines into unified syringe platforms, compressing inventory carrying costs for multi-site clinic operators.
FDA's evolving guidance on biostimulatory filler PMA requirements is tightening evidentiary standards for poly-L-lactic acid and calcium hydroxylapatite devices seeking expanded indications. Manufacturers must now submit longer-term safety data and histological neocollagenesis documentation for initial approvals. United States-based developers are responding by front-loading clinical trial investment and delaying European parallel submissions until domestic clearance is secured.
Patients are consolidating aesthetic spending with single-provider memberships and subscription-based maintenance programs that bundle fillers with neurotoxin and energy-based treatments. This model displaces transactional per-syringe purchasing at independent dermatology practices and surgery centers. The shift is most visible in United States coastal metropolitan markets where patient acquisition costs have risen sharply and lifetime value optimization has become the dominant commercial priority.
Global Dermal Filler Market Segmentation
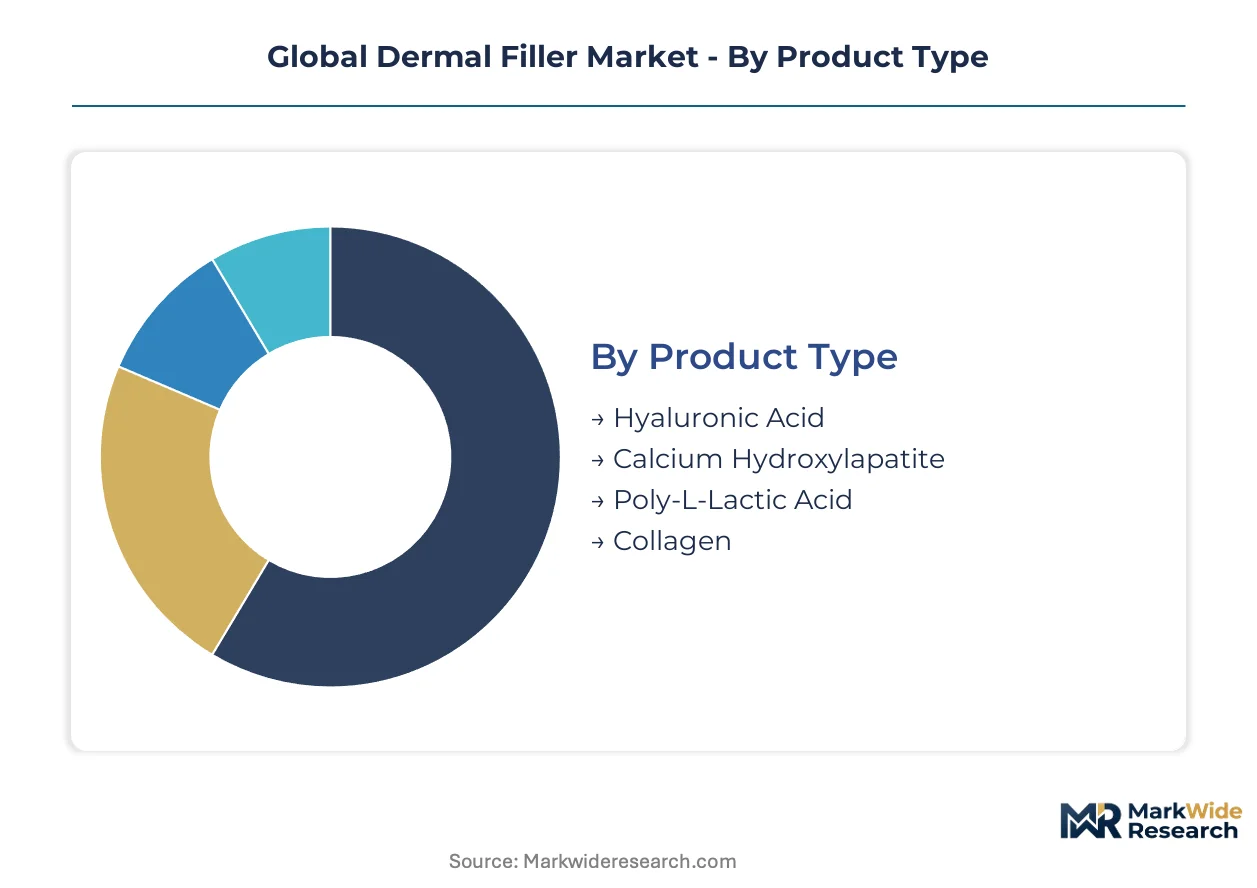
Dermal filler procurement patterns diverge sharply across formulation chemistry, clinical setting, and channel structure. Manufacturers configure production lines and regulatory submissions around these divisions because reimbursement pathways and practitioner training requirements vary by segment.
Product Type:
Capital intensity peaks with biostimulatory formulations requiring extended neocollagenesis trials and specialized microsphere manufacturing infrastructure.
- Hyaluronic Acid:Cross-linked polysaccharide gels dominate current procurement volumes due to immediate volumetric correction and established reversibility protocols. United States dermatology clinics in Los Angeles and Miami concentrate demand here, driven by patient preference for hyaluronidase safety nets and shorter recovery windows.
- Calcium Hydroxylapatite:Biosynthetic microspheres suspended in aqueous carriers stimulate collagen deposition over extended intervals. São Paulo plastic surgery centers favor these formulations for structural cheek and jawline augmentation where longer treatment spacing justifies premium positioning.
- Poly-L-Lactic Acid:Biodegradable polymer particles require reconstitution and series-based injection protocols.
- Collagen:Bovine and porcine-derived matrices now occupy niche applications following displacement by synthetic alternatives.
Most installed capacity flows through Hyaluronic Acid. Expansion is steepest in Poly-L-Lactic Acid.
Application:
Procedure complexity and anatomical risk stratification determine which segments attract board-certified specialists versus general aesthetic practitioners.
- Wrinkle Reduction:Superficial and mid-dermal placement for rhytid correction represents the highest-repeat-purchase segment with shortest learning curves. Seoul medical aesthetic clinics process substantial volume here, supported by dense physician training infrastructure and competitive per-syringe pricing.
- Volume Restoration:Deep dermal and subdermal implantation for lipoatrophy and structural deficiency demands advanced cannula technique. Dubai aesthetic hubs attract medical tourism flows for combination volume-laser protocols unavailable in patients' home markets.
- Facial Contouring:Jawline and chin augmentation using high-G-prime formulations.
- Lip Enhancement:Vermilion border and body augmentation with cohesive low-viscosity gels.
Procedure volume concentrates in Wrinkle Reduction. Training investment is climbing fastest in Volume Restoration.
End User:
Credentialing requirements and emergency protocol infrastructure separate clinically regulated settings from cosmetology-permitted environments.
- Dermatology Clinics:Board-certified specialists with vascular occlusion recognition training and on-site hyaluronidase stocks capture premium pricing for complex facial zones. United States metropolitan markets show pronounced consolidation here as group practices acquire independent operators.
- Plastic Surgery Centers:Operating room infrastructure and anesthesia support enable combination surgical-filler protocols. Brazil's São Paulo and Rio de Janeiro clusters concentrate global surgical aesthetic volume, sustaining demand for high-viscosity structural formulations.
- Beauty Salons:Non-physician injector regulations vary by jurisdiction.
- Hospitals:Reconstructive and post-oncology applications dominate procurement.
Revenue per procedure peaks at Plastic Surgery Centers. Patient acquisition investment is expanding most rapidly at Dermatology Clinics.
Distribution Channel:
Cold chain requirements and lot-traceability obligations favor direct manufacturer relationships over fragmented wholesale networks.
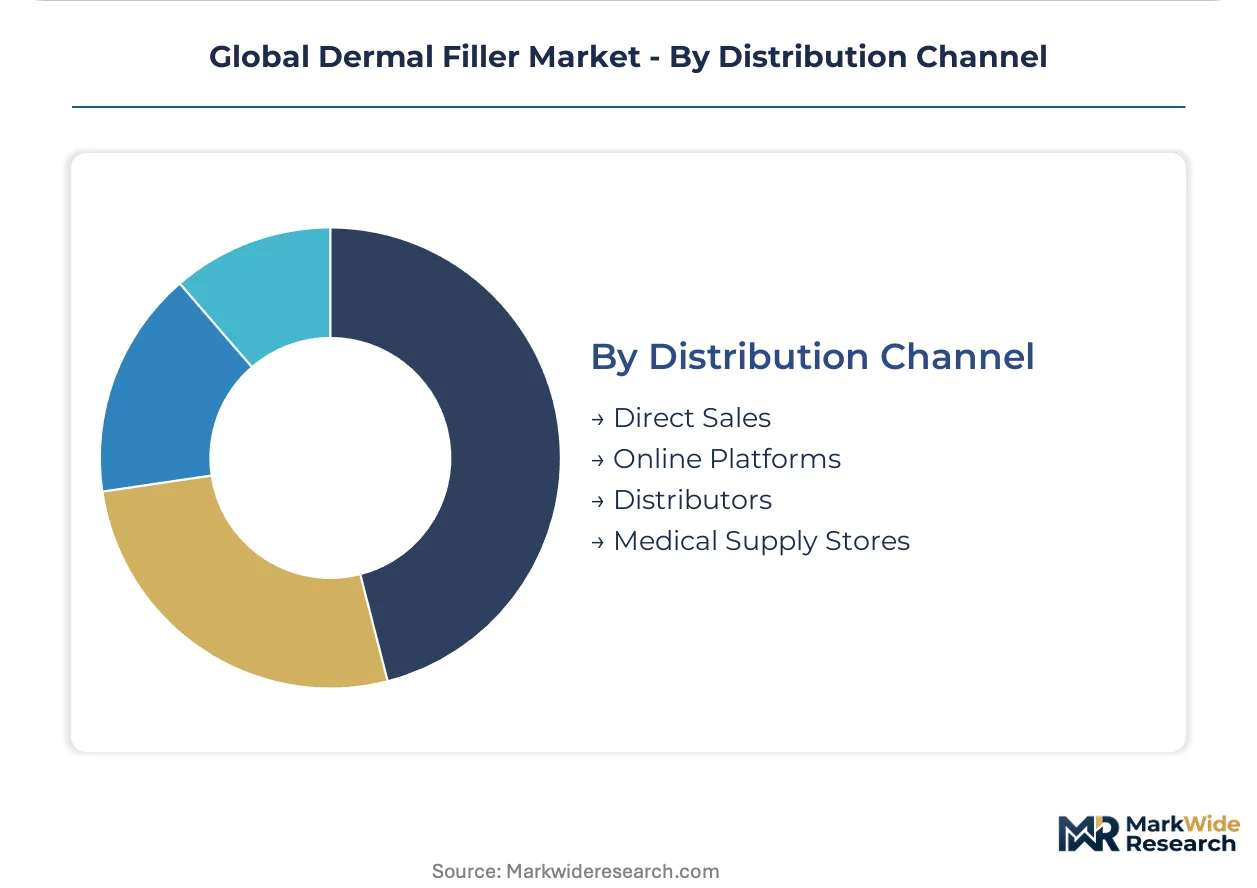
- Direct Sales:Manufacturer-employed specialists provide on-site technique training and inventory management for high-volume United States group practices. This channel captures the steepest discount tiers and tightest supply security.
- Distributors:Regional medical device wholesalers with ISO 13485 certification serve mid-tier clinics across European markets where language and regulatory fragmentation complicate direct coverage.
- Online Platforms:B2B procurement portals with credential verification layers.
- Medical Supply Stores:Brick-and-mortar retailers with limited cold chain capabilities.
Contract value concentrates through Direct Sales. Platform development is advancing fastest in Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium pricing through dense physician networks, while Brazil leverages surgical aesthetic heritage to sustain calcium hydroxylapatite demand. South Korea compresses approval timelines through regulatory innovation. Germany anchors European clinical evidence generation. The UAE captures medical tourism flows from underserved neighboring markets.
United States
FDA clearance pathways and hyaluronidase reversibility infrastructure sustain dermatology clinic consolidation in Los Angeles and Miami. The agency's evolving biostimulatory filler guidance demands longer-term safety submissions. Metropolitan coastal markets show pronounced shift toward subscription-based patient retention models bundling fillers with neurotoxin treatments.
Brazil
ANVISA medical device registration protocols and board-certified physician density in São Paulo support structural filler adoption for jawline augmentation. The national pharmaceutical regulator maintains alignment with international standards while accommodating local clinical practice patterns. Rio de Janeiro plastic surgery centers sustain demand for high-viscosity formulations through combination surgical-filler protocols.
South Korea
MFDS accelerated review pathways and Seoul's aesthetic cluster density compress time-to-market for novel hyaluronic acid innovations. The national regulator streamlines novel biostimulatory formulation approvals. Gangnam medical aesthetic clinics process substantial wrinkle reduction volume through competitive per-syringe pricing and dense training infrastructure.
Germany
EMA MDR clinical evidence thresholds and ISO 13485 quality management standards shape European formulation development timelines. The EU regulatory framework demands expanded PMA-equivalent submissions for biostimulatory devices. Frankfurt and Munich aesthetic practices concentrate demand for premium cohesive polydensified matrix technology with lidocaine pre-incorporation.
United Arab Emirates
MOHAP medical device registration and Dubai's positioning as regional aesthetic hub attract patients from Saudi Arabia, Kuwait, and Egypt. The national health authority facilitates combination filler-laser protocols unavailable in patients' home markets. Dubai aesthetic centers capture premium pricing through medical tourism corridors serving underserved Gulf Cooperation Council demand.
Global Dermal Filler Market Vendor Landscape
Top-tier vendors anchor premium biostimulatory segments, while mid-cap specialists occupy hyaluronic acid commodity tiers. Market structure shows moderate consolidation around integrated manufacturing networks and specialized R&D capabilities. Three archetypes dominate: cross-linked polymer engineers, calcium microsphere technologists, and direct-to-clinic platform operators. Competitive moves concentrate on backward integration into fermentation-derived raw materials and geographic expansion through medical tourism corridor partnerships.
Among Swiss and German-based manufacturers, Galderma and Merz Pharma exemplify integrated network archetypes, while AbbVie Inc. anchors North American channel control. Galderma represents manufacturing consolidation through captive supply of high-viscosity formulations. Merz Pharma occupies a position within specialized microsphere technology development. AbbVie Inc. exemplifies dermatology clinic and plastic surgery center penetration across United States and European metropolitan markets.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Galderma |
| Merz Pharma |
| Sinclair Pharma |
| Revance Therapeutics, Inc. |
| Teoxane Laboratories |
| Zimmer Aesthetics |
| Croma Pharma |
| Prollenium Medical Technologies |
| Others |
Supply Flow & Price Mechanics
Fermentation-derived hyaluronic acid raw material costs cascade through three distinct pricing tiers, with pharmaceutical-grade Chinese bioreactor output feeding premium Seoul and Los Angeles clinic pricing while commodity-grade inputs serve mid-tier Brazilian distributors. Cross-linking density and lidocaine pre-incorporation separate these tiers, with G-prime specifications and MFDS registration status determining final syringe positioning.
Pricing Analysis
Capacity additions in South Korea's Gangnam aesthetic cluster are reshaping price floors for cohesive polydensified matrix formulations. Three-tier pricing structure across premium, standard, and economy levels separates MFDS-registered biostimulatory protocols from commodity hyaluronic acid and unbranded alternatives. Pricing pressure stems from direct-to-clinic digital procurement platforms bypassing traditional distributor markups. United States group practices show lowest price sensitivity due to subscription-based patient retention models, while Brazilian independent clinics face highest cost compression.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Dubai, and São Paulo maintain hub-and-spoke cold chain patterns for temperature-sensitive gel formulations. Manufacturing concentrates in Switzerland, Germany, and South Korea for finished syringes, with fermentation-derived sodium hyaluronate feeding from Chinese bioreactor facilities. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade raw material inputs. Distribution runs through direct manufacturer relationships for high-volume United States dermatology groups, with ISO 13485-certified regional wholesalers serving fragmented European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biostimulatory filler segments where extended treatment intervals elevate per-patient lifetime value and compress customer acquisition cost ratios. Premium-tier shifts toward cohesive polydensified matrix technology with lidocaine pre-incorporation supports pricing power in Seoul and Los Angeles metropolitan markets.
For Market Incumbents: Acquire specialized microsphere manufacturing infrastructure to secure calcium hydroxylapatite supply continuity against Chinese raw material volatility. Defend channel position by embedding manufacturer-employed specialists within high-volume United States group practices for technique training and inventory management. Prioritize backward integration into fermentation-derived hyaluronic acid production to reduce input cost exposure. For New Entrants and Emerging Players: Direct-to-clinic digital procurement platforms offer the most penetrable route for mid-cap specialists seeking United States dermatology group access without legacy distributor relationships. Target medical tourism corridors in Dubai where combination filler-laser protocols attract underserved Gulf Cooperation Council demand. Pursue white-space functional indications including HIV-associated lipoatrophy and post-oncology facial reconstruction for reimbursable European pathways. For Investors and Strategic Acquirers: Consolidation pressure builds where R&D-intensive biostimulatory developers face extended FDA PMA-equivalent timelines and inflated clinical trial investment thresholds. Long-term viability favors integrated manufacturers with captive raw material supply and direct channel control across North American and European metropolitan markets. Watch EMA MDR classification debates for biostimulatory mechanisms as the critical inflection signal for European market access risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation-Derived Raw Materials | Captive hyaluronic acid supply from Chinese bioreactor partnerships reduces input cost volatility for high-viscosity formulations. |
| Direct-to-Clinic Digital Platform Launch | B2B procurement portals with credential verification layers bypass distributor markups for United States dermatology groups. |
| Biostimulatory Filler PMA Submission | FDA clearance for poly-L-lactic acid neocollagenesis protocols demands longer-term safety data and histological documentation. |
| Medical Tourism Corridor Partnership | Dubai aesthetic hub positioning attracts Saudi, Kuwaiti, and Egyptian patients for combination filler-laser protocols. |
| Hybrid Cohesive Polydensified Matrix Product Line | Single-product versatility across superficial and deep dermal planes compresses inventory carrying costs for multi-site operators. |
Methodological Framework
Bottom-up dermatology clinic and plastic surgery center modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with board-certified dermatologists, plastic surgeons, clinic procurement managers, and biomedical engineers combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, ANVISA registration records, and MFDS approval documentation. Cross-referencing hyaluronidase emergency protocol standards across state medical boards anchored United States demand calibration.
Input-output matrices mapped formulation chemistry segments against end-user settings and distribution channel structures across the analysis window. Segmentation dimensions modeled include product type, application complexity, clinical setting credentialing requirements, and regional regulatory cluster. CAGRs derived from volume-price trajectory analysis incorporating physician training density, disposable income proxies, and medical tourism flow patterns. Forecast inputs included MFDS accelerated review pathway utilization rates and EMA MDR clinical evidence threshold evolution.
Regulatory reclassification, raw material supply disruption, and energy-based device substitution are the dominant revision risks for biostimulatory filler demand projections. Forecasts reflect documented assumptions regarding physician training program capacity and hyaluronidase reversibility infrastructure penetration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Dermal Fillers and Botulinum Toxin Market
Aesthetic Medicine
Global Aesthetic Fillers Market