
 Global Dentures Market | 2026-2036
Global Dentures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dentures Market Foresight
ISO 20795-1 certification for denture base polymers is redrawing competitive boundaries in dental prosthetics manufacturing. Straumann Group leverages its digital workflow integration to sustain premium positioning across implant-supported denture segments. DENTSPLY SIRONA Inc. anchors North American distribution through its chairside CAD/CAM ecosystem. Ivoclar Vivadent AG specializes in high-translucency monolithic materials that differentiate its portfolio in aesthetic denture applications.
Dentures are removable prosthetic devices fabricated from acrylic resin, metal alloy, or flexible thermoplastic bases supporting artificial teeth, designed to restore masticatory function and facial aesthetics for partially or fully edentulous patients. Complete dentures retain dominant volume share due to aging demographics, though implant-supported dentures command superior margin pools through titanium abutment integration and precision attachment systems. Flexible thermoplastic materials are gaining fastest adoption in partial denture fabrication as patient comfort preferences shift away from rigid acrylic frameworks. Dental laboratories represent the most concentrated end-user channel, with consolidation trends favoring high-throughput providers capable of same-day digital denture production.
FDA 510(k) clearance requirements govern U.S. denture base material biocompatibility, while EMA Medical Device Regulation (MDR) Class IIa rules enforce post-market surveillance across European distribution. Japan's PMDA mandates material-specific biological safety testing that shapes import eligibility for foreign manufacturers. China's NMPA recently tightened registration standards for custom-made dental prostheses, affecting cross-border laboratory outsourcing arrangements. Stakeholders must monitor evolving digital manufacturing qualifications as regulatory bodies harmonize software-as-a-medical-device frameworks with traditional prosthodontic material approvals.
Market Dynamics
Digital CAD/CAM workflows are restructuring denture manufacturing economics by collapsing traditional laboratory turnaround times from weeks to hours while elevating precision margins that conventional wax-based methods cannot match.
Growth Catalysts
- FDA 510(k) Streamlining:Accelerated clearance pathways for digitally manufactured dental devices reduce time-to-market for new denture base materials and attachment systems.
- Japan's Geriatric Infrastructure:Expanded prosthodontic service mandates in elderly care facilities create dedicated demand channels for complete and implant-supported denture solutions.
- Flexible Thermoplastic Adoption:Patient comfort preferences are pulling partial denture fabrication toward nylon-based and polyamide frameworks that eliminate metal clasp visibility.
Market Restraints
- Acrylic Resin Cost Volatility:Petroleum-derived monomer feedstocks expose denture base manufacturers to energy-price swings that compress margin predictability.
- Baden-Württemberg Supply Concentration:Germany's precision dental laboratory cluster concentrates high-throughput digital production capacity, creating geographic dependency risk for European distribution.
- EMA MDR Class IIa Surveillance:Enhanced post-market clinical follow-up requirements for custom-made dental prostheses extend compliance timelines and documentation burdens.
Strategic Opportunities
- China's NMPA Registration Reform:Tightened standards for cross-border laboratory outsourcing create openings for domestic digital denture production partnerships.
- ISO 20795-1 Certification Gap:Biocompatibility certification for next-generation denture base polymers offers differentiation leverage for materials suppliers.
- Chairside CAD/CAM Convergence:Integration of intraoral scanning with in-office milling systems enables same-day denture delivery models that bypass traditional laboratory channels.
Industry Challenges
- Digital Workflow Talent Scarcity:Shortage of technicians proficient in 3D design software and additive manufacturing equipment constrains laboratory scaling.
- Legacy System Integration Friction:Dental practices face capital and training barriers when retrofitting conventional impression workflows to digital scanning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dentures Market |
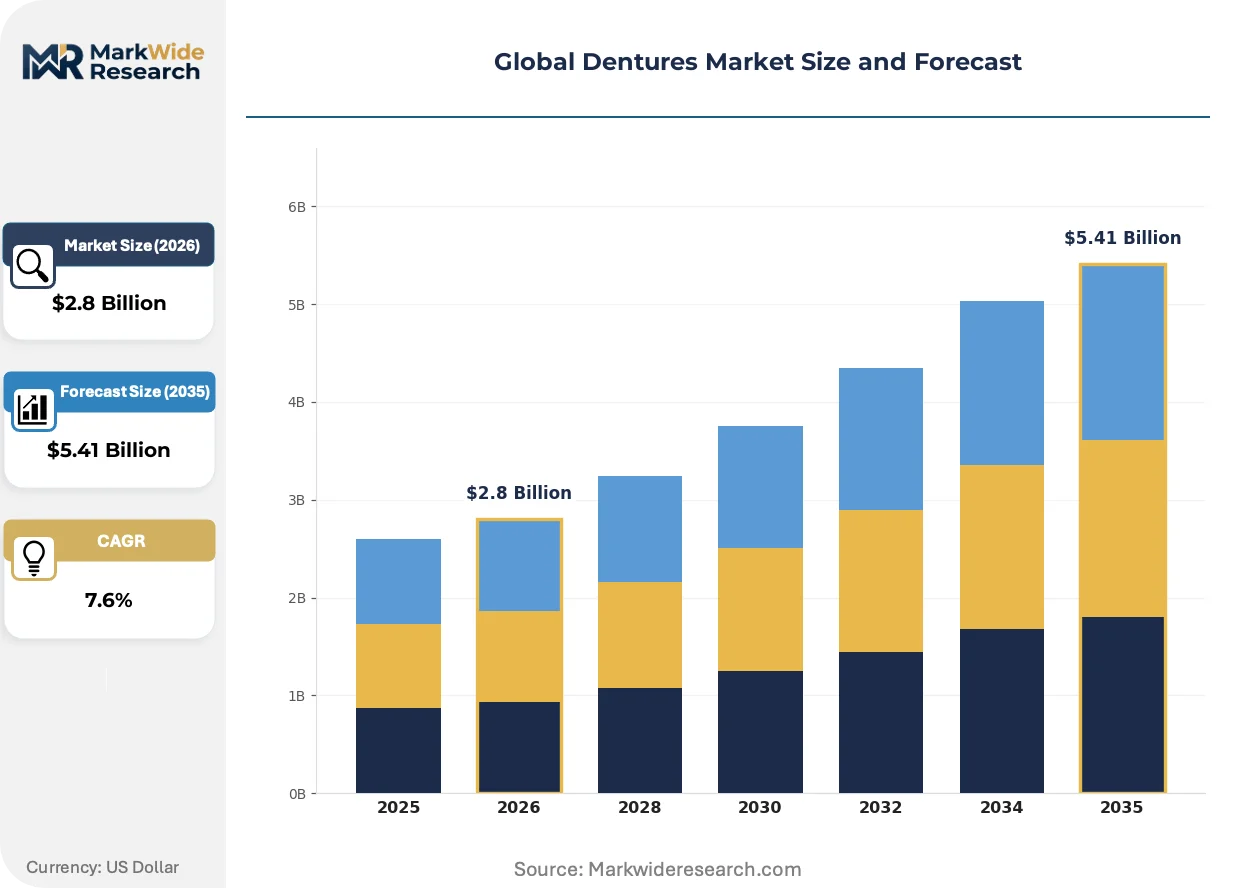
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Dentures, Partial Dentures, Implant-supported Dentures, Immediate Dentures, Overdentures Material: Acrylic Resin, Metal Alloy, Flexible Thermoplastic, Porcelain, Nylon Application: Edentulism Treatment, Tooth Replacement, Oral Rehabilitation, Cosmetic Dentistry, Temporomandibular Disorder Care End User: Dental Clinics, Prosthodontics Centers, Dental Laboratories, Geriatric Care Facilities, Oral Surgery Centers |
| Companies Covered | Modern Dental Group Ltd., Planmeca Group, DENTSPLY SIRONA Inc., COLTENE Holding AG, Amann Girrbach AG, Straumann Group, Zimmer Biomet Holdings Inc., 3Shape A/S, Ivoclar Vivadent AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dentures Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization efforts are converging to redefine performance benchmarks for dental prosthetics, with patient-specific customization replacing standardized production paradigms.
Monolithic high-translucency zirconia and hybrid ceramic composites are displacing layered acrylic denture teeth in premium aesthetic applications. Specialist dental laboratories in Switzerland and Japan are adopting these materials for anterior tooth replacement where optical properties must mimic natural enamel. The shift is compressing demand for conventional acrylic tooth inventories while elevating capital requirements for sintering and characterization equipment.
Europe's Medical Device Regulation (MDR) is enforcing Unique Device Identification (UDI) traceability across custom-made dental prostheses. Laboratory outsourcing arrangements now require documented supply chain visibility that many traditional workflows cannot satisfy. German and French dental technicians' associations are investing in blockchain-based provenance systems to meet EMA compliance deadlines.
Patient-direct digital channels are fragmenting traditional dentist-laboratory relationships. Consumers in South Korea and Australia are accessing teledentistry platforms that coordinate remote impression capture with centralized manufacturing. The model is most visible in metropolitan markets where smartphone penetration and logistics infrastructure support at-home dental kit distribution.
Global Dentures Market Segmentation
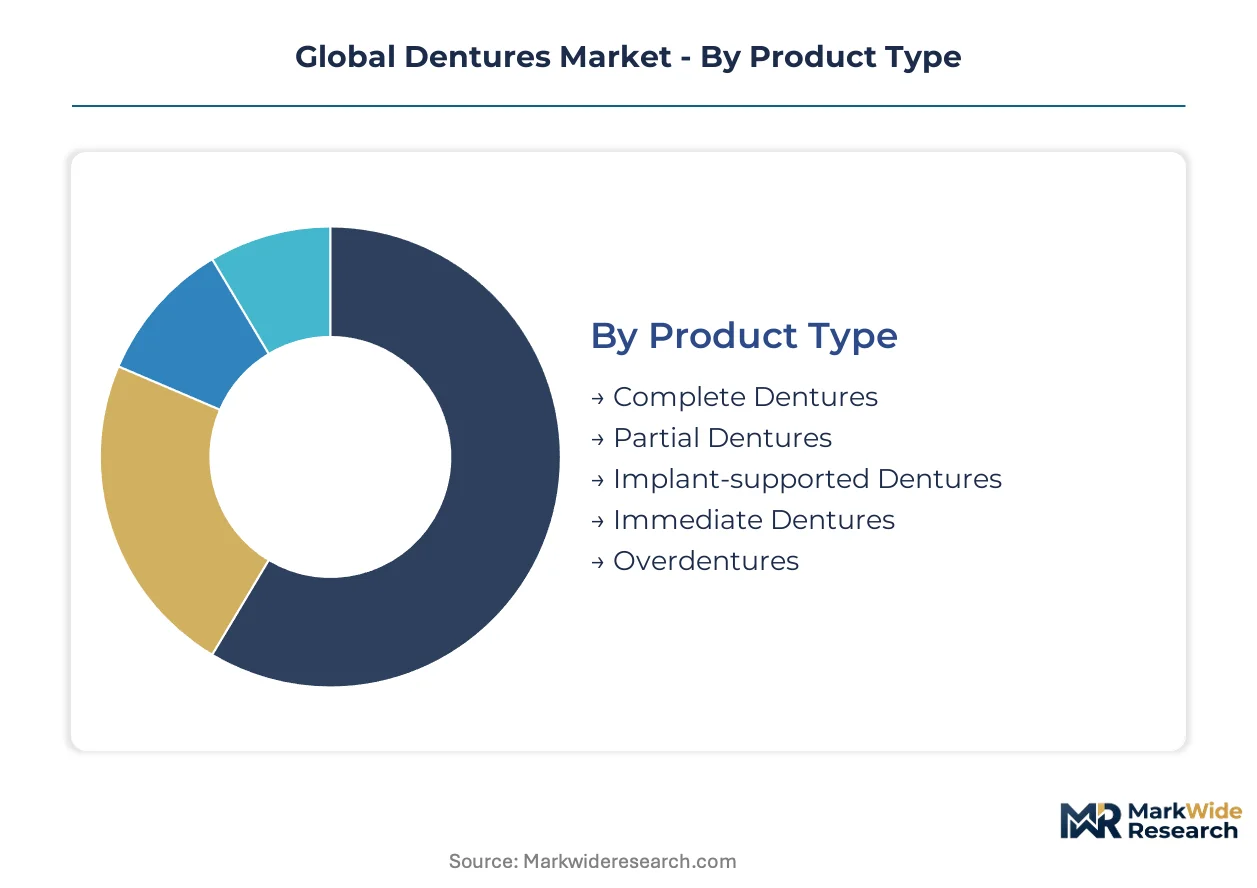
Denture market segmentation reveals distinct procurement patterns across patient acuity levels and manufacturing sophistication tiers. Each category channels demand through different regulatory pathways and reimbursement structures that shape vendor positioning strategies.
Product Type:
Complete dentures dominate domestic consumption in aging populations, while implant-supported variants drive cross-border trade in premium dental tourism corridors.
- Complete Dentures:Full-arch removable prostheses fabricated from heat-cured acrylic resin bases with artificial tooth arrays. Demand concentrates in Japan's geriatric care facilities where government-mandated prosthodontic coverage expansion creates dedicated procurement channels for edentulous patients.
- Implant-supported Dentures:Precision-retained prostheses integrating titanium abutments with attachment systems for enhanced stability. Export-led demand flows through Germany's Baden-Württemberg laboratory cluster, where CAD/CAM integration enables same-day production for international dental tourism markets.
- Partial Dentures:Removable frameworks replacing select missing teeth while preserving natural dentition.
- Immediate Dentures:Pre-fabricated prostheses delivered immediately post-extraction.
- Overdentures:Removable prostheses designed to fit over retained tooth roots or implant abutments.
Complete dentures command the established base. The steepest expansion runs through implant-supported configurations.
Material:
Cost tier differentiation separates commodity acrylic formulations from premium ceramic composites, with mid-market flexible alternatives capturing price-sensitive segments.
- Acrylic Resin:Petroleum-derived polymethyl methacrylate forming the standard denture base matrix. Procurement concentrates in high-volume dental laboratories serving price-sensitive markets, though monomer cost volatility compresses margin predictability for manufacturers.
- Flexible Thermoplastic:Nylon-based and polyamide frameworks eliminating metal clasp visibility in partial applications. Patient comfort preferences in South Korea and Australia are accelerating adoption through teledentistry channels that emphasize aesthetic discretion.
- Metal Alloy:Cobalt-chromium frameworks providing structural rigidity for cast partial dentures.
- Porcelain:Ceramic tooth materials prized for natural optical properties in anterior applications.
- Nylon:Biocompatible polyamide resins for flexible denture base applications.
Acrylic resin maintains volume leadership across all price tiers. Flexible thermoplastic materials are climbing the fastest as comfort preferences reshape partial denture specifications.
Application:
Volume concentration aligns with demographic burden, while margin pools concentrate in functional rehabilitation cases requiring multidisciplinary coordination.
- Edentulism Treatment:Full-arch restoration for completely toothless patients. Demand localizes in elderly care infrastructure, with Japan's expanded prosthodontic service mandates creating institutional procurement channels distinct from retail dental markets.
- Tooth Replacement:Single or multiple unit restoration preserving partial dentition. Aesthetic requirements in cosmetic dentistry segments pull toward high-translucency monolithic materials that command premium positioning.
- Oral Rehabilitation:Comprehensive functional restoration following trauma or surgical intervention.
- Cosmetic Dentistry:Elective aesthetic enhancement procedures.
- Temporomandibular Disorder Care:Occlusal stabilization appliances addressing joint dysfunction.
Edentulism treatment anchors volume demand through institutional channels. Tooth replacement applications are expanding most quickly as aesthetic expectations elevate material specifications.
End User:
Customer type fragmentation separates high-throughput laboratory production from chairside delivery models, with geriatric facilities emerging as a distinct procurement category.
- Dental Laboratories:Centralized manufacturing hubs executing prescription-based prosthetic fabrication. Germany's precision laboratory cluster around Baden-Württemberg concentrates European digital production capacity, creating geographic dependency for cross-border distribution.
- Geriatric Care Facilities:Institutional settings serving elderly populations with dedicated prosthodontic services. Japan's regulatory mandates for edentulous patient coverage are carving out a specialized demand channel with distinct reimbursement protocols.
- Dental Clinics:General practice settings providing primary prosthodontic care.
- Prosthodontics Centers:Specialist referral facilities handling complex rehabilitation cases.
- Oral Surgery Centers:Surgical settings coordinating immediate post-extraction prosthesis delivery.
Dental laboratories retain the established production base. Geriatric care facilities are gaining share fastest as aging demographics institutionalize prosthodontic service delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's distribution dominance for precision dental laboratory equipment, while Japan's Shinkansen freight network connects geriatric care facilities to centralized prosthodontic manufacturing hubs.
United States
FDA 510(k) clearance pathways for CAD/CAM-manufactured dental devices accelerate digital denture approvals, reducing time-to-market for new base materials and attachment systems. The agency's streamlined biocompatibility reviews reshape competitive entry dynamics. Chairside production clusters concentrate in Arizona and Texas, where dental service organizations deploy same-day milling systems.
Germany
EMA Medical Device Regulation Class IIa surveillance enforces Unique Device Identification traceability across custom-made dental prostheses, extending compliance timelines for laboratory outsourcing arrangements. The country's central bank monitors export credit flows for precision dental equipment. Baden-Württemberg's laboratory cluster dominates European high-throughput digital production, creating geographic dependency for cross-border distribution.
Japan
PMDA mandates material-specific biological safety testing that shapes import eligibility for foreign denture manufacturers, particularly for acrylic resin and flexible thermoplastic formulations. METI coordinates geriatric infrastructure expansion. Prosthodontic service mandates in elderly care facilities carve out institutional procurement channels distinct from retail dental markets in the Kanto region.
China
NMPA tightened registration standards for custom-made dental prostheses affect cross-border laboratory outsourcing arrangements, creating openings for domestic digital production partnerships. The country's dual carbon goals pressure petroleum-derived monomer feedstock sourcing. Yangtze River Delta dental laboratories invest in localized CAD/CAM capacity to replace imported fabrication services.
Switzerland
Swissmedic enforces ISO 20795-1 certification requirements for denture base polymers entering the domestic market, redrawing competitive boundaries for materials suppliers. The country's precision manufacturing heritage supports high-translucency monolithic material development. Specialist dental laboratories in the Zurich region adopt zirconia and hybrid ceramic composites for anterior tooth replacement applications.
Global Dentures Market Competitive Landscape
Listed leaders compete with private specialists across digital workflow integration and premium material portfolios, producing a tiered structure where scale-driven conglomerates anchor high-volume channels while family-owned laboratories defend niche customization segments. Three archetypes dominate: integrated dental technology conglomerates with chairside-to-laboratory ecosystems; precision materials specialists commanding premium positioning through biocompatibility certification; and regional fabrication networks leveraging geographic proximity for same-day delivery. M&A activity concentrates on digital scanning software assets, while strategic partnerships between polymer suppliers and milling equipment manufacturers reshape upstream supply arrangements.
Among Switzerland-based materials specialists, Ivoclar Vivadent AG and Straumann Group occupy positions exemplifying premium-tier differentiation through monolithic high-translucency portfolios and implant-supported system integration. DENTSPLY SIRONA Inc. represents the integrated conglomerate archetype, anchoring North American distribution density through its chairside CAD/CAM ecosystem. These three entities illustrate how certification depth and workflow convergence separate market tiers.
| Leading Market Players |
|---|
| Modern Dental Group Ltd. |
| Planmeca Group |
| DENTSPLY SIRONA Inc. |
| COLTENE Holding AG |
| Amann Girrbach AG |
| Straumann Group |
| Zimmer Biomet Holdings Inc. |
| 3Shape A/S |
| Ivoclar Vivadent AG |
| Others |
Supply & Pricing Matrix
ISO 20795-1 certification gates both supply qualification and price differentiation in denture base polymers, separating certified premium-grade suppliers from uncertified commodity producers while forcing buyers to pay certification premiums for biocompatibility assurance.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts between dental laboratories and polymer suppliers, with high-throughput German laboratories commanding 15-20% price advantages over smaller regional fabricators. Pricing stratifies across premium, standard, and economy tiers based on material certification grade and digital workflow integration depth. Cost compression in economy acrylic tiers is intensifying because petroleum-derived monomer feedstock volatility squeezes manufacturer margins. Geriatric care facilities in Japan exhibit highest price sensitivity due to government reimbursement caps, while Swiss specialist laboratories show least sensitivity given aesthetic premium positioning.
Supply Chain Analysis
Inbound logistics costs from Asia-Europe container lanes shape raw material economics for denture base polymer distributors serving the Baden-Württemberg laboratory cluster. Manufacturing concentrates in Germany, China, and Switzerland, with acrylic resin monomer production anchored in petrochemical corridors near the Port of Rotterdam and Singapore. The supply chain draws from titanium abutment forging, CAD/CAM milling equipment, and high-translucency ceramic blanks as critical inputs. Single-source vulnerability concentrates in precision attachment systems from Swiss component specialists. Distribution runs through dental laboratory networks rather than direct-to-practice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where digital workflow software subscriptions and remote design support contracts expand faster than physical denture hardware shipments.
For Market Incumbents: Shield premium positioning by deepening backward integration into monolithic zirconia blank production and securing exclusive distribution rights for next-generation flexible thermoplastic formulations. The threat of chairside CAD/CAM systems bypassing laboratory channels demands defensive certification investment in ISO 20795-1 biocompatibility tiers that new entrants cannot rapidly replicate. For New Entrants and Emerging Players: Anchor in China's Yangtze River Delta domestic production partnerships, where NMPA registration reform has opened white-space for localized digital denture fabrication replacing cross-border laboratory outsourcing. Teledentistry-enabled patient-direct channels in South Korea and Australia offer the most penetrable go-to-market angle, leveraging at-home impression kits with centralized manufacturing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chairside CAD/CAM equipment manufacturing as dental service organizations consolidate purchasing power. Long-term viability over the next decade favors acquisition targets with software-defined workflow assets rather than pure hardware fabricators. The signal to watch is FDA 510(k) clearance velocity for digitally manufactured devices as inflection indicator for regulatory-compressed competitive windows.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20795-1 Certification Investment | Biocompatibility certification from Straumann Group and Ivoclar Vivadent redraws competitive boundaries for premium polymer suppliers. |
| Chairside CAD/CAM Integration | Same-day milling systems in Arizona and Texas dental service organizations bypass traditional laboratory channel economics. |
| Blockchain Provenance Implementation | German and French dental technicians' associations deploy ledger systems to satisfy EMA MDR Unique Device Identification traceability mandates. |
| Domestic China Production Partnership | Yangtze River Delta laboratories localize CAD/CAM capacity to replace imported fabrication services under tightened NMPA standards. |
| Flexible Thermoplastic Portfolio Expansion | Nylon-based and polyamide frameworks eliminate metal clasp visibility for South Korean and Australian teledentistry channels. |
Research Methodology
A standing panel of prosthodontic laboratory directors, dental materials procurement managers, CAD/CAM equipment specialists, and geriatric care facility administrators provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, PMDA biological safety testing records, and NMPA registration disclosures. Customs data for acrylic resin monomer trade flows and dental equipment import statistics anchored bottom-up demand modeling, cross-checked against top-down macroeconomic projections for aging demographics. Triangulation across these sources ensured consistency in volume and value estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework modeled segmentation dimensions including product type, material grade, application acuity, and end-user channel structure. CAGRs were derived from fitted growth curves incorporating dental laboratory consolidation rates, digital adoption penetration, and regulatory approval timelines as industry-specific forecast inputs. Cross-referencing with independent trade association data on laboratory throughput and equipment installation bases confirmed model alignment.
Material uncertainties — petroleum price volatility, regulatory harmonization delays for software-as-a-medical-device frameworks, and supply chain disruptions in precision attachment component sourcing — sit outside the modeled envelope. Forecasts reflect assumptions about continued digital workflow adoption and stable reimbursement policies for geriatric prosthodontic services. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Dental Delivery System Market
Dental Devices
Dental Chair Market
Dental Devices
United States Dental Implants Market
Dental Devices
Dental Impression System Market
Dental Devices
Dental Caries Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Orthodontics Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
GCC Dental Implants Market
Dental Devices
China Dental Devices Market