
 Europe Data Protection-As-A-Service Market | 2026-2036
Europe Data Protection-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Protection-As-A-Service Market Foresight
Modular bundling of backup, encryption, and compliance tools into unified subscription tiers is hardening as the dominant procurement pattern across European enterprises. Microsoft Corporation leverages its Azure-native data protection stack to anchor hybrid cloud deployments for large financial institutions. IBM Corporation competes through specialized mainframe-resilient backup architectures that sustain demand among legacy-heavy German manufacturing clients. Commvault Systems Inc. differentiates via granular workload recovery capabilities that position its platform for complex multi-cloud environments.
Data Protection-As-A-Service denotes a cloud-delivered operational model where backup, disaster recovery, encryption, and compliance functions are consumed via subscription rather than owned infrastructure, typically orchestrated through APIs and policy engines with recovery point objectives measured in minutes. The primary commercial purpose is to transfer capital expenditure to operational expenditure while ensuring regulatory recoverability and business continuity. Hybrid cloud deployment captures the widest margin pools as organizations retain sensitive workloads on-premises while bursting archival tiers to public infrastructure. AI-Based Solutions within the technology dimension represent the fastest-expanding segment as automated anomaly detection reduces recovery time objectives. Compliance Management services remain structurally mature across European government agencies with procurement cycles elongated by public tender requirements.
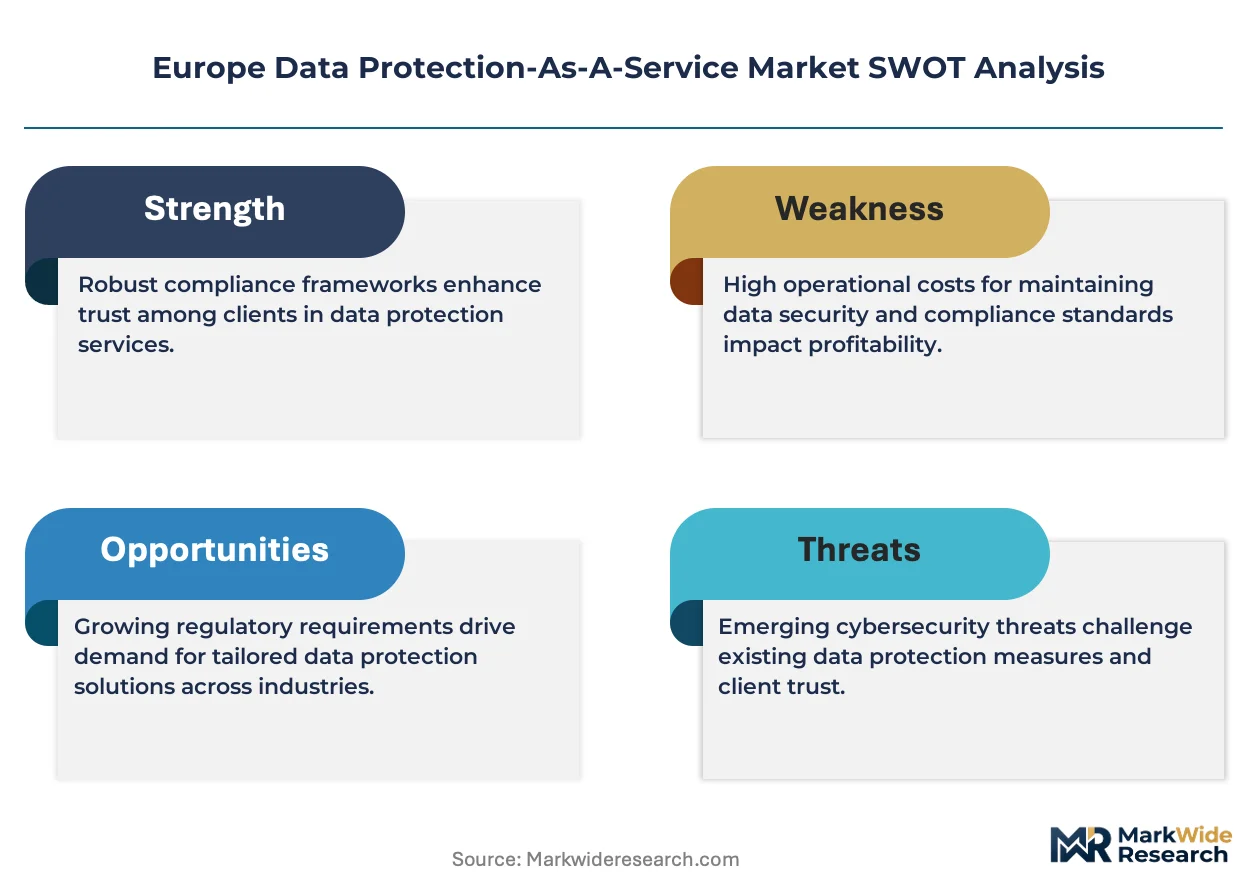
GDPR mandates enforced by CNIL in France, the ICO in the United Kingdom, and BfDI in Germany impose strict breach notification timelines and cross-border data transfer safeguards that directly shape encryption and disaster recovery specifications. The EU AI Act introduces additional algorithmic audit trails that expand compliance management scope for automated data classification systems. Stakeholders must monitor divergence between national supervisory authority interpretations as enforcement intensity varies and creates uneven procurement urgency across member states.
Market Dynamics
GDPR enforcement intensity variations across CNIL, ICO, and BfDI are fragmenting procurement urgency and creating uneven competitive terrain for data protection vendors serving European enterprises.
Growth Catalysts
- GDPR Article 33 Breach Notification Mandates:National data protection authorities in France, Germany, and the United Kingdom impose strict 72-hour disclosure timelines that compel enterprises to deploy automated disaster recovery and encryption solutions.
- Financial Services Regulatory Pressure:European banking supervisors require demonstrable backup recoverability for critical payment systems, driving subscription uptake among Frankfurt, London, and Paris headquartered institutions.
- Hybrid Cloud Architecture Migration:German manufacturing and French healthcare organizations are splitting sensitive workloads between on-premises infrastructure and Azure, AWS, and Google Cloud archival tiers.
Market Restraints
- Cross-Border Data Transfer Uncertainty:Schrems II rulings and adequacy decision volatility between the European Union and the United States create compliance friction for cloud-native backup architectures.
- Legacy Mainframe Integration Costs:German automotive and industrial conglomerates face elevated migration expenses when connecting IBM zSystems environments to API-driven protection services.
- Public Sector Procurement Cycles:European government agencies operate under extended tender frameworks that compress vendor margins and elongate revenue recognition timelines.
Strategic Opportunities
- EU AI Act Algorithmic Audit Requirements:Automated data classification systems used in French and Dutch public administration must maintain explainable decision trails, expanding compliance management scope.
- Small and Medium Enterprise Underpenetration:Italian and Spanish mid-market manufacturers remain reliant on on-premises tape backup, presenting conversion potential for subscription-tier offerings.
- Edge Computing Convergence:Integration of 5G-connected industrial sensors with centralized backup orchestration is creating new workload categories for distributed manufacturing sites in Bavaria and Lombardy.
Industry Challenges
- Zero-Trust Architecture Skill Scarcity:European enterprises report insufficient internal expertise in identity-centric security frameworks, forcing reliance on vendor professional services.
- Multi-Cloud Orchestration Complexity:Fragmented API standards across Azure, AWS, and Google Cloud complicate unified policy enforcement for enterprises operating heterogeneous environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Protection-As-A-Service Market |
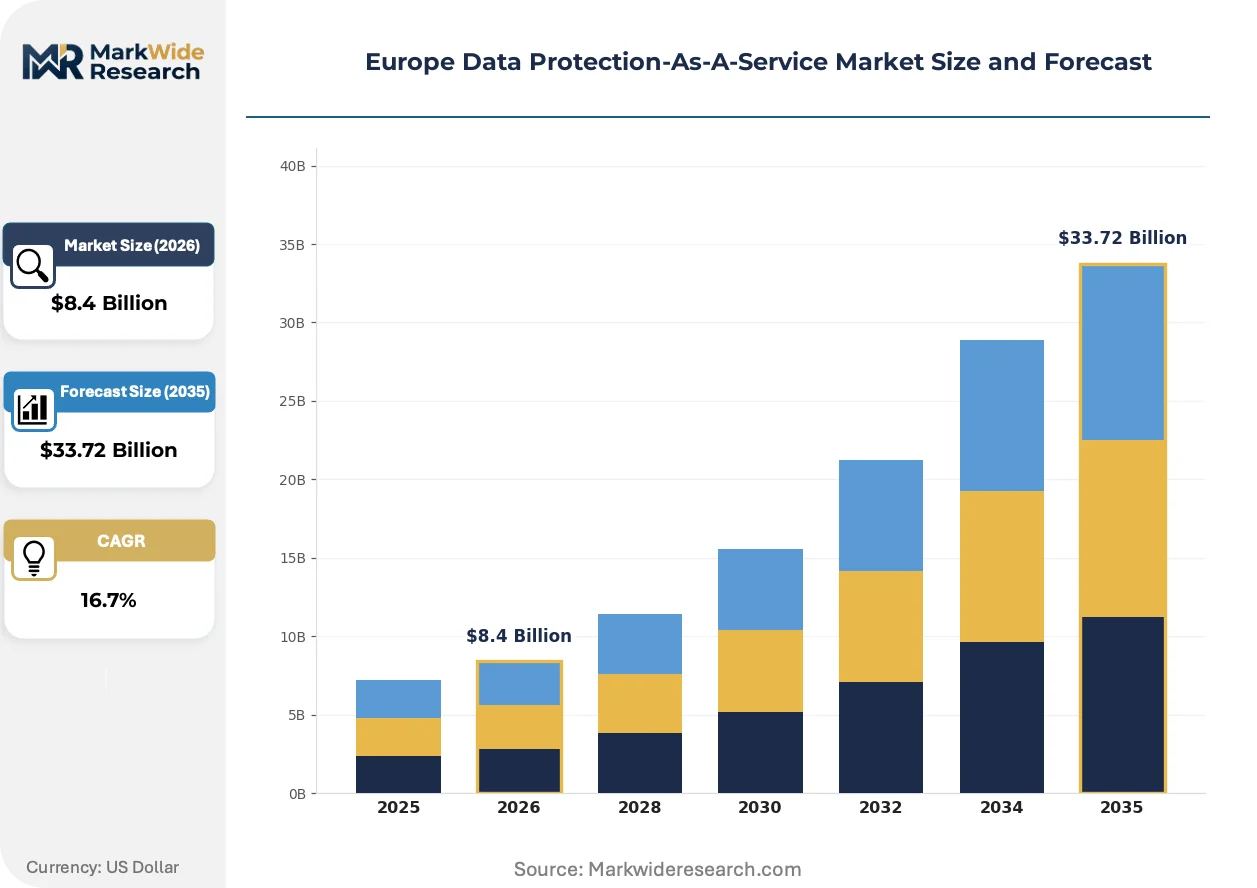
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Backup, Disaster Recovery, Compliance Management, Data Encryption End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Technology: AI-Based Solutions, Blockchain, Encryption, Machine Learning |
| Companies Covered | IBM Corporation, Hewlett Packard Enterprise Company, Oracle Corporation, VMware Inc., Cisco Inc., Microsoft Corporation, Amazon Web Services Inc., Dell Technologies, Commvault Systems Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Protection-As-A-Service Market Shifts & Advancements
Artificial intelligence is compressing recovery time objectives while regulatory layering between GDPR and the EU AI Act is expanding compliance scope beyond traditional data protection boundaries.
Automated anomaly detection systems are integrating behavioral analysis with backup telemetry to identify ransomware encryption patterns before full payload deployment. German financial institutions in Frankfurt and Munich are deploying these capabilities at scale. The technology is integrating forensic response workflows directly into disaster recovery orchestration, collapsing the gap between breach identification and restoration.
The EU AI Act introduces mandatory documentation requirements for automated decision systems processing personal data. French healthcare networks and Dutch government agencies must now maintain algorithmic audit trails alongside traditional backup records. Medical imaging and predictive analytics workloads in Paris and Amsterdam hospitals face expanded compliance scope.
Consumption-based pricing models are displacing capacity-reserved contracts among mid-market European enterprises. Italian manufacturing firms and Spanish logistics operators now prefer per-workload metering over fixed subscription tiers. This behavioral shift is most visible in Milan and Barcelona, where procurement teams prioritize operational expenditure flexibility over multi-year capital commitments.
Europe Data Protection-As-A-Service Market Segmentation
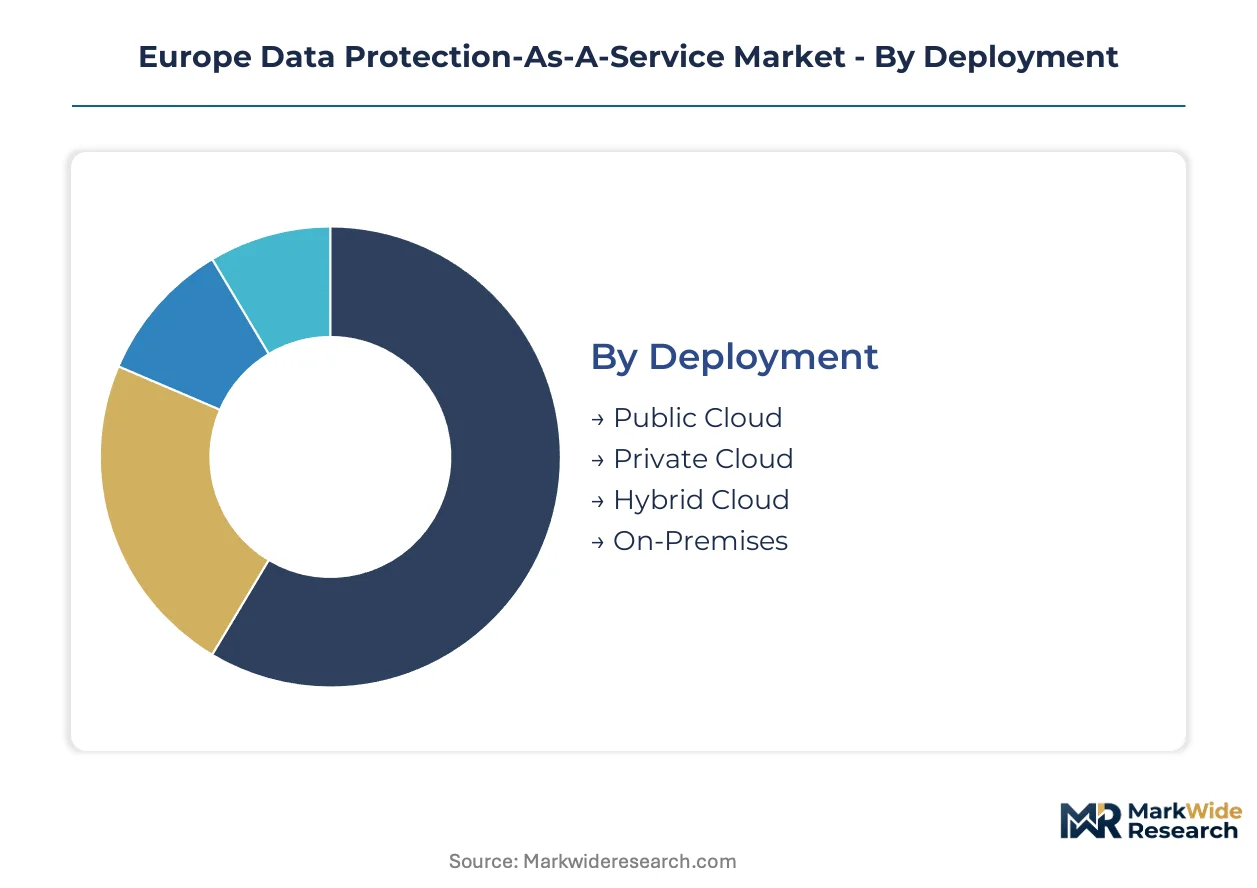
Segmentation in the Europe Data Protection-As-A-Service Market reveals how procurement patterns split between standardized cloud tiers and customized compliance bundles. Organizations in Frankfurt, London, and Paris select deployment modes and service combinations based on regulatory exposure and legacy infrastructure constraints.
Deployment:
The customization-vs-standardization spectrum across deployment modes ranges from fully managed public tiers to architecturally complex hybrid stacks requiring bespoke orchestration.
- Hybrid Cloud:Combines on-premises infrastructure with burst capacity to Azure, AWS, or Google Cloud archival tiers. German manufacturing conglomerates in Bavaria and Baden-Württemberg favor this model to retain sensitive design data locally while offloading historical backups. Regulatory fragmentation between BfDI and CNIL interpretations drives demand for policy engines that enforce divergent cross-border transfer rules.
- Public Cloud:Delivers backup and recovery via multi-tenant infrastructure with API-driven provisioning. French fintech startups in Paris and Lyon prioritize this option for rapid scaling without capital commitment. Schrems II uncertainty constrains adoption among enterprises processing health or financial records subject to GDPR adequacy requirements.
- Private Cloud:Dedicated single-tenant environments with isolated compute and storage resources. UK defense contractors and Dutch critical infrastructure operators specify this deployment for air-gapped recovery capabilities.
- On-Premises:Traditional owned infrastructure with licensed software agents. Italian public administration and Spanish regional health authorities maintain these configurations due to extended public tender cycles that delay cloud migration approvals.
Leading the category by volume: Hybrid Cloud. Growing fastest: Public Cloud.
Service Type:
Cost tier stratification separates premium compliance bundles from standardized backup subscriptions, with encryption services commanding margin premiums in regulated verticals.
- Backup:Scheduled data replication with configurable recovery point objectives ranging from minutes to hours. German automotive suppliers in Stuttgart and Wolfsburg deploy these services to protect CAD repositories and production telemetry. Subscription metering based on protected workload volume is displacing capacity-reserved contracts among mid-market manufacturers.
- Compliance Management:Policy enforcement, audit trail generation, and regulatory reporting automation. French healthcare networks and Dutch government agencies require these capabilities to satisfy EU AI Act documentation mandates alongside GDPR Article 30 records. Procurement cycles elongate due to public sector tender frameworks that compress vendor margins.
- Disaster Recovery:Orchestrated failover and restoration workflows with defined recovery time objectives. UK financial services firms in the City of London specify these services for payment system continuity under PRA supervision.
- Data Encryption:Key management, tokenization, and cryptographic protection for data at rest and in transit. Demand concentrates among Frankfurt-based banking institutions facing ECB cybersecurity expectations.
Backup commands the largest revenue pool. Compliance Management is expanding most quickly.
End User:
Application complexity varies sharply across customer types, with government agencies requiring extended integration phases and SMEs demanding rapid deployment templates.
- Large Enterprises:Multi-divisional organizations with heterogeneous infrastructure spanning mainframe, virtualized, and containerized workloads. German industrial conglomerates in the Rhine-Ruhr region maintain IBM zSystems alongside cloud-native applications, necessitating specialized backup architectures. Procurement teams negotiate enterprise license agreements with professional services attachments.
- SMEs:Mid-market organizations with 50-500 employees and limited internal IT specialization. Italian manufacturing firms in Milan and Turin and Spanish logistics operators in Barcelona favor per-workload metering over fixed commitments. Conversion potential remains substantial as tape-dependent operations modernize.
- Government Agencies:National and regional public administration bodies subject to public procurement directives. Extended tender frameworks in France, Germany, and the United Kingdom elongate revenue recognition timelines for vendors.
- Educational Institutions:Universities and research organizations with fluctuating storage demands tied to academic calendars. UK Russell Group institutions represent concentrated demand for research data preservation services.
Large Enterprises dominate current spending. SMEs are gaining share fastest.
Technology:
Maturity gradients separate production-ready encryption stacks from emerging AI and blockchain capabilities with limited standardization.
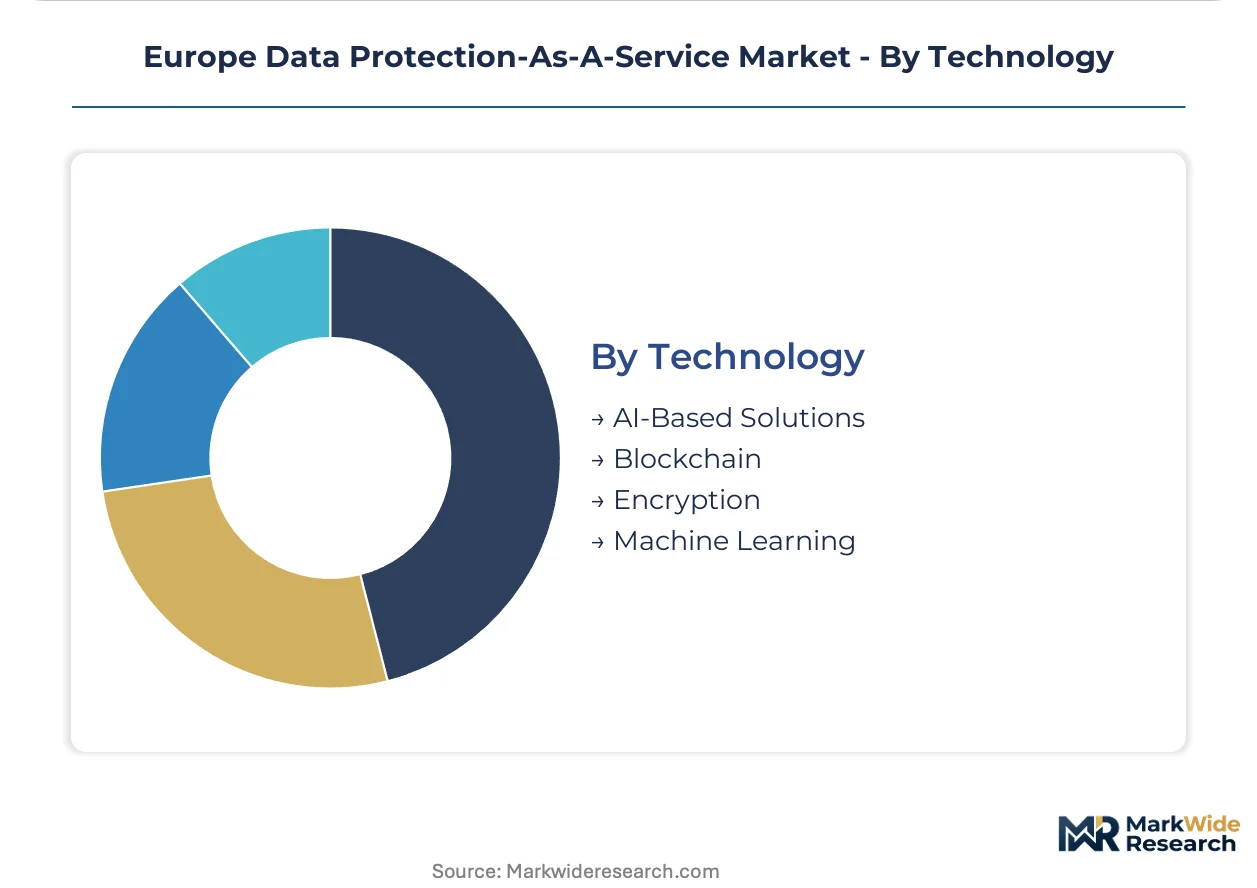
- AI-Based Solutions:Automated anomaly detection integrating behavioral analysis with backup telemetry to identify ransomware encryption patterns. Frankfurt and Munich financial institutions deploy these capabilities at scale. Forensic response workflows collapse the gap between breach identification and restoration.
- Encryption:Established cryptographic protocols including AES-256 and elliptic curve implementations. French healthcare networks and UK banking infrastructure rely on these foundations for GDPR Article 32 security compliance.
- Machine Learning:Predictive capacity planning and policy optimization based on historical workload patterns. Dutch cloud service providers integrate these capabilities into managed protection offerings.
- Blockchain:Distributed ledger verification for backup integrity attestation. Experimental deployments in Swiss pharmaceutical supply chains and Estonian digital government infrastructure remain limited by scalability constraints.
Encryption anchors the installed base. AI-Based Solutions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's Mainhattan financial district and Paris-Saclay technology cluster function as Europe's primary concentration zones for data protection procurement, with regulatory enforcement intensity varying sharply across CNIL, BfDI, and ICO jurisdictions.
Germany
Bavarian automotive suppliers and Frankfurt banking headquarters drive hybrid cloud adoption for CAD repository protection and payment system continuity. BfDI enforcement of GDPR Article 33 mandates compels 72-hour breach notification capabilities across Rhine-Main financial institutions. Stuttgart and Wolfsburg manufacturing clusters deploy specialized backup architectures for production telemetry and design data.
France
Paris fintech startups and Lyon healthcare networks prioritize rapid-scaling public cloud deployments with API-driven provisioning. CNIL sanctions for cross-border transfer violations accelerate encryption procurement among Île-de-France enterprises. French healthcare networks in Paris and Marseille face expanded EU AI Act compliance scope for medical imaging workloads.
United Kingdom
City of London financial institutions and UK defense contractors split demand between disaster recovery orchestration and air-gapped private cloud specifications. ICO enforcement timelines for personal data breaches drive automated anomaly detection deployment. London-based payment system operators maintain demonstrable recoverability under PRA supervisory expectations.
Italy
Milan and Turin mid-market manufacturers present substantial conversion potential from tape-dependent operations to subscription-tier offerings. Extended public tender cycles in Italian regional administration delay cloud migration approvals. Lombardy industrial clusters favor per-workload metering over fixed commitments for operational expenditure flexibility.
Netherlands
Amsterdam healthcare networks and Dutch government agencies require algorithmic audit trails under EU AI Act mandates alongside traditional backup records. Dutch cloud service providers integrate predictive capacity planning into managed protection offerings. Rotterdam logistics operators and Eindhoven technology firms concentrate demand for behavioral analysis integration with backup telemetry.
Europe Data Protection-As-A-Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across subscription tiers, creating a tiered structure where scale advantages concentrate in hybrid cloud orchestration. The vendor base separates into three strategic archetypes: hyperscale cloud platforms with native protection stacks, legacy infrastructure specialists with mainframe-resilient architectures, and independent software vendors with granular workload recovery capabilities. Dominant competitive moves include modular bundling of compliance tools into unified tiers and API-driven integration partnerships for multi-cloud policy enforcement.
Within the diversified technology conglomerate tier, IBM Corporation and Microsoft Corporation exemplify contrasting approaches to European enterprise penetration. IBM Corporation occupies a position among legacy infrastructure specialists serving manufacturing-heavy German clients with mainframe-adjacent requirements. Microsoft Corporation anchors the hyperscale platform archetype through Azure-native data protection for financial institutions pursuing hybrid architectures. Commvault Systems Inc. sits within the independent software vendor tier, representing granular recovery specialization for complex multi-cloud environments. Hewlett Packard Enterprise Company and Dell Technologies occupy positions bridging hardware-centric and cloud-delivered service models.
| Leading Market Players |
|---|
| IBM Corporation |
| Hewlett Packard Enterprise Company |
| Oracle Corporation |
| VMware Inc. |
| Cisco Inc. |
| Microsoft Corporation |
| Amazon Web Services Inc. |
| Dell Technologies |
| Commvault Systems Inc. |
| Others |
Supply & Pricing Matrix
Cloud infrastructure costs from Azure, AWS, and Google Cloud data centers cascade through subscription tiers, compressing margins for mid-market vendors while hyperscale providers absorb economies of scale into bundled enterprise agreements. German automotive and French healthcare buyers negotiate per-workload metering that shifts cost risk upstream to service orchestration layers.
Pricing Analysis
Margin tightening in mid-market subscription tiers reflects hyperscale bundling pressure as Microsoft and Amazon fold data protection into broader cloud commitments. Three-tier pricing structure across premium compliance bundles, standard backup subscriptions, and economy archival tiers separates buyers by regulatory exposure and recovery time requirements. Cost compression accelerates in Italian and Spanish SME segments where tape-dependent operations resist operational expenditure conversion. Government agencies exhibit lowest price sensitivity due to extended tender frameworks that prioritize audit trail depth over unit cost.
Supply Chain Analysis
Workforce scarcity in Ireland, Netherlands, and Germany constrains delivery capacity for specialized compliance integration and mainframe-resilient architecture deployment. Cloud infrastructure provisioning draws from hyperscale data center footprints in Frankfurt, Dublin, and Amsterdam, with encryption key management hardware sourcing from semiconductor fabricators in Taiwan and South Korea. Single-source vulnerability concentrates in API orchestration layers where fragmented standards across Azure, AWS, and Google Cloud complicate unified policy enforcement. Distribution runs through direct enterprise sales teams and managed service provider channels serving mid-market manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor consolidation accelerates as GDPR enforcement variations and EU AI Act compliance scope expansion force subscale players toward acquisition or exit. Hyperscale bundling and specialized compliance depth separate survivors from casualties.
For Market Incumbents:Hedge against margin erosion in standardized backup tiers by deepening vertical integration into mainframe-resilient orchestration for German automotive clients and AI-driven anomaly detection for Frankfurt banking institutions. Acquire compliance management specialists with established CNIL and BfDI audit frameworks to capture EU AI Act documentation mandates ahead of tender-driven procurement cycles.
For New Entrants and Emerging Players:Capture white-space opportunity in Italian and Spanish mid-market manufacturing where tape-dependent operations present conversion potential for per-workload metering models. Target edge computing convergence in Bavarian and Lombardy industrial sensor networks with 5G-connected backup orchestration purpose-built for distributed manufacturing telemetry.
For Investors and Strategic Acquirers:BfDI enforcement intensity divergence from CNIL and ICO timelines is the leading indicator that regulatory fragmentation will favor acquisition targets with multi-jurisdiction compliance automation. Position for 5-10 year viability around pure-play specialists with granular workload recovery capabilities and established API-driven multi-cloud orchestration. Monitor Schrems II adequacy decision volatility as the signal triggering accelerated consolidation among cloud-native backup architectures exposed to cross-border transfer uncertainty.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure-native data protection anchors hybrid deployments for Frankfurt banking institutions. |
| Acquisition of Specialist Firm | Mainframe-resilient backup capabilities sustain demand among Stuttgart automotive suppliers. |
| Strategic Partnership | API-driven integration partnerships enable unified policy enforcement across multi-cloud environments. |
| Geographic Expansion | Milan and Barcelona SME penetration converts tape-dependent operations to subscription tiers. |
| Product Launch | AI-based anomaly detection compresses recovery time objectives for Munich financial institutions. |
Research Methodology
Document review covered regulatory filings from CNIL, BfDI, and ICO, complemented by interviews with CTOs at Frankfurt banking institutions, IT procurement officers in Paris healthcare networks, platform engineers at Dutch cloud service providers, and compliance leads at German automotive suppliers. Secondary validation drew from SEC filings of listed vendors, hyperscaler capex disclosures, EU AI Act implementation guidance, and GDPR enforcement tracker databases. Bottom-up deployment modeling triangulated against top-down market sizing across subscription tiers.
Segmentation outputs reflect deployment mode, service type, end-user scale, and technology maturity dimensions modeled across the projection horizon. CAGRs derived from elasticity analysis of regulatory enforcement intensity, cloud migration velocity, and AI adoption curves in financial services and healthcare verticals. Forecast inputs incorporated BfDI breach notification timelines, Schrems II adequacy decision uncertainty, and EU AI Act algorithmic audit requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between national supervisory authorities and cross-border data transfer framework volatility. Forecasts reflect documented assumptions regarding enforcement consistency and cloud infrastructure availability. Material deviation in GDPR penalty trajectories or adequacy decision stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Europe Data Exfiltration Market
Cybersecurity
ASEAN Cyber Security Market
Cybersecurity
Threat Intelligence Security Market
Cybersecurity
Network Sandboxing Market
Cybersecurity
Data Center Security Market
Cybersecurity
Nordics Cybersecurity Market
Cybersecurity
Turkey Cybersecurity Market
Cybersecurity
Europe Cloud DLP Market
Cybersecurity
Cyber Security As a Service Market
Cybersecurity
Cloud-Based Email Security Market
Cybersecurity
Mainframe Security Market
Cybersecurity
Sweden Cybersecurity Market
Cybersecurity
India Cybersecurity Market
Cybersecurity
Cloud Security Market
Cybersecurity
Mobile Encryption Market
Cybersecurity
Artificial Intelligence-Based Cybersecurity Market