
 India Cybersecurity Market | 2026-2036
India Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
India Cybersecurity Market Foresight
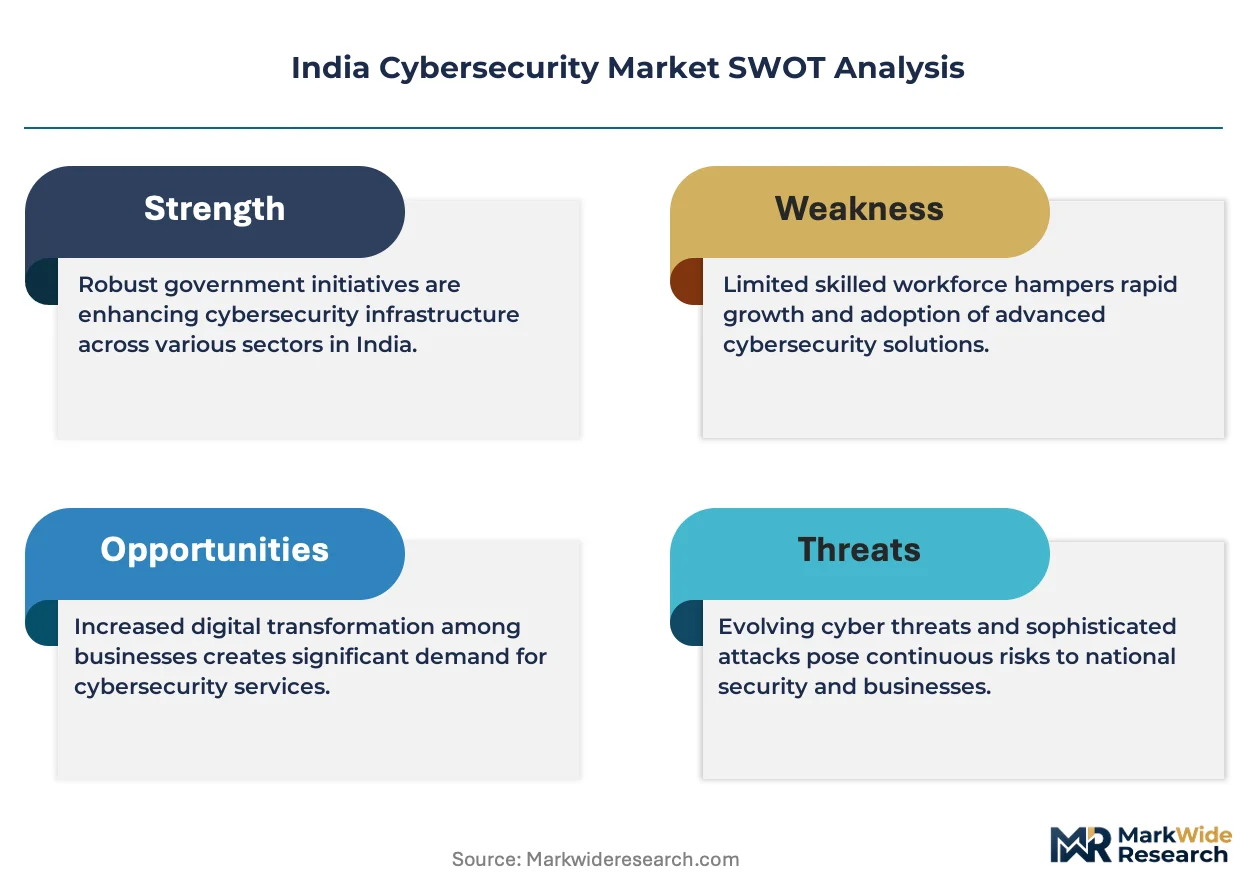
The Digital Personal Data Protection Act is shifting compliance burdens across enterprise IT budgets, forcing organizations to reallocate capital toward data governance and breach-response capabilities. HCL Technologies leverages its integrated cybersecurity services portfolio to anchor large government and BFSI contracts. Tata Consultancy Services sustains competitive pressure through its managed security service centers. Quick Heal Technologies specializes in endpoint protection for India's mid-market segment.
India cybersecurity encompasses hardware, software, and services designed to protect networks, endpoints, and data assets from unauthorized access, malware propagation, and exfiltration attacks, typically operating through real-time threat detection engines with sub-millisecond response latency and AES-256 encryption standards for data-at-rest protection. The primary purpose spans safeguarding critical infrastructure, ensuring business continuity, and preserving consumer trust in digital commerce platforms. Firewall and intrusion detection solutions within the solution type dimension dominate current procurement volumes as perimeter defense remains foundational. Cloud deployment models are expanding fastest among mid-tier enterprises migrating from legacy on-premises architectures. Managed services within the service type category capture disproportionate margin pools due to recurring revenue structures and specialized talent scarcity.
BIS cybersecurity standards, CERT-In incident reporting mandates, and SEBI's IT governance frameworks for capital markets collectively shape product certification requirements and procurement eligibility across regulated sectors. RBI's cyber security guidelines for banks and NBFCs further tighten access controls and audit frequencies. Stakeholders must monitor evolving data localization requirements and quantum-resistant encryption standards to anticipate compliance-driven replacement cycles.
Market Dynamics
The Digital Personal Data Protection Act is compressing procurement cycles across Indian enterprises, forcing immediate capital reallocation toward compliance-ready security architectures before enforcement deadlines crystallize.
Growth Catalysts
- DPDPA Compliance Deadlines:Organizations face mandatory data localization and breach notification rules, triggering replacement of legacy encryption systems with quantum-resistant alternatives.
- RBI Cyber Security Guidelines:Banks and NBFCs must upgrade audit frequencies and access controls, expanding managed security service contracts across Mumbai-Pune financial corridors.
- Cloud Migration Acceleration:Mid-tier enterprises in Maharashtra and Karnataka are abandoning on-premises firewalls for hybrid cloud security stacks, driving infrastructure refresh cycles.
Market Restraints
- Specialized Talent Scarcity:Certified security architects command premium compensation, inflating service delivery costs for MSSP providers operating in Bengaluru and Hyderabad.
- Import Dependency for Hardware:Next-generation firewall appliances rely on semiconductor components concentrated in East Asian supply chains, exposing procurement to geopolitical friction.
- Legacy System Integration Friction:Decades-old core banking infrastructure resists API-based security overlays, delaying zero-trust adoption at public sector institutions.
Strategic Opportunities
- Tier-2 City Expansion:Underpenetrated markets in Ahmedabad, Kochi, and Chandigarh present whitespace for channel partners delivering packaged endpoint protection to SMBs.
- SEBI IT Governance Mandates:Capital market intermediaries must deploy real-time threat detection, creating demand for SOC-as-a-service offerings tailored to broker-dealers.
- AI-Augmented Threat Hunting:Convergence of machine learning with behavioral analytics enables predictive breach prevention, commanding premium pricing from BFSI buyers.
Industry Challenges
- Certification Bottlenecks:BIS cybersecurity product approvals face 8-12 month processing windows, delaying market entry for foreign hardware vendors.
- Fragmented State-Level Procurement:Divergent tender specifications across Maharashtra, Telangana, and Tamil Nadu inflate customization costs for security integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cybersecurity Market |
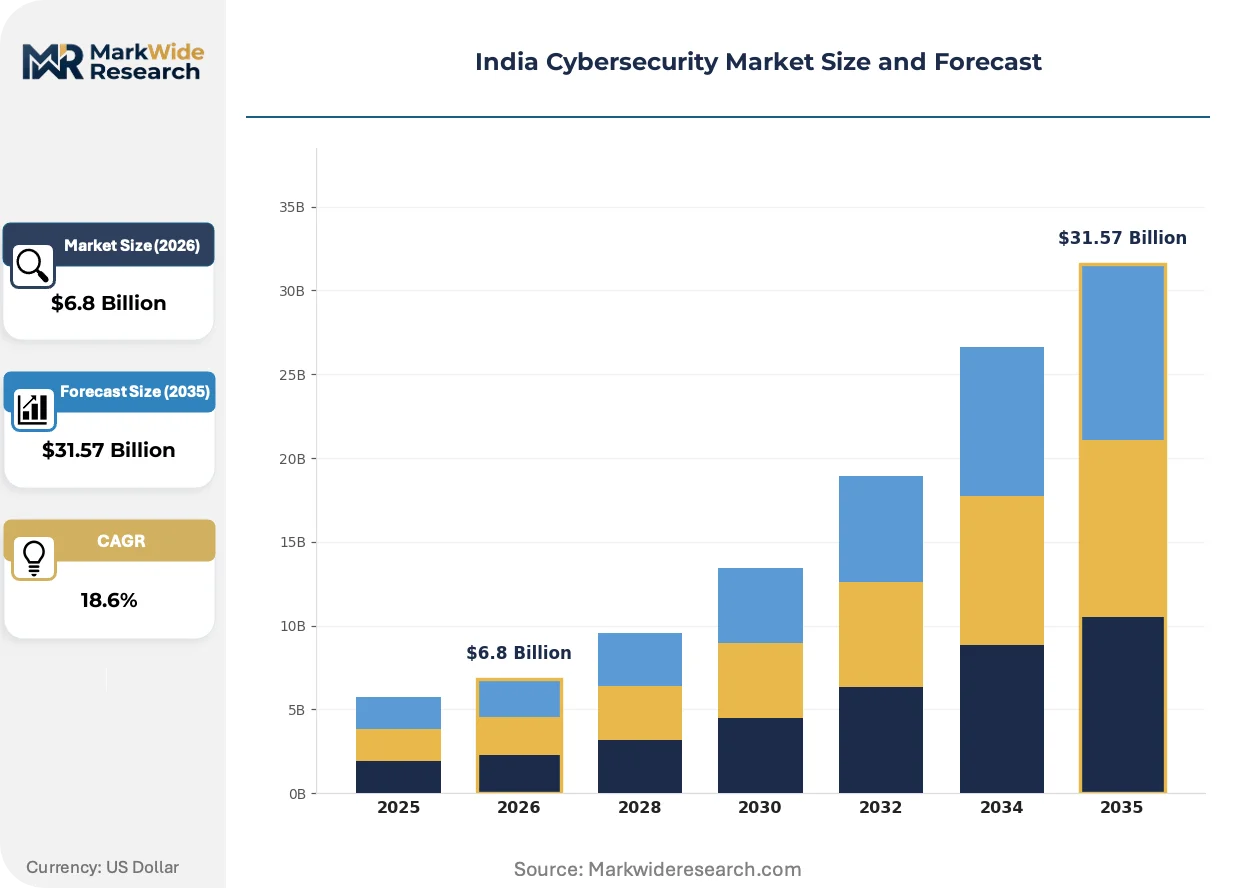
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.57 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
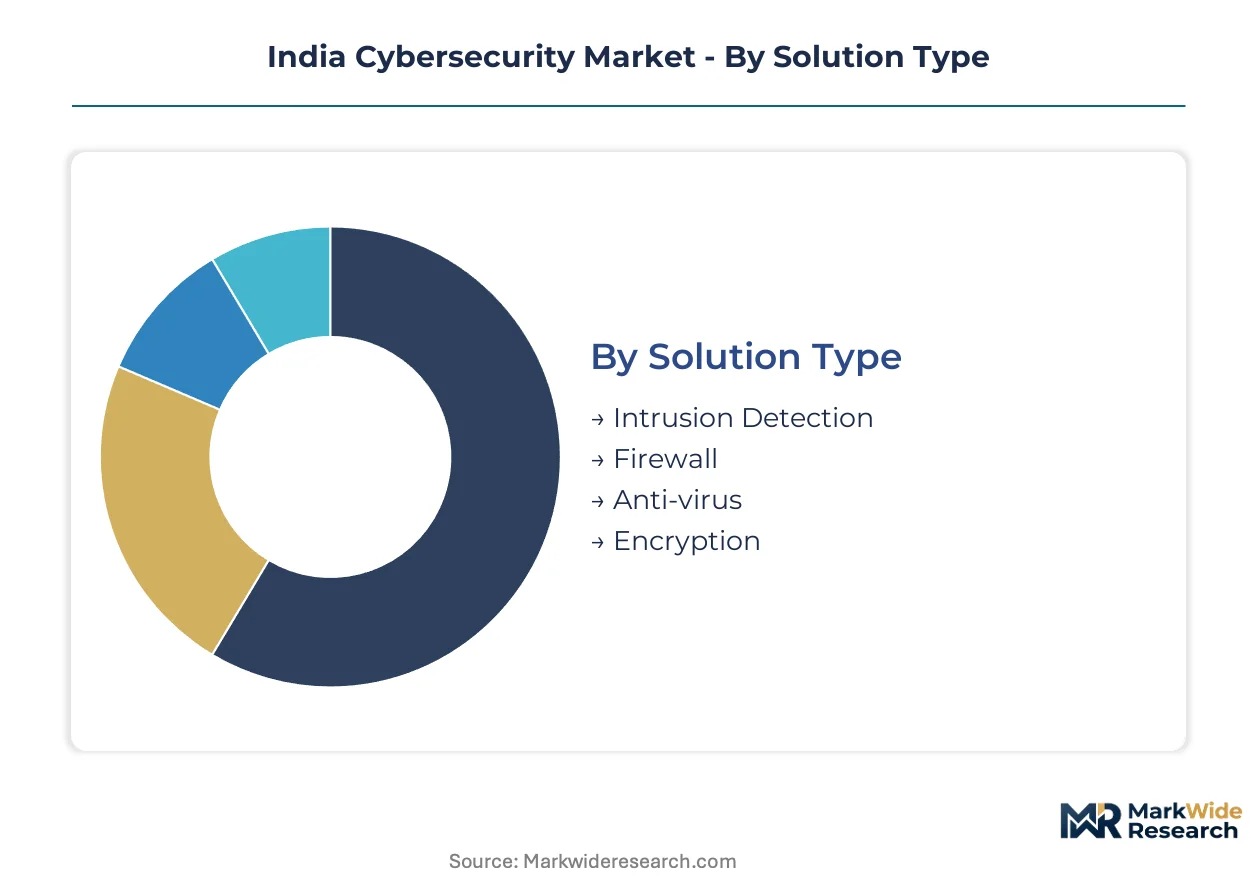
| Segmentation | Solution Type: Intrusion Detection, Firewall, Anti-virus, Encryption Deployment Model: On-premises, Cloud, Hybrid, Managed Security End User: Government, BFSI, Healthcare, Retail Service Type: Consulting, Training, Support, Managed Services |
| Companies Covered | HCL Technologies, IBM Security, Tata Consultancy Services (TCS), CloudSEK, Quick Heal Technologies, Infosys, Tech Mahindra, Fortinet, Wipro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cybersecurity Market Shifts & Advancements
Security architecture is pivoting from perimeter defense to identity-centric protection, compressing the relevance window for traditional firewall-centric spending while elevating continuous authentication and microsegmentation investments.
Zero-trust network architecture is expanding into Indian enterprise environments, replacing VPN-dependent remote access models. IT teams at pharmaceutical and manufacturing firms in Hyderabad and Pune are piloting software-defined perimeters at scale. This shift is compressing hardware firewall refresh cycles while elevating identity governance platform procurement.
CERT-In incident reporting mandates now require six-hour disclosure windows for critical infrastructure operators, fundamentally altering breach response workflows. Financial institutions and data center operators must maintain 24/7 SOC capabilities or face operational eligibility restrictions. Large banks in Mumbai are consolidating vendor relationships to ensure unified telemetry across hybrid environments.
Consumption-based security licensing is displacing perpetual software purchases across mid-market enterprises. Channel partners in Delhi-NCR and Bengaluru are unbundling managed detection and response from broader IT outsourcing contracts. Manufacturing firms in Tamil Nadu and Gujarat now prefer monthly billing aligned to endpoint counts rather than upfront capital deployment.
India Cybersecurity Market Segmentation
India's cybersecurity procurement patterns diverge sharply across solution architectures and operational models. Buyers in Mumbai-Pune financial corridors prioritize compliance-ready stacks, while government tenders emphasize sovereign deployment controls. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume scales.
Solution Type:
Buyer procurement cycles in Maharashtra and Karnataka cluster around perimeter defense upgrades mandated by CERT-In directives, with technical specifications increasingly shaped by quantum-resistant encryption timelines.
- Firewall:Next-generation appliances with deep packet inspection and application-layer filtering dominate enterprise refresh cycles. Mumbai-based banks and NBFCs under RBI cyber security guidelines are replacing legacy stateful inspection systems with AI-augmented threat detection engines.
- Encryption:AES-256 standards for data-at-rest and TLS 1.3 for data-in-transit form baseline procurement specifications. The Digital Personal Data Protection Act is forcing hospitals and fintech operators in Delhi-NCR to re-architect key management systems for localized data storage.
- Intrusion Detection:Network-based and host-based systems with behavioral analytics integration.
- Anti-virus:Endpoint protection platforms with centralized policy management for distributed workforces.
Firewall leads on scale; Encryption leads on momentum.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises builds from operational expenditure models preferred by mid-tier enterprises in Gujarat and Tamil Nadu.
- Managed Security:24/7 SOC capabilities with CERT-In compliant incident response workflows command premium pricing. Bengaluru MSSPs are consolidating vendor relationships for large banks facing six-hour breach disclosure mandates.
- Cloud:Native security controls and CASB deployments accelerate among SaaS-dependent retailers in Hyderabad. Subscription licensing aligns procurement with fluctuating endpoint counts, reducing upfront capital deployment.
- Hybrid:Split architectures maintaining sensitive workloads on-premises while leveraging cloud analytics.
- On-premises:Air-gapped installations for defense and critical infrastructure operators with data sovereignty requirements.
Managed Security leads on scale; Cloud leads on momentum.
End User:
Application-specific compliance burdens create divergent technology requirements across regulated sectors, with SEBI and RBI frameworks imposing distinct audit frequencies and access control specifications.
- BFSI:Real-time fraud detection and transaction monitoring systems absorb disproportionate security budgets. Mumbai-headquartered banks are deploying zero-trust architectures to satisfy RBI cyber security guideline upgrades for NBFCs.
- Government:Classified network segmentation and indigenous cryptographic modules dominate procurement. Central ministries are mandating BIS-certified products with extended processing windows for foreign vendor approvals.
- Healthcare:Patient data protection with Digital Personal Data Protection Act compliance for electronic health records.
- Retail:Payment card industry standards and e-commerce platform protection for consumer transaction volumes.
BFSI leads on scale; Government leads on momentum.
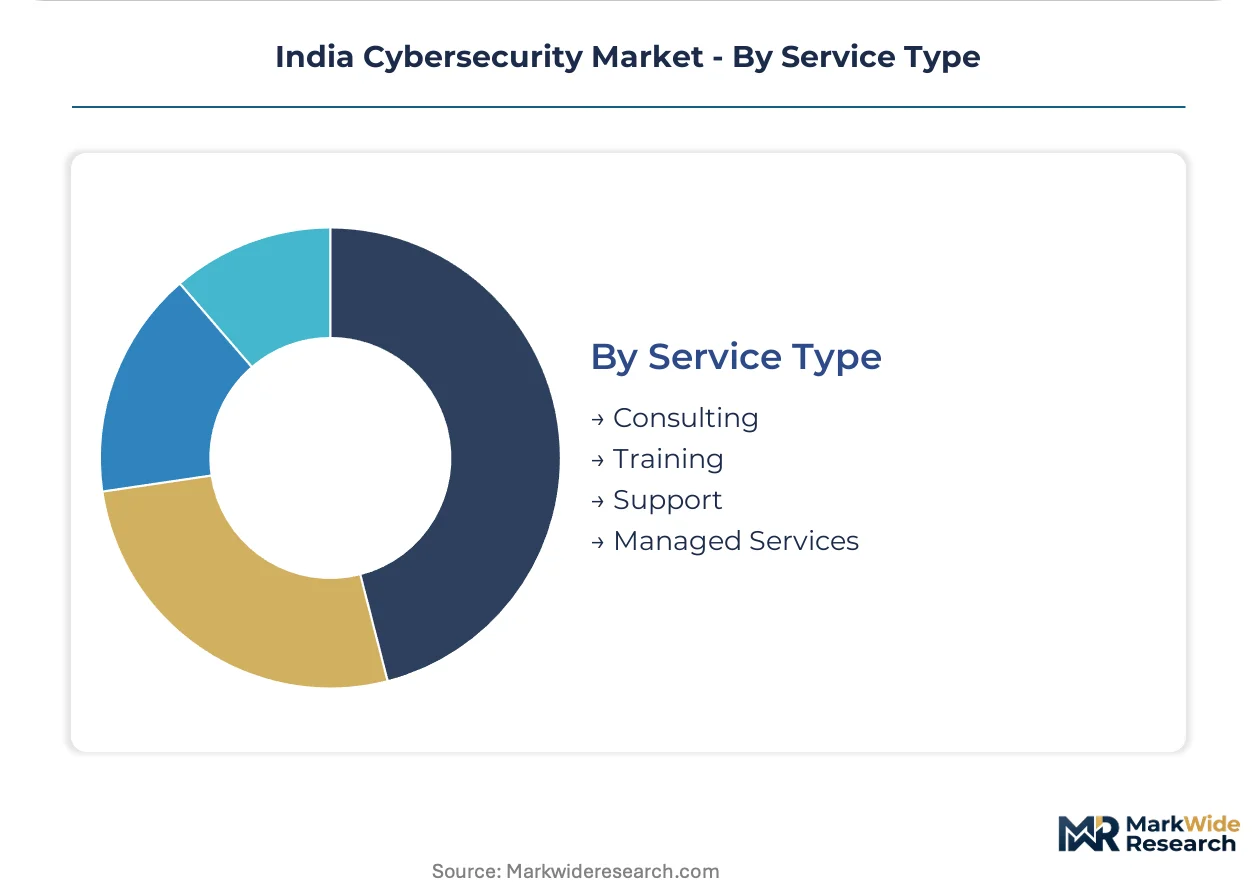
Service Type:
Customer type stratification separates transactional support engagements from multi-year managed service contracts with recurring revenue structures.
- Managed Services:Continuous monitoring, threat hunting, and incident response delivered through dedicated security operations centers. Pune-based enterprises are outsourcing entire security functions to address certified architect scarcity in local talent markets.
- Consulting:Risk assessment, compliance gap analysis, and security architecture design for pre-procurement planning. Firms in Ahmedabad and Kochi are engaging advisory services ahead of DPDPA enforcement deadlines.
- Support:Break-fix maintenance and patch management for deployed security infrastructure.
- Training:Certification programs and simulated phishing exercises for internal security awareness.
Managed Services leads on scale; Consulting leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's cybersecurity industry traces its commercial roots to the 1990s software services boom in Bengaluru and Hyderabad, where export-oriented IT firms first developed security practices for foreign clients before domestic demand accelerated with digital payment proliferation.
Maharashtra
Mumbai's concentration of banking headquarters and Pune's manufacturing-IT hybrid economy generate concentrated demand for managed security services. RBI cyber security guidelines for NBFCs mandate quarterly security audits across financial institutions headquartered here. The Mumbai-Pune corridor hosts India's densest cluster of SOC facilities serving BFSI clients.
Karnataka
Bengaluru's SaaS ecosystem and startup density create demand for cloud-native security architectures among mid-market enterprises. CERT-In directives on incident reporting compliance pressure local firms to maintain 24/7 monitoring capabilities. Whitefield and Electronic City sub-clusters specialize in AI-augmented threat detection development.
Telangana
Hyderabad's pharmaceutical and defense manufacturing base drives air-gapped security requirements for intellectual property protection. State government data center localization policies mandate sovereign deployment models for sensitive workloads. The Genome Valley-HITEC City corridor concentrates on industrial control system security.
Gujarat
Ahmedabad and Surat's SME manufacturing base remains underpenetrated by enterprise-grade security solutions, creating whitespace for packaged endpoint protection. The state's port and logistics infrastructure drives demand for supply chain cybersecurity frameworks. GIFT City's fintech licensing regime imposes SEBI-aligned IT governance standards.
Tamil Nadu
Chennai's automotive and electronics manufacturing clusters require operational technology security integration with legacy shop floor systems. State-level procurement specifications for government digitization projects emphasize BIS-certified indigenous products. The Sriperumbudur-Oragadam industrial belt pilots zero-trust architectures for multi-vendor supplier networks.
India Cybersecurity Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the managed services and consulting spectrum, with recurring revenue structures commanding valuation multiples distinct from transactional product sales. The vendor base stratifies into three tiers: integrated IT services conglomerates, pure-play cybersecurity specialists, and channel-dependent product distributors. Dominant competitive moves include portfolio consolidation through capability tuck-ins and geographic expansion into tier-2 cities via franchise partner networks.
Within the integrated services tier, HCL Technologies and Tata Consultancy Services occupy positions as anchor providers for large government and BFSI contracts, while Quick Heal Technologies exemplifies the product-centric specialist model targeting India's mid-market segment through channel-intensive distribution.
| Leading Market Players |
|---|
| HCL Technologies |
| IBM Security |
| Tata Consultancy Services (TCS) |
| CloudSEK |
| Quick Heal Technologies |
| Infosys |
| Tech Mahindra |
| Fortinet |
| Wipro |
| Others |
Supply & Pricing Matrix
BIS cybersecurity product certification mandates gate qualified supply access and premium-tier pricing eligibility, compressing margins for uncertified foreign hardware vendors while elevating pricing power for indigenous solution providers meeting sovereign deployment standards.
Pricing Analysis
Subscription-based consumption licensing with tiered service levels anchors enterprise procurement, separating premium SOC-as-a-service bundles from standard endpoint protection and economy-tier break-fix support. Price differentiation rests on CERT-In compliance certification and AI-augmented threat detection capabilities. Pricing pressure stems from certified security architect scarcity inflating managed service delivery costs. Mid-market SMBs in Gujarat and Tamil Nadu exhibit highest price sensitivity, while Mumbai-headquartered banks accept premium pricing for 24/7 breach response guarantees.
Supply Chain Analysis
Security operations center workforce availability in Bengaluru and Hyderabad constrains service delivery scaling, forcing MSSP providers to source certified analysts from competing technology hubs. Next-generation firewall hardware draws from semiconductor fabrication concentrated in Taiwan, South Korea, and China. Single-source vulnerability in East Asian chip supply chains exposes procurement to geopolitical friction. Distribution runs through systems integrator partnerships anchored in Delhi-NCR and Mumbai-Pune corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's cybersecurity market offers margin expansion through compliance-driven premium-tier shifts, as DPDPA and RBI mandates force replacement cycles that favor certified indigenous providers over commoditized foreign hardware.
For Market Incumbents: Deploy zero-trust architecture portfolios to capture RBI guideline upgrade spending across Mumbai-Pune NBFCs. Consolidate vendor relationships for large banks facing six-hour CERT-In breach disclosure mandates. Channel control through franchise partner networks in Ahmedabad and Kochi defends against emerging pure-play specialists. For New Entrants and Emerging Players: SEBI IT governance mandates in Maharashtra open a window for SOC-as-a-service offerings tailored to broker-dealers in GIFT City. Target underpenetrated pharmaceutical manufacturing in Hyderabad's Genome Valley corridor with air-gapped industrial control system security. Go-to-market through channel partners bundling endpoint protection with compliance advisory accelerates SMB acquisition. For Investors and Strategic Acquirers: Roll-up economics work for regional MSSP specialists because certified talent scarcity prevents organic scaling and creates forced sellers. Five-to-ten year viability hinges on quantum-resistant encryption transition timing. Watch BIS certification processing windows as inflection indicator for foreign vendor market access.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Deployment | RBI cyber security guidelines for NBFCs mandate access control upgrades across Mumbai financial headquarters. |
| AI-Augmented Threat Detection Development | Machine learning integration enables predictive breach prevention commanding premium BFSI pricing. |
| Tier-2 City Channel Expansion | Franchise partner networks in Ahmedabad and Kochi capture whitespace SMB endpoint protection demand. |
| Quantum-Resistant Encryption Investment | DPDPA data localization rules force replacement of legacy cryptographic systems in Delhi-NCR hospitals. |
| Managed Detection and Response Unbundling | Monthly billing alignment to endpoint counts reduces upfront capital barriers for Tamil Nadu manufacturers. |
Research Methodology
Multiple input streams — primary interviews with CISOs at Mumbai-headquartered banks, procurement officers at Pune manufacturing firms, and channel partners in Bengaluru — were reconciled against secondary validation from CERT-In incident reports, RBI circulars, and SEBI IT governance frameworks. Bottom-up endpoint count modeling and top-down security spending allocation across BFSI, government, and healthcare verticals enabled triangulation.
Historical security procurement patterns were cross-referenced against expert panel assessments of DPDPA enforcement impact across the analysis window. Segmentation dimensions modeled include solution type, deployment model, end-user vertical, and service tier. CAGRs were derived from compliance-driven replacement cycle timing and cloud migration velocity among mid-tier enterprises.
Revisions become necessary when BIS certification processing delays extend beyond current windows or when quantum-resistant encryption standards accelerate ahead of modeled timelines. Material deviation in regulatory enforcement intensity or East Asian semiconductor supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Global Database Encryption Market
Cybersecurity
Chile Cybersecurity Market
Cybersecurity
Global Cyber Data Security Market
Cybersecurity
Malaysia Cybersecurity Market
Cybersecurity
Cyber Warfare Market
Cybersecurity
Global Cloud Security Posture Management Market
Cybersecurity
Portugal Cybersecurity Market
Cybersecurity
Global IoT Digital Forensics Market
Cybersecurity
Data-Centric Security Market
Cybersecurity
Web Application Firewall Market
Cybersecurity
Asia Pacific Digital Forensics Market
Cybersecurity
China Cybersecurity Market
Cybersecurity
Banking Cyber Security Market
Cybersecurity
Global Data Exfiltration Market
Cybersecurity
Kuwait Cybersecurity Market
Cybersecurity
Data Protection Market