
 Turkey Cybersecurity Market | 2026-2036
Turkey Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Cybersecurity Market Insights
Mid-market manufacturers are reorganizing their cybersecurity procurement, shifting from perimeter firewalls toward integrated threat detection platforms. Cisco Systems leverages its channel partnerships across Anatolia to sustain enterprise relationships. Palo Alto Networks anchors its position through cloud-native security specialization for Turkish telecom operators.
Turkey cybersecurity encompasses hardware, software, and services engineered to protect digital infrastructure from unauthorized access, data exfiltration, and operational disruption through encryption protocols, intrusion detection systems, and automated response orchestration. Its primary purpose is ensuring confidentiality, integrity, and availability of critical information assets across enterprise and government networks. Network Security occupies the largest installed base due to legacy infrastructure in state-owned enterprises, while Cloud Security represents the fastest-expanding category as Turkish banks migrate core systems to hybrid architectures. Managed Security Services captures concentrated margin pools because mid-sized firms lack in-house Security Operations Center capabilities.
KVKK, the country's national cybersecurity authority, and BTK enforce data localization and incident reporting obligations that compel foreign vendors to establish domestic data centers. The EU Cybersecurity Act's extraterritorial influence shapes product certification requirements for Turkish exporters serving European clients. Stakeholders must monitor regulatory divergence between KVKK mandates and evolving EU NIS2 implementation timelines to calibrate compliance investments.
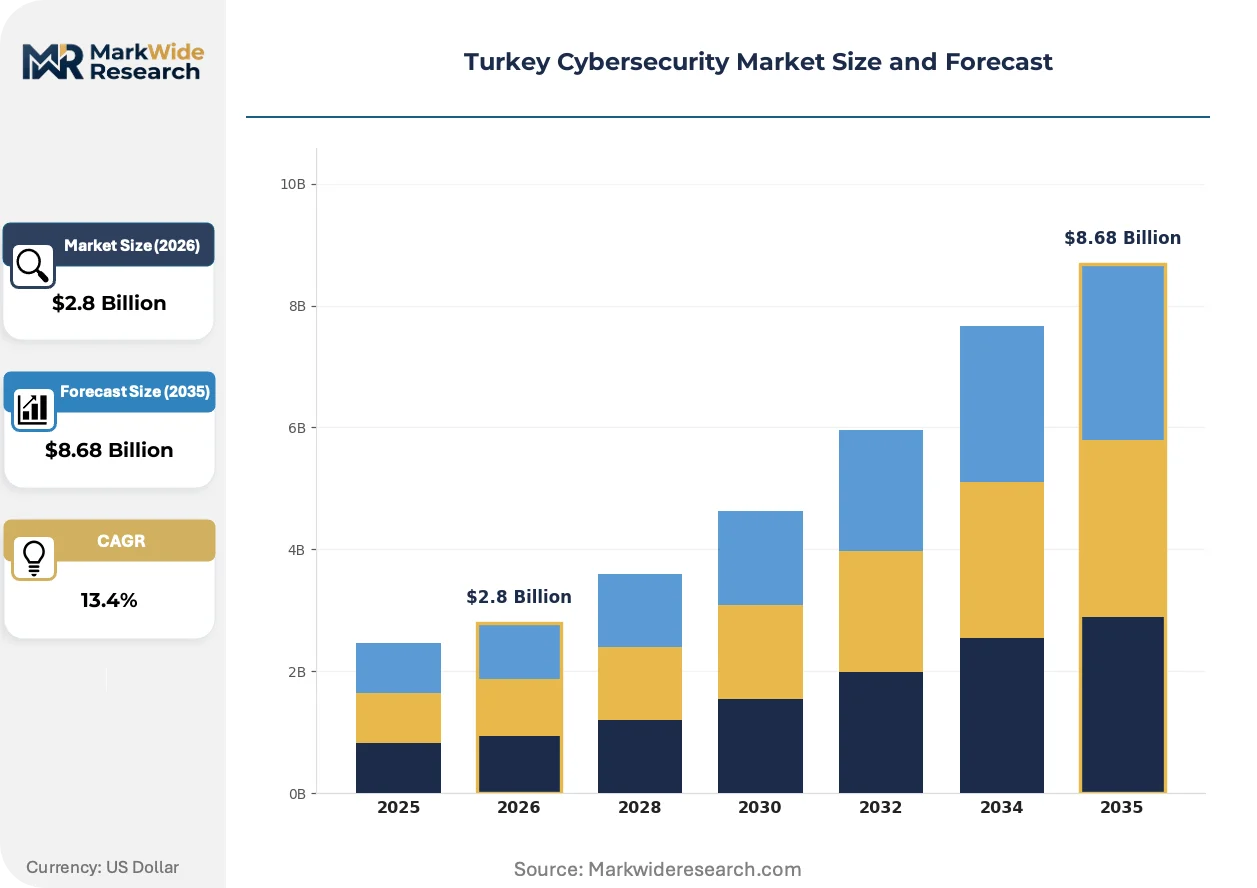
Market Dynamics
Turkish financial institutions are accelerating zero-trust architecture procurement as KVKK mandates tighten breach notification timelines, forcing infrastructure rebuilds across Istanbul's banking corridor.
Growth Catalysts
- KVKK Breach Notification Mandates:The Personal Data Protection Authority's strict reporting timelines compel enterprises to upgrade detection and response capabilities, driving sustained demand for managed security services.
- Hybrid Cloud Migration:Turkish banks are migrating core systems to hybrid architectures, expanding the attack surface and requiring cloud-native security specialization across the sector.
- Istanbul Banking Corridor Concentration:Geographic clustering of financial institutions in Turkey's commercial capital creates dense procurement pools and accelerates technology diffusion among peer institutions.
Market Restraints
- Domestic Data Center Requirements:KVKK and BTK data localization obligations force foreign vendors to establish Turkish facilities, raising capital barriers and extending market entry timelines.
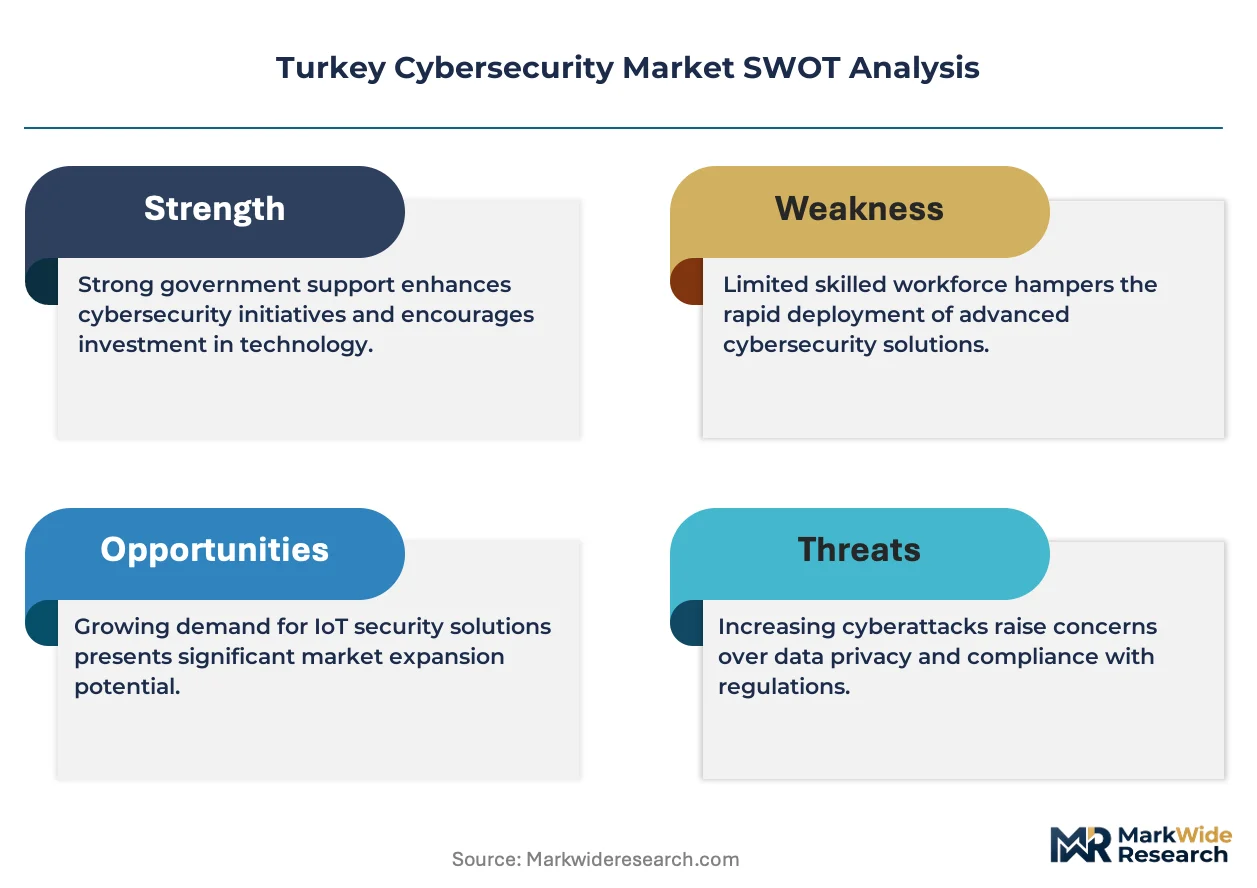
- Legacy Infrastructure Inertia:State-owned enterprises maintain extensive perimeter firewall installations, slowing the transition to integrated threat detection platforms and compressing near-term addressable market.
- EU NIS2 Divergence Risk:Evolving European cybersecurity standards create compliance complexity for Turkish exporters serving European clients, fragmenting product certification requirements.
Strategic Opportunities
- Anatolian Mid-Market Expansion:Manufacturers outside Istanbul lack in-house Security Operations Center capabilities, creating concentrated margin pools for managed security services providers.
- Zero-Trust Architecture Convergence:Integration of identity management with network segmentation enables vendors to displace legacy perimeter approaches in financial services procurement cycles.
- Telecom Operator Cloud Specialization:Turkish carriers are building sovereign cloud infrastructure, opening procurement channels for cloud-native security platforms tailored to regulated workloads.
Industry Challenges
- Security Operations Talent Scarcity:Mid-sized firms cannot staff 24/7 monitoring functions, forcing reliance on outsourced providers and constraining internal capability building.
- Legacy-Modern Integration Complexity:Hybrid architectures require orchestration between decades-old state enterprise systems and cloud-native platforms, extending deployment timelines and raising project risk.
- Certification Timeline Compression:KVKK mandates and EU Cybersecurity Act requirements impose overlapping compliance deadlines, straining vendor certification resources and delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Cybersecurity Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.68 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Network Security, Application Security, Cloud Security, Endpoint Security Service Type: Consulting, Managed Security Services, Incident Response, Training End User: Government, Healthcare, Financial Services, Telecom Deployment: On-Premises, Cloud-Based, Hybrid, Community Cloud |
| Companies Covered | ADEO Group, Cisco Systems, Inc., Palo Alto Networks, Inc., Fortinet, Inc., Check Point Software Technologies Ltd., Trend Micro Inc., Kaspersky Lab, IBM Security, McAfee Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Cybersecurity Market Trends and Innovations
Automation and sovereignty requirements are actively reshaping how Turkish enterprises architect security, with regulatory pressure and cloud migration converging to transform procurement patterns.
Extended detection and response platforms aggregate telemetry across endpoints, networks, and cloud workloads into unified analysis pipelines. Mid-market manufacturers in Anatolia are adopting these systems faster than legacy SIEM replacements, seeking to compress incident response timelines without expanding headcount. This technology is displacing siloed point-product procurement that dominated Turkish enterprise security spending through the past decade.
KVKK has aligned enforcement mechanisms with EU GDPR adequacy requirements, creating extraterritorial compliance obligations for data processors. The regulation now mandates documented data flow mapping and processor accountability chains, forcing vendors to restructure service delivery models. Financial institutions in Istanbul are responding by demanding contractual data residency guarantees and audit rights that exceed standard commercial terms.
Enterprise buyers are unbundling managed security services from hardware procurement, separating detection platform licensing from 24/7 monitoring contracts. Turkish banks are leading this shift, using competitive tender processes to pit specialized managed security service providers against traditional vendor-managed offerings. This pattern is most visible in Istanbul's fintech corridor, where procurement teams prioritize operational flexibility over single-source accountability.
Turkey Cybersecurity Market Segmentation
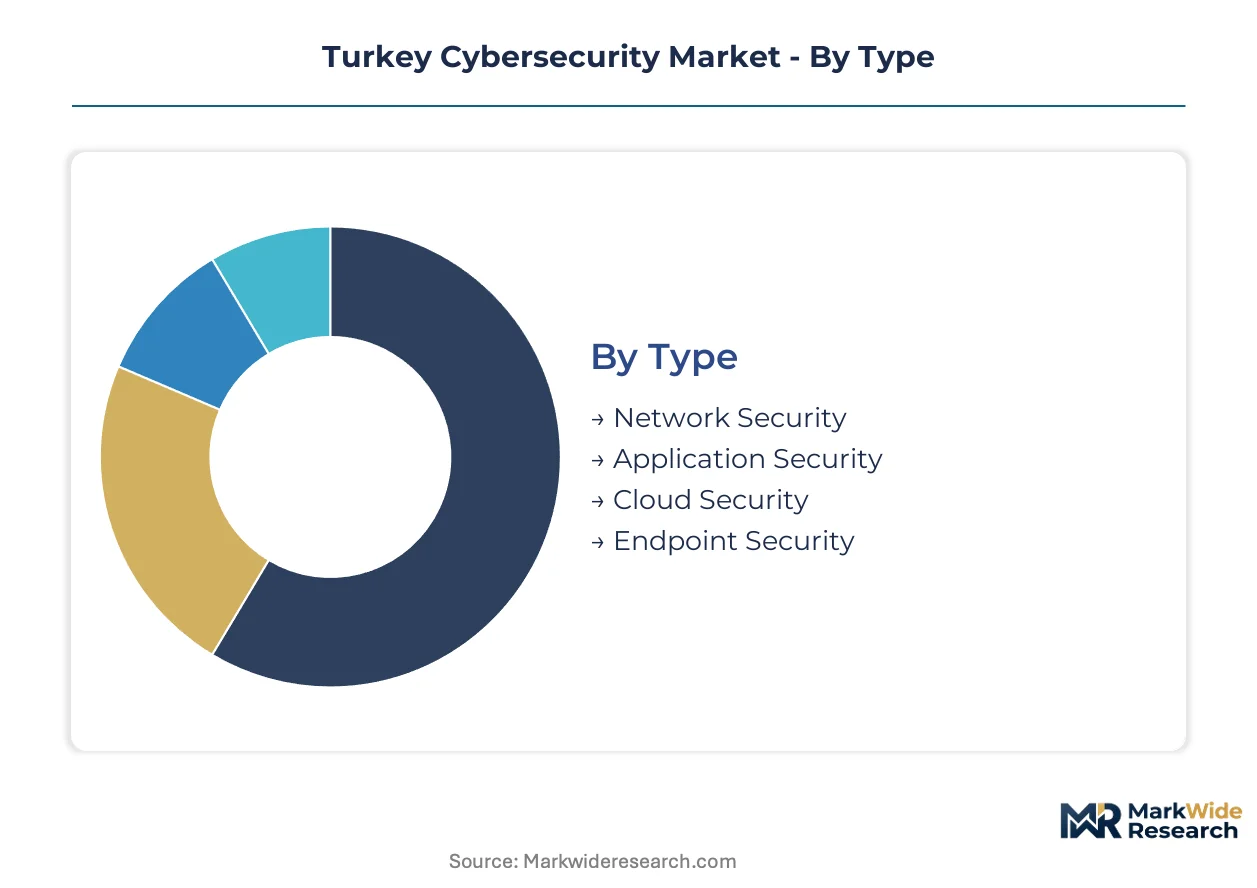
Turkish cybersecurity procurement patterns diverge sharply across infrastructure layers, with legacy state enterprises anchoring hardware demand while fintech clusters drive cloud-native adoption. Segment boundaries are blurring as KVKK mandates force integration between detection platforms and managed service delivery.
Type:
Network Security and Cloud Security flow through distinct channel architectures—hardware distributors dominate the former, while direct vendor relationships and systems integrators control the latter.
- Network Security:Perimeter firewalls, intrusion detection systems, and segmentation appliances protect on-premises infrastructure. State-owned enterprises in Ankara maintain extensive installed bases, though KVKK breach notification timelines are forcing selective upgrades toward integrated platforms.
- Cloud Security:Cloud-native platforms secure hybrid and multi-cloud workloads through policy orchestration and continuous compliance monitoring. Istanbul's banking corridor represents the concentrated demand pool as institutions migrate core systems.
- Application Security:Code scanning, runtime protection, and API security tools address software-layer vulnerabilities. Turkish fintech startups are prioritizing DevSecOps integration to accelerate deployment cycles.
- Endpoint Security:EDR and XDR platforms aggregate telemetry from devices across distributed workforces. Mid-market manufacturers in Anatolia are adopting these faster than full SIEM replacements.
Network Security dominates installed base. Cloud Security is where expansion concentrates.
Service Type:
Margin structures vary dramatically—consulting commands premium pricing in Istanbul, while managed services generate recurring revenue across Anatolian manufacturing belts.
- Managed Security Services:24/7 SOC operations, threat hunting, and managed detection and response delivered through subscription models. Mid-sized firms outside Istanbul lack internal staffing capabilities, creating concentrated demand pools.
- Consulting:Risk assessment, architecture design, and compliance readiness services. Financial institutions in Istanbul's banking corridor use competitive tender processes to separate advisory from implementation.
- Incident Response:Retained breach response, forensic investigation, and recovery orchestration. KVKK's strict notification timelines are elevating procurement priority.
- Training:Security awareness programs, certification preparation, and simulation exercises. Public sector mandates are expanding addressable market beyond enterprise.
Managed Security Services anchors recurring revenue. Consulting is climbing the fastest as compliance complexity deepens.
End User:
Procurement sophistication stratifies sharply—financial services demand contractual data residency guarantees while healthcare lags in detection capability maturity.
- Financial Services:Banks, insurers, and fintech operators with zero-trust architecture mandates. Istanbul's geographic clustering accelerates technology diffusion through peer institution benchmarking.
- Government:Central ministries, regional administrations, and critical infrastructure operators. BTK data localization requirements shape vendor selection criteria.
- Telecom:Mobile and fixed-line carriers building sovereign cloud infrastructure. Turkcell and Vodafone Turkey are opening procurement channels for cloud-native platforms.
- Healthcare:Hospitals, clinics, and health information exchanges with legacy system constraints. Patient data protection requirements are outpacing security investment cycles.
Financial Services leads procurement sophistication. Telecom is gaining share fastest as sovereign cloud buildouts accelerate.
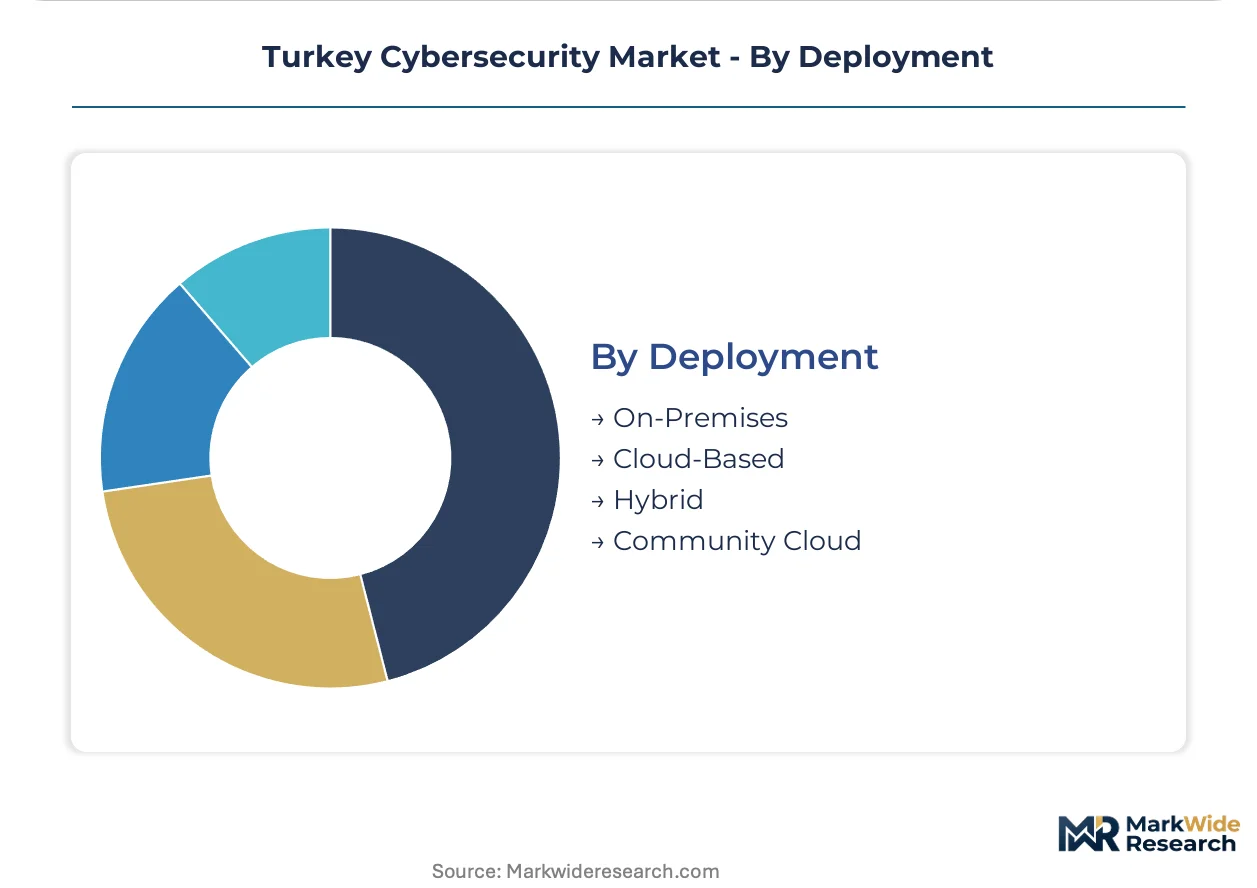
Deployment:
Supply concentration dictates channel strategy—on-premises deployments flow through hardware distributors, while cloud-based solutions favor direct vendor relationships.
- On-Premises:Hardware appliances and perpetual-licensed software operating within customer data centers. State-owned enterprises maintain extensive legacy commitments.
- Cloud-Based:SaaS-delivered security platforms with consumption-based pricing. Turkish banks are unbundling these from managed service contracts to preserve operational flexibility.
- Hybrid:Orchestrated security across on-premises and cloud workloads. Integration complexity between decades-old state systems and cloud-native platforms extends deployment timelines.
- Community Cloud:Shared infrastructure serving regulated industry verticals with common compliance requirements. Healthcare and public sector consortia are evaluating shared SOC models.
On-Premises retains largest installed base. Hybrid is expanding most quickly as migration timelines extend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey exports cybersecurity services and compliance expertise to European banking clients navigating GDPR-KVKK adequacy requirements, creating a cross-border procurement corridor anchored in Istanbul's fintech infrastructure.
Marmara Region
Istanbul's banking corridor concentrates zero-trust architecture demand as financial institutions rebuild infrastructure under KVKK breach notification mandates. The Personal Data Protection Authority enforces strict reporting timelines. Turkcell and Vodafone Turkey anchor sovereign cloud buildouts in the metropolitan zone, opening procurement channels for cloud-native security platforms.
Central Anatolia
Ankara hosts state-owned enterprises maintaining extensive perimeter firewall installations that KVKK compliance deadlines are forcing toward selective upgrades. BTK data localization requirements shape vendor selection criteria for government ministries. The capital's defense and aerospace clusters generate classified workload security demand distinct from commercial banking patterns.
Aegean Region
Izmir's manufacturing belt drives managed security services adoption as mid-sized firms lack 24/7 Security Operations Center staffing. The country's national cybersecurity authority extends enforcement reach into industrial zones. Automotive and textile exporters serving EU clients face overlapping KVKK and EU Cybersecurity Act certification requirements.
Mediterranean Region
Antalya's tourism and healthcare infrastructure presents patient data protection requirements outpacing security investment cycles. Provincial hospital networks evaluate shared SOC models under community cloud procurement frameworks. The region's lagging detection capability maturity creates consulting margin pools for compliance readiness services.
Black Sea Region
Samsun and Trabzon anchor logistics and port infrastructure where operational technology security intersects with maritime regulatory compliance. Critical infrastructure operators navigate BTK incident reporting obligations for industrial control systems. The corridor's geographic distance from Istanbul concentrates demand for remote-managed detection and response capabilities.
Turkey Cybersecurity Market Competitive Landscape
Listed leaders compete with private specialists across channel architecture, with publicly traded network security vendors facing agile domestic managed services providers in Anatolian manufacturing belts. The vendor base stratifies into three tiers: global platform providers with Turkish data center presence, regional systems integrators bundling detection platforms with compliance consulting, and specialized managed security services operators. Dominant competitive moves include establishing domestic data center infrastructure to satisfy KVKK localization mandates and unbundling hardware procurement from 24/7 monitoring contracts to capture operational flexibility demand.
Within the global platform tier, Cisco Systems, Inc. and Palo Alto Networks, Inc. exemplify divergent channel strategies—Cisco leverages established hardware distributor relationships across Anatolia while Palo Alto anchors through direct cloud-native specialization for telecom operators. Fortinet, Inc. occupies a position bridging perimeter appliance legacy and integrated platform transition. These three listed entities represent how foreign vendors navigate capital barriers and extended market entry timelines imposed by domestic facility requirements.
| Leading Market Players |
|---|
| ADEO Group |
| Cisco Systems, Inc. |
| Palo Alto Networks, Inc. |
| Fortinet, Inc. |
| Check Point Software Technologies Ltd. |
| Trend Micro Inc. |
| Kaspersky Lab |
| IBM Security |
| McAfee Corp. |
| Others |
Pricing and Supply Chain Analysis
KVKK certification tiers gate vendor qualification and price differentiation simultaneously, forcing foreign suppliers to absorb domestic data center costs while Turkish buyers unbundle detection platforms from monitoring contracts to compress total cost of ownership.
Pricing Analysis
Next-generation cloud-native security platforms command premiums over legacy perimeter appliances and emerging AI-augmented threat detection systems. SaaS-tiered subscription models dominate Turkish procurement, with price differentiation resting on KVKK compliance certification grade and data residency guarantee depth. Cost compression in mid-market managed services is intensifying because Anatolian manufacturers lack internal Security Operations Center staffing and pit multiple providers against each other. Financial institutions in Istanbul's banking corridor exhibit lowest price sensitivity, prioritizing contractual audit rights over unit economics.
Supply Chain Analysis
Israel and the United States anchor threat intelligence feed production, while Ireland and Germany supply compliance consulting expertise for KVKK-GDPR adequacy alignment. Hardware appliances draw from Taiwan and China for chipset fabrication, with software development concentrated in India and Eastern European engineering hubs. Single-source vulnerability concentrates in Israeli threat intelligence APIs, where geopolitical disruption could sever real-time indicator feeds. Distribution runs through Anatolian hardware distributors for on-premises deployments and direct vendor relationships for cloud-native platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's cybersecurity market is recovering from compliance-driven infrastructure overbuild, with KVKK enforcement cycles now normalizing procurement patterns after the initial mandate surge.
For Market Incumbents: Consolidate channel control across Anatolian manufacturing belts by acquiring specialized managed security services operators before domestic competitors scale. Cisco Systems and Palo Alto Networks should deepen data center vertical integration in Istanbul to defend against emerging regional systems integrators bundling detection with compliance consulting. Certification investment in KVKK-EU Cybersecurity Act dual compliance represents the critical defensive lever.
For New Entrants and Emerging Players: KVKK fast-track certification for cloud-native platforms opens procurement channels in Istanbul's fintech corridor where incumbent relationships have decayed through contract unbundling. White-space concentrates in Anatolian mid-market manufacturing, where Security Operations Center talent scarcity forces reliance on outsourced providers. Go-to-market should target community cloud consortia in healthcare and provincial government, where shared infrastructure models reduce customer acquisition costs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pure-software security platforms as cloud delivery eliminates hardware inventory requirements, improving cash conversion cycles. Long-term viability favors vendors with recurring revenue depth in managed detection and response rather than transactional appliance sales. Acquisition target archetype: domestic Turkish managed security services operators with KVKK-certified delivery infrastructure. The signal to watch is Turkcell and Vodafone Turkey sovereign cloud procurement timelines, which will concentrate demand for compliant security orchestration.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Establishment | KVKK localization mandates force foreign vendors to absorb capital barriers or exit procurement pools. |
| Zero-Trust Architecture Integration | Identity-network convergence displaces legacy perimeter firewalls in Istanbul banking corridor rebuilds. |
| Managed Services Unbundling | Turkish banks separate detection licensing from 24/7 monitoring to preserve operational flexibility. |
| Anatolian Channel Partnership | Mid-market manufacturers outside Istanbul lack internal SOC capabilities, creating concentrated margin pools. |
| Dual Certification Investment | EU Cybersecurity Act alignment with KVKK requirements fragments vendor resource allocation across compliance deadlines. |
Research Methodology
The analysis maps network security hardware, cloud-native platforms, managed security services, and compliance consulting segments, each validated through chief information security officers, procurement directors at financial institutions, channel partners across Anatolia, and KVKK regulatory affairs specialists. Primary interviews combined with secondary validation from BTK enforcement disclosures, KVKK breach notification databases, hyperscaler Turkish region capex announcements, and EU Cybersecurity Act implementation timelines. Bottom-up segment sizing triangulated against top-down market aggregation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical regulatory intensity, and geographic procurement cluster. CAGRs derived from segment-level growth trajectory analysis incorporating compliance deadline phasing, cloud migration velocity, and managed services adoption curves. Industry-specific forecast inputs include KVKK enforcement staffing expansion and Turkcell sovereign cloud buildout timelines.
Underlying assumptions cover KVKK enforcement continuity, EU Cybersecurity Act adequacy maintenance, and Istanbul banking corridor infrastructure replacement cycles, with deviation risk concentrated in regulatory timeline compression and geopolitical disruption to threat intelligence feed sources. Recalibration cycles align with material shifts in KVKK penalty enforcement patterns and EU-Turkey data adequacy negotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Micro-Segmentation Solutions Market
Cybersecurity
Europe Software Defined Perimeter Market
Cybersecurity
Latin America IoT Security Market
Cybersecurity
Kuwait Cybersecurity Market
Cybersecurity
Global Container and Kubernetes Security Market
Cybersecurity
Middle East Cybersecurity Market
Cybersecurity
Application Programming Interface Security Market
Cybersecurity
Global Data Exfiltration Market
Cybersecurity
AI in Cybersecurity Market
Cybersecurity
Global Dynamic Data Masking Market
Cybersecurity
Enterprise Firewall Market
Cybersecurity
Sweden Cybersecurity Market
Cybersecurity
Secure Socket Layer (SSL) Certification Market
Cybersecurity
LAMEA Deception Technology Market
Cybersecurity
France Cybersecurity Market
Cybersecurity
Network Security Market