
 Pulp Roll Cradles Market | 2026-2036
Pulp Roll Cradles Market Size, Share, and Industry Trends Forecast 2026-2036
Pulp Roll Cradles Market Outlook
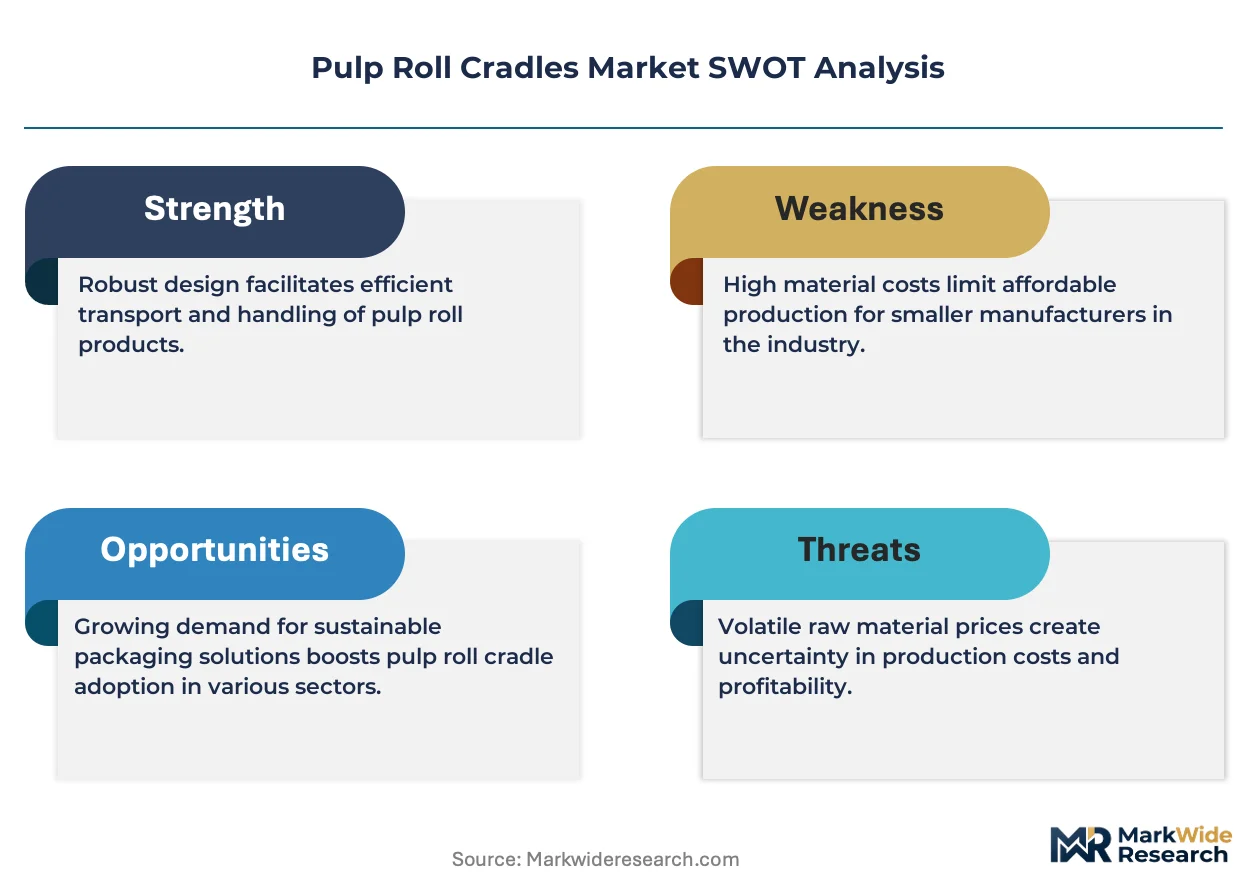
The EU Green Deal is expanding requirements for circular packaging materials across European paper and board supply chains. Henry Molded Products leverages its specialization in molded fiber engineering to serve integrated pulp producers with custom cradle geometries. Rollguard Products anchors its position through geographic dominance in North American paper logistics corridors. Pucel Enterprises differentiates via product specialization in adjustable cradle systems for variable roll diameters.
Pulp roll cradles are structural support devices manufactured from molded fiber, corrugated paperboard, or engineered plastics, designed to secure cylindrical paper rolls during transit and storage with load ratings typically spanning 500 to 5,000 pounds per unit. Their primary purpose centers on preventing edge crush, moisture transfer, and lateral displacement across intermodal shipping networks. Standard cradles occupy the mature volume tier where paper mills enforce strict interchangeability protocols, while heavy-duty variants capture concentrated margin pools in specialty grade transport. Composite materials represent the fastest-growing segment as converters seek weight reduction without sacrificing compressive strength.
The EPA oversees recyclable content claims in the United States, while REACH governs chemical restrictions in European fiber binders, and ISO 186 sets paper roll dimension tolerances that cradle manufacturers must accommodate. These frameworks collectively shape product certification requirements and cross-border market access conditions. Stakeholders must monitor evolving extended producer responsibility mandates that could redefine cradle-to-cradle accountability in paper logistics.
Market Dynamics
The EU Green Deal's circular packaging mandates are forcing paper mills to abandon plastic containment systems, redirecting capital toward molded fiber cradle procurement and reshaping supplier qualification criteria across European logistics networks.
Growth Catalysts
- REACH chemical restrictions:European fiber binder formulations now exclude formaldehyde-based adhesives, accelerating demand for compliant molded fiber cradles in German and French paper corridors.
- Corrugated packaging plant expansion:Integrated producers in the US Southeast are consolidating roll handling standards, driving volume contracts for interchangeable cradle geometries.
- Recyclable load containment:Walmart and Amazon fulfillment centers now mandate cradle-to-cradle packaging scores, pulling molded fiber solutions into e-commerce supply chains.
Market Restraints
- Old corrugated container price volatility:OCC feedstock costs for molded fiber production swing with Chinese import quotas, compressing margin stability for mid-tier suppliers.
- Polypropylene substitution threat:Reusable plastic cradles retain cost advantage in closed-loop brewery and textile roll applications where return logistics are captive.
- ISO 186 tolerance compliance:Dimensional variance requirements for paper rolls force cradle manufacturers to maintain six sigma production controls, elevating quality system costs.
Strategic Opportunities
- Extended Producer Responsibility tailwinds:France's AGEC law imposes packaging waste penalties on non-recyclable systems, creating preferential procurement channels for fiber-based cradles.
- India paper logistics modernization:West Bengal and Maharashtra state industrial corridors are installing automated roll handling systems, opening specification windows for standardized cradle formats.
- Composite material convergence:Bamboo-pulp hybrid fibers combined with bio-based binders are enabling lighter cradles that retain compressive ratings, targeting air freight weight restrictions.
Industry Challenges
- Mold design engineering scarcity:Finite talent pools for pulp molding die engineering constrain rapid product customization for specialty roll diameter ranges.
- Legacy ERP integration friction:Paper mill procurement systems require EDI compatibility that smaller cradle suppliers lack, elongating sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulp Roll Cradles Market |
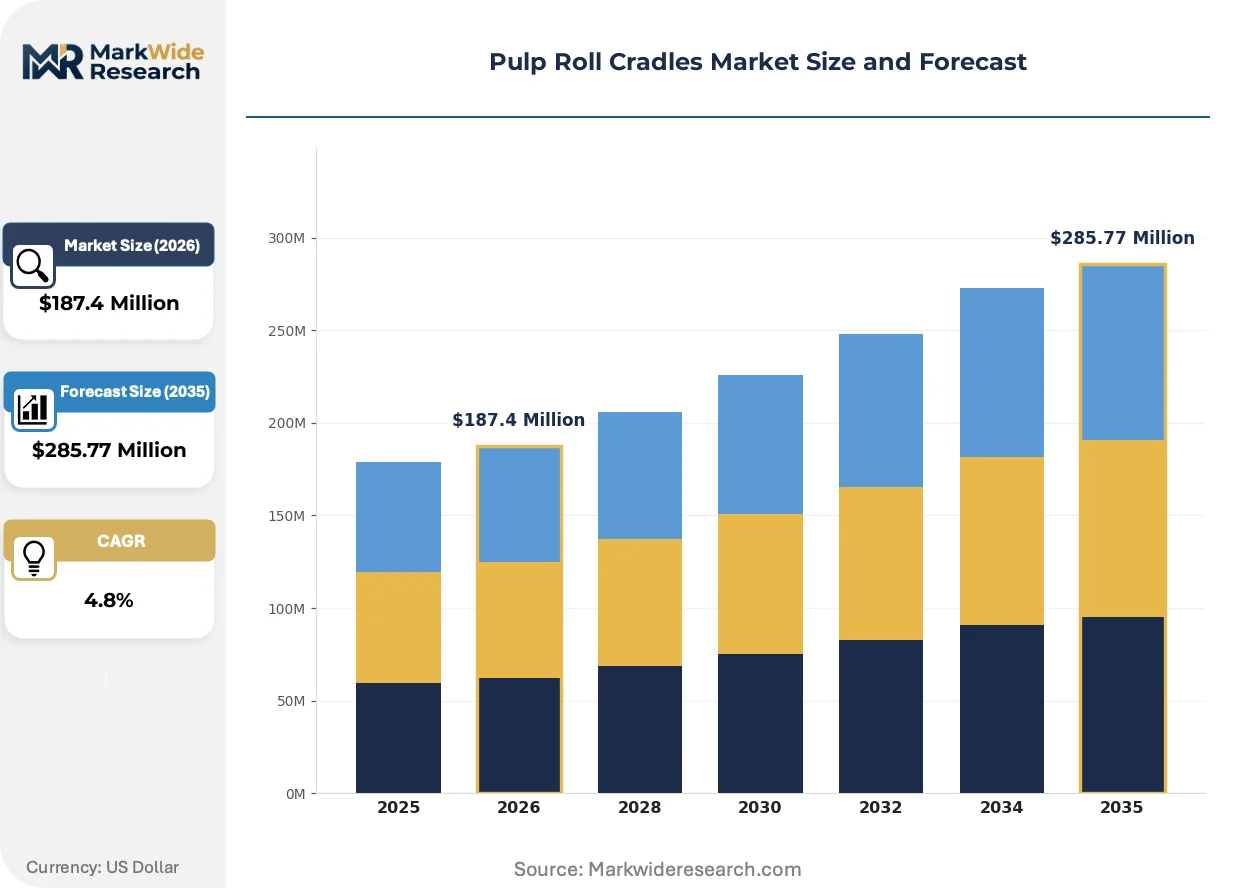
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cradles, Adjustable Cradles, Heavy-Duty Cradles, Lightweight Cradles Material: Metal, Plastic, Composite, Wood Industry Vertical: Pulp & Paper, Packaging, Printing, Textile End User: Manufacturers, Distributors, Retailers, Exporters |
| Companies Covered | Arrows Up, Henry Molded Products, Pucel Enterprises, Rollguard Products, Birch Brothers Southern, Fibreform Containers, Spectrum Bags Incorporated, Fenner Dunlop Engineered Conveyor Solutions, Associated Machine Design, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulp Roll Cradles Market Strategic Shifts
Material science breakthroughs and regulatory sequencing are compressing product lifecycles, forcing cradle manufacturers to synchronize R&D roadmaps with evolving paper mill automation standards and cross-border chemical compliance frameworks.
Cellulose nanofiber reinforcement is rewriting compressive strength benchmarks for molded fiber cradles. Specialty paper producers in Finland and Sweden are piloting these ultra-lightweight units for air-freighted art paper rolls. The technology is compressing weight-based shipping premiums that previously favored plastic alternatives.
The EPA's recyclable content verification protocols are tightening substantiation requirements for molded fiber environmental claims. US paper mills now demand third-party chain-of-custody documentation that traces fiber sourcing to post-consumer waste streams. Integrated producers with captive recycling operations are internalizing cradle supply to capture compliance arbitrage.
Buyer consortium purchasing is consolidating cradle procurement decisions across multi-mill paper groups. Regional cooperative buying organizations in the US Midwest and Nordic clusters are displacing individual mill sourcing autonomy. This concentration is most visible in Germany, where Verband Deutscher Papierfabriken members negotiate standardized cradle specifications through collective tenders.
Pulp Roll Cradles Market Segmentation
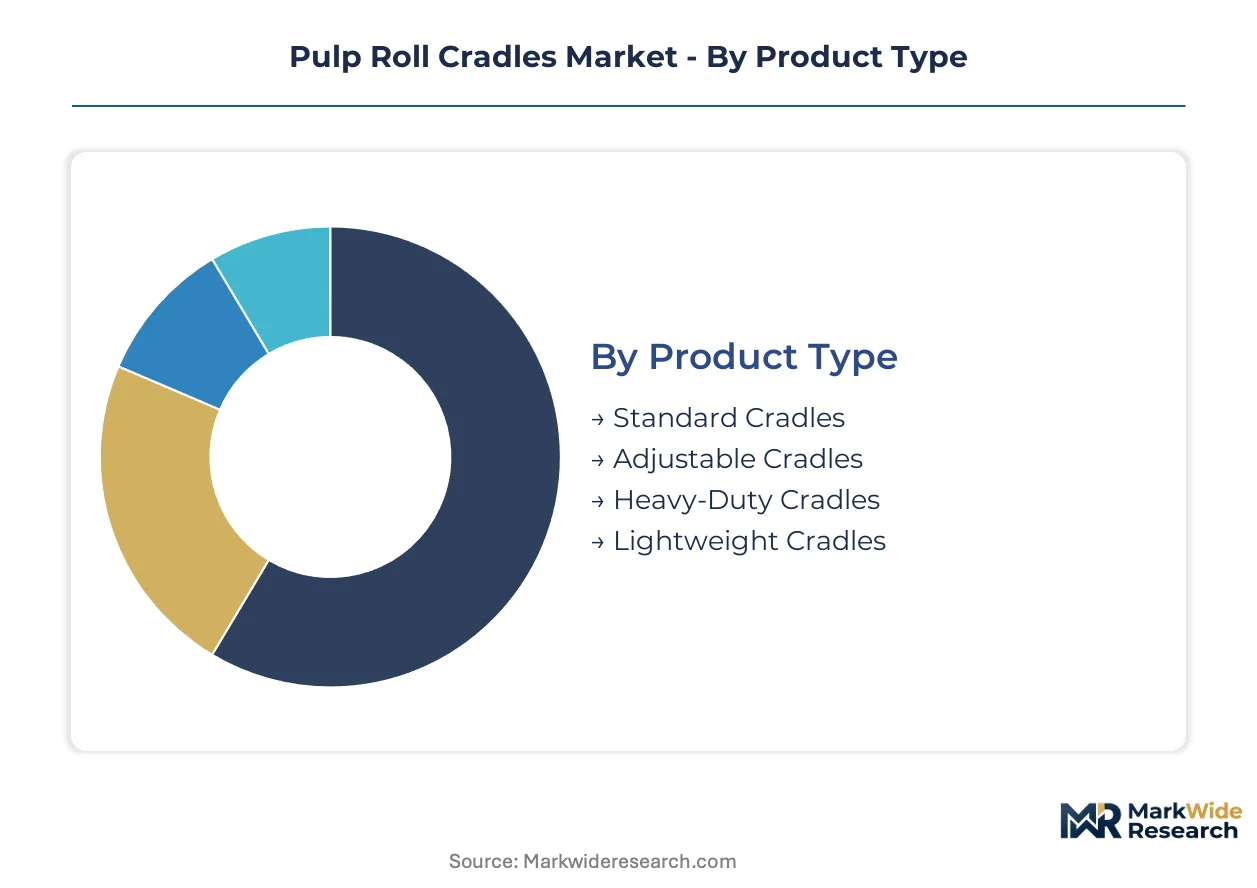
Pulp roll cradle procurement decisions hinge on load rating precision, material compliance mandates, and automation compatibility. Paper mills segment their supplier portfolios across four dimensions that directly map to logistics network configuration and circular packaging obligations.
Product Type:
Supply concentration in standard cradles reflects paper mill insistence on interchangeability protocols across multi-facility networks.
- Standard Cradles:Fixed-geometry molded fiber units designed for 40-inch to 60-inch diameter rolls dominate procurement volumes in Germany's integrated pulp-to-paper corridors. Verband Deutscher Papierfabriken collective tenders enforce dimensional uniformity that locks in supplier relationships. REACH-compliant fiber binders now exclude formaldehyde-based adhesives, elevating qualification barriers.
- Heavy-Duty Cradles:Reinforced structures rated above 5,000 pounds per unit capture margin concentration in specialty grade transport. Finnish art paper producers pilot these for air-freighted high-value rolls where compressive strength outweighs weight premiums.
- Adjustable Cradles:Variable-diameter systems accommodate mixed roll inventories without SKU proliferation. Pucel Enterprises anchors its market position through proprietary adjustment mechanisms.
- Lightweight Cradles:Sub-500-pound rated units target e-commerce fulfillment applications where single-roll handling dominates.
Today's leader: Standard Cradles. Tomorrow's challenger: Heavy-Duty Cradles.
Material:
Cost tier stratification separates premium composite formulations from commodity molded fiber volumes.
- Composite:Bamboo-pulp hybrid fibers combined with bio-based binders enable weight reduction without sacrificing compressive ratings. These formulations are climbing the fastest as converters target air freight restrictions and Walmart's cradle-to-cradle packaging mandates.
- Metal:Steel and aluminum cradles retain captive demand in closed-loop brewery applications where return logistics justify capital intensity. Polypropylene substitution threats persist in textile roll handling.
- Plastic:Polypropylene units face regulatory pressure from France's AGEC law packaging waste penalties, redirecting procurement toward fiber alternatives.
- Wood:Engineered timber cradles occupy niche positions in emerging market installations where local fiber sourcing reduces import dependency.
Composite materials command the steepest expansion trajectory. Molded fiber retains volume dominance.
Industry Vertical:
Application-specific load profiles dictate cradle specification divergence across end-use sectors.
- Pulp & Paper:Integrated producers operate the densest logistics networks, driving standardization requirements that favor high-volume cradle contracts. Henry Molded Products serves this vertical through custom geometry engineering.
- Packaging:Corrugated packaging plant expansion in the US Southeast consolidates roll handling standards, pulling interchangeable cradle geometries into volume procurement.
- Printing:Commercial print operations demand adjustable systems for variable job runs, fragmenting supplier relationships compared to mill-direct purchasing.
- Textile:Fabric roll handling retains plastic cradle preference where closed-loop return systems operate outside circular packaging mandates.
Pulp & Paper verticals anchor procurement volumes. Packaging verticals are gaining share fastest through e-commerce fulfillment integration.
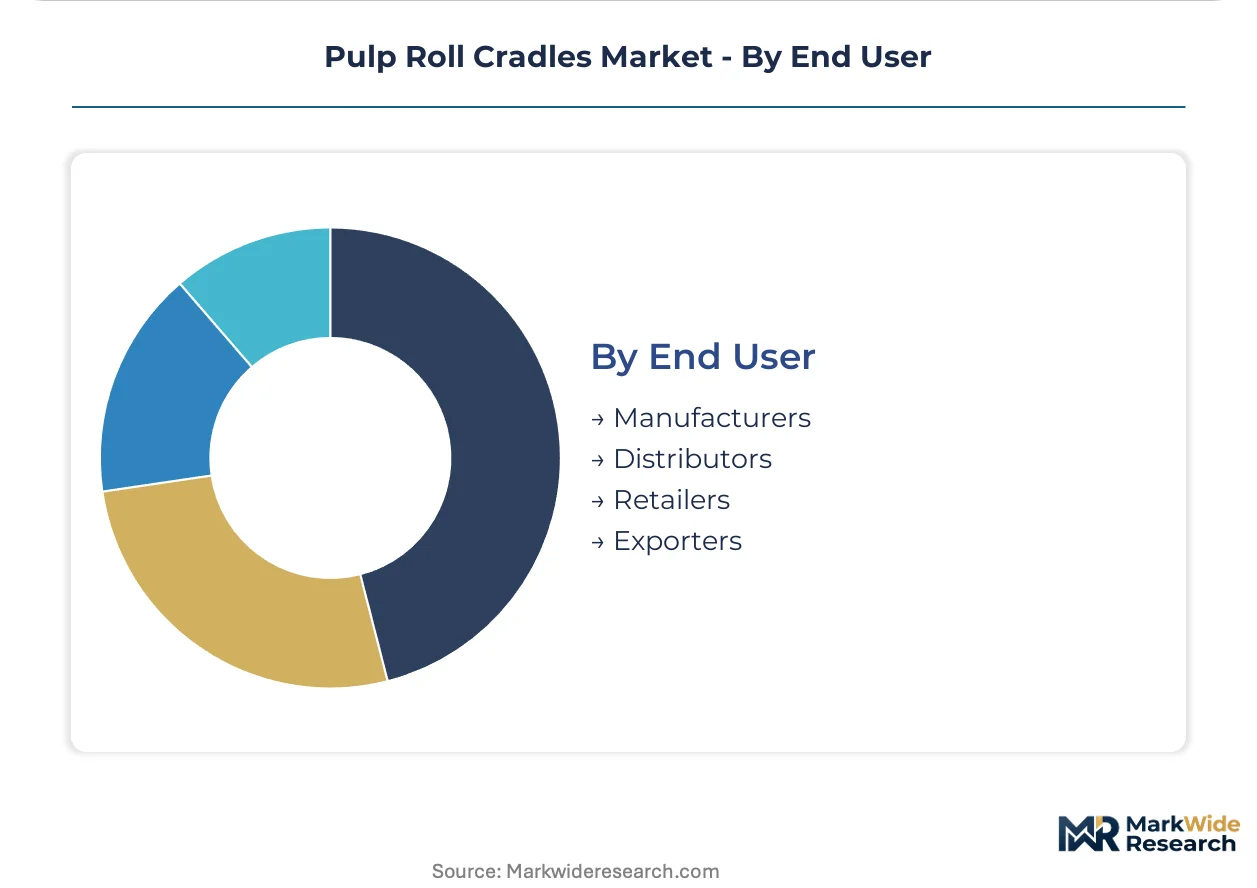
End User:
Customer type determines contract structure, with manufacturers demanding EDI integration that smaller distributors cannot support.
- Manufacturers:Paper mills enforce six sigma production controls and chain-of-custody documentation requirements that trace fiber to post-consumer waste streams. Rollguard Products anchors its position through North American paper logistics corridor dominance.
- Distributors:Third-party logistics providers prioritize SKU consolidation, favoring adjustable cradle systems that reduce inventory carrying costs.
- Retailers:Amazon and Walmart fulfillment centers mandate cradle-to-cradle packaging scores, pulling molded fiber solutions into specifications previously tolerant of plastic alternatives.
- Exporters:Cross-border shippers face ISO 186 tolerance compliance requirements that elevate quality system costs for cradle suppliers.
Manufacturers dictate specification standards. Retailers are rewriting procurement criteria through sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered molded fiber industrialization in the 1950s, establishing the engineering standards that now govern European roll handling protocols. The country's integrated pulp-to-paper producers created the template for cradle standardization that competitors worldwide still reference.
Germany
Verband Deutscher Papierfabriken collective tenders enforce dimensional uniformity across multi-facility networks. REACH chemical restrictions now exclude formaldehyde-based adhesives from fiber binder formulations. The Ruhr industrial corridor hosts dense logistics networks where standardized cradle interchangeability remains mandatory.
United States
Corrugated packaging plant expansion in the Southeast consolidates roll handling standards through volume procurement contracts. EPA recyclable content verification protocols tighten substantiation requirements for environmental claims. Wisconsin's paper mill clusters internalize cradle supply to capture compliance arbitrage from captive recycling operations.
France
AGEC law packaging waste penalties redirect procurement toward fiber-based alternatives from plastic systems. ECHA governs chemical restrictions in fiber binder formulations across the national supply base. The Grand Est region's paper logistics networks adopt standardized cradle specifications through cooperative buying organizations.
India
West Bengal and Maharashtra state industrial corridors install automated roll handling systems, opening specification windows for standardized formats. BIS standards increasingly reference ISO 186 tolerance requirements for dimensional compliance. Mumbai-Pune logistics clusters pilot molded fiber cradle adoption in containerized export operations.
Sweden
Finnish and Swedish specialty paper producers pilot cellulose nanofiber-reinforced cradles for air-freighted art paper rolls. EU Green Deal circular packaging mandates accelerate abandonment of plastic containment systems. The Nordic paper corridor concentrates R&D investment in ultra-lightweight compressive strength solutions.
Pulp Roll Cradles Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent capability matrices. The vendor base splits between integrated molders with captive pulp supply and specialized engineering houses focused on custom geometry development. Two strategic archetypes dominate: regional logistics anchors leveraging geographic corridor density, and adjustable-system specialists capturing fragmented demand from variable-diameter roll handlers. Competitive moves concentrate on EDI integration for paper mill procurement compatibility and composite material R&D partnerships with bio-based binder suppliers.
Among North American fabricators, Rollguard Products exemplifies corridor-density positioning, while Henry Molded Products occupies the custom-engineering tier for integrated pulp producers. Pucel Enterprises represents the adjustable-system specialization archetype through its proprietary diameter-variable mechanisms. These three anchors illustrate how geographic concentration, material science integration, and mechanical innovation define separable competitive vectors in cradle procurement.
| Leading Market Players |
|---|
| Arrows Up |
| Henry Molded Products |
| Pucel Enterprises |
| Rollguard Products |
| Birch Brothers Southern |
| Fibreform Containers |
| Spectrum Bags Incorporated |
| Fenner Dunlop Engineered Conveyor Solutions |
| Associated Machine Design |
| Others |
Value Chain & Pricing Dynamics
OCC feedstock costs transmit from Chinese import quota fluctuations through molded fiber cradle production tiers, compressing margin stability for mid-tier suppliers while integrated producers with captive recycling operations capture compliance arbitrage.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between paper mills and cradle suppliers, with pricing stratifying across REACH-compliant premium tiers, standard molded fiber volumes, and economy-grade plastic alternatives. Price differentiation rests on certification grade and volume scale, with six sigma ISO 186 tolerance compliance commanding premiums. Cost compression in standard cradles intensifies because OCC price volatility squeezes mid-tier suppliers. Distributors exhibit highest price sensitivity due to SKU consolidation pressures, while integrated pulp producers prioritize interchangeability over unit cost.
Supply Chain Analysis
Freight cost differentials between intermodal rail corridors and containerized ocean routes reshape supplier competitiveness across the Ruhr industrial cluster, Wisconsin paper mill networks, and US Southeast corrugated packaging corridors. Raw material sourcing draws from post-consumer OCC streams, bamboo-pulp hybrid fiber cultivation, and bio-based binder formulations. Single-source vulnerability concentrates in formaldehyde-free adhesive supply chains governed by REACH restrictions. Distribution runs through paper mill direct procurement with EDI integration requirements and third-party logistics provider channels favoring adjustable cradle SKU consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulp roll cradle procurement has shifted toward premium specifications as Walmart and Amazon mandate cradle-to-cradle packaging scores, elevating composite material solutions above commodity alternatives.
For Market Incumbents: Acquire captive pulp recycling operations to internalize OCC feedstock supply and buffer margin compression from Chinese import quota volatility. Invest in cellulose nanofiber R&D partnerships with Finnish specialty paper producers to anchor air-freight lightweighting demand. Polypropylene substitution threats in closed-loop brewery applications require defensive certification investments in bio-based binder formulations. For New Entrants and Emerging Players: Launch via e-commerce fulfillment center specifications in North American logistics corridors where cradle-to-cradle mandates displace plastic alternatives. Target India's West Bengal and Maharashtra automated roll handling installations before standardized format windows close. White-space exists in adjustable cradle systems for commercial print variable-diameter requirements where Pucel Enterprises holds limited geographic presence. For Investors and Strategic Acquirers: Consolidation pressure builds where EDI integration requirements and six sigma quality system costs exceed smaller suppliers' capital access. Long-term viability favors vertically integrated molders with captive fiber supply and custom geometry engineering capabilities. The signal to watch is buyer consortium purchasing concentration through Verband Deutscher Papierfabriken collective tenders and US Midwest cooperative buying organizations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Recycling | Captive fiber supply buffers margin compression from Chinese import quota volatility. |
| Cellulose Nanofiber R&D Partnership | Finnish art paper producers pilot ultra-lightweight cradles for air-freight weight restrictions. |
| REACH-Compliant Binder Certification | Formaldehyde-free adhesive qualification unlocks Verband Deutscher Papierfabriken collective tenders. |
| EDI Integration Investment | Paper mill procurement system compatibility shortens sales cycles against smaller competitors. |
| Adjustable Cradle Mechanism Patent | Variable-diameter systems reduce distributor SKU carrying costs in fragmented print verticals. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with paper mill procurement directors, molded fiber plant managers, corrugated packaging logistics coordinators, and REACH compliance officers with secondary validation from EPA recyclable content protocols, EU Green Deal circular packaging mandates, customs OCC trade flow data, and ISO 186 tolerance documentation. Bottom-up cradle production capacity modeling and top-down paper logistics network demand estimation provided triangulation anchors.
Segment-weighting applied product type, material formulation, industry vertical, and end-user customer type dimensions across the projection horizon. CAGRs derived from installed base replacement cycles, automation adoption curves in emerging markets, and regulatory sequencing timelines for extended producer responsibility mandates. Forecast inputs incorporated Walmart and Amazon fulfillment center specification shifts, cellulose nanofiber pilot scale-up trajectories, and buyer consortium purchasing concentration indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under OCC commodity price spike conditions or accelerated EU Green Deal enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Box and Carton Overwrapping Machines Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Carton Liners Market
Cartons
Digital Folding Cartons Market
Cartons
Brick Liquid Carton Market
Cartons
Mono Carton Market
Cartons
Metallized PET Cartons Market
Cartons
Wax Boxes Market
Cartons
Global Printed Cartons Market
Cartons
Carton Display Market
Cartons
Luxury Folding Carton Market
Cartons
End Load Cartoning Machine Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Tetrahedron Carton Market
Cartons
Cupcake Box Market
Cartons
Carton Bottle Market