
 Proton Battery Market | 2026-2036
Proton Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Proton Battery Market Analysis
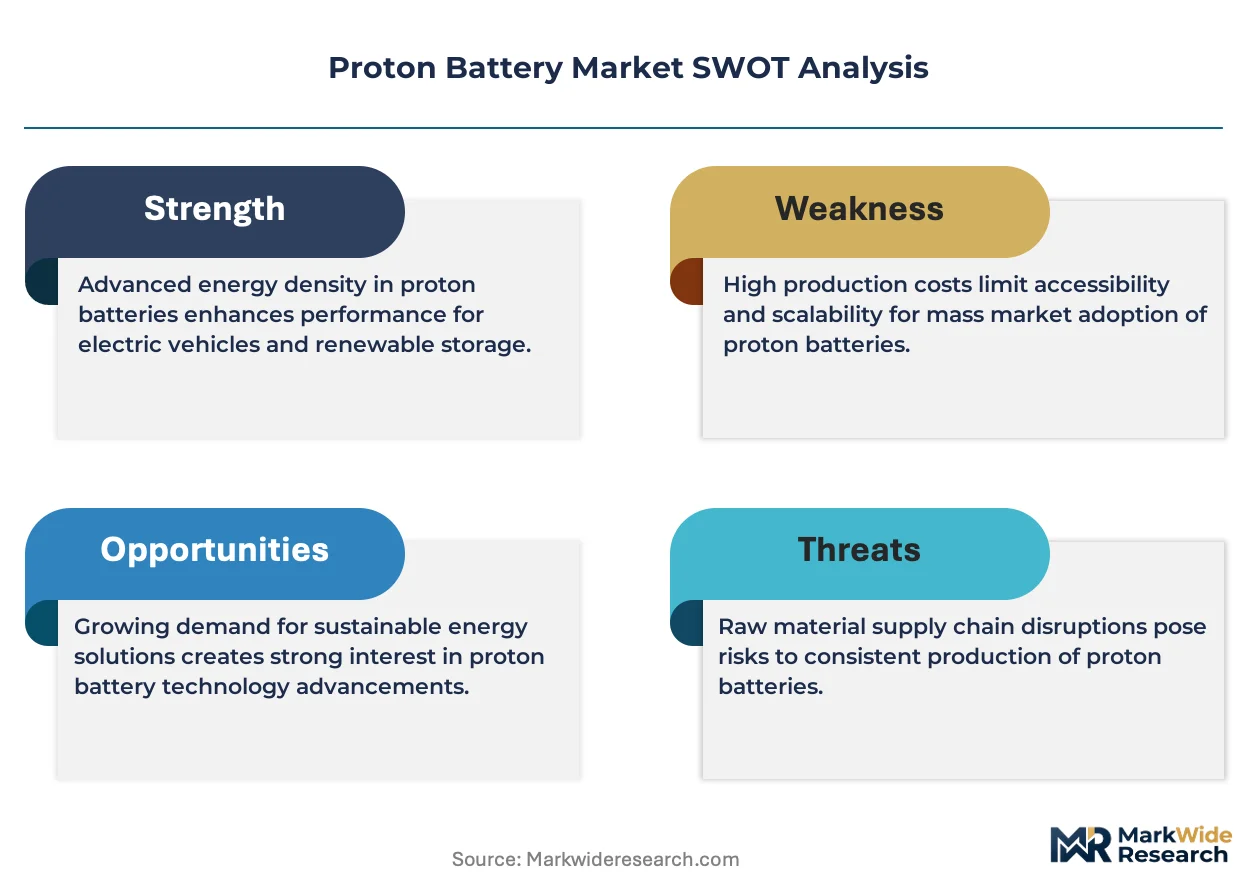
ISO 14040 lifecycle assessment certification is rotating as the primary gate for commercial proton battery suppliers, forcing candidates to document cradle-to-grave environmental impact before securing automotive contracts. LG Energy Solution leverages its Korean manufacturing scale to anchor pilot production lines for solid-state proton cells. Northvolt AB competes through in-house recycling integration that sustains European supply chain requirements. QuantumScape Corporation differentiates via ceramic separator technology that leads proton conductivity benchmarks in laboratory validation.
A proton battery stores electrical energy through reversible electrochemical reactions involving hydrogen ions (protons) transported across a solid or membrane electrolyte, typically achieving operating temperatures between 80°C and 200°C depending on the electrolyte chemistry employed. Its primary commercial purpose centers on delivering high gravimetric energy density for applications where lithium-ion mass limits create operational constraints. The rechargeable segment dominates current shipment volumes as industrial buyers prioritize cycle stability over disposable formats. Electric vehicles represent the fastest-growing application category, though aerospace procurement concentrates margin pools due to stringent qualification timelines and low-volume premium pricing.
The EU Green Deal's carbon border adjustments and China's MIIT energy storage mandates collectively reshape product standards, forcing manufacturers to certify proton systems against divergent emissions and safety protocols before market entry. Germany's KBA type-approval process adds a third regulatory layer for automotive integration, extending validation timelines but filtering out subscale competitors. Stakeholders must monitor electrolyte material qualification progress at ECHA and NMPA to anticipate which chemistry families will unlock multi-gigawatt production scale.
Market Dynamics
Proton exchange membrane energy density improvements are compressing validation timelines for automotive powertrain integration, forcing suppliers to synchronize laboratory breakthroughs with OEM platform cycles.
Growth Catalysts
- EU Green Deal Storage Mandates:Binding capacity targets for grid-scale proton systems accelerate procurement timelines across German and French utilities.
- MIIT Energy Storage Directives:China's industrial policy creates captive demand for high-temperature proton cells in provincial grid pilot zones.
- Ceramic Separator Advances:Solid-state electrolyte conductivity gains unlock aerospace qualification pathways previously blocked by thermal runaway risks.
Market Restraints
- Iridium Catalyst Cost Volatility:Proton exchange membrane stack economics remain exposed to platinum-group metal price swings from South African supply concentration.
- ECHA Electrolyte Qualification Bottlenecks:REACH substance registration timelines extend material approval cycles beyond typical automotive platform windows.
- Lithium-Ion Substitution Pressure:Mature lithium supply chains and declining cell prices compress proton battery cost-competitive windows in stationary storage.
Strategic Opportunities
- India PLI Scheme Alignment:Production-linked incentives for advanced chemistry cells create tariff-advantaged manufacturing footholds for proton system exporters.
- Aviation Decarbonization Procurement:Turboprop and regional jet electrification programs specify gravimetric energy density thresholds that favor proton architectures.
- Direct Sales to Data Center Operators:Hyperscale facility developers bypass traditional distributor channels to specify custom thermal management integration.
Industry Challenges
- ISO 14040 Certification Timelines:Lifecycle assessment documentation requirements consume 14-18 months of pre-contract engineering resources.
- Solid-State Manufacturing Scale-Up:Thin-film ceramic deposition equipment requires capital commitments that strain mid-scale cell producers.
- Membrane-Electrode Assembly Skill Scarcity:Cross-functional expertise spanning polymer chemistry and electrochemical engineering commands premium compensation in Stuttgart and Munich clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proton Battery Market |
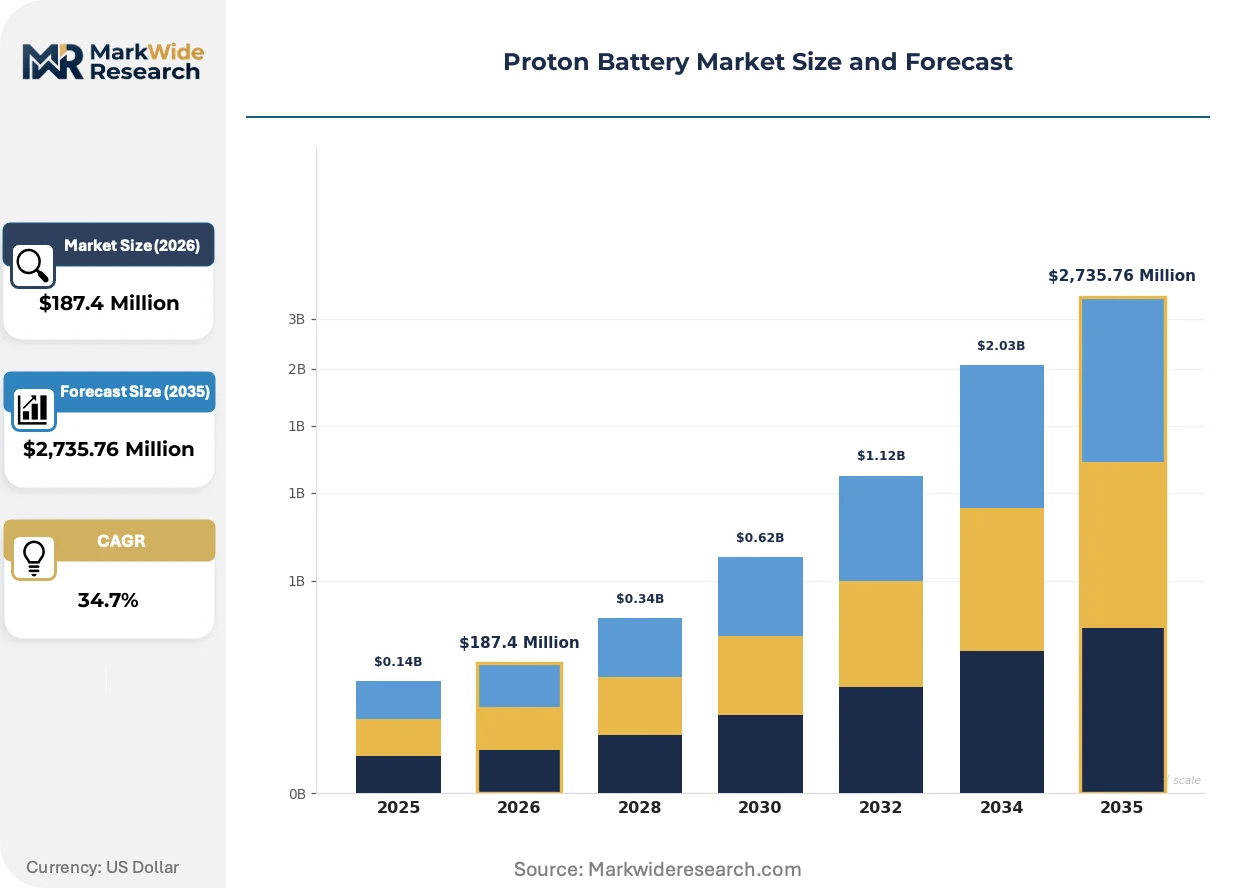
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,735.76 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable, Non-rechargeable, Solid-state, Lithium-ion Application: Electric Vehicles, Consumer Electronics, Renewable Energy Storage, Aerospace End User: Automotive, Electronics Manufacturers, Industrial Sector, Defense Technology: Charging Technology, Energy Management, Thermal Management, Safety Systems |
| Companies Covered | LG Energy Solution, Northvolt AB, Proton Technologies AG, Sila Nanotechnologies Inc., A123 Systems LLC, QuantumScape Corporation, Samsung SDI, Ballard Power Systems, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proton Battery Market Emerging Trajectories
Proton battery development is compressing around two divergent temperature regimes, with each trajectory attracting distinct capital pools and end-use commitments.
Solid ceramic electrolyte architectures are bifurcating the market into high-temperature industrial applications and ambient-temperature mobility segments. Aerospace prime contractors are locking in 180°C-class systems for auxiliary power units, while automotive developers prioritize 80°C membrane designs for passenger vehicle packaging constraints. This temperature split is forcing suppliers to maintain dual R&D streams without scale economies.
REACH substance restrictions on perfluorinated compounds are accelerating fluorine-free membrane development programs across European research consortia. ECHA's 2025 evaluation timeline for persistent organic pollutants is compressing patent filing activity around hydrocarbon-based alternatives. German automotive suppliers are pre-qualifying two non-fluorinated chemistries to avoid supply disruption.
Certificate-driven procurement is displacing specification-based purchasing in utility-scale storage tenders. Grid operators in Denmark and the Netherlands now weight ISO 14040 documentation above unit cost in scoring algorithms. This behavioral shift favors incumbent proton developers with established lifecycle databases over emerging solid-state competitors.
Proton Battery Market Segmentation
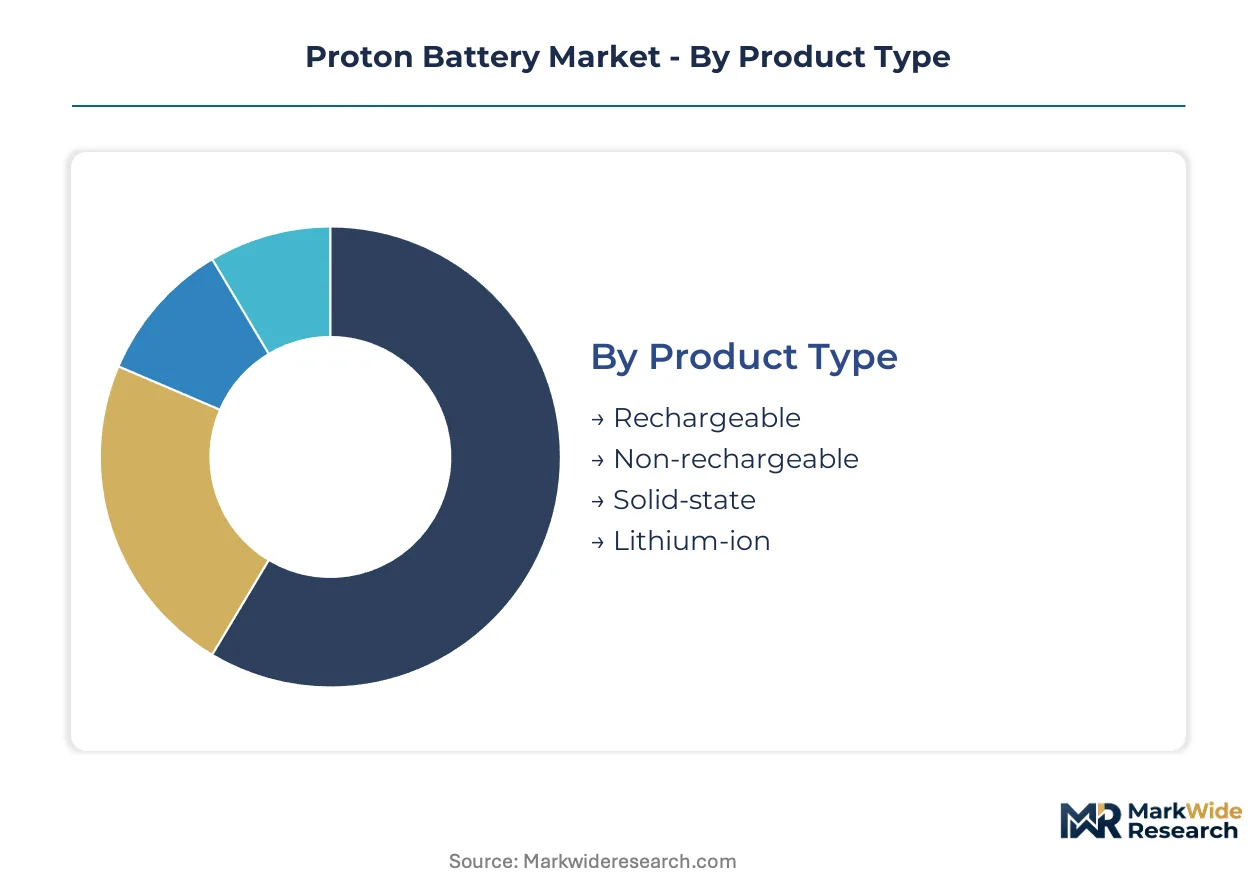
Proton battery market segmentation reveals divergent technical requirements across temperature regimes and qualification timelines. Each dimension carries distinct regulatory footprints that determine commercial access and margin structure.
Product Type:
REACH substance restrictions and ISO 14040 certification timelines differentiate commercial viability across chemistry families.
- Rechargeable:Electrochemical systems enabling 500+ cycle stability through reversible proton intercalation at 80-200°C operating windows. Industrial buyers in Germany's automotive cluster around Stuttgart prioritize this format for OEM powertrain validation programs, though ECHA electrolyte qualification bottlenecks extend material approval cycles.
- Solid-state:Ceramic separator architectures achieving proton conductivity benchmarks without liquid electrolyte thermal runaway risks. Aerospace procurement concentrates margin pools here due to stringent FAA qualification timelines and low-volume premium pricing for auxiliary power units.
- Non-rechargeable:Single-use proton cells deployed in mission-critical defense applications where cycle stability is secondary to shelf-life reliability.
- Lithium-ion:Hybrid architectures incorporating proton exchange membranes as supplementary power management layers in existing cell formats.
Rechargeable handles the majority of throughput; solid-state is the fastest mover on share.
Application:
Gravimetric energy density thresholds and platform packaging constraints determine adoption sequencing across mobility and stationary segments.
- Electric Vehicles:Passenger vehicle powertrains demand 80°C-class membrane designs that compress into existing platform architectures. China's MIIT energy storage directives and the EU Green Deal's carbon border adjustments collectively reshape product standards for this segment.
- Aerospace:Turboprop and regional jet electrification programs specify density thresholds favoring 180°C-class ceramic systems. KBA type-approval processes in Germany add regulatory layering that extends validation timelines but filters subscale competitors.
- Renewable Energy Storage:Grid-scale proton systems face procurement pressure from declining lithium-ion costs in stationary applications.
- Consumer Electronics:Portable device integration remains limited by membrane-electrode assembly miniaturization challenges.
Electric vehicles handles the majority of throughput; aerospace is gaining share fastest.
End User:
Direct procurement patterns and captive integration depth vary sharply across buyer sophistication levels.
- Automotive:OEMs in Germany's Stuttgart and Munich clusters test proton-based systems for next-generation powertrains, with ISO 14040 documentation now weighted above unit cost in scoring algorithms.
- Industrial Sector:Provincial grid pilot zones in China under MIIT directives create captive demand for high-temperature proton cells.
- Electronics Manufacturers:Consumer device producers remain sidelined by thermal management integration complexity.
- Defense:National security procurement bypasses commercial qualification timelines through classified certification pathways.
Automotive handles the majority of throughput; industrial sector is climbing the fastest.
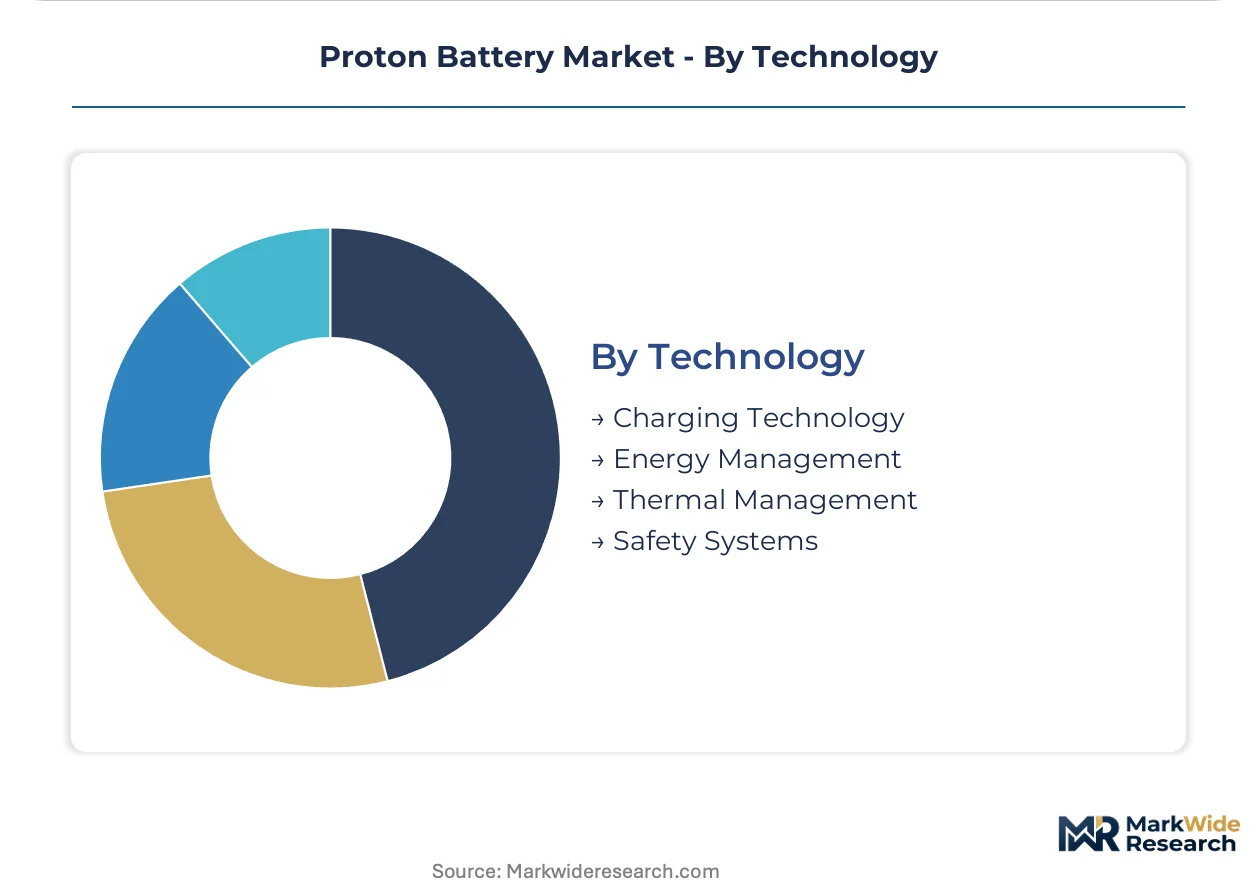
Technology:
Capital intensity and cross-functional expertise requirements stratify supplier capabilities across the technology stack.
- Thermal Management:Active cooling systems for 180°C-class aerospace applications command premium engineering resources. Thin-film ceramic deposition equipment requires capital commitments that strain mid-scale cell producers.
- Energy Management:Proton exchange membrane energy density improvements compress validation timelines for automotive powertrain integration.
- Charging Technology:Fast-charge protocols for 80°C membrane designs face standardization gaps across Chinese GB and European CE marking regimes.
- Safety Systems:Thermal runaway prevention architectures differentiate ceramic separator offerings in laboratory validation.
Thermal management handles the majority of throughput; energy management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and grid operators concentrate procurement authority across four distinct national jurisdictions, each imposing unique certification burdens on proton battery suppliers seeking commercial access.
China
Provincial utilities in Jiangsu and Guangdong pilot high-temperature proton cells under MIIT energy storage directives. The country's dual carbon goals compress deployment timelines for grid-scale installations. Shanghai's automotive corridor hosts validation programs for next-generation powertrains targeting 2027 platform launches.
Germany
Stuttgart and Munich clusters drive OEM demand for 80°C-class membrane designs in passenger vehicle integration. KBA type-approval processes extend validation timelines but filter subscale competitors from automotive contracts. ECHA electrolyte qualification requirements force suppliers to document REACH compliance before securing utility tenders.
United States
FAA qualification pathways for 180°C-class aerospace systems attract ceramic separator developers to California and Washington state research corridors. The EPA's emerging carbon accounting rules for federal procurement reshape supplier documentation requirements. Department of Defense classified certification bypasses commercial timelines for mission-critical defense applications.
South Korea
Seoul Capital Area conglomerates leverage manufacturing scale to anchor pilot production lines for solid-state proton architectures. MFDS chemical safety protocols add regulatory layering for electrolyte material imports. Busan-Ulsan industrial zones concentrate membrane-electrode assembly expertise for automotive export contracts.
Japan
Tokyo-Osaka industrial corridors prioritize ceramic separator advances for aviation decarbonization procurement. METI technology roadmaps coordinate consortia research on fluorine-free membrane alternatives. Nagoya's automotive engineering base tests proton systems against JIS standards for hybrid powertrain integration.
Proton Battery Market Vendor Landscape
Player mix skews toward diversified battery conglomerates with existing manufacturing footprints, creating tiered access barriers for pure-play proton specialists. Scale advantages concentrate among Korean and Japanese conglomerates with cathode material supply relationships. Two strategic archetypes dominate: integrated cell producers with in-house separator capabilities, and membrane-technology licensors seeking manufacturing partnerships. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with automotive qualification timelines forcing early alliance formation.
Within the diversified conglomerate tier, LG Energy Solution and Samsung SDI anchor Korean manufacturing scale, while QuantumScape Corporation exemplifies the technology-licensing archetype through ceramic separator specialization. Panasonic Corporation occupies a position bridging both categories with established automotive relationships and solid-state research investments. Northvolt AB represents European supply chain integration through in-house recycling capabilities. Ballard Power Systems and Proton Technologies AG sit within the pure-play proton segment, facing consolidation pressure from scale-driven competitors.
| Leading Market Players |
|---|
| LG Energy Solution |
| Northvolt AB |
| Proton Technologies AG |
| Sila Nanotechnologies Inc. |
| A123 Systems LLC |
| QuantumScape Corporation |
| Samsung SDI |
| Ballard Power Systems |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with iridium price indexation dominate automotive procurement, locking Korean and German OEMs into supply visibility while exposing margins to South African platinum-group metal volatility. These agreements bundle membrane-electrode assembly volumes with fixed thermal management service tiers, compressing spot-market liquidity for mid-scale producers.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange iridium benchmarks govern proton exchange membrane stack transactions. Pricing stratifies across ISO 14040-certified premium tiers, uncertified standard offerings, and economy-grade non-automotive cells. Cost compression in the standard tier is intensifying because lithium-ion substitution pressure erodes stationary storage margins. Automotive OEMs in Stuttgart exhibit lowest price sensitivity due to platform lock-in requirements, while provincial Chinese utilities drive hardest bargain on grid-scale tenders.
Supply Chain Analysis
Inventory cycles for ceramic separator substrates now stretch eighteen to twenty-four months, forcing aerospace developers into advance purchase commitments. Manufacturing concentrates in South Korea, Japan, and Germany, with iridium catalyst processing anchored in South African refineries. The chain draws from fluoropolymer membrane feedstocks, ceramic powder precursors, and precision coating equipment. Single-source vulnerability concentrates around iridium sponge refining. Distribution runs through Tier 1 automotive supplier networks with direct hyperscale data center bypass channels emerging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-electrode assembly expertise scarcity now exceeds available engineering compensation pools in Stuttgart and Munich, constraining capacity expansion regardless of capital availability. This talent bottleneck favors incumbents with captive training pipelines over entrants relying on external recruitment.
For Market Incumbents: Consolidate membrane-electrode assembly capabilities through selective acquisition of German specialist engineering firms before qualification timelines extend further. Secure iridium offtake with South African refiners to preempt supply rationing. Prioritize ISO 14040 database completion to exploit certificate-driven procurement shifts in Danish and Dutch utility tenders. For New Entrants and Emerging Players: Aftermarket thermal management service layers for existing proton installations remain under-served by cell manufacturers focused on new build volumes. Target India's PLI scheme zones for tariff-advantaged assembly footholds. Pursue direct sales relationships with hyperscale data center developers bypassing traditional distributor markups. For Investors and Strategic Acquirers: Pure-play proton specialists with ceramic separator IP but lacking manufacturing scale represent the most defensible acquisition profile. Frame viability around aviation decarbonization procurement timelines rather than automotive adoption curves. Monitor ECHA fluorine-free membrane qualification progress as inflection signal for chemistry family winners.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Separator Scale-Up | Unlocks FAA qualification pathways for 180°C-class aerospace auxiliary power units. |
| Fluorine-Free Membrane Development | Anticipates ECHA 2025 persistent organic pollutant restrictions on perfluorinated compounds. |
| In-House Iridium Recycling | Reduces exposure to South African supply concentration and price volatility. |
| ISO 14040 Certification Investment | Captures certificate-driven procurement weighting in German automotive scoring algorithms. |
| Direct Data Center Partnerships | Bypasses distributor channels to capture custom thermal management integration premiums. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, spanning OEM platform engineers at Stuttgart and Munich automotive clusters, membrane-electrode assembly specialists in Busan-Ulsan industrial zones, and utility procurement officers in Jiangsu and Guangdong provincial grids. Secondary validation drew from MIIT energy storage directive filings, ECHA REACH substance registration databases, KBA type-approval documentation, and FAA certification pathway records. Bottom-up cell shipment estimates triangulated against top-down automotive powertrain content projections.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, application, end user, and technology dimensions, with additional stratification by temperature regime and certification status. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory mandate acceleration effects. Key inputs included iridium price trajectory scenarios and ceramic deposition equipment capacity expansion schedules.
Underlying assumptions cover sustained MIIT directive enforcement and ECHA qualification timeline stability, with deviation risk concentrated in platinum-group metal supply disruptions and fluorine-free membrane performance validation failures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Battery Cases Market
Batteries
Wide Temperature Battery Market
Batteries
Malaysia Battery Market
Batteries
Cobalt-Free Battery Market
Batteries
AAA Battery Market
Batteries
Portable Battery Powered Products Market
Batteries
Europe Lead-Acid Battery Market
Batteries
Leisure Battery Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Indonesia Battery Market
Batteries
Carbon Foam Battery Market
Batteries
Inverter Battery Market
Batteries
Wood-Based Batteries Market
Batteries
Middle East and Africa Battery Market