
 Rotary Hammers Market | 2026-2036
Rotary Hammers Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Hammers Market Analytics
The gap between premium professional-grade rotary hammers and entry-level consumer units is expanding in concrete terms of motor durability, vibration control systems, and battery platform compatibility. Hilti AG anchors its position through fleet management services and direct-to-contractor channels that lock in recurring revenue. Robert Bosch GmbH leverages its battery ecosystem strategy to cross-sell cordless rotary hammers to existing power tool users. Makita Corporation competes on breadth, sustaining coverage across compact renovation units through extra-large demolition rigs.
Rotary hammers are percussive drilling tools that combine rotational motion with hammering action to penetrate concrete, masonry, and stone, typically delivering impact energy measured in joules and utilizing either electro-pneumatic or mechanical hammering mechanisms. Cordless rotary hammers with brushless motor technology are capturing the fastest growth trajectory as lithium-ion battery platforms extend runtime and cut weight for overhead applications. Heavy-duty rotary hammers with SDS Max interfaces dominate margin pools in demolition and infrastructure maintenance, while compact cordless units lead volume in residential renovation where maneuverability trumps raw power.
OSHA vibration exposure limits in the United States and EU machinery directives under CE marking requirements in Europe are forcing manufacturers to redesign handles and isolate percussion mechanisms to reduce hand-arm vibration syndrome risks. The EPA and equivalent European regulators scrutinize battery disposal chains, shaping aftermarket service obligations and recycling partnerships. Buyers and suppliers must monitor how cordless platform wars and tightening ergonomic standards reshape which technology investments yield durable competitive separation.
Market Dynamics
The transition from corded to cordless rotary hammers is compressing replacement cycles as lithium-ion battery platforms mature and construction contractors prioritize jobsite mobility over peak power output.
Growth Catalysts
- CE marking machinery directives:Harmonized vibration exposure limits across European markets are accelerating replacement of legacy equipment with compliant models, particularly in Germany's renovation sector.
- Brushless motor adoption:Permanent magnet motor technology eliminates carbon brush maintenance and extends tool lifespan for professional contractors managing mixed fleet portfolios.
- Residential renovation intensity:Housing stock refurbishment programs in Germany and similar mature markets sustain above-average demand for compact cordless units in bathroom and kitchen retrofit applications.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack materials including cobalt and nickel remain exposed to commodity price swings that compress margin on cordless entry-level SKUs.
- SDS Max bit supply concentration:Specialty carbide tooling production clusters in Central Europe create single-source risk for heavy-duty demolition contractors requiring rapid bit replacement.
- Electro-pneumatic mechanism thermal limits:Sealed hammering systems in compact cordless units face hard power ceilings that exclude them from structural concrete drilling above 20mm diameter.
Strategic Opportunities
- India infrastructure buildout:National highway and metro expansion programs create first-time demand for professional-grade rotary hammers among domestic construction firms transitioning from manual methods.
- Tool-as-a-service platforms:Subscription-based fleet management models lock in recurring revenue streams while capturing usage data for predictive maintenance algorithms.
- Battery ecosystem convergence:Cross-platform compatibility between rotary hammers and existing cordless portfolios from power tool manufacturers reduces buyer switching costs and accelerates cordless adoption.
Industry Challenges
- Hand-arm vibration certification delays:ISO 28927-10 testing protocols require extended validation timelines that postpone product launches by 6-12 months for new handle isolation designs.
- Aftermarket service network density:Cordless platform proliferation fragments repair parts inventory, forcing distributors to maintain parallel stocking for multiple battery voltages and connector standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Hammers Market |
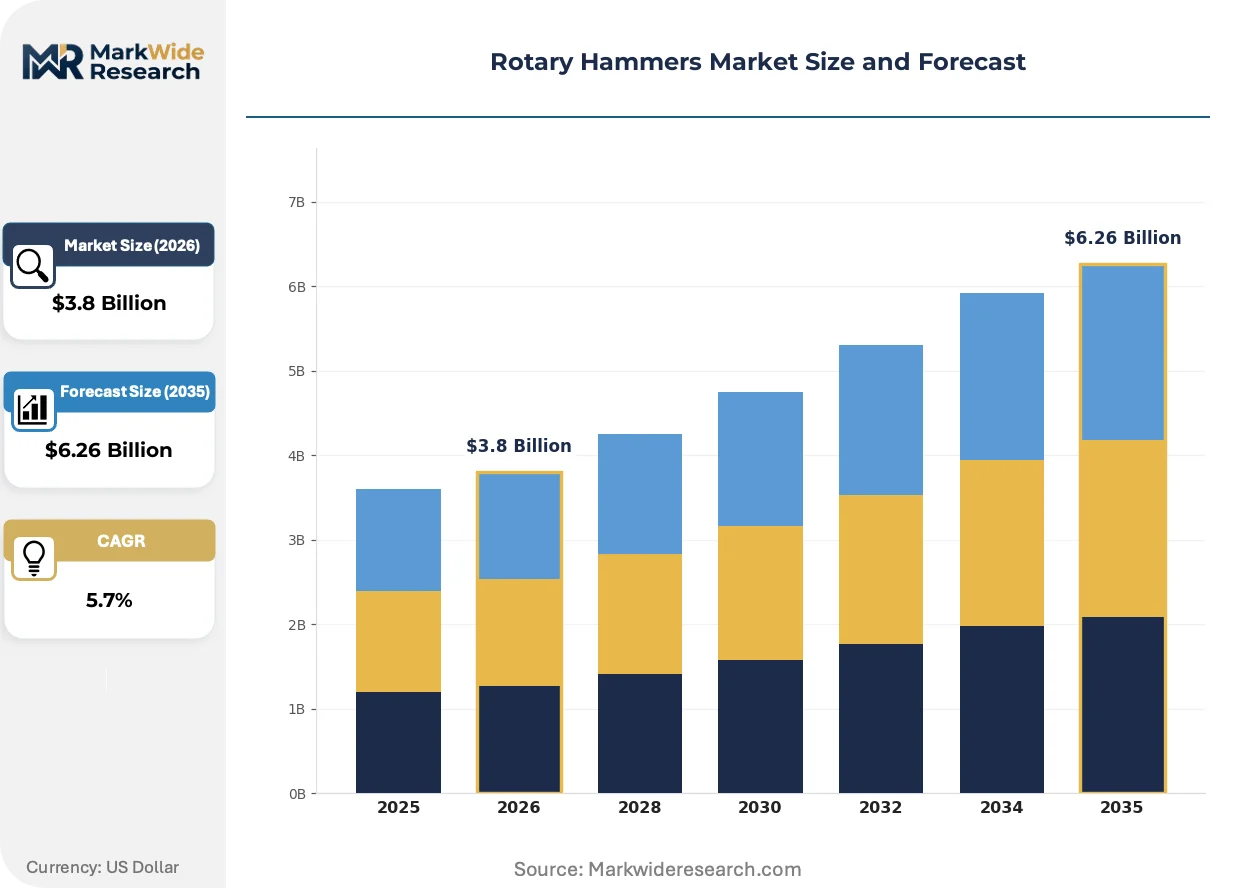
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Rotary Hammers, Pneumatic Rotary Hammers, Cordless Rotary Hammers, Heavy-Duty Rotary Hammers Technology: Brushless Motor, SDS Max, SDS Plus, Pneumatic Technology End User: Construction, Demolition, Renovation, Maintenance Size: Compact, Medium, Large, Extra-Large |
| Companies Covered | Hilti AG, Koki Holdings Co., Ltd., Robert Bosch GmbH, C. & E. Fein GmbH, Metabowerke GmbH, Stanley Black & Decker, Inc., Techtronic Industries Co. Ltd., DeWalt, Makita Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Hammers Market Evolving Landscape
Active control systems and connectivity modules are redefining how professional contractors interact with rotary hammer equipment, shifting value capture from hardware sales toward data-enabled service relationships.
Brushless motor technology is absorbing the functional role once reserved for corded units in medium-duty concrete drilling applications. Commercial renovation contractors in Germany and France are standardizing on 18V-36V platforms for overhead ceiling work where trailing cables create fall hazards. This absorption of corded market share is compressing the price premium between cordless and corded equivalents to under fifteen percent at equivalent joule ratings.
OSHA vibration exposure standards in the United States and parallel EU machinery directives are mandating active vibration control systems on professional-grade equipment. Manufacturers must integrate accelerometer-based feedback loops that modulate percussion intensity in real time. Heavy-duty demolition contractors operating in California and Texas are encountering inspection regimes that disqualify pre-2020 equipment from public infrastructure tenders.
Fleet management software is displacing traditional warranty registration as the primary post-sale customer touchpoint. Construction equipment rental houses in Germany are bundling rotary hammer subscriptions with usage analytics and automated maintenance scheduling. This behavioral shift is most pronounced among mid-sized general contractors managing 50-200 unit mixed fleets who prioritize uptime guarantees over capital ownership.
Rotary Hammers Market Segmentation
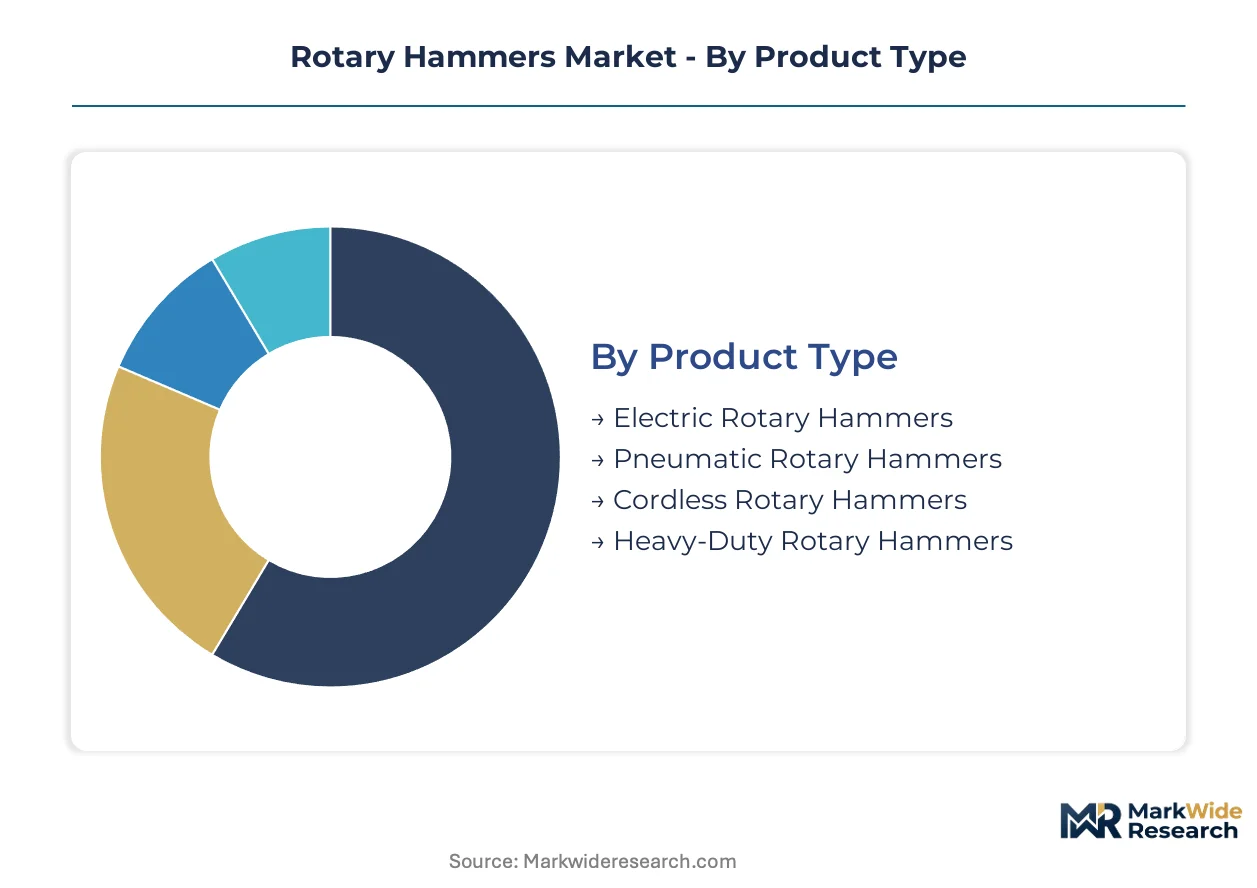
Rotary hammer procurement patterns diverge sharply across product architectures, power platforms, and jobsite applications. Contractors segment their fleets by task intensity rather than brand loyalty, creating distinct margin pools for manufacturers who align specifications with named end-use requirements.
Product Type:
Standardization dominates at the entry level while customization concentrates in professional-grade configurations where battery platform compatibility and vibration isolation systems differentiate procurement decisions.
- Electric Rotary Hammers:Corded units with sustained power delivery for continuous drilling in structural concrete. Demand concentrates in German infrastructure maintenance where trailing cables pose acceptable trade-offs against runtime certainty.
- Cordless Rotary Hammers:Lithium-ion platforms with brushless motor technology eliminate carbon brush maintenance and extend operational lifespan. German renovation contractors prioritize these for bathroom and kitchen retrofits where overhead maneuverability trumps peak power output.
- Pneumatic Rotary Hammers:Compressed-air systems for explosion-risk environments in petrochemical maintenance.
- Heavy-Duty Rotary Hammers:SDS Max interface units for demolition contractors requiring sustained impact energy above 10 joules.
Leading the category by volume: Cordless Rotary Hammers. Growing fastest: Cordless Rotary Hammers.
Technology:
Cost tier stratification separates premium motor and chuck technologies from commodity mechanical systems, with professional contractors absorbing price premiums for reduced downtime and extended service intervals.
- Brushless Motor:Permanent magnet designs eliminate brush replacement and reduce thermal losses, extending tool lifespan for contractors managing mixed fleet portfolios. German commercial renovation firms standardize on 18V-36V platforms for overhead ceiling work.
- SDS Max:Large-format chuck interface for heavy carbide bits above 20mm diameter in structural demolition. Demand concentrates in German infrastructure refurbishment programs where bit retention security prevents costly dropped-tool incidents.
- SDS Plus:Compact chuck standard for residential renovation and light commercial drilling.
- Pneumatic Technology:Compressed-air hammering mechanisms for hazardous environment compliance.
Brushless Motor commands the premium tier by margin. SDS Plus dominates unit shipments across all geographies.
End User:
Application intensity determines equipment specification, with vibration exposure regulations and uptime requirements reshaping fleet composition across contractor specializations.
- Construction:General contractors require versatile platforms spanning foundation work through finish carpentry, prioritizing battery ecosystem compatibility over single-tool performance optimization. German residential building permits sustain replacement cycles for mid-duty cordless units.
- Demolition:Specialized contractors demand sustained impact energy and rapid bit change systems for structural concrete removal. OSHA vibration exposure limits in the United States and EU machinery directives mandate active control systems for professional-grade equipment qualification.
- Renovation:Compact cordless units for residential retrofit where maneuverability outweighs raw power.
- Maintenance:Predictable-duty-cycle applications in facility management with standardized replacement schedules.
Renovation leads by unit volume. Demolition generates highest revenue per unit.
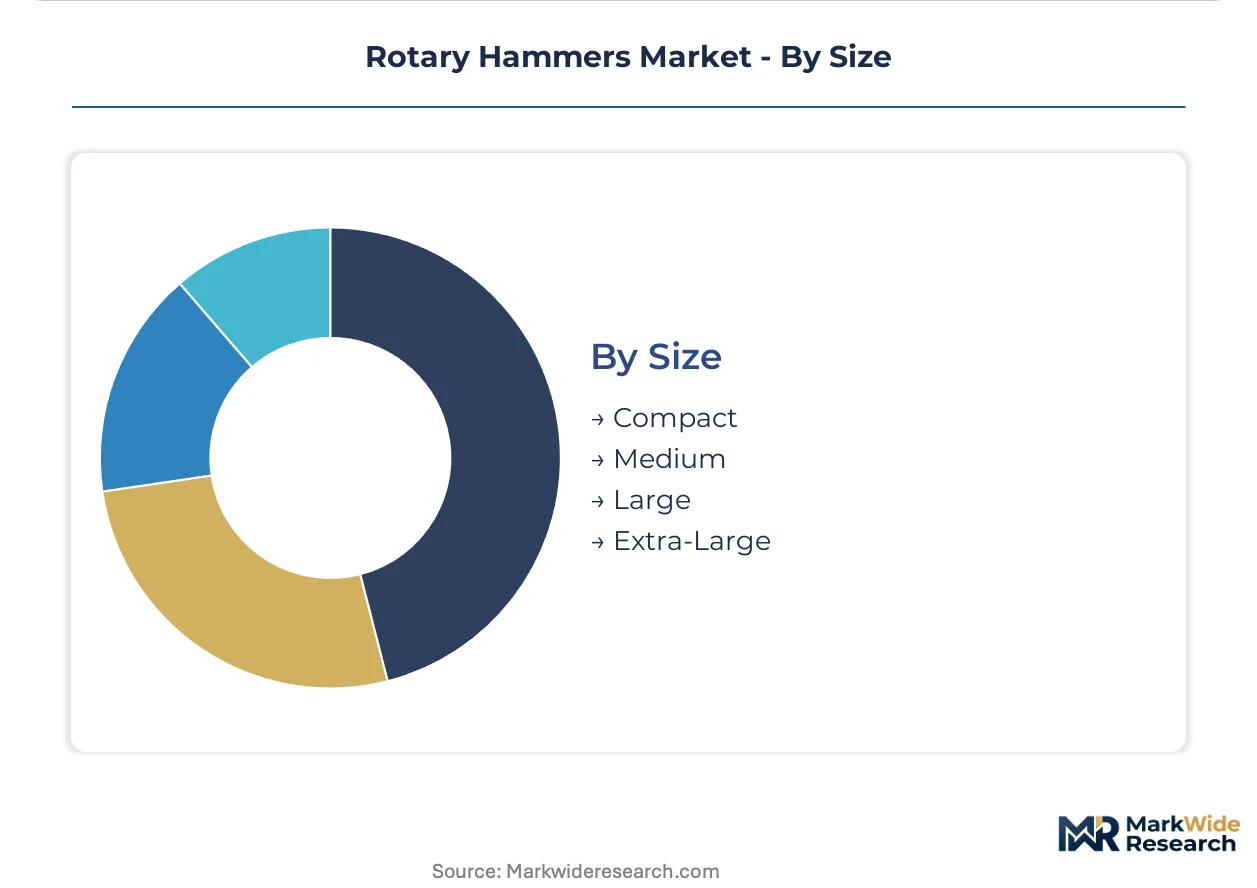
Size:
Volume distribution follows the inverse relationship between tool mass and application frequency, with compact units achieving scale through residential penetration while extra-large configurations capture margin in specialized infrastructure work.
- Compact:Sub-3kg cordless units with brushless motor technology for overhead and confined-space applications. German bathroom and kitchen retrofit contractors prioritize these for ceiling drilling where single-handed operation prevents fatigue-related quality defects.
- Medium:General-purpose platforms balancing power and maneuverability for mixed commercial construction.
- Large:SDS Max equipped units for foundation and structural work requiring sustained drilling above 20mm diameter.
- Extra-Large:Dedicated demolition rigs with active vibration control for continuous operation in bridge and tunnel refurbishment.
Compact size leads by shipment volume. Extra-Large commands highest average selling price.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European rotary hammer demand through its dense concentration of construction equipment manufacturers and specialized trade distributors serving renovation contractors across southwestern Germany.
Germany
Residential refurbishment programs in North Rhine-Westphalia and Bavaria sustain replacement cycles for compact cordless units. CE marking machinery directives under EU harmonized standards accelerate fleet turnover among professional contractors. The Rhine-Main industrial corridor hosts distribution centers supplying SDS Max tooling to demolition specialists.
United States
Commercial construction in Texas and California drives procurement of heavy-duty units for structural concrete work. OSHA vibration exposure limits enforce active control system mandates on public infrastructure tenders. Chicago-area rental houses bundle fleet management software with rotary hammer subscriptions.
China
Metro expansion in Shanghai and Beijing generates first-time demand for professional-grade equipment among domestic contractors. GB standards and MIIT regulations shape battery platform certification requirements. The Yangtze River Delta manufacturing cluster produces brushless motor assemblies for regional OEM supply.
India
National highway construction under the Ministry of Road Transport and Highways creates volume demand for medium-duty corded units. BIS certification requirements for power tools filter substandard imports from unorganized suppliers. Mumbai-Pune industrial corridor distributors stock carbide bits for foundation contractors.
Japan
Seismic retrofit programs in Tokyo and Osaka sustain replacement demand for vibration-isolated equipment. METI energy efficiency guidelines favor brushless motor adoption in commercial renovation. Nagoya-based construction firms standardize on compact cordless platforms for interior finishing work.
Rotary Hammers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base stratifies into three concentration levels: integrated multinationals controlling battery ecosystems, specialized German fabricators dominating professional-grade niches, and Asian manufacturers capturing volume in emerging markets. Strategic moves center on platform convergence tactics and predictive maintenance service bundling rather than pure hardware differentiation.
Among German-based fabricators, Hilti AG and Metabowerke GmbH exemplify the premium professional-grade archetype through direct-channel fleet management models. Robert Bosch GmbH anchors the ecosystem-tier position, leveraging cross-platform battery compatibility to reduce contractor switching costs. Stanley Black & Decker, Inc. occupies the scale-driven multinational tier, distributing through retail and professional channels across North American and European markets.
| Leading Market Players |
|---|
| Hilti AG |
| Koki Holdings Co., Ltd. |
| Robert Bosch GmbH |
| C. & E. Fein GmbH |
| Metabowerke GmbH |
| Stanley Black & Decker, Inc. |
| Techtronic Industries Co. Ltd. |
| DeWalt |
| Makita Corporation |
| Others |
Value Network & Pricing Analysis
German commercial renovation contractors concentrate procurement authority for compact cordless units, anchoring value-based pricing models that tie equipment cost to guaranteed uptime and vibration compliance certification rather than per-unit hardware margins.
Pricing Analysis
Outcome-based pricing anchors professional-grade rotary hammer procurement, with fleet management subscriptions bundling tool access, maintenance scheduling, and usage analytics under per-month contracting. Price differentiation separates CE-marked vibration-compliant units from uncertified imports, while battery platform compatibility commands loyalty premiums. Cost compression in entry-level cordless SKUs intensifies as lithium-ion cell volatility squeezes margins. Residential renovation contractors exhibit highest price sensitivity, whereas demolition specialists absorbing SDS Max tooling prioritize bit retention security over capital outlay.
Supply Chain Analysis
Dual-sourcing mandates from heavy-duty demolition contractors qualify brushless motor assemblies from both China and Japan to mitigate single-factory disruption risk. Lithium-ion battery cells draw from South Korean and Japanese chemical suppliers, while carbide bit production clusters in Central Europe. Commodity price volatility in cobalt and nickel concentrates supply risk upstream. Distribution runs through specialized trade distributors in Germany and rental house networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless motor controller fabrication capacity constrains cordless platform expansion, propping pricing power for qualified suppliers across the analysis window.
For Market Incumbents: Lock in fleet management subscription penetration among mid-sized German general contractors to preempt emerging battery ecosystem rivals. Defend SDS Max bit supply relationships through captive inventory positions in Central Europe. Prioritize ISO 28927-10 certification investment to accelerate compliant product launches against delayed competitors. For New Entrants and Emerging Players: Equipment rental houses in Texas and California represent the most penetrable channel archetype for subscription-based market entry. Target commercial construction contractors managing 50-200 unit mixed fleets with predictive maintenance software bundling. Pursue white-label manufacturing partnerships with Yangtze River Delta brushless motor assemblers to bypass R&D timelines. For Investors and Strategic Acquirers: The window for entry favors vertically integrated battery platform operators with existing cordless tool portfolios. Long-term viability centers on capturing recurring service revenue rather than transactional hardware margins. Watch for BIS certification acceleration in India as inflection signal for infrastructure-driven demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Ecosystem Convergence | Cross-platform compatibility with existing 18V-36V portfolios reduces contractor switching costs. |
| Fleet Management Platform Launch | Subscription bundling with usage analytics locks in recurring revenue from German renovation contractors. |
| Active Vibration Control Certification | Accelerometer-based handle isolation meets OSHA and CE marking compliance for public tenders. |
| Backward Integration into Motor Controllers | In-house brushless assembly production secures supply against lithium-ion platform demand surges. |
| Regional Distribution Partnership | Specialized trade distributor alliances in North Rhine-Westphalia capture bathroom retrofit volume. |
Research Methodology
Trade association filings, customs import records, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with maintenance directors at German construction firms, procurement leads at North American rental houses, aftermarket service heads at power tool distributors, and plant engineers at brushless motor assembly facilities. Bottom-up and top-down triangulation validated segment-level estimates against macro demand indicators.
Bottom-up modeling aggregated unit shipment projections across cordless, corded, and pneumatic architectures, while top-down analysis calibrated total addressable market expansion against construction permit data and infrastructure budget appropriations. Segmentation dimensions included product type, power platform, chuck interface standard, end-use application intensity, and regional regulatory cluster. CAGRs derived from fitted trend lines applied to historical replacement cycle patterns and battery platform adoption curves.
Caveats apply where lithium-ion cell cost volatility or ISO 28927-10 certification delays could materially shift the outlook. Forecasts reflect assumptions around brushless motor reliability maturation and CE marking enforcement consistency. Deviation in German residential refurbishment program funding would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Global Crane and Hoist Market
Construction Equipment
Drilling Machine Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Dust Suppression Fog Cannon Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Collating Machinery Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Global Dragline Excavator Market