
 Viscosity Index Improvers Market | 2026-2036
Viscosity Index Improvers Market Size, Share, and Industry Trends Forecast 2026-2036
Viscosity Index Improvers Market Intelligence
The EU Green Deal is pivoting lubricant blenders toward lower-viscosity engine oils that demand precise polymer selection. Evonik Industries AG leverages its methacrylate chemistry platform to supply dispersant VI improvers for European OEM fill programs. BASF SE anchors supply of hydrogenated styrene-diene copolymers to Asian lubricant compounders seeking cold-crank compatibility. Infineum International Limited competes through integrated additive package design that bundles VI performance with detergent and antioxidant chemistry.
Viscosity index improvers are polymeric additives that expand at elevated temperatures to counteract base oil thinning, with molecular weights typically ranging from ten thousand to over one million Daltons determining shear stability and thickening efficiency. Their primary purpose is to enable multi-grade lubricants that maintain operational viscosity across wide temperature spans. Ethylene propylene copolymer dominates volume demand in automotive lubricants due to cost-performance balance and broad OEM qualification, while polyisobutylene occupies niche industrial applications requiring exceptional oxidative stability. Styrenated phenol retains importance in specialized hydraulic fluids where anti-wear synergy with zinc dithiophosphates matters.
EPA fuel economy standards and REACH polymer registration requirements in Europe are tightening specifications for permanent shear stability index in passenger car motor oils. China's MEE enforces China VI emission limits that cascade into lubricant viscosity grade reductions, directly influencing polymer selection by domestic blenders. India's BIS certification for automotive lubricants adds another compliance layer for suppliers targeting aftermarket channels. Stakeholders must monitor how OEM drain interval extensions and electrified powertrain penetration alter the volume-intensity relationship between VI improver consumption and finished lubricant demand.
Market Dynamics
OEM drain interval extensions and electrified powertrain penetration are fundamentally altering the volume-intensity relationship between VI improver consumption and finished lubricant demand. Polymer suppliers now face pressure to justify treat rates in lower-viscosity formulations while maintaining shear stability under tighter mechanical tolerances.
Growth Catalysts
- China VI emission limits:China's MEE enforces viscosity grade reductions that cascade into polymer selection by domestic blenders seeking cold-crank compatibility.
- Hot-climate durability specifications:Formulators in India and Brazil specify higher treat rates to meet OEM requirements under extreme operating temperatures.
- Ethylene propylene copolymer qualification:Automotive lubricant manufacturers expand procurement of EPM grades as engine oil specifications tighten under Euro 6 rules.
Market Restraints
- Alpha-olefin feedstock volatility:Ethylene and propylene monomer costs fluctuate with crude oil derivatives, compressing margin visibility for copolymer producers.
- REACH polymer registration friction:ECHA requirements in Europe impose documentation burdens on imported VI improver grades, slowing market entry for non-EU suppliers.
- Permanent shear stability trade-offs:Higher molecular weight polymers deliver thickening efficiency but sacrifice mechanical durability under high-shear fuel injection equipment.
Strategic Opportunities
- India BIS aftermarket certification:Domestic lubricant compounders require compliant additive packages, creating specification-driven demand for qualified polymer suppliers.
- Dispersant VI improver convergence:Methacrylate chemistry platforms enable dual-function additives that combine viscosity modification with soot handling for hybrid powertrains.
- Industrial hydraulic niche expansion:Styrenated phenol retains anti-wear synergy with zinc dithiophosphates in specialized fluid applications outside automotive saturation.
Industry Challenges
- Shear stability index testing bottlenecks:Extended certification timelines for new polymer architectures delay OEM qualification and revenue recognition.
- Formulation integration complexity:VI improvers must coexist with detergent, antioxidant, and friction modifier chemistries without phase separation or performance interference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viscosity Index Improvers Market |
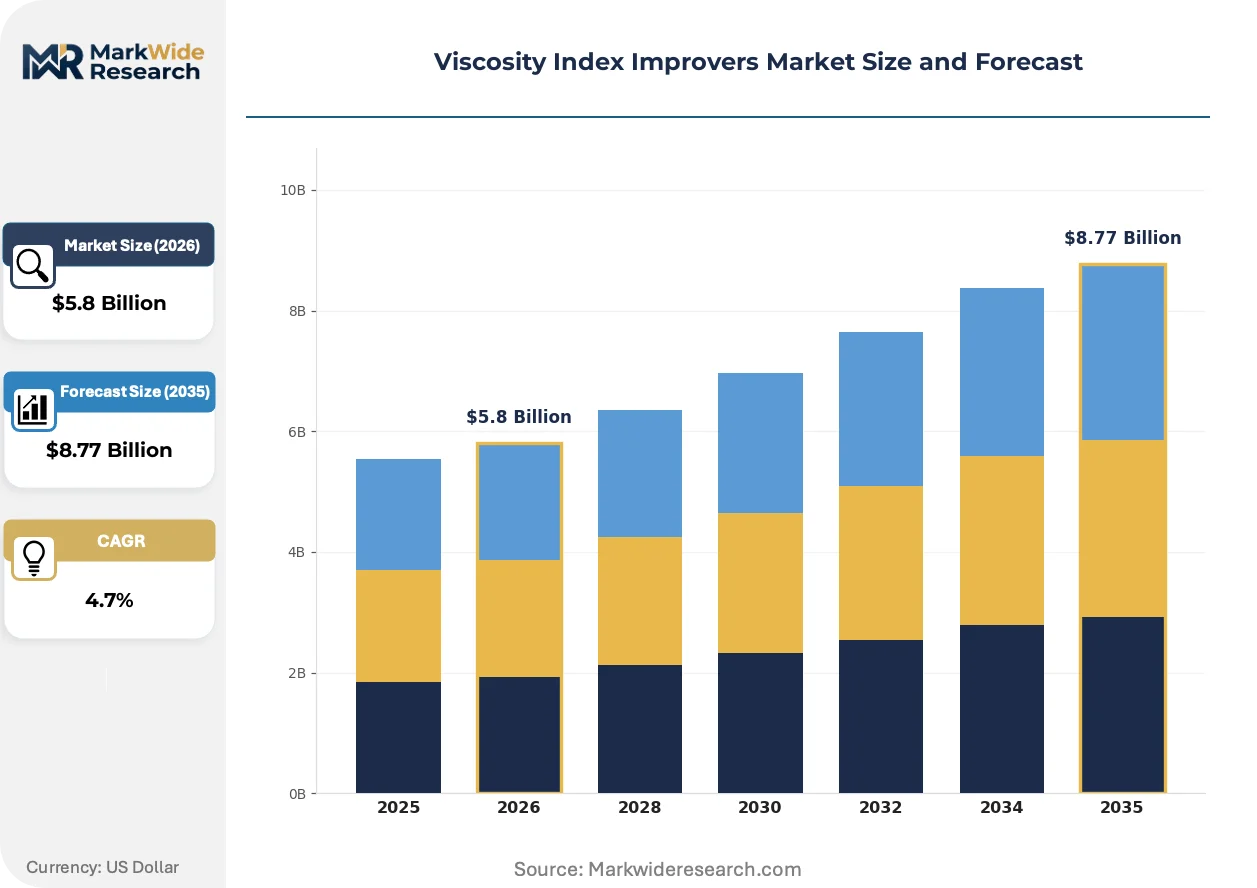
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polybutene, Polyisobutylene, Styrenated Phenol, Ethylene Propylene Copolymer Application: Automotive Lubricants, Industrial Oils, Gear Oils, Hydraulic Fluids End User: OEMs, Aftermarket Providers, Industrial Manufacturers, Lubricant Distributors Packaging Type: Drums, IBC Containers, Pails, Bulk |
| Companies Covered | Chevron Oronite Company LLC, Evonik Industries AG, The Lubrizol Corporation, LANXESS AG, Sanyo Chemical Industries, Ltd., Infineum International Limited, BASF SE, Mitsui Chemicals, Inc., Afton Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viscosity Index Improvers Market Strategic Shifts & Innovations
Polymer architecture innovation is compressing the traditional trade-off between thickening efficiency and mechanical durability. Suppliers are re-engineering molecular weight distributions and introducing functional side chains to meet simultaneous OEM demands for fuel economy and extended drain intervals.
Star-branched polymethacrylate architectures are integrating dispersant functionality directly into the polymer backbone. European OEM fill programs specify these grades for lower-viscosity engine oils under EU Green Deal carbon reduction targets. The technology is integrating soot handling and viscosity control into single-additive solutions, reducing total treat rates and package complexity for blenders.
EPA fuel economy standards and REACH polymer registration requirements are tightening specifications for permanent shear stability index in passenger car motor oils. The industrial consequence is a qualification bottleneck for imported polymer grades lacking European regulatory dossiers. North American lubricant compounders are responding by dual-sourcing from domestic hydrogenated styrene-diene suppliers to mitigate ECHA documentation risk.
Aftermarket procurement is consolidating around certified additive packages rather than discrete component sourcing. Indian and Brazilian lubricant blenders now specify pre-qualified VI improver bundles from integrated suppliers, displacing historical spot-market polymer purchasing. This behavior shift concentrates volume with formulators offering bundled detergent-antioxidant-polymer systems, particularly visible in high-growth climate-stressed operating environments.
Viscosity Index Improvers Market Segmentation
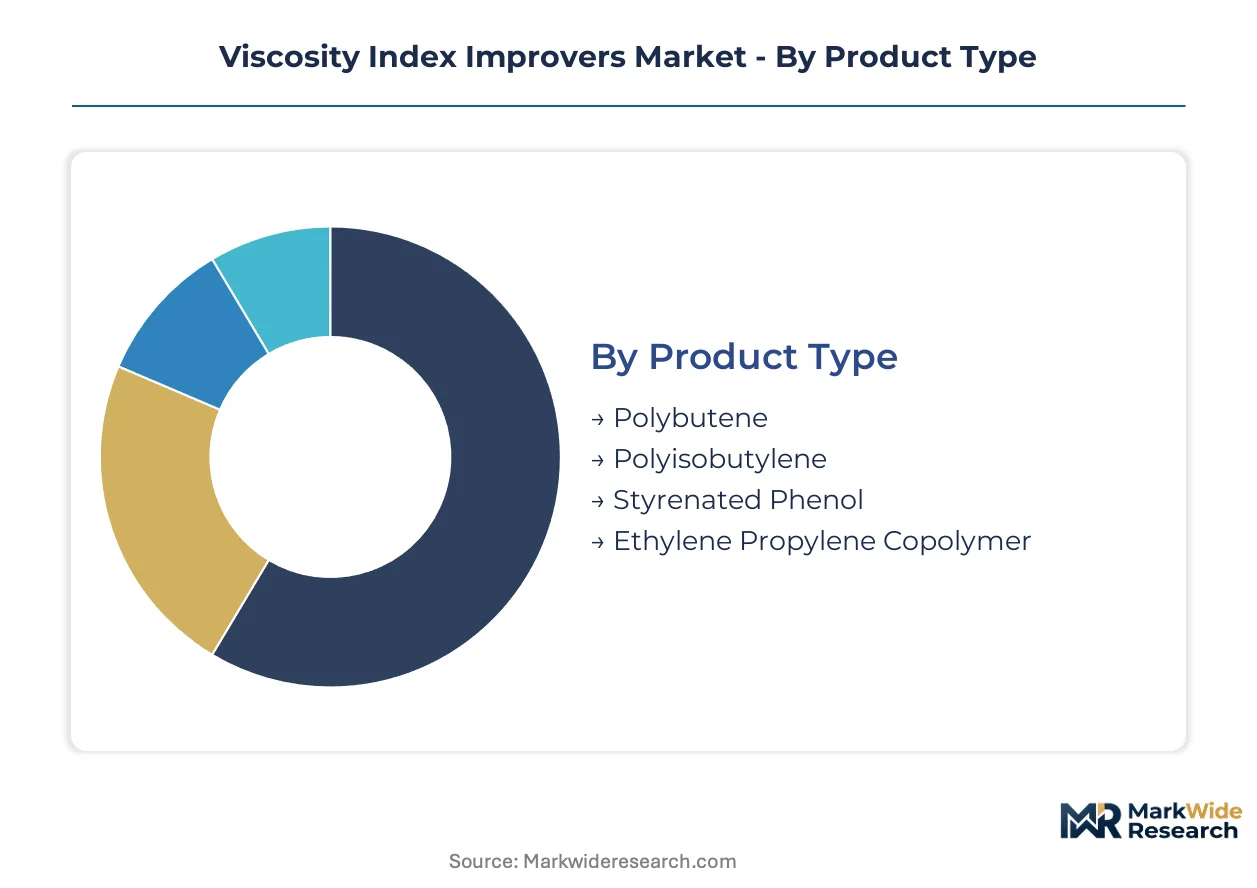
Viscosity index improver selection hinges on polymer architecture compatibility with base oil chemistry and shear stability requirements. Segmentation reveals how formulation economics and supply chain logistics create distinct procurement patterns across end-use categories.
Product Type:
Volume concentration favors commodity copolymers, while premium formulations demand specialized architectures with functional side chains.
- Ethylene Propylene Copolymer:Linear and branched EPM grades dominate automotive engine oil formulations due to cost-performance balance and broad OEM qualification portfolios. Indian and Brazilian blenders specify higher treat rates under hot-climate durability requirements, while European procurement tightens around Euro 6-compliant low-viscosity grades.
- Polyisobutylene:Low-molecular-weight PIB variants deliver exceptional oxidative stability for industrial compressor oils and metalworking fluids. Demand concentrates in German and Japanese industrial lubricant channels where extended drain intervals justify premium polymer economics.
- Styrenated Phenol:Retains niche importance in specialized hydraulic fluids requiring anti-wear synergy with zinc dithiophosphates.
- Polybutene:Serves adhesive and sealant applications adjacent to lubricant markets with distinct viscosity modification requirements.
Mature deployment sits with ethylene propylene copolymer. Newer deployment is concentrated in polyisobutylene for industrial oxidation resistance.
Application:
Automotive specifications cascade into polymer selection faster than industrial channels due to OEM qualification intensity and regulatory alignment.
- Automotive Lubricants:Passenger car motor oils and heavy-duty diesel formulations consume the majority of VI improver volume, with China VI and Euro 6 emission limits forcing viscosity grade reductions. Polymer suppliers face pressure to maintain shear stability index under tighter mechanical tolerances while enabling fuel economy gains.
- Industrial Oils:Compressor, turbine, and circulating oil applications prioritize oxidative stability over cold-crank performance, favoring hydrogenated styrene-diene and polyisobutylene chemistries. Japanese and German industrial lubricant compounders specify these grades for extended drain interval programs.
- Hydraulic Fluids:Mobile and stationary equipment applications balance viscosity control with anti-wear additive compatibility.
- Gear Oils:Axle and transmission lubricants require high-temperature thickening efficiency under extreme pressure conditions.
Specification intensity peaks in automotive lubricants. Volume expansion is climbing fastest in industrial oils as maintenance interval extension programs proliferate.
End User:
Procurement authority separates between specification-setters and formulation executors with distinct technical service requirements.
- OEMs:Original equipment manufacturers dictate polymer qualification through factory fill approvals and service fill specifications. European and Chinese automotive OEMs now require REACH-compliant dossiers and China VI test data as baseline entry requirements.
- Aftermarket Providers:Independent lubricant blenders in India and Brazil increasingly specify pre-qualified additive packages rather than discrete polymer sourcing, consolidating volume with integrated suppliers offering bundled detergent-antioxidant-polymer systems.
- Industrial Manufacturers:In-house lubricant blending operations at steel, cement, and mining operations procure bulk polymer for captive formulation.
- Lubricant Distributors:Channel partners specify packaged additive systems for regional blending and private label programs.
Contract security concentrates with OEMs. Procurement flexibility is expanding fastest among aftermarket providers adopting certified package sourcing.
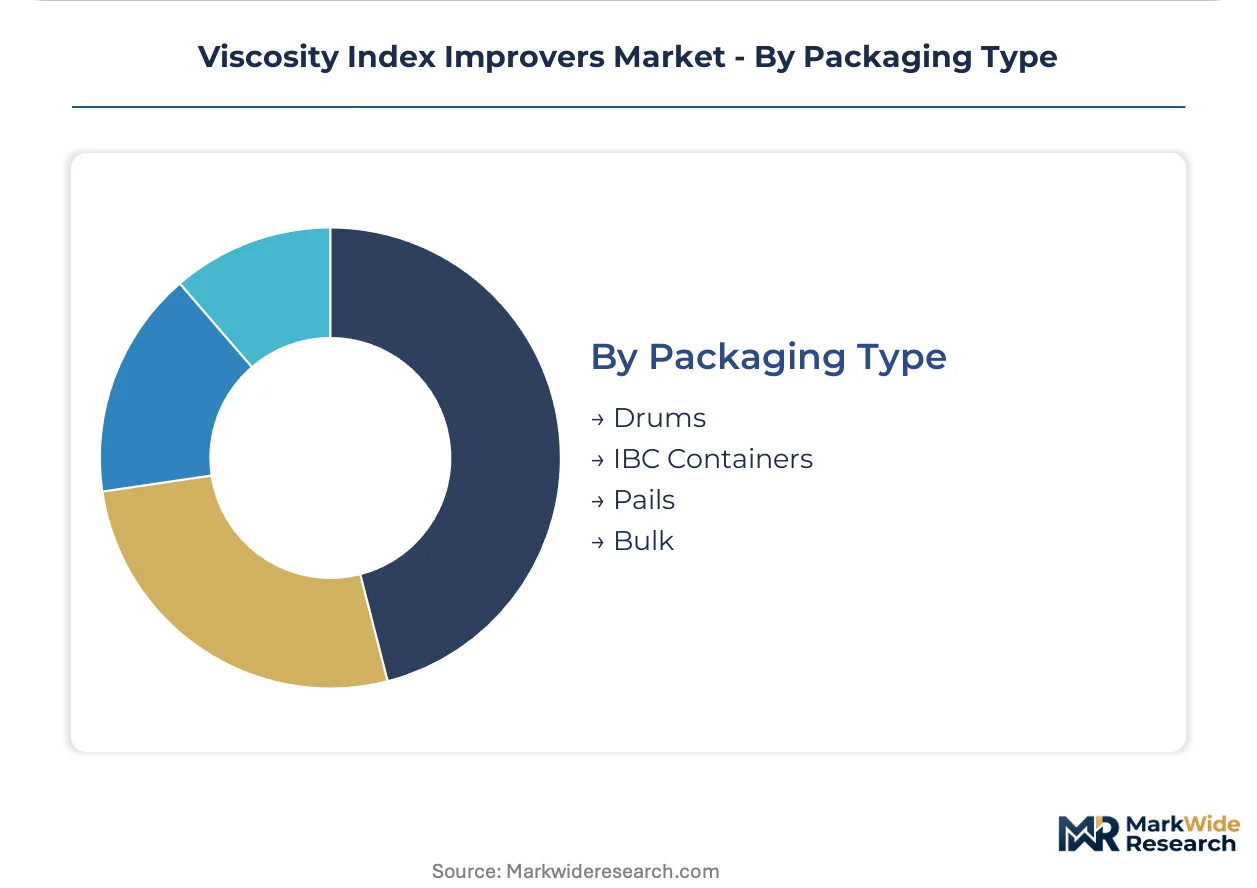
Packaging Type:
Logistics economics and formulation scale determine packaging selection, with bulk infrastructure investments creating regional supply moats.
- Bulk:Tank truck and railcar deliveries serve high-volume lubricant compounders with dedicated storage and blending infrastructure. North American and European integrated suppliers leverage bulk logistics to defend position against imported polymer grades lacking regional distribution networks.
- IBC Containers:Intermediate bulk containers balance freight efficiency with flexibility for mid-scale blenders and regional formulators.
- Drums:Standard 55-gallon steel drums serve smaller compounders and specialty lubricant manufacturers with limited storage capacity.
- Pails:Five-gallon and smaller containers address laboratory sampling, trial formulations, and maintenance shop direct sales.
Scale economies favor bulk. Packaging flexibility is gaining share fastest among regional distributors serving fragmented aftermarket channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for ethylene propylene copolymers clusters in Germany, Japan, and the United States, while formulation demand concentrates in China, India, and Brazil where hot-climate engine durability requirements drive higher polymer treat rates. This production-consumption divide shapes logistics economics and qualification timelines for VI improver suppliers.
China
Domestic lubricant blenders in Shanghai and Shandong provinces are expanding procurement of lower-viscosity base stocks to meet MEE's China VI emission limits. The Ministry of Ecology and Environment enforces viscosity grade reductions that cascade directly into polymer selection criteria. Tianjin's lubricant additive cluster is integrating dispersant VI improvers for hybrid powertrain compatibility.
Germany
Evonik Industries AG leverages its methacrylate chemistry platform from Marl and Darmstadt facilities to supply European OEM fill programs. ECHA's REACH polymer registration requirements impose documentation burdens that slow market entry for non-EU suppliers. The Rhine-Ruhr industrial corridor anchors hydrogenated styrene-diene copolymer production for cold-crank compatibility specifications.
United States
EPA fuel economy standards tighten permanent shear stability index specifications for passenger car motor oils. Chevron Oronite Company LLC and Afton Chemical Corporation operate integrated additive package facilities along the Gulf Coast. Houston's petrochemical infrastructure supports bulk polymer logistics for North American lubricant compounders dual-sourcing to mitigate ECHA documentation risk.
India
Formulators in Maharashtra and Gujarat specify higher VI improver treat rates to meet OEM durability requirements under extreme operating temperatures. BIS certification for automotive lubricants adds compliance layers for suppliers targeting aftermarket channels. The Mumbai-Pune industrial belt is consolidating procurement around pre-qualified additive packages rather than discrete polymer sourcing.
Brazil
Hot-climate operating conditions in São Paulo and Minas Gerais states drive specification of elevated polymer loadings in heavy-duty diesel formulations. ANVISA alignment with Mercosur automotive standards influences lubricant additive qualification pathways. The ABC Paulista manufacturing region is adopting certified package sourcing from integrated suppliers displacing historical spot-market purchasing.
Viscosity Index Improvers Market Key Industry Players
The competitive structure tilts toward integrated additive package suppliers with captive polymer synthesis capabilities. Three to five multinational chemical conglomerates control formulation qualification pathways through OEM factory fill approvals, while regional compounders compete on aftermarket certification speed. Strategic archetypes separate into methacrylate chemistry specialists, hydrogenated styrene-diene producers, and ethylene propylene copolymer volume leaders. Dominant competitive moves include backward integration into alpha-olefin feedstocks and geographic expansion through regional blending partnerships.
Within the integrated additive package tier, Infineum International Limited and The Lubrizol Corporation exemplify suppliers bundling VI performance with detergent and antioxidant chemistry. Among German-based chemical conglomerates, BASF SE and LANXESS AG occupy positions anchored to European regulatory compliance infrastructure. Japanese specialists including Sanyo Chemical Industries, Ltd. and Mitsui Chemicals, Inc. represent producers with concentrated exposure to industrial oxidation-resistant formulations.
| Leading Market Players |
|---|
| Chevron Oronite Company LLC |
| Evonik Industries AG |
| The Lubrizol Corporation |
| LANXESS AG |
| Sanyo Chemical Industries, Ltd. |
| Infineum International Limited |
| BASF SE |
| Mitsui Chemicals, Inc. |
| Afton Chemical Corporation |
| Others |
Cost & Logistics Intelligence
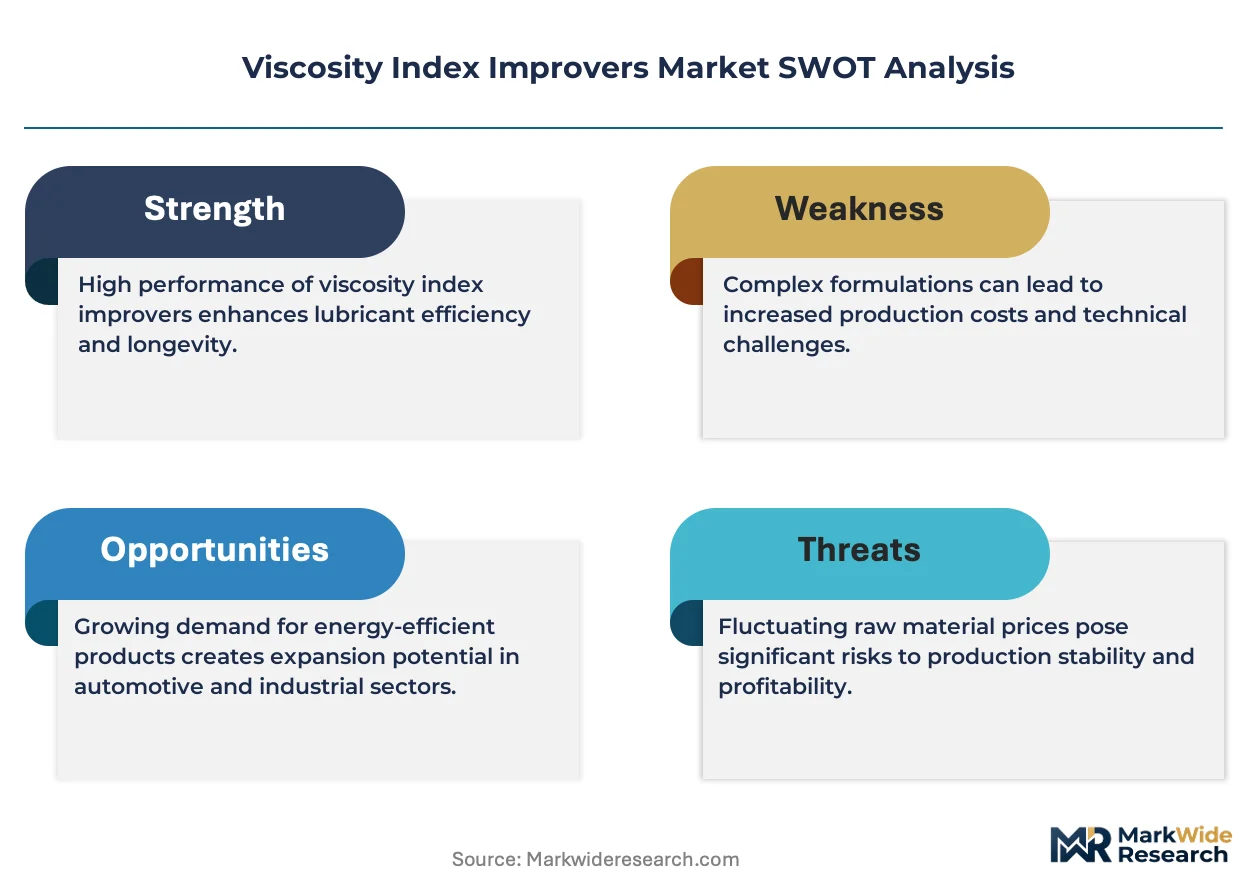
Star-branched polymethacrylate architecture migration is compressing formulation economics while concentrating procurement leverage with integrated additive package suppliers. This dual shift simultaneously elevates R&D amortization burdens for standalone polymer producers and rewards captive synthesis capabilities that bundle VI performance with detergent chemistry.
Pricing Analysis
Margin tightening in commodity ethylene propylene copolymer grades reflects alpha-olefin feedstock volatility and oversupply in Asian merchant markets. Contract-based long-term offtake dominates OEM procurement, while spot purchasing persists among Indian and Brazilian aftermarket blenders. Price differentiation hinges on REACH dossier completeness and China VI test data certification. Least price-sensitive buyers are European OEM fill programs demanding dual-function dispersant VI improvers; most sensitive are industrial hydraulic compounders in price-driven maintenance markets.
Supply Chain Analysis
Reverse-logistics flows for spent lubricant collection and re-refining are creating closed-loop feedstock channels that bypass virgin base oil markets. Manufacturing concentration centers on Germany, Japan, and the United States for hydrogenated styrene-diene and methacrylate chemistries. Feedstock dependencies span ethylene and propylene monomers, hydrogenation catalysts, and methacrylic acid esters. Single-source vulnerability sits with European REACH-compliant polymer grades lacking qualified second-source alternatives. Distribution runs through bulk tanker networks serving integrated Gulf Coast and Rhine-Ruhr additive package facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA REACH polymer registration requirements erect a documentation moat that protects incumbent suppliers with existing dossiers while imposing multi-year entry delays on non-EU competitors.
For Market Incumbents: Hedge against electrified powertrain volume erosion by deepening dispersant VI improver capabilities for hybrid compatibility. Prioritize backward integration into alpha-olefin feedstocks to defend margin position against crude derivative volatility. Accelerate India BIS certification timelines to capture aftermarket consolidation toward pre-qualified additive packages. For New Entrants and Emerging Players: Direct-to-blender digital platforms offer route-to-market bypassing established distributor networks in fragmented Latin American and Southeast Asian channels. Target industrial hydraulic fluid segments outside automotive saturation where styrenated phenol anti-wear synergy commands specification premiums. Lead with certified small-batch IBC packaging for regional compounders lacking bulk storage infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated additive package conglomerates seeking methacrylate chemistry capabilities. Long-term viability favors suppliers with captive hydrogenation capacity and REACH-compliant European manufacturing footprints. Monitor OEM drain interval extension announcements as volume-intensity inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Olefin Feedstocks | Captive ethylene and propylene supply insulates margin from crude derivative volatility. |
| REACH Dossier Expansion for Polymer Grades | European regulatory compliance accelerates OEM qualification timelines. |
| India BIS Certification Investment | Aftermarket consolidation toward pre-qualified packages rewards early certification. |
| Dispersant VI Improver R&D Scale-Up | Dual-function additives reduce total treat rates for hybrid powertrain formulations. |
| Regional Blending Partnership in Brazil | Hot-climate durability specifications elevate polymer loadings in heavy-duty diesel. |
Research Approach
Independent corroboration across lubricant formulator procurement leads, OEM technical specification managers, and additive package R&D directors underwrites the qualitative findings. Primary fieldwork encompassed technical interviews with plant managers at European and Asian polymer synthesis facilities, downstream procurement leads at integrated lubricant compounders, and distribution channel partners in India and Brazil. Secondary validation drew from ECHA REACH registration databases, customs trade flows for ethylene propylene copolymer grades, and SEC filings of listed chemical conglomerates. Bottom-up segment sizing triangulated against top-down macro lubricant demand projections.
Rate-of-change decomposition across the analysis window isolates volume effects from mix shifts and pricing dynamics. Segmentation dimensions modeled include polymer architecture type, application category, end-user procurement authority, and packaging logistics format. CAGRs derive from elasticity-adjusted demand curves incorporating OEM drain interval extension scenarios and electrified powertrain penetration assumptions. Industry-specific forecast inputs encompass China VI viscosity grade reduction mandates and Euro 6 mechanical tolerance specifications.
The model holds under stable regulatory enforcement timelines; deviation in REACH dossier approval velocity or China VI implementation strictness would shift polymer qualification bottlenecks. Forecasts reflect documented assumptions regarding hybrid powertrain lubricant formulation rates and industrial maintenance interval extension adoption. Practitioners should monitor OEM factory fill specification releases and MEE enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Canada Anti-Caking Market
Additives
Inorganic Rheology Modifiers Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Automotive Additives Market
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Gluconic Acid and Derivatives Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Dry-Mix Mortar Additives and Chemicals Market
Additives
Plasticizer Alcohols Market
Additives
Metal Modifiers Market
Additives
Sorbitan Tristearate Market
Additives
Asia-Pacific Feed Acidifiers Market
Additives
Viscosity Reducing Agents Market
Additives
Conditioning Agent Market
Additives
Global Flame Retardant Masterbatches Market