
 Europe Fuel Additives Market | 2026-2036
Europe Fuel Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fuel Additives Market Foresight
Chemical engineering talent scarcity across European petrochemical hubs is bifurcating the competitive landscape between integrated multinationals and specialized additive houses. BASF SE leverages its Ludwigshafen manufacturing complex to sustain captive supply chains for detergent and dispersant chemistries. Evonik Industries AG anchors its position through specialized organometallic catalyst technologies for diesel cetane improvement. The Lubrizol Corporation competes by controlling distribution networks that reach independent fuel blenders across the continent.
Europe fuel additives comprise chemical formulations—typically comprising carrier fluids, active detergents, dispersants, anti-oxidants, and corrosion inhibitors at treat rates between 50 and 2000 ppm—designed to enhance combustion efficiency, protect engine hardware, and ensure fuel stability across storage and distribution systems. Deposit control additives dominate value capture in the petrol application segment due to direct OEM specification and warranty linkage, while marine fuels represent the fastest-growing application as vessel operators reformulate for IMO 2020 sulfur compliance and EU MRV carbon reporting. Liquid formulation types occupy the majority share given injection system compatibility and blending logistics, though concentrated packages are gaining traction in aviation sector procurement for weight and volume efficiency.
REACH registration requirements administered by ECHA govern substance authorization and restriction, directly shaping which chemistries remain commercially viable for fuel additive producers serving European blenders. The EU Green Deal's transport decarbonization trajectory and F-Gas Regulation monitoring of fluorinated compounds are forcing reformulation investments across the supply base. Stakeholders must monitor the interaction between FuelEU Maritime standards and national renewable blending mandates to anticipate specification divergence and procurement complexity.
Market Dynamics
Marine operators across North Sea and Baltic routes are forcing rapid additive reformulation as IMO sulfur caps and EU MRV carbon reporting tighten operational parameters for residual fuel combustion.
Growth Catalysts
- IMO 2020 Sulfur Compliance:Vessel operators in the North Sea and Baltic routes are expanding procurement of detergent-dispersant packages to treat very low sulfur fuel oil and maintain engine cleanliness.
- Germany:Refinery upgrading activity and automotive OEM compliance specifications are concentrating demand for deposit control additives in the country's fuel blending infrastructure.
- Organometallic Catalyst Technologies:Cetane improver demand from heavy-duty diesel fleets is accelerating adoption of manganese and iron-based combustion enhancers across Central European transport corridors.
Market Restraints
- Base Oil Volatility:Price instability in Group II and Group III base stocks compresses formulation margins for additive houses dependent on external carrier fluid supply.
- REACH Registration Burden:ECHA substance authorization costs and data requirements create capital barriers for smaller additive producers seeking market access.
- Biofuel Substitution:Renewable diesel and hydrotreated vegetable oil penetration in Scandinavian markets displaces conventional additive-treated fossil diesel in some fleet applications.
Strategic Opportunities
- Poland and Czech Republic:Independent fuel blending capacity expansion in these markets offers additive suppliers underpenetrated distribution channels outside established German and Benelux networks.
- Aviation Concentrates:Airlines are shifting procurement toward concentrated additive packages that reduce weight and volume in jet fuel logistics, creating formulation specialization openings.
- FuelEU Maritime Standards:The EU's well-to-wake carbon intensity regulations will mandate renewable marine fuel blending, requiring new stabilizer and compatibility additive development.
Industry Challenges
- Organometallic Chemistry Expertise:Talent scarcity in organometallic synthesis and combustion kinetics limits formulation innovation at mid-scale additive houses competing with integrated multinationals.
- Certification Timeline Compression:OEM engine test protocol updates and CEC qualification requirements are extending product validation cycles beyond typical commercial development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fuel Additives Market |
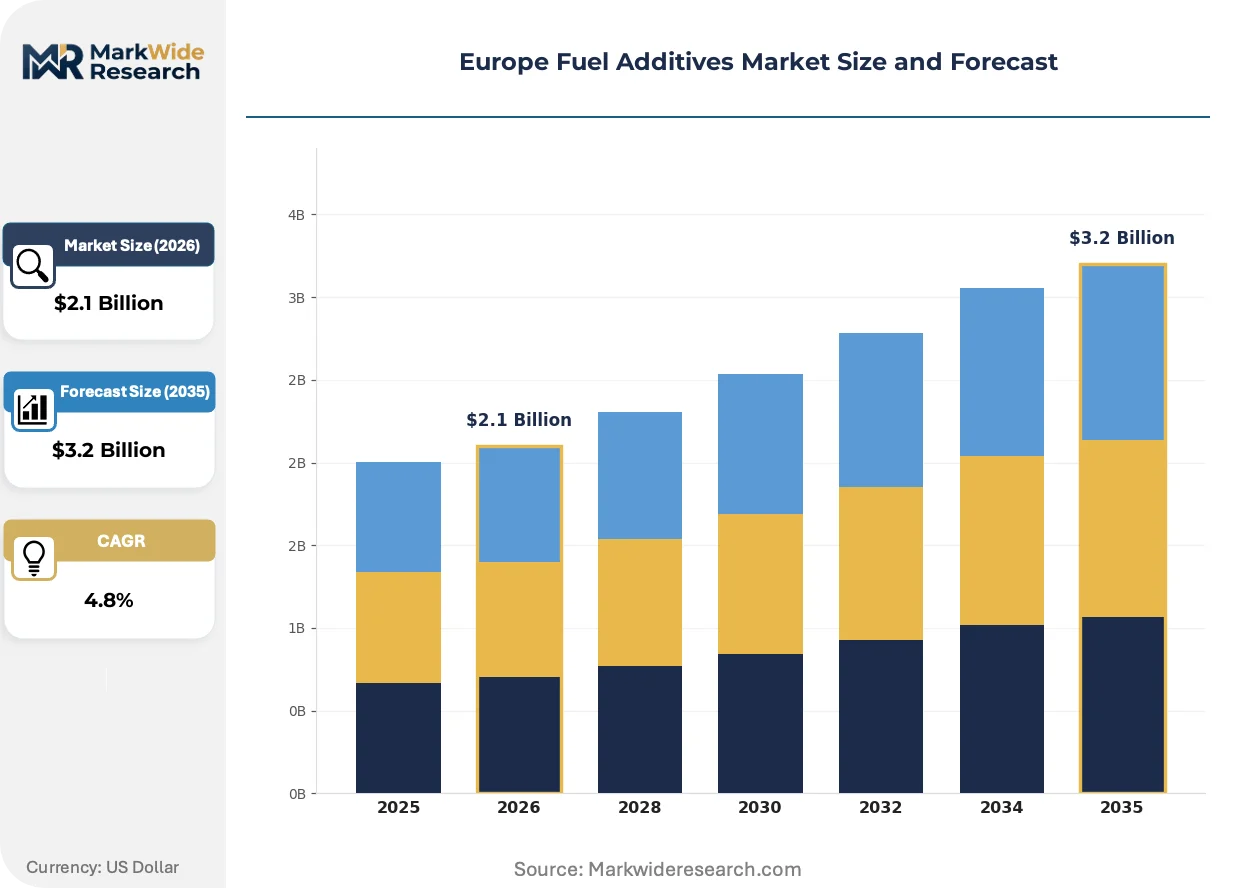
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Premium Additives, Performance Enhancers, Deposit Control Additives, Anti-Oxidants Application: Petrol, Diesel, Aviation Fuels, Marine Fuels Formulation Type: Liquid, Powder, Emulsified, Concentrated End User: Automotive Industry, Aviation Sector, Marine Industry, Industrial Applications |
| Companies Covered | BASF SE, The Lubrizol Corporation, Afton Chemical, Infineum International Limited, Evonik Industries AG, LANXESS, Clariant, Chevron Corporation, Innospec Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fuel Additives Market Shifts & Advancements
Reformulation investments are accelerating across the European additive supply base as REACH restrictions, F-Gas Regulation monitoring, and transport decarbonization mandates simultaneously constrain legacy chemistries and open novel formulation pathways.
Polyisobutylene succinimide detergent chemistry is bifurcating the deposit control segment. Marine fuel blenders are adopting high-total-base-number variants for residual fuel stability at accelerated procurement rates. This technology is bifurcating competitive positioning between suppliers with captive PIB supply and those dependent on merchant feedstock.
F-Gas Regulation oversight by ECHA is compressing fluorinated surfactant availability for fuel system corrosion inhibitors. Additive houses are reformulating with alternative chemistries to maintain performance in biodiesel blends. Aviation and marine segments face the steepest substitution timelines given their corrosion protection specifications.
Independent blenders are consolidating procurement relationships to secure volume commitments and technical service access. This channel compression is displacing fragmented distributor networks in Southern and Eastern European markets. The shift is most visible in Italy and Spain where fuel marketing unbundling has created new blender entrants seeking direct additive supply arrangements.
Europe Fuel Additives Market Segmentation
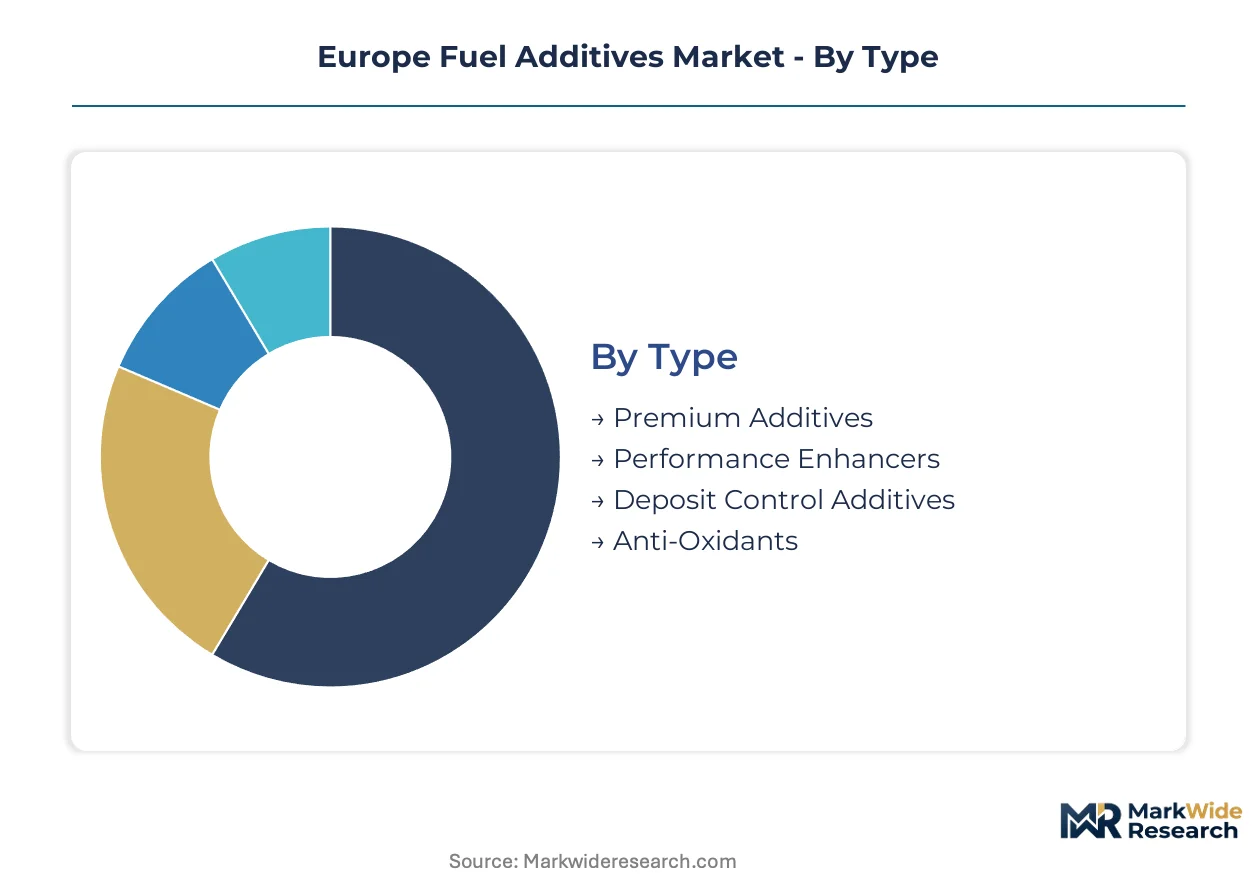
Fuel additive purchasing decisions in Europe fragment across specification tiers, combustion systems, and regulatory exposure. Understanding where procurement authority concentrates within each dimension reveals which formulation investments yield sustainable margin capture.
Type:
Margin pools concentrate in deposit control and premium additive tiers where OEM specification linkage creates pricing power independent of base fuel economics.
- Deposit Control Additives:Polyisobutylene succinimide formulations dominate this tier through direct automotive OEM warranty requirements and engine test protocol certification. German and Czech refinery upgrading activity is concentrating procurement of high-total-base-number variants for gasoline direct injection systems.
- Premium Additives:Multi-functional packages combining detergents, dispersants, and corrosion inhibitors command formulation premiums through consolidated blender procurement relationships in Benelux and Northern Italy.
- Performance Enhancers:Cetane improvers and combustion catalysts serve heavy-duty diesel fleets across Central European transport corridors with manganese and iron-based organometallic chemistries.
- Anti-Oxidants:Phenolic and aminic stabilizers protect biodiesel blends in Scandinavian markets where renewable diesel penetration is displacing conventional fossil fuel treatment.
Deposit control additives hold installed capacity. Performance enhancers are rotating up the share rankings.
Application:
Volume concentration tracks fuel consumption patterns, but value capture diverges sharply based on regulatory stringency and specification complexity.
- Marine Fuels:Very low sulfur fuel oil treatment packages for IMO 2020 compliance represent the steepest expansion trajectory, with North Sea and Baltic route operators reformulating for residual fuel stability and engine cleanliness under EU MRV carbon reporting.
- Petrol:Gasoline direct injection deposit control dominates value capture through OEM specification linkage, with German automotive compliance activity driving specification tightening across the continent's blending infrastructure.
- Diesel:Heavy-duty fleet treatment for cetane improvement and emissions compliance serves transport corridors through Poland and Czech Republic where independent blending capacity is expanding.
- Aviation Fuels:Jet fuel additives concentrate in corrosion inhibition and anti-icing specifications, with airlines shifting procurement toward concentrated packages for weight and volume efficiency in logistics.
Petrol holds installed capacity. Marine fuels are rotating up the share rankings.
Formulation Type:
Logistics economics and injection system compatibility shape competitive positioning across physical form factors.
- Liquid:Standard pump and injector compatibility sustains majority procurement across European terminals, with established distribution networks favoring incumbent supply arrangements.
- Concentrated:Airlines and marine operators are adopting high-active packages to reduce transport costs and storage footprint, creating formulation specialization openings for additive houses with dilution logistics expertise.
- Emulsified:Water-fuel emulsion additives serve niche industrial combustion applications with NOx reduction specifications in Southern European manufacturing clusters.
- Powder:Solid additive forms occupy limited aviation ground handling and remote marine bunkering applications where liquid logistics prove impractical.
Liquid formulations hold installed capacity. Concentrated packages are rotating up the share rankings.
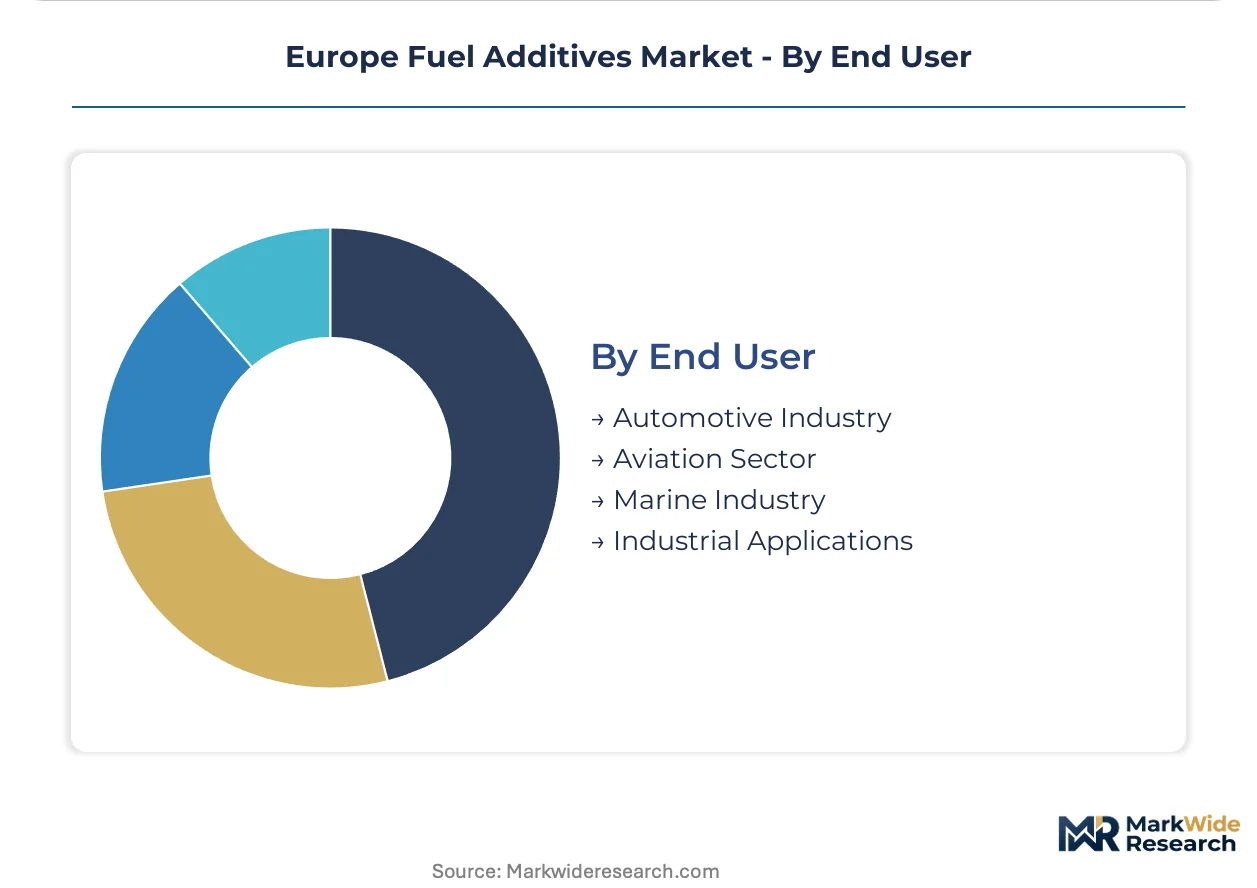
End User:
Procurement authority fragments between integrated oil companies, independent blenders, and fleet operators with diverging technical service requirements.
- Automotive Industry:OEM specification setting and warranty linkage creates captive demand for certified deposit control additives, with German and Italian vehicle manufacturers driving formulation standards.
- Marine Industry:Vessel operators and fuel suppliers share procurement authority for IMO compliance packages, with North Sea route concentration creating volume aggregation opportunities.
- Aviation Sector:Airlines and into-plane service providers specify jet fuel additives under IATA guidance, with concentrated packages gaining traction for operational efficiency.
- Industrial Applications:Power generation and heating oil segments follow automotive and marine specification trends with delayed adoption cycles and price-sensitive procurement.
Automotive industry demand holds installed capacity. Marine industry procurement is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA registration requirements under REACH govern substance authorization across the continent, directly shaping which chemistries remain commercially viable for additive producers serving European blenders.
Germany
Refinery upgrading activity and automotive OEM compliance specifications concentrate demand for deposit control additives in the country's fuel blending infrastructure. The EU Green Deal's transport decarbonization trajectory tightens carbon intensity benchmarks for transport fuels. Ludwigshafen and the broader Rhine-Neckar chemical cluster anchor manufacturing capacity for detergent and dispersant chemistries serving domestic and export markets.
United Kingdom
Marine operators across North Sea routes expand procurement of detergent-dispersant packages to treat very low sulfur fuel oil and maintain engine cleanliness. FuelEU Maritime standards interact with national renewable blending mandates to create specification complexity for bunker fuel suppliers. London and the Thames Estuary logistics corridor aggregate procurement authority for IMO compliance packages among vessel operators and fuel suppliers.
Netherlands
Independent fuel blending capacity in the Rotterdam-Antwerp corridor creates volume aggregation opportunities for additive houses with distribution reach. The F-Gas Regulation compresses fluorinated surfactant availability for fuel system corrosion inhibitors, forcing reformulation investments. The Port of Rotterdam serves as the primary entry point for marine fuel additive packages distributed across Northwest European bunkering networks.
Poland
Independent fuel blending capacity expansion offers additive suppliers underpenetrated distribution channels outside established German and Benelux networks. Cetane improver demand from heavy-duty diesel fleets accelerates adoption of organometallic combustion enhancers across Central European transport corridors. The Upper Silesian industrial zone and Warsaw logistics hub concentrate procurement activity for transport fuel treatment.
Italy
Fuel marketing unbundling has created new blender entrants seeking direct additive supply arrangements, displacing fragmented distributor networks in Southern European markets. REACH registration costs and data requirements create capital barriers for smaller additive producers seeking market access. The Milan-Turin-Genoa industrial triangle and Adriatic port cluster anchor procurement relationships for premium multi-functional additive packages.
Europe Fuel Additives Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding captive feedstock supply and the latter competing on formulation agility. BASF SE leverages its Ludwigshafen manufacturing complex to sustain captive supply chains for detergent and dispersant chemistries. The competitive terrain rewards backward integration into active ingredient production and control over distribution networks reaching independent fuel blenders. Two dominant competitive moves define current rivalry: strategic partnerships securing volume commitments from consolidating blender networks, and portfolio diversification into concentrated packages for aviation and marine logistics efficiency.
Within the integrated multinational tier, BASF SE and Evonik Industries AG exemplify divergent strategic positions. BASF anchors its position through captive manufacturing infrastructure at scale. Evonik occupies a specialization vector in organometallic catalyst technologies. The Lubrizol Corporation represents the distribution-control archetype, competing through network reach rather than feedstock integration. These three companies illustrate how competitive advantage in European fuel additives derives from distinct capability configurations rather than uniform scale economics.
| Leading Market Players |
|---|
| BASF SE |
| The Lubrizol Corporation |
| Afton Chemical |
| Infineum International Limited |
| Evonik Industries AG |
| LANXESS |
| Clariant |
| Chevron Corporation |
| Innospec Inc. |
| Others |
Supply & Pricing Matrix
REACH registration requirements administered by ECHA simultaneously gate supply qualification and stratify price tiers, as substance authorization costs create capital barriers that only integrated producers can absorb while passing compliance premiums to specification-critical buyers.
Pricing Analysis
Price spreads between German and Polish additive procurement run 15-25% depending on volume scale and technical service bundling. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified deposit control packages from generic detergent formulations and unbranded commodity blends. Cost compression in the standard tier is intensifying because independent blenders in Poland and Czech Republic are consolidating procurement to extract volume discounts. Fleet operators represent the most price-sensitive segment, while marine fuel suppliers accepting IMO 2020 liability exposure show lowest sensitivity due to warranty-linked specification requirements.
Supply Chain Analysis
Rotterdam port congestion and Rhine water level volatility create intermittent chokepoints for additive concentrate movements into Central European blending terminals. Manufacturing gravity centers on Germany, Netherlands, and Belgium, with the Ludwigshafen and Antwerp chemical clusters anchoring active ingredient production. Formulation draws from polyisobutylene succinimide feedstocks, organometallic precursors, and Group II/III carrier base oils. Single-source vulnerability concentrates in manganese and iron-based cetane improver precursors where Evonik maintains dominant organometallic synthesis capacity. Distribution runs through Rotterdam-Antwerp pipeline networks reaching independent blenders across the continent.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
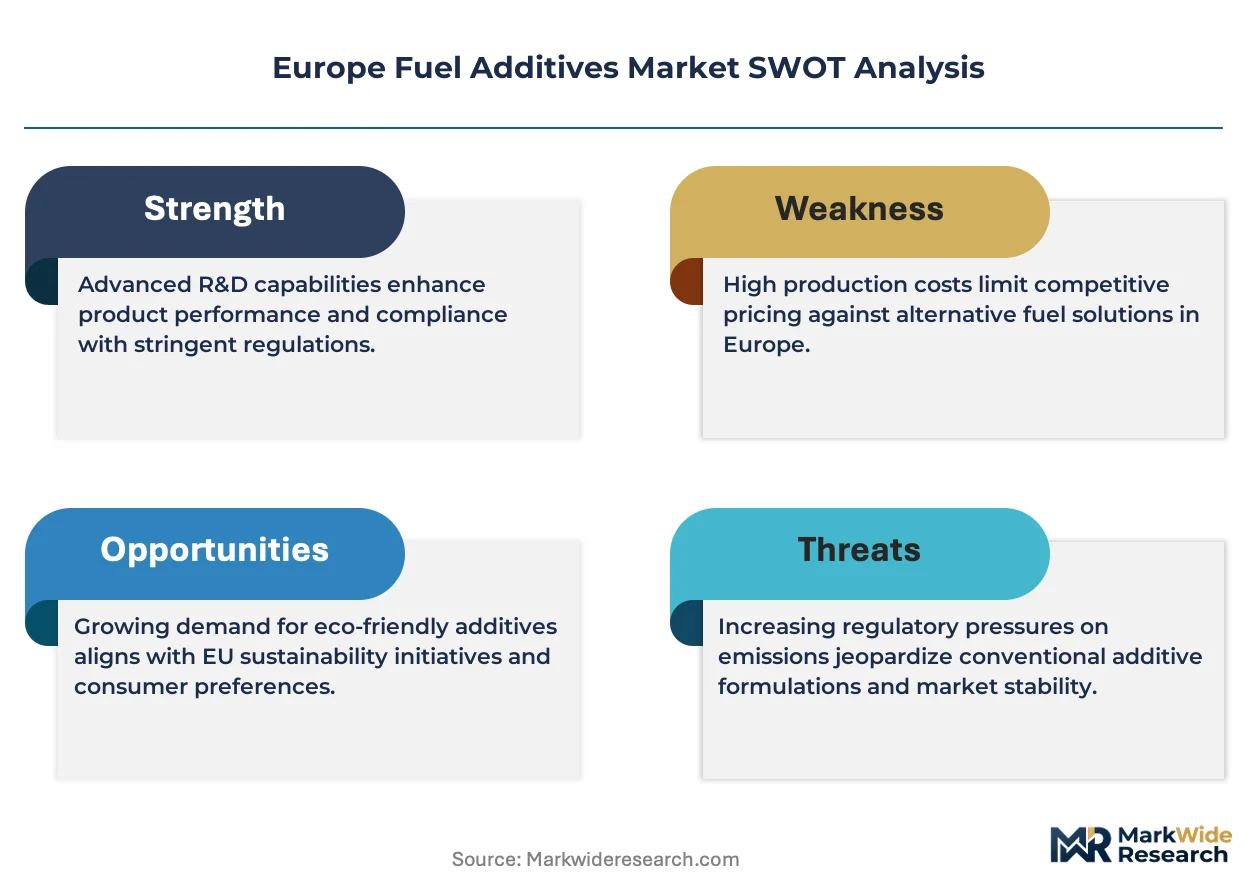
FuelEU Maritime standards and renewable blending mandates are creating platform-economics inflection, as interoperability between conventional additive packages and biofuel-compatible reformulations becomes the decisive competitive dimension.
For Market Incumbents: Consolidate backward integration into polyisobutylene succinimide feedstock production to defend margin position against merchant-dependent specialists. Lock in long-term offtake agreements with Rotterdam-Antwerp corridor blenders before channel compression completes. The threat of biofuel substitution in Scandinavian markets demands accelerated R&D investment in biodiesel stabilizer chemistries.
For New Entrants and Emerging Players: Anchor in Poland and Czech Republic independent blending capacity expansion, the most penetrable geography outside established German-Benelux networks. Target concentrated package formulation for aviation sector procurement, where weight-efficiency specifications create specialist openings against liquid-dominant incumbents. Pursue direct technical service relationships with new blender entrants in Italy's unbundled fuel marketing sector.
For Investors and Strategic Acquirers: FuelEU Maritime implementation reshapes the acquisition landscape toward additive houses with renewable marine fuel compatibility portfolios. Long-term viability favors targets with captive organometallic synthesis expertise and REACH-registered substance libraries. The signal to watch is CEC qualification timeline compression, which will strand development-stage products lacking certified engine test data.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PIB Feedstock | BASF's Ludwigshafen complex demonstrates how captive succinimide supply insulates margin from merchant volatility. |
| Concentrated Package Development | Aviation sector procurement shifts toward high-active formulations that reduce jet fuel logistics weight and volume. |
| REACH Registration Portfolio Expansion | ECHA substance authorization costs create defensive moats against smaller competitors lacking capital for data generation. |
| Direct Blender Relationship Consolidation | Channel compression in Italy and Spain displaces fragmented distributors with volume-commitment partnerships. |
| Biofuel Compatibility Reformulation | F-Gas Regulation and renewable diesel penetration force corrosion inhibitor substitution away from fluorinated surfactants. |
Research Methodology
Initial hypotheses were tested against primary input from refinery technology directors, marine fuel procurement managers, automotive OEM fuel system engineers, and independent blender operations heads, and refined through secondary validation against ECHA registration databases, EU MRV carbon reporting filings, CEC engine test protocol documentation, and customs trade data for additive concentrate movements. Bottom-up segment sizing triangulated against top-down fuel consumption projections across the analysis window.
Variance decomposition across type, application, formulation, and end-user dimensions structured the analytical framework, with CAGRs derived from elasticity-adjusted demand curves and substitution modeling for biofuel penetration scenarios. Industry-specific forecast inputs incorporated IMO sulfur cap compliance timelines, FuelEU Maritime carbon intensity benchmarks, and automotive OEM specification revision cycles.
Decision-makers should treat outputs as directional under assumptions of stable REACH authorization timelines and continued Rhine corridor logistics access; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Texture Modifier Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Global Scale Inhibitors Market
Additives
Defoaming Coating Additives Market
Additives
Water-Borne Coating Additives Market
Additives
Cetane Improver Additives Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Iso-Butyric Acid Market
Additives
Europe Citric Acid Market
Additives
Pectin Market
Additives
Binder Excipients Market
Additives
Global PVC Additives Market
Additives
Rosin Ester Market
Additives
Polyols and Sorbitols Products Market
Additives
Cement Grinding Aid and Performance Enhancers Market
Additives
Sodium Citrate Anhydrous Market