
 Gestational Trophoblastic Disease Market | 2026-2036
Gestational Trophoblastic Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Gestational Trophoblastic Disease Market Intelligence
The shift towards targeted immunotherapy is reconfiguring treatment protocols for chemo-resistant choriocarcinoma. This evolution moves beyond traditional cytotoxic agents. Pfizer Inc. leverages its oncology pipeline to develop novel immunotherapies for rare gynecological cancers. Sanofi sustains its market presence through a broad portfolio of established chemotherapy drugs, while Bristol-Myers Squibb competes on the strength of its checkpoint inhibitor research.
Gestational trophoblastic disease encompasses a group of rare tumors arising from placental tissue following conception. These conditions are characterized by abnormal proliferation of trophoblastic cells, with human chorionic gonadotropin (hCG) serving as a critical serum biomarker for diagnosis and monitoring. Within therapy areas, hydatidiform mole represents the most common and treatable form, while choriocarcinoma requires more aggressive multi-agent chemotherapy. Treatment is predominantly administered in specialized hospitals and oncology centers, which command the majority of spending on chemotherapy drugs and surgical equipment.
Market access for new therapies depends on navigating stringent clinical trial requirements set by regulators like the United States FDA and the European Medicines Agency (EMA). In parallel, China's NMPA is aligning its approval pathways for orphan drugs with international standards, influencing regional development strategies. The key decision for drug developers is balancing investment between single-agent regimens for common subtypes and complex combination therapies for resistant disease.
Market Dynamics
The core market dynamic is the scientific and economic divergence between therapies for common versus rare forms of gestational trophoblastic disease. This split influences everything from research funding to hospital procurement, creating a bifurcated landscape for drug development and patient access.
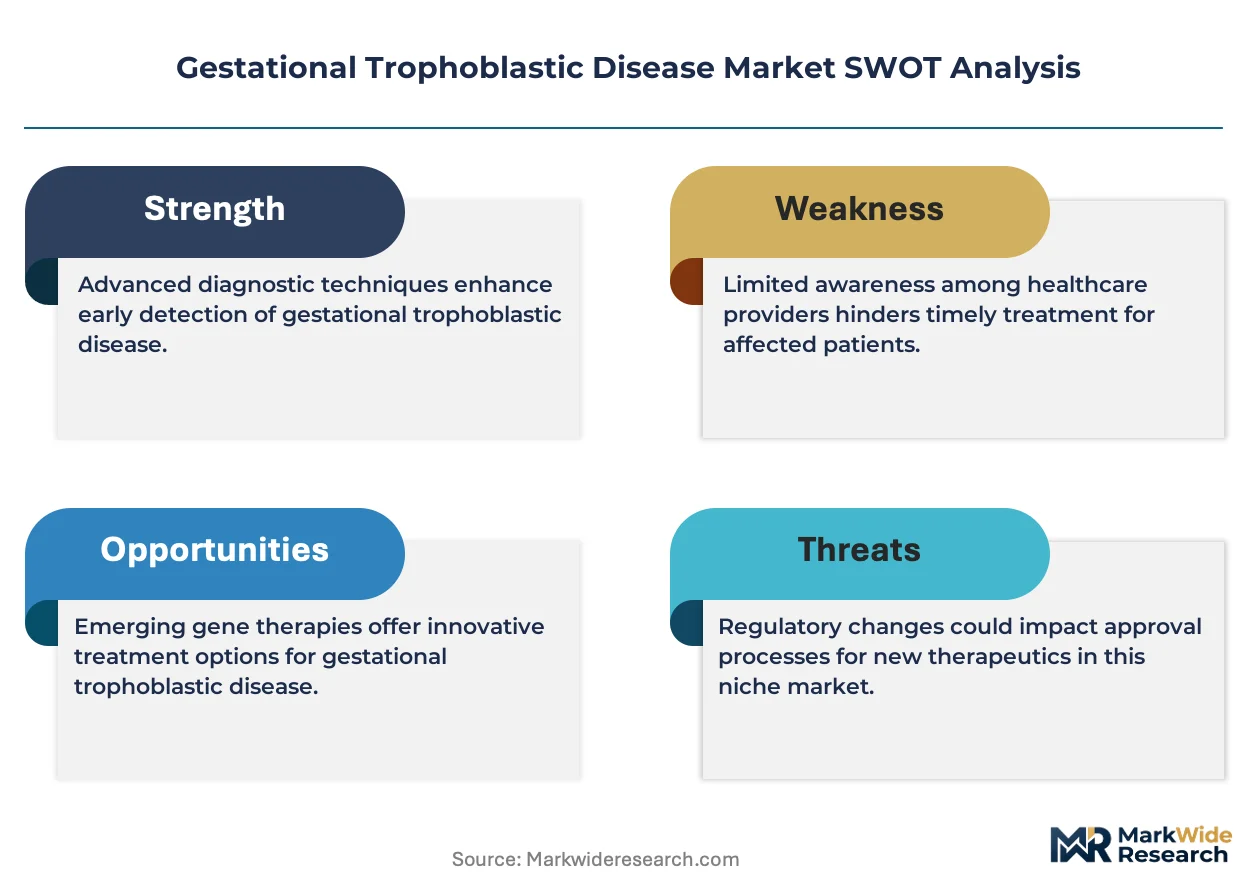
Growth Catalysts
- Public Health Initiatives:China's national programs promoting early cancer screening for women are increasing the incidental detection of GTD, driving demand for diagnostic services and first-line treatments.
- Diagnostic Technology:The integration of next-generation sequencing into clinical workflows improves the diagnostic accuracy for rare subtypes, enabling more precise and earlier therapeutic intervention.
- Specialized Centers:Growing patient volumes at specialized hospitals and oncology centers concentrate purchasing power for advanced chemotherapy drugs and diagnostic equipment, supporting premium product segments.
Market Restraints
- Therapy Cost Structure:The high development and administration costs of novel immunotherapies for chemo-resistant choriocarcinoma limit their use to well-funded healthcare systems and specialized centers.
- Regulatory Hurdles:Navigating stringent clinical trial requirements for orphan drug indications, as mandated by the FDA and EMA, creates significant delays and costs for new therapy approvals.
- Patient Cohort Size:The extreme rarity of subtypes like placental site trophoblastic tumor makes it statistically challenging to conduct large-scale clinical trials, hindering evidence-based therapy development.
Strategic Opportunities
- Regulatory Harmonization:China's NMPA aligning its orphan drug approval pathways with international standards opens a faster route to market for therapies targeting a large patient population.
- Liquid Biopsy Development:The advancement of non-invasive liquid biopsies to monitor treatment response via circulating tumor DNA could complement or partially replace frequent hCG serum testing.
- Indication Expansion:Checkpoint inhibitors validated in resistant choriocarcinoma can be investigated for other rare gynecological malignancies that share similar molecular markers, expanding the addressable market.
Industry Challenges
- Pathology Skill Gaps:A global shortage of pathologists with deep expertise in identifying rare GTD subtypes can lead to misdiagnosis, delaying appropriate and timely treatment initiation.
- Data Integration Complexity:Implementing the IT infrastructure and training needed to integrate complex genomic data from NGS into routine hospital workflows remains a significant barrier to adoption.
- Protocol Standardization:The absence of globally standardized treatment guidelines for the rarest forms of GTD complicates international research collaboration and the comparison of clinical outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gestational Trophoblastic Disease Market |
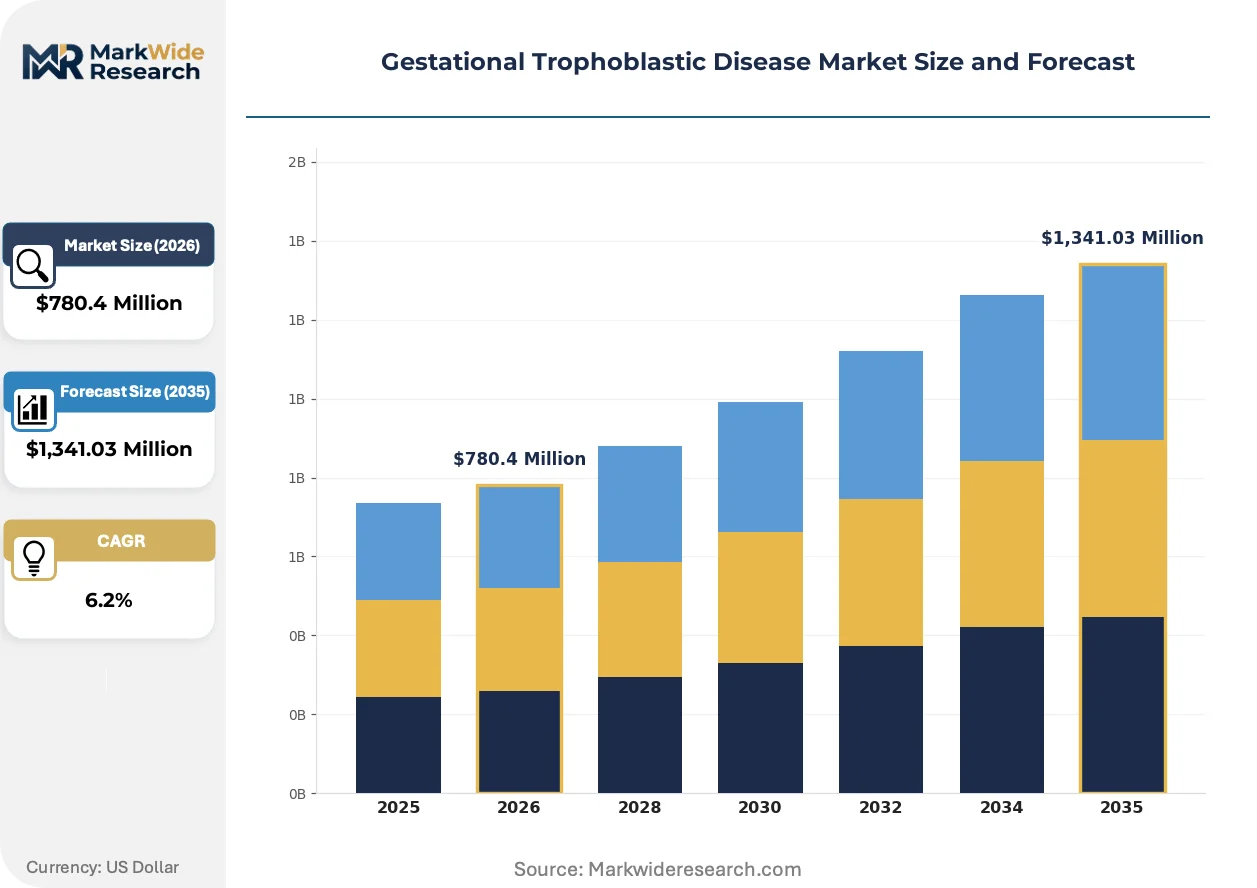
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,341.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Chemotherapy Drugs, Surgery Equipment, Follow-up Monitors Therapy Area: Hydatidiform Mole, Invasive Mole, Choriocarcinoma, Placental Site Trophoblastic Tumor End User: Oncology Centers, Gynecology Clinics, Research Laboratories, Specialized Hospitals Treatment Modality: Single-agent Chemotherapy, Multi-agent Chemotherapy, Surgical Resection, Immunotherapy |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Sanofi, Pfizer Inc., Amgen Inc., Bayer AG, Bristol-Myers Squibb Company, Hikma Pharmaceuticals PLC, Merck, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gestational Trophoblastic Disease Market Strategic Shifts & Innovations
Precision medicine is fundamentally altering the GTD treatment paradigm. This evolution moves beyond a one-size-fits-all chemotherapy approach, instead leveraging advanced diagnostics to stratify patients and tailor interventions based on specific tumor biology and resistance profiles.
Next-generation sequencing provides a detailed genomic map of trophoblastic tumors, identifying specific mutations that may predict response or resistance to therapy. Specialized oncology centers are increasingly adopting these comprehensive panels for patients with high-risk or recurrent disease. This diagnostic insight is hybridizing treatment selection, combining traditional hCG biomarker monitoring with molecular data to rationalize the use of targeted immunotherapies over standard chemotherapy.
Orphan drug designations, offered by regulators like the United States FDA and the European Medicines Agency, provide critical incentives for GTD therapeutic development. These policies offer benefits such as market exclusivity and accelerated review timelines, which significantly de-risk the high cost of R&D for rare diseases. The chemo-resistant choriocarcinoma segment is most affected, as developers now have a more viable commercial pathway for novel immunotherapies and other targeted agents.
Centralization of care is concentrating the management of GTD patients within a few high-volume, specialized referral centers. This model disrupts the historical pattern of treatment by local, non-specialist oncologists, who now refer complex or high-risk cases earlier in the diagnostic process. This consolidation of expertise and patient volume is most pronounced in countries with national health systems, such as the United Kingdom, where regional centers of excellence are formally designated for GTD management.
Gestational Trophoblastic Disease Market Segmentation
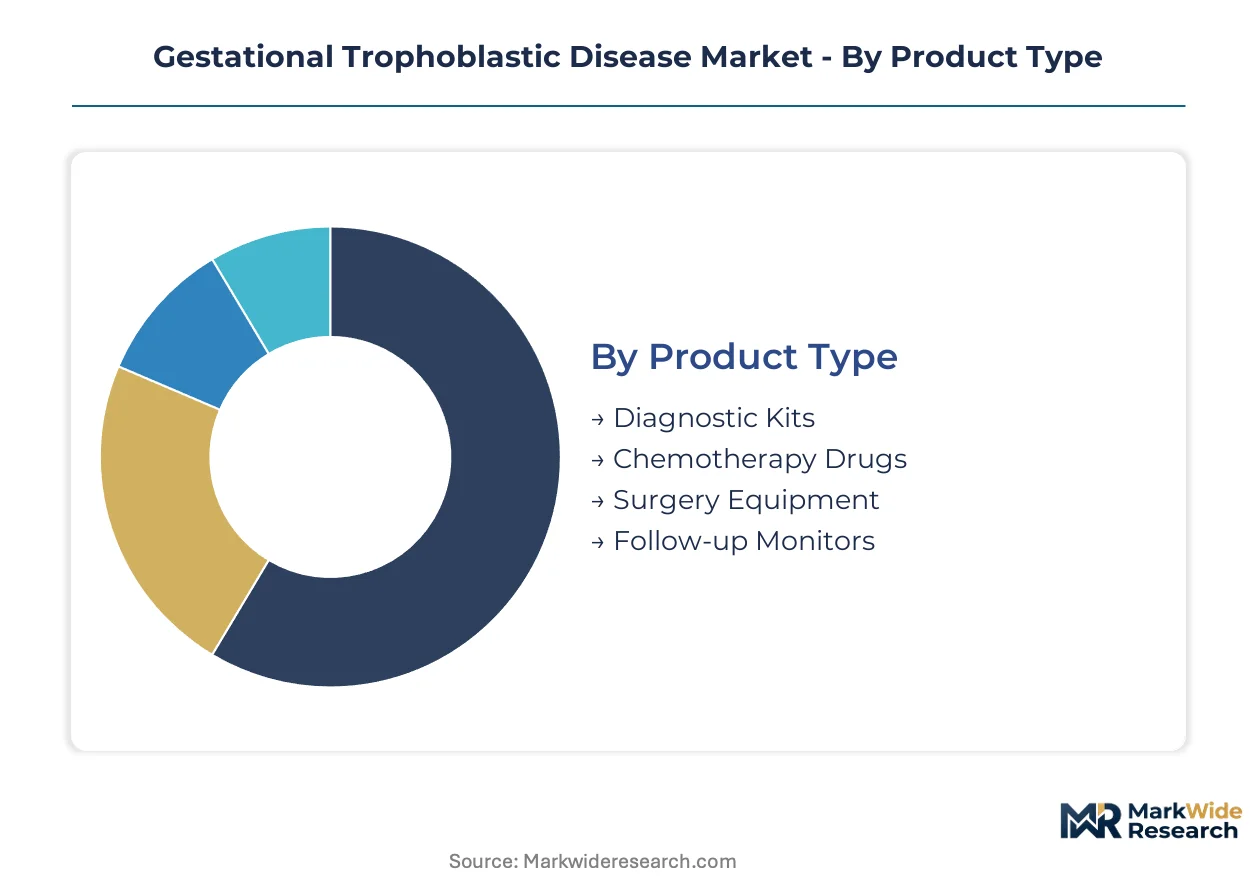
The Gestational Trophoblastic Disease market segmentation reflects the diverse clinical needs and technological advancements driving patient care. This analysis delineates the critical components of diagnosis, treatment, and monitoring for these rare placental tumors. Understanding these segments is essential for strategic planning.
Product Type:
The product type segmentation addresses the full spectrum of tools and pharmaceuticals used from initial detection through long-term patient surveillance.
- Chemotherapy Drugs:This category includes cytotoxic agents like methotrexate, etoposide, and actinomycin D, which form the backbone of treatment for various GTD forms. Procurement for these drugs is concentrated in specialized hospitals, which manage complex choriocarcinoma cases.
- Diagnostic Kits:These kits utilize assays for human chorionic gonadotropin (hCG) and molecular markers, providing crucial data for early detection and disease classification. Demand concentrates in public health initiatives in China, where early cancer screening drives their utilization.
- Surgery Equipment:Surgical instruments facilitate procedures such as dilation and curettage (D&C) for hydatidiform mole evacuation or hysterectomy in select, aggressive cases.
- Follow-up Monitors:These devices and tests enable continuous surveillance of hCG levels post-treatment, ensuring early detection of recurrence.
Established volume favors Chemotherapy Drugs; emerging adoption favors Diagnostic Kits.
Therapy Area:
The therapy area segmentation distinguishes GTD based on its specific pathological presentation and clinical aggression, guiding tailored treatment protocols.
- Choriocarcinoma:This highly malignant form requires aggressive multi-agent chemotherapy regimens due to its metastatic potential and rapid progression. Treatment protocols for chemo-resistant choriocarcinoma are shifting towards targeted immunotherapy.
- Hydatidiform Mole:Representing the most common and treatable GTD form, it primarily involves abnormal placental tissue growth and is typically managed by surgical evacuation. Specialized hospitals manage the majority of these cases, especially those with high-risk features.
- Invasive Mole:This condition involves myometrial invasion by hydatidiform mole tissue, necessitating closer monitoring and often chemotherapy.
- Placental Site Trophoblastic Tumor:This rare, aggressive subtype is characterized by localized tumor growth and requires distinct management strategies, often including surgery.
The steepest expansion trajectory is observed in Choriocarcinoma treatment, while Hydatidiform Mole maintains a substantial volume base for initial interventions.
End User:
The end user segmentation highlights the varied institutional settings responsible for GTD patient management, ranging from specialized treatment to fundamental research.
- Specialized Hospitals:These institutions serve as primary referral centers for complex GTD cases, concentrating expertise and advanced treatment capabilities. They command the majority of spending on advanced chemotherapy drugs and surgical equipment.
- Oncology Centers:Dedicated to cancer treatment, these centers provide comprehensive care for malignant GTD forms, including multi-agent chemotherapy and follow-up. Patient volumes at these centers support premium product segments.
- Gynecology Clinics:These clinics often represent the first point of contact for patients, handling initial diagnoses and managing less complex GTD cases.
- Research Laboratories:These facilities focus on understanding GTD pathogenesis, developing new diagnostic markers, and evaluating novel therapeutic targets.
Demand concentration is highest in Specialized Hospitals, with Research Laboratories representing a niche but growing segment for innovation.
Treatment Modality:
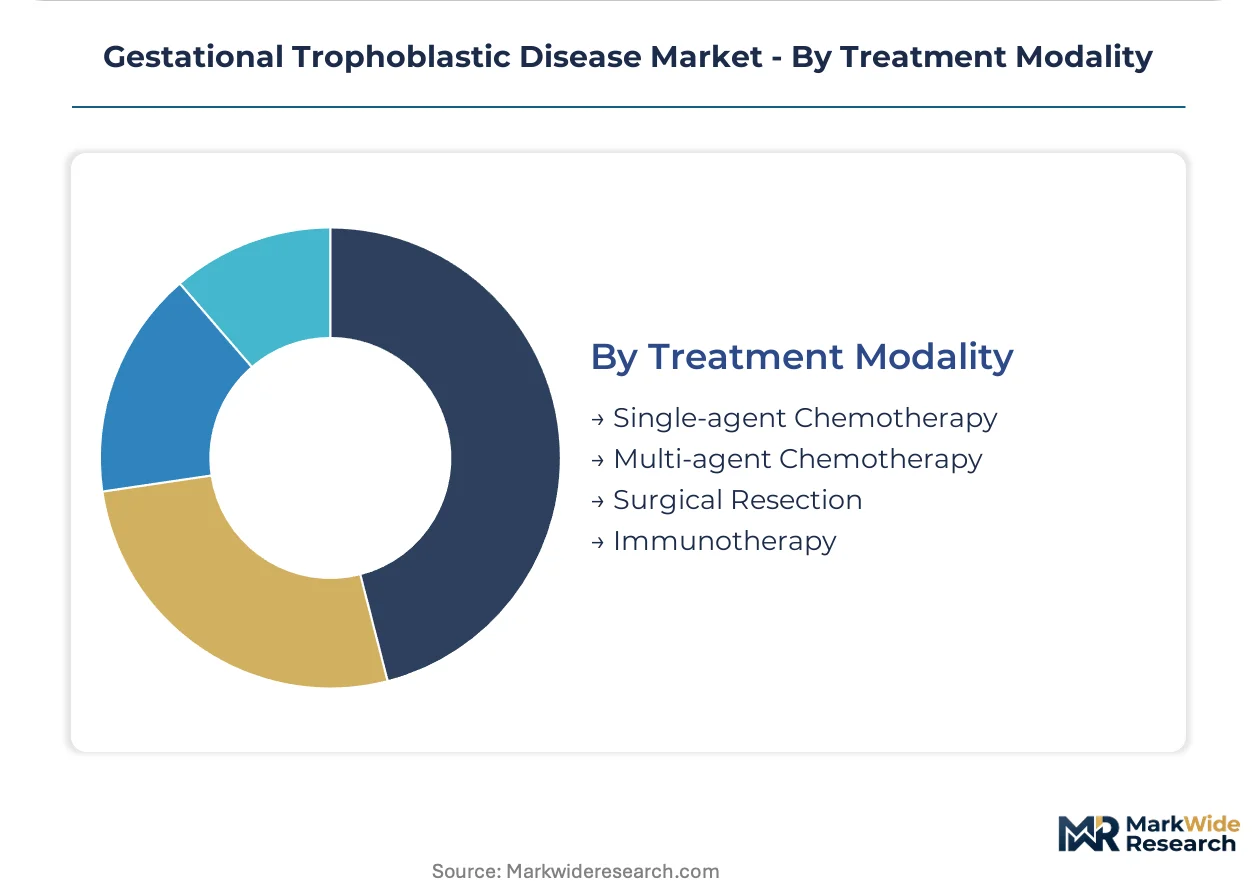
The treatment modality segmentation delineates the diverse therapeutic approaches employed, from traditional surgical removal to advanced targeted interventions.
- Multi-agent Chemotherapy:This aggressive regimen combines several cytotoxic drugs to treat high-risk and metastatic choriocarcinoma. This approach is central to managing resistant disease.
- Immunotherapy:This emerging modality, particularly checkpoint inhibitors, targets the immune system to combat chemo-resistant choriocarcinoma. Pfizer Inc. and Bristol-Myers Squibb are leveraging their oncology pipelines in this area.
- Surgical Resection:This involves the physical removal of trophoblastic tissue, commonly for hydatidiform moles or localized tumors.
- Single-agent Chemotherapy:This less intensive chemotherapy approach is often used for low-risk GTD or as maintenance therapy.
The market for Surgical Resection remains mature, while Immunotherapy is experiencing significant innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, a primary hub for pharmaceutical innovation, influences global treatment protocols for gestational trophoblastic disease. Advanced diagnostic techniques and novel immunotherapies developed there often set benchmarks for adoption worldwide. This scientific exchange underpins global market dynamics.
United States
Demand for advanced diagnostics and immunotherapies drives market expansion. The FDA's orphan drug designation provides significant incentives for GTD therapeutic development. Specialized oncology centers in Boston and Houston focus on complex choriocarcinoma cases.
China
Public health initiatives promoting early cancer screening for women increase GTD detection rates. The NMPA aligns its orphan drug approval pathways with international standards, facilitating market entry. Major urban centers like Shanghai and Beijing see concentrated demand for diagnostic kits.
Germany
A sophisticated healthcare system supports high utilization of advanced GTD treatments. The European Medicines Agency (EMA) influences therapy approval across the continent. Specialized university hospitals in Munich and Heidelberg manage complex GTD patient cohorts.
Japan
Early detection programs and a strong focus on precision medicine shape the GTD market. The PMDA streamlines approval processes for innovative therapies. Research institutions in Tokyo contribute to understanding rare GTD subtypes.
India
Rising healthcare infrastructure development and increasing awareness contribute to market growth. The CDSCO regulates pharmaceutical products, ensuring treatment quality. Major metropolitan areas like Mumbai and Delhi are expanding their specialized oncology services.
Gestational Trophoblastic Disease Market Key Industry Players
Channel-controlling players compete with product-specialist players across the gestational trophoblastic disease market. The market structure exhibits a tiered consolidation, where large pharmaceutical companies dominate the chemotherapy and emerging immunotherapy segments. Diversified oncology leaders represent one strategic archetype, focusing on broad treatment portfolios. Specialized diagnostic innovators form another archetype, driving precision medicine advancements. Companies primarily engage in portfolio diversification and strategic partnerships to strengthen their market presence and expand geographic reach.
Diversified pharmaceutical giants like Pfizer Inc. and Sanofi exemplify the market's oncology leadership. Pfizer Inc. actively leverages its extensive oncology pipeline to develop novel immunotherapies for rare gynecological cancers, reflecting a focus on innovation. Sanofi sustains its market presence through a broad portfolio of established chemotherapy drugs, anchoring the traditional treatment segment. Bristol-Myers Squibb Company also occupies a significant position, driven by its robust checkpoint inhibitor research. These companies collectively shape the therapeutic landscape through their extensive R&D capabilities and global distribution networks for both conventional and advanced treatments.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Sanofi |
| Pfizer Inc. |
| Amgen Inc. |
| Bayer AG |
| Bristol-Myers Squibb Company |
| Hikma Pharmaceuticals PLC |
| Merck |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
Specialized hospital capacity utilization, particularly for advanced diagnostics and treatments, drives both supplier behavior and pricing posture in the Gestational Trophoblastic Disease market. High demand for complex case management in these centers sustains premium pricing for novel therapies and specialized equipment. Conversely, high-volume diagnostic kit procurement is influenced by public health initiative scale.
Pricing Analysis
Cost-plus contract patterns with indexation to active pharmaceutical ingredient (API) costs govern much of the chemotherapy drug segment. Price differentiation stems from regulatory approval status (e.g., FDA or EMA designation) and the complexity of drug formulation. Pricing softness affects generic cytotoxic agents due to volume purchasing by hospital groups. Specialized hospitals are less price-sensitive for novel immunotherapies, while gynecology clinics prioritize cost-effective diagnostic kits.
Supply Chain Analysis
Specialized contract manufacturers hold capacity for complex biologic production, particularly for novel immunotherapies. Geographic supply concentration for pharmaceutical APIs centers on India and China, while specialized diagnostic reagents often source from Europe and the United States. Raw material dependencies include specific chemical precursors for cytotoxic agents and highly purified antibodies for diagnostic assays. Regulatory divergence across major markets presents a structural supply chain risk. Distribution runs through specialized pharmaceutical wholesalers and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gestational Trophoblastic Disease market faces a significant challenge from a global shortage of pathologists with expertise in identifying rare GTD subtypes, creating capability scarcity.
For Market Incumbents:Harden existing market positions by investing in advanced R&D for chemo-resistant choriocarcinoma, especially checkpoint inhibitors. Diversify oncology pipelines to address multiple rare gynecological cancers, mitigating the threat of single-product reliance. Leverage global distribution networks to ensure broad market access for established chemotherapy drugs. Pursue strategic partnerships with specialized oncology centers to secure preferred formulary status for novel therapies.
For New Entrants and Emerging Players:Build out diagnostic technology platforms, focusing on next-generation sequencing and liquid biopsy for rare GTD subtypes. Target underpenetrated segments like advanced molecular diagnostics in developing markets, leveraging regulatory harmonization in regions like China. A specific go-to-market angle involves partnering with research laboratories to develop companion diagnostics that predict immunotherapy response. Focus on patient stratification tools to demonstrate clear clinical value.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized diagnostic innovators with strong intellectual property in precision medicine. Long-term viability rests on the shift towards targeted therapies and early detection. Identify acquisition targets with robust pipelines for orphan drug designations or established relationships with high-volume specialized hospitals. The signal to watch is successful clinical trial data for novel immunotherapies in rare, resistant GTD forms.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates regulatory approval for novel immunotherapies targeting chemo-resistant choriocarcinoma. |
| Regulatory Approval Pathway | Secures orphan drug designations, providing market exclusivity and accelerated review for rare GTD treatments. |
| Licensing Agreement | Expands market access for specialized diagnostic kits in regions with evolving public health initiatives. |
| Manufacturing Scale-Up | Ensures consistent supply of critical chemotherapy drugs and novel biologics to specialized hospitals. |
| Pipeline Diversification | Mitigates R&D risk by addressing multiple rare gynecological malignancies beyond core GTD indications. |
Research Approach
The analysis maps Gestational Trophoblastic Disease sub-sectors, each validated through extensive interviews with oncologists, pathologists, and hospital procurement managers. Primary research involved discussions with regulatory affairs specialists to understand market access dynamics. Secondary data sources included FDA filings, EMA submissions, ClinicalTrials.gov, and public health reports from China's NMPA, triangulating bottom-up and top-down market insights.
The forecast framework holds macroeconomic conditions and major healthcare policy structures fixed across the analysis window, while varying assumptions for technological adoption and treatment protocol evolution. Segmentation dimensions modeled include Product Type, Therapy Area, End User, Treatment Modality, and regional regulatory frameworks. Compound annual growth rates were derived from historical data and projected trends in hCG biomarker testing and orphan drug designation rates over the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified pharmaceutical giants or specialized diagnostic innovators would shift outcomes. Forecasts reflect assumptions regarding clinical trial success rates and regulatory approval timelines. Quarterly review of clinical trial milestones and major regulatory decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Morgellons Disease Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Global Human Embryonic Stem Cells Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Humanized Liver Mice Model Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Nanomedicine Market