
 Breast Tissue Markers Market | 2026-2036
Breast Tissue Markers Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Tissue Markers Market Analysis
Hospital procurement channels is rewriting how breast tissue markers reach end users, with group purchasing organizations consolidating vendor lists and squeezing out regional distributors. Hologic leverages its installed base of mammography systems to bundle marker sales with imaging contracts. BD anchors its position through deep relationships with interventional radiology departments across integrated delivery networks. Merit Medical competes on customization, offering site-specific configurations for high-volume biopsy centers.
Breast tissue markers are implantable devices placed during percutaneous biopsy to denote lesion location for subsequent surgical excision or radiotherapy planning, typically manufactured from titanium, stainless steel, or bioabsorbable polymers with dimensions under 5 millimeters to minimize migration risk. The material dimension shows titanium markers commanding premium placement in academic medical centers due to MRI compatibility, while bioabsorbable polymers gain traction in value-oriented settings seeking to eliminate secondary removal procedures. Among applications, tumor localization generates the densest margin pools as preoperative wire replacement protocols expand, whereas diagnostic imaging represents the mature baseline where price per unit faces sustained compression.
The FDA's 510(k) clearance pathway for permanent implantables and the EU MDR's tightened clinical evidence requirements for Class IIb devices collectively extend development timelines and elevate compliance spending for manufacturers seeking dual-market access. ISO 13485 quality management certification has become table stakes rather than differentiator, forcing mid-tier suppliers to absorb audit costs without pricing power recovery. Stakeholders must monitor how CMS reimbursement adjustments for image-guided biopsy procedures reshape purchasing authority between hospital materials management and physician preference item committees.
Market Dynamics
Wire-free localization systems are compressing replacement cycles across oncology departments, as facilities retire clip-and-wire protocols in favor of magnetic seed and radar-based alternatives that integrate with existing imaging infrastructure.
Growth Catalysts
- Preoperative Wire Replacement Protocols:Academic medical centers in the United States are standardizing non-palpable lesion marking through magnetic seed deployment, eliminating same-day scheduling constraints and reducing positive margin rates.
- FDA 510(k) Streamlining for Predicate Devices:Manufacturers leveraging substantial equivalence claims for titanium-based markers are compressing clearance timelines, accelerating competitive entry into the permanent implantable category.
- Dual-Energy Mammography Diffusion:High-resolution spectral imaging is expanding detectable marker size thresholds, enabling smaller bioabsorbable polymer formulations without compromising visualization reliability.
Market Restraints
- Titanium Feedstock Concentration:Surgical-grade titanium supply channels cluster among a limited set of aerospace-qualified mills, exposing marker manufacturers to spot-price volatility and allocation rationing during defense procurement surges.
- EU MDR Clinical Evidence Burden:Class IIb reclassification of permanent implantables demands extended follow-up studies for CE marking renewal, elevating compliance spending without commensurate pricing recovery in European markets.
- Radioactive Seed Substitution:Iodine-125 brachytherapy seeds retain entrenched reimbursement codes for certain lesion types, constraining magnetic seed penetration in hospital systems with captive radiation oncology departments.
Strategic Opportunities
- Outpatient Surgery Center Expansion:Freestanding ambulatory facilities in the United States are installing dedicated breast biopsy suites, creating demand for single-use marker kits with simplified inventory profiles.
- AI-Integrated Localization Workflows:Machine learning algorithms for automated lesion tracking are converging with RFID-tagged markers, enabling real-time coordinate verification during robotic-assisted excision.
- India PLI Medical Device Incentive:Production-linked incentive schemes for domestic manufacturing of implantable devices are attracting contract manufacturers to establish ISO 13485-certified assembly operations near Mumbai and Hyderabad clusters.
Industry Challenges
- Interventional Radiology Training Bottlenecks:Deployment proficiency for non-wire localization systems requires hands-on credentialing that outpaces fellowship program expansion, constraining adoption velocity at community hospitals.
- Legacy PACS Integration Friction:Marker coordinate data formats vary across imaging vendors, forcing facilities to maintain middleware layers or manual transcription protocols that introduce scheduling delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Tissue Markers Market |
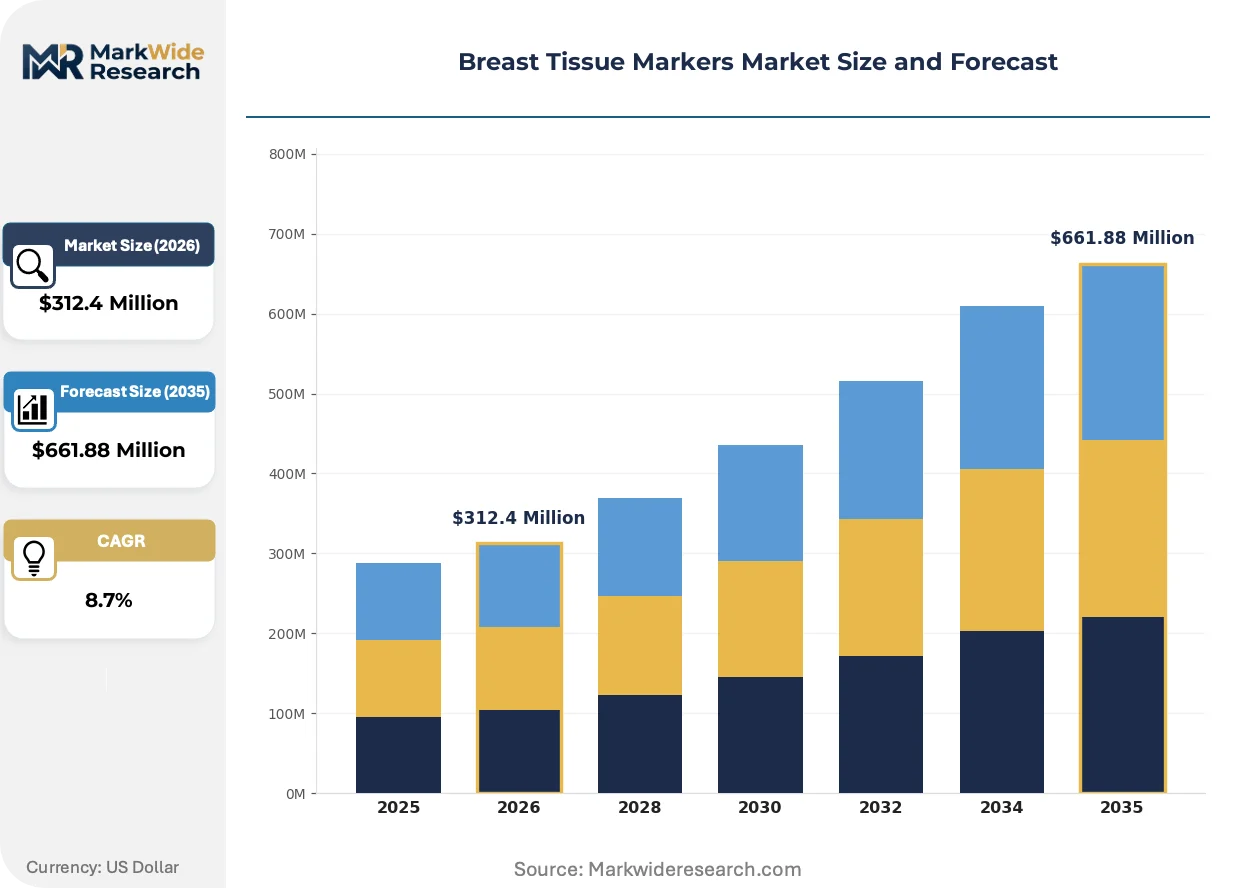
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stereotactic Markers, Ultrasound Markers, Magnetic Markers, Biopsy Markers Application: Diagnostic Imaging, Surgical Procedures, Tumor Localization, Radiotherapy End User: Hospitals, Diagnostic Centers, Research Laboratories, Oncology Clinics Material: Stainless Steel, Bioabsorbable Polymers, Titanium, Silicone |
| Companies Covered | Hologic, BD, INRAD, Carbon Medical Technologies, Mammotome, Mermaid Medical, SOMATEX Medical Technologies, Merit Medical, Argon Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Tissue Markers Market Emerging Trajectories
Localization technology is fragmenting into modality-specific ecosystems, with magnetic, radar, and radiofrequency platforms each cultivating distinct clinical adherents. This divergence is reshaping vendor competitive strategy and procurement evaluation criteria.
Magnetic seed localization is hybridizing with radar-based detection systems, creating dual-confirmation protocols that reduce false localization events. High-volume breast centers in the United States are piloting combined workflows that deploy magnetic seeds for deep lesions while reserving radar reflectors for superficial or axillary sites. This convergence is compressing the addressable market for single-technology vendors and elevating platform-agnostic distributors.
The EU MDR's tightened post-market surveillance requirements for Class IIb implantables are extending clinical evidence timelines for bioabsorbable polymer markers. Manufacturers must now demonstrate degradation kinetics through 24-month follow-up studies to maintain CE marking, favoring incumbents with established bioresorption databases over new entrants. German notified bodies are applying the most stringent interpretation, creating regulatory friction for products seeking dual US-EU market access.
Hospital materials management committees are consolidating localization device purchasing into capital equipment bundles rather than maintaining discrete physician preference item status. Integrated delivery networks in Texas and Florida are negotiating three-year sole-source agreements that tie marker supply to mammography system maintenance contracts. This concentration is marginalizing independent distributors and compressing price transparency for individual clinicians.
Breast Tissue Markers Market Segmentation
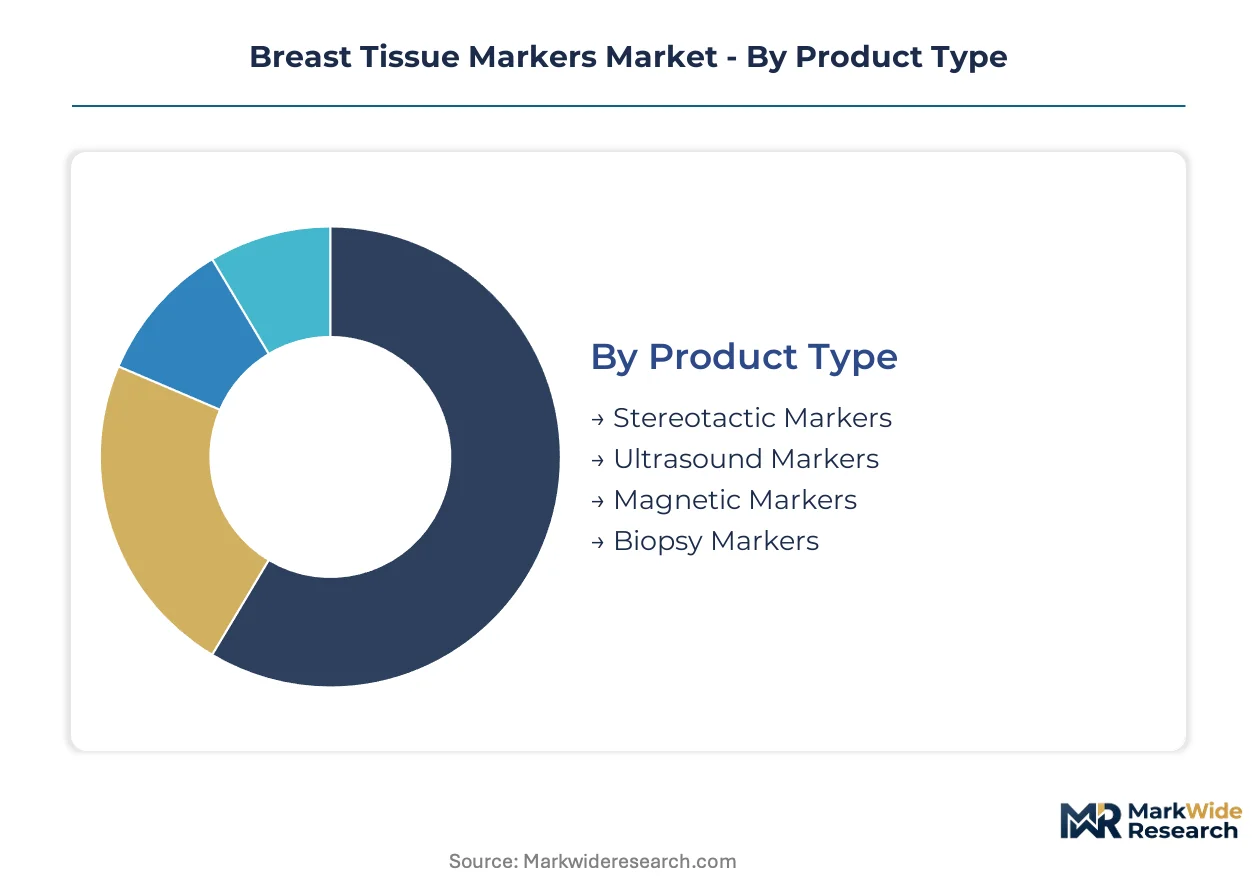
Segmentation in breast tissue markers reflects divergent clinical workflows across imaging modalities and surgical protocols. Material selection and end-user channel dynamics determine margin structures and regulatory pathways for manufacturers.
Product Type:
Cost tier differentiation separates capital-intensive magnetic platforms from commoditized biopsy accessories, with reimbursement codes reinforcing the stratification.
- Magnetic Markers:These ferrite-core devices enable wire-free localization through handheld magnetic detection probes, eliminating same-day scheduling constraints. Academic medical centers in the United States are standardizing magnetic seed deployment for non-palpable lesions, driven by reduced positive margin rates and improved patient throughput.
- Biopsy Markers:Standardized clip devices deployed post-biopsy to denote lesion coordinates for subsequent excision, typically manufactured from titanium or bioabsorbable polymers. High-volume community hospitals prioritize these for their compatibility with existing mammography infrastructure and lower per-procedure cost profiles.
- Stereotactic Markers:Precision-engineered for coordinate-based deployment under stereotactic guidance systems.
- Ultrasound Markers:Designed for real-time sonographic visualization during percutaneous biopsy procedures.
Magnetic markers hold installed capacity. Biopsy markers are rotating up the share rankings.
Application:
Maturity gradients separate established diagnostic imaging from emerging therapeutic planning workflows, with tumor localization commanding premium placement.
- Tumor Localization:Preoperative marking of non-palpable lesions to guide surgical excision or radiotherapy targeting, now displacing wire-localization protocols. Oncology clinics across integrated delivery networks are expanding magnetic seed programs, compelled by CMS reimbursement adjustments favoring outpatient same-day scheduling.
- Diagnostic Imaging:Post-biopsy clip placement for longitudinal lesion monitoring and multi-modality tracking. This segment faces sustained price compression as group purchasing organizations consolidate vendor lists and squeeze unit economics.
- Surgical Procedures:Intraoperative marker retrieval and margin verification workflows.
- Radiotherapy:Permanent implantables for boost field delineation and treatment planning.
Tumor localization is climbing the fastest. Diagnostic imaging retains volume concentration.
End User:
Customer type determines purchasing authority structures, with hospital materials management committees displacing individual physician preference in integrated networks.
- Hospitals:Inpatient and outpatient surgical departments with capital equipment bundling authority over localization device procurement. Texas and Florida health systems are negotiating sole-source agreements that tie marker supply to mammography maintenance contracts, compressing price transparency.
- Oncology Clinics:Dedicated breast centers and ambulatory surgical facilities installing dedicated biopsy suites. Freestanding centers in the United States are driving demand for simplified single-use marker kits with reduced inventory profiles.
- Diagnostic Centers:Independent imaging facilities performing screening mammography and biopsy services.
- Research Laboratories:Academic institutions evaluating novel bioabsorbable formulations and degradation kinetics.
Hospitals hold installed capacity. Oncology clinics are rotating up the share rankings.
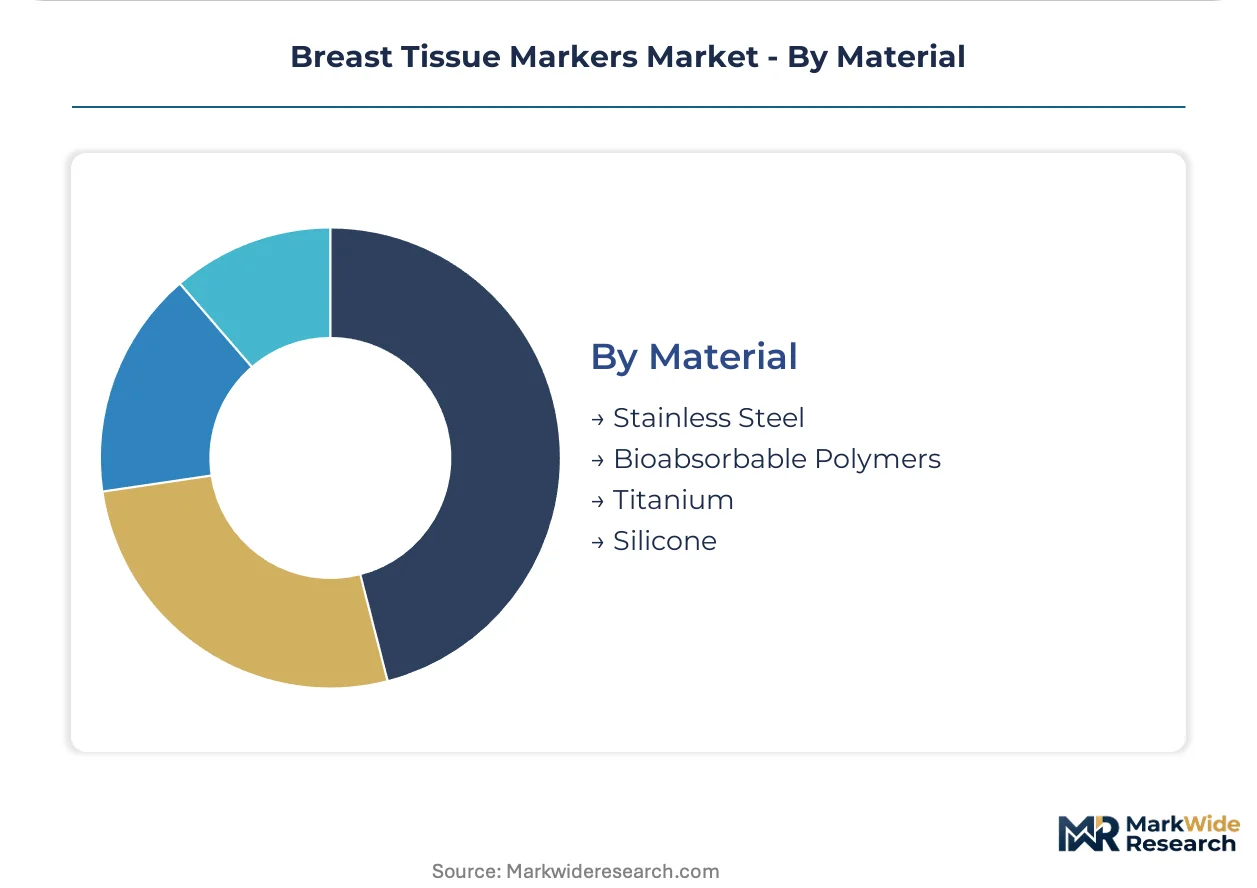
Material:
Supply concentration in aerospace-qualified titanium mills shapes cost structures, while bioabsorbable polymers attract value-oriented settings seeking elimination of secondary removal.
- Titanium:Surgical-grade implantable alloy offering MRI compatibility and minimal artifact generation across imaging modalities. Academic medical centers command premium placement for titanium markers, justified by compatibility with high-field MRI surveillance protocols and long-term biocompatibility data.
- Bioabsorbable Polymers:Resorbable lactide-glycolide formulations eliminating explantation requirements. Value-oriented community hospitals are gaining traction with these materials, motivated by reduced follow-up procedural burden and simplified patient counseling.
- Stainless Steel:Cost-optimized alternative for standard mammographic visualization without MRI compatibility requirements.
- Silicone:Elastomer-based markers selected for specific ultrasound visibility characteristics.
Titanium holds installed capacity. Bioabsorbable polymers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA device classification frameworks and production-linked incentive schemes are redirecting manufacturing capacity toward regulated markets while CMS reimbursement adjustments reshape procurement authority across hospital systems.
United States
Academic medical centers in Texas and Florida are standardizing magnetic seed deployment for non-palpable lesions, eliminating same-day scheduling constraints. CMS reimbursement codes for image-guided biopsy procedures concentrate purchasing authority within hospital materials management committees. The Dallas-Fort Worth and Miami health system clusters are negotiating three-year sole-source agreements that tie marker supply to mammography maintenance contracts.
Germany
Notified bodies are applying stringent interpretations of EU MDR Class IIb requirements for permanent implantables, extending clinical evidence timelines for bioabsorbable polymer markers. The EU MDR's 24-month follow-up study mandates favor incumbents with established bioresorption databases. Munich and Stuttgart medical device clusters are absorbing elevated compliance spending without commensurate pricing recovery in European markets.
India
Domestic manufacturing of implantable devices is accelerating under PLI medical device incentive schemes, attracting ISO 13485-certified assembly operations near Mumbai and Hyderabad. CDSCO regulatory harmonization with global standards is compressing market entry timelines for contract manufacturers. The Maharashtra and Telangana clusters are scaling production of titanium and bioabsorbable polymer formulations for export markets.
Japan
PMDA streamlined review pathways for predicate titanium-based markers are accelerating clearance timelines for manufacturers seeking substantial equivalence claims. METI industrial policy is supporting high-field MRI surveillance protocol adoption in academic medical centers. The Tokyo-Osaka corridor is concentrating demand for MRI-compatible markers compatible with advanced imaging infrastructure.
United Kingdom
NHS procurement frameworks are consolidating vendor lists for biopsy localization devices, squeezing regional distributors from hospital supply chains. MHRA post-Brexit regulatory autonomy is maintaining alignment with EU MDR clinical evidence requirements for Class IIb implantables. The London-Southeast hospital network is piloting AI-integrated localization workflows with RFID-tagged markers for robotic-assisted excision.
Breast Tissue Markers Market Vendor Landscape
On the supply side, the industry is consolidating around imaging system manufacturers with installed base leverage and interventional radiology specialists with deep hospital relationships. Three archetypes dominate: capital equipment bundlers leveraging mammography system contracts, interventional radiology department partners within integrated delivery networks, and customization-focused suppliers for high-volume biopsy centers. M&A activity concentrates on magnetic seed technology acquisitions, while strategic partnerships proliferate between marker manufacturers and AI localization workflow developers.
Among imaging-integrated bundlers, Hologic occupies a position exemplifying installed base leverage, while BD anchors the interventional radiology partnership archetype through integrated delivery network relationships. Merit Medical represents the customization-focused tier, serving high-volume biopsy centers with site-specific configurations.
| Leading Market Players |
|---|
| Hologic |
| BD |
| INRAD |
| Carbon Medical Technologies |
| Mammotome |
| Mermaid Medical |
| SOMATEX Medical Technologies |
| Merit Medical |
| Argon Medical |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific air freight corridors connecting aerospace-qualified titanium mills in the United States to ISO 13485-certified assembly operations in India transmit feedstock cost volatility directly into downstream price tiers, with surgical-grade titanium allocation rationing during defense procurement surges compressing margins for magnetic marker manufacturers while bioabsorbable polymer alternatives capture value-oriented segments.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-cleared titanium markers commanding placement in academic medical centers against CE-marked bioabsorbable alternatives in community hospitals. Per-unit transactional pricing dominates, though three-year sole-source agreements tied to mammography maintenance contracts are displacing spot purchasing in Texas and Florida health systems. Cost compression in standard biopsy clips intensifies because group purchasing organization consolidation squeezes vendor lists, with interventional radiology departments least price-sensitive due to physician preference item status while materials management committees drive aggressive unit economics.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier financing arrangements for titanium feedstock, with contract manufacturers absorbing working capital strain to secure aerospace-qualified mill allocation. Surgical-grade titanium concentrates in United States and Japanese supply channels, while bioabsorbable polymer resins draw from German and Indian chemical clusters. Raw material dependencies center on ferrite cores for magnetic detection, lactide-glycolide copolymers for resorbable formulations, and surgical-grade stainless steel for cost-optimized alternatives. Single-source vulnerability in titanium mill capacity creates exposure during defense procurement surges. Distribution runs through group purchasing organizations and integrated delivery network contracts, marginalizing independent regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proficiency in magnetic seed deployment and wire-free localization workflows represents the scarcest capability in this market, with fellowship-trained interventional radiologists commanding premium placement at academic medical centers and constraining adoption velocity at community hospitals lacking credentialing infrastructure.
For Market Incumbents: Build regulatory data moats through 24-month bioresorption databases that satisfy EU MDR Class IIb renewal requirements, blocking new entrant CE marking pathways. Anchor hospital materials management relationships through capital equipment bundling that ties marker supply to mammography system maintenance contracts, neutralizing emerging customization-focused competitors. FDA 510(k) clearance compression for predicate devices accelerates competitive entry, demanding accelerated clinical evidence generation. For New Entrants and Emerging Players: Freestanding ambulatory surgical centers in the United States represent the most penetrable entry point, with simplified single-use marker kit demand outpacing incumbent inventory complexity. India's PLI medical device incentive zones near Mumbai and Hyderabad offer contract manufacturing footholds for ISO 13485-certified assembly with export market access. Go-to-market execution should emphasize direct procurement relationships with oncology clinic administrators bypassing GPO consolidation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device parents with undermonetized breast localization portfolios lacking magnetic seed technology integration. Long-term viability centers on platform-agnostic localization workflows spanning magnetic, radar, and radiofrequency modalities rather than single-technology dependence. Signal to watch: CMS reimbursement code adjustments for image-guided biopsy procedures that shift purchasing authority between hospital materials management and physician preference committees.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Class IIb compliance compresses timelines for bioabsorbable polymer market access against German notified body stringency. |
| Hospital System Partnership | Three-year sole-source agreements in Texas and Florida tie marker supply to mammography maintenance, locking out competitors. |
| Software Companion Development | AI-integrated localization workflows with RFID-tagged markers enable real-time coordinate verification during robotic-assisted excision. |
| Reimbursement Strategy | CMS code optimization for wire-free localization protocols accelerates magnetic seed displacement of clip-and-wire methods. |
| Backward Integration into Titanium | Captive supply of surgical-grade feedstock insulates against aerospace mill allocation rationing during defense procurement surges. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR notified body guidance documents, CMS reimbursement code databases, and hospital procurement records preceded structured interviews with interventional radiologists, hospital materials management directors, GPO contracts managers, and biomedical engineers. Secondary validation drew from CDSCO regulatory harmonization notices, PLI scheme disclosures, and integrated delivery network capital expenditure filings. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Assumptions held fixed include FDA device classification frameworks, EU MDR Class IIb clinical evidence requirements, and CMS reimbursement parity between wire and wire-free localization protocols. Variables stress-tested encompass titanium feedstock spot price volatility, fellowship program expansion rates for interventional radiology credentialing, and PACS middleware integration friction. Segmentation dimensions modeled span material type, application workflow, end-user channel, and regional regulatory cluster. CAGRs derived from procedure volume forecasts weighted by technology substitution curves and hospital capital expenditure cycles.
Stress conditions across titanium mill allocation rationing, EU MDR notified body interpretation variance, and CMS reimbursement adjustment timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic contraction affecting hospital capital budgets, regulatory reclassification of permanent implantables, or disruptive localization technology emergence would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
CMO and CDMO Biotechnology Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Global Human Embryonic Stem Cells Market
Medical Biotechnology
Global Hormone Refractory Breast Cancer Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Mecobalamin Injection Market