
 Global Dental Turbine Market | 2026-2036
Global Dental Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Turbine Market Foresight
The EU Green Deal is realigning material sourcing requirements for dental device manufacturers, pushing suppliers toward recycled stainless steel and reduced-packaging protocols. Nakanishi Inc. leverages its precision machining heritage to dominate high-speed turbine cartridge production in East Asia. W&H Group sustains competitive positioning through backward integration into ceramic bearing manufacturing. KaVo Dental anchors its premium positioning via proprietary LED illumination technology that reduces shadowing during complex restorative work.
A dental turbine is a pneumatically or electrically driven rotary instrument housed within a handpiece, typically operating at rotational speeds between 300,000 and 400,000 RPM via a miniature turbine cartridge with ceramic or steel bearings, designed to cut, shape, or polish hard and soft oral tissues during clinical procedures. Air turbine handpieces remain the volume backbone across dental clinics worldwide due to established maintenance infrastructure and lower per-unit capital outlay. Fiber optic technology commands premium placement in oral surgery centers where illumination precision directly affects procedural outcomes. Electric turbine systems are gaining share in academic institutions where torque consistency supports training standardization.
The FDA enforces 510(k) premarket notification pathways for high-speed dental handpieces, while the EU MDR imposes stricter biocompatibility and sterilization validation on turbine cartridges entering European markets. Japan's PMDA maintains rigorous electrical safety standards for hybrid turbine systems that combine pneumatic and electric drive elements. Stakeholders must monitor evolving regulatory convergence between FDA and EU MDR requirements to avoid duplicative compliance costs and supply chain fragmentation.
Market Dynamics
The EU MDR sterilization mandates are compressing supplier margins while forcing cartridge assembly relocation toward East Asian precision clusters with validated cleanroom infrastructure.
Growth Catalysts
- EU Green Deal material protocols:Recycled stainless steel sourcing requirements are opening certified supply contracts for turbine housing manufacturers with verified carbon accounting.
- Academic institution procurement:Electric turbine systems with torque consistency features are displacing pneumatic units in dental schools across Germany and Japan for standardized training curricula.
- Brazilian clinic expansion:Procedural volume growth in São Paulo and Rio de Janeiro dental networks is pulling high-speed handpiece replacement cycles forward.
Market Restraints
- Ceramic bearing supply concentration:Precision ceramic ball manufacturing clusters in Japan and Germany create single-source vulnerability for cartridge assemblers.
- EU MDR biocompatibility validation costs:Extended sterilization cycle documentation for turbine cartridges entering European markets stretches working capital cycles for mid-tier suppliers.
- Electric motor substitution:Brushless electric handpieces with programmable torque curves are capturing share in premium restorative segments previously served by air turbines.
Strategic Opportunities
- India clinic modernization:Underpenetrated Tier-2 and Tier-3 cities present volume expansion for mid-speed turbine systems with simplified maintenance protocols.
- Fiber optic LED convergence:Integrated illumination handpieces are commanding placement in South Korean oral surgery centers where shadow reduction affects procedural precision.
- US FDA 510(k) pathway optimization:Streamlined premarket notification for turbine cartridge variants with established predicate devices reduces time-to-market for iterative designs.
Industry Challenges
- Precision machining talent scarcity:Turbine cartridge micro-bore drilling and balancing operations require specialized technicians concentrated in Japanese and Swiss manufacturing regions.
- Legacy pneumatic infrastructure lock-in:Dental clinics with amortized air compressor systems face capital friction when evaluating electric turbine migration paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Turbine Market |
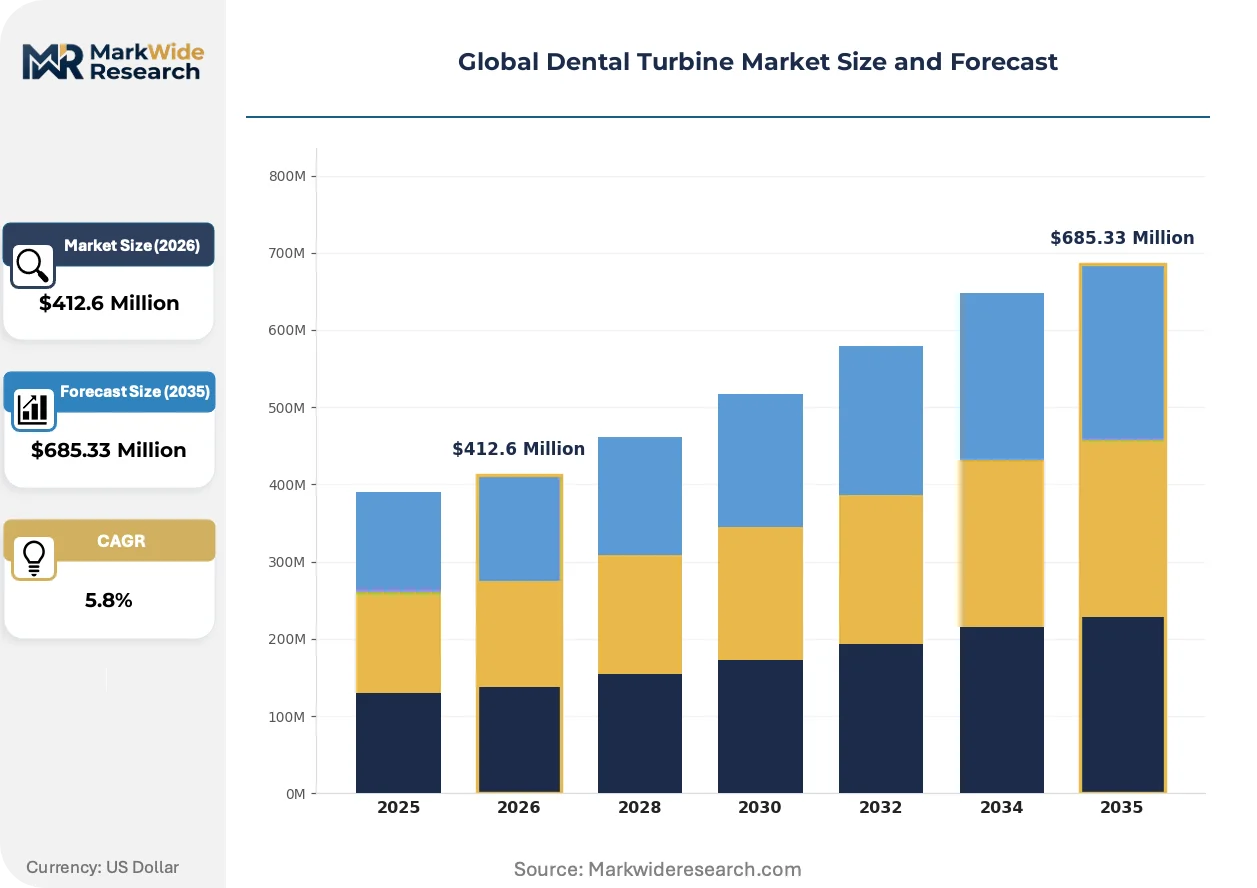
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Turbine, Electric Turbine, Hybrid Turbine, Micro Motor, Straight Handpiece Technology: Fiber Optic, Non-Fiber Optic, LED Illumination, Turbine Cartridge Application: Restorative Procedures, Endodontic Procedures, Surgical Procedures, Orthodontic Adjustments End User: Dental Clinics, Oral Surgery Centers, Dental Laboratories, Academic Institutions |
| Companies Covered | Dentsply Sirona, Inc., Nakanishi Inc., W&H Group, KaVo Dental, Bien Air, BA International, A-dec, Inc., Guilin Woodpecker Medical Instrument Co., Ltd., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Turbine Market Shifts & Advancements
Digital dentistry workflows and sustainability mandates are reshaping how turbine systems are specified, maintained, and disposed of across clinical settings.
Smart connected handpieces with embedded usage sensors are expanding into multi-location dental service organizations seeking predictive maintenance scheduling and instrument lifecycle analytics. DSO procurement teams in the United States and United Kingdom are piloting subscription models tied to verified utilization data. This connectivity layer is expanding into fleet management software that unifies turbine inventory across regional clinic networks.
REACH substance restrictions on nickel release are forcing European manufacturers toward cobalt-chrome and titanium alloy alternatives for turbine housing components. The ECHA sunset date for certain nickel compounds in prolonged skin contact applications has compressed reformulation timelines. German and Italian turbine assemblers are responding with accelerated biocompatibility testing partnerships in certified European laboratories.
After-sales service unbundling is disrupting traditional distributor relationships as clinics seek direct manufacturer relationships for cartridge refurbishment and bearing replacement. Independent dental service technicians in Australia and Canada are capturing maintenance revenue previously held by authorized dealers. This channel fragmentation is most visible in mature markets where turbine fleet age exceeds seven years and out-of-warranty units dominate installed bases.
Global Dental Turbine Market Segmentation
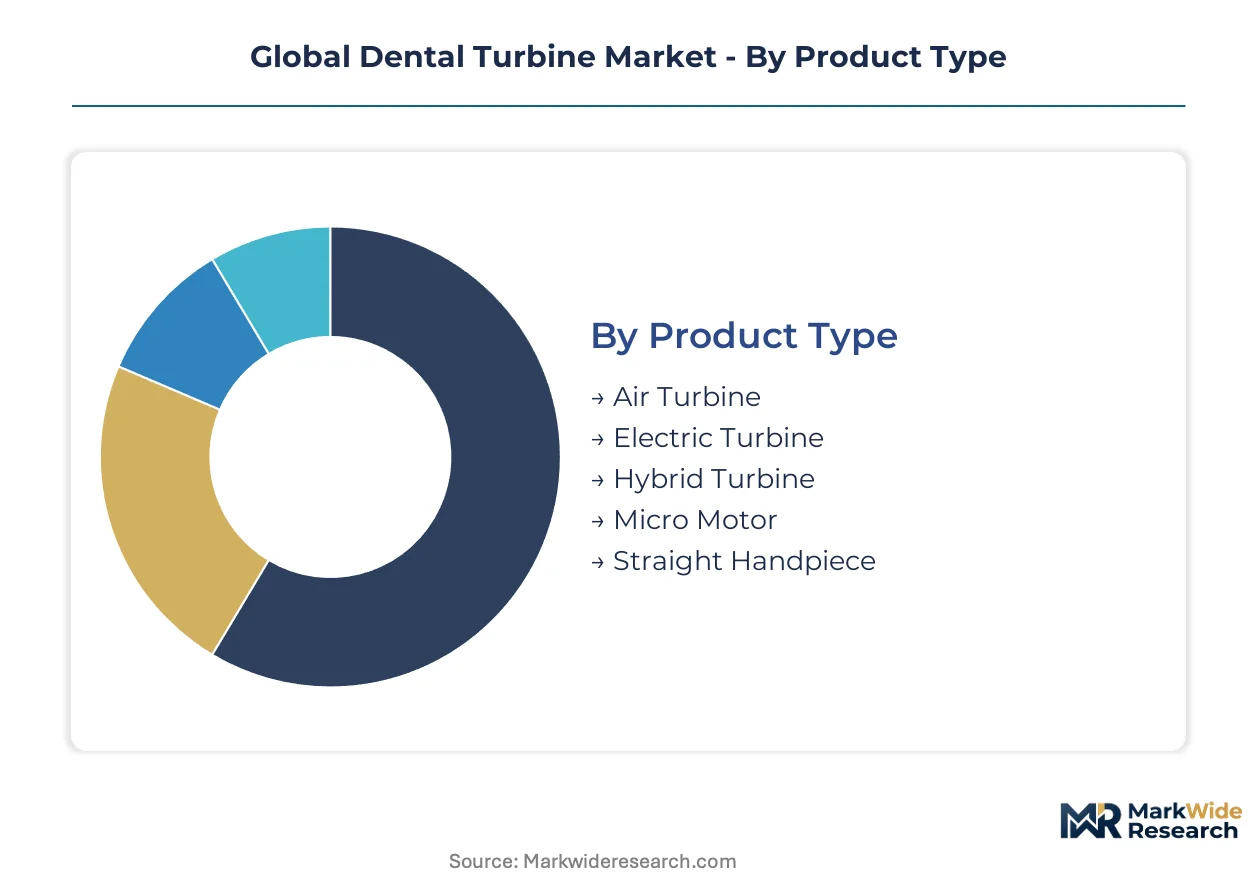
Dental turbine segmentation reveals distinct procurement patterns across clinical settings. Technology specifications determine maintenance infrastructure requirements, while application scope dictates rotational speed and torque specifications.
Product Type:
Rotational drive mechanisms differentiate capital outlay, maintenance cadence, and procedural suitability across clinical environments.
- Air Turbine:Pneumatic drive systems operating via compressed air supply dominate high-speed cutting applications. Brazilian and Chinese dental clinic networks pull replacement cycles forward as procedural volumes expand.
- Electric Turbine:Brushless motor systems deliver programmable torque curves with consistent power output. German and Japanese dental schools favor these units for standardized training curricula where torque predictability supports skill acquisition.
- Hybrid Turbine:Dual-mode systems switch between pneumatic and electric drive elements. Japan's PMDA maintains rigorous electrical safety validation protocols for these configurations.
- Micro Motor:Low-speed rotary attachments for polishing and finishing work. Laboratory technicians in Italian dental labs specify these for prosthetic refinement tasks.
- Straight Handpiece:Direct-drive instruments for surgical access in confined oral spaces. Oral surgeons in South Korean centers deploy these for third molar extractions.
Mature deployment sits with Air Turbine systems. Newer deployment is concentrated in Electric Turbine configurations.
Technology:
Illumination and bearing architecture specifications separate premium placement from standard procurement tiers.
- Fiber Optic:Bundled glass fiber light transmission integrated into handpiece bodies. South Korean oral surgery centers command these units where shadow reduction affects procedural precision.
- Non-Fiber Optic:External illumination dependency with simplified handpiece construction. Tier-2 Indian clinics favor these for capital-constrained modernization programs.
- LED Illumination:Solid-state diode arrays with daylight-balanced color temperature. KaVo Dental anchors premium positioning via proprietary LED systems that reduce shadowing during complex restorative work.
- Turbine Cartridge:Replaceable bearing and rotor assemblies enabling field refurbishment. EU MDR sterilization mandates compress supplier margins while forcing assembly relocation toward East Asian cleanroom clusters.
Volume concentration favors Non-Fiber Optic procurement. Value expansion is climbing fastest in LED Illumination configurations.
Application:
Procedural intensity and tissue interaction requirements shape turbine specification across clinical workflows.
- Restorative Procedures:Crown preparation, cavity excavation, and margin refinement demand high-speed precision. São Paulo dental networks drive handpiece replacement frequency as cosmetic procedure volumes rise.
- Endodontic Procedures:Root canal access and canal shaping require controlled torque delivery. Academic institutions in Japan specify electric turbine systems for endodontic training consistency.
- Surgical Procedures:Bone cutting and osteotomy applications need sustained power under load. Oral surgery centers in Germany and South Korea prioritize fiber optic illumination for visibility in posterior sites.
- Orthodontic Adjustments:Adhesive removal and bracket positioning utilize lower-speed rotary attachments. Orthodontic practices in Brazil deploy straight handpieces for efficient debonding workflows.
Replacement revenue concentrates in Restorative Procedures. Surgical Procedures are gaining share fastest as implantology expands.
End User:
Procurement authority and fleet scale determine pricing negotiation leverage and service contract structures.
- Dental Clinics:General practice settings with mixed procedural portfolios and compressed capital cycles. Rio de Janeiro clinic networks accelerate high-speed handpiece turnover amid expansion.
- Oral Surgery Centers:Specialized facilities with premium instrumentation requirements and extended utilization hours. South Korean centers command fiber optic LED convergence for precision outcomes.
- Dental Laboratories:Prosthetic fabrication sites utilizing low-speed rotary systems for model work and finishing. Italian lab clusters specify micro motor systems for ceramic adjustment protocols.
- Academic Institutions:Training environments standardizing curricula across student cohorts. German and Japanese dental schools displace pneumatic units with electric systems for torque consistency.
Installed base volume sits with Dental Clinics. Procurement standardization is expanding most quickly in Academic Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka anchors precision turbine cartridge manufacturing through Nakanishi Inc.'s machining heritage, while São Paulo dental networks accelerate replacement cycles amid clinic expansion. Demand concentrates across four distinct national markets with divergent regulatory and infrastructure profiles.
United States
Multi-location dental service organizations pilot predictive maintenance subscriptions for connected handpiece fleets. The FDA enforces 510(k) premarket notification pathways for high-speed dental handpieces entering clinical use. Procurement standardization in Texas and Florida clinic networks is compressing distributor margins through direct manufacturer relationships.
Germany
Dental schools in Bavaria and North Rhine-Westphalia displace pneumatic units with electric turbine systems for torque consistency in training curricula. The EU MDR imposes stricter biocompatibility and sterilization validation on turbine cartridges entering European markets. W&H Group's backward integration into ceramic bearing manufacturing sustains competitive positioning in Baden-Württemberg precision clusters.
Japan
Academic institutions in Tokyo and Osaka specify electric turbine configurations for endodontic training standardization. The PMDA maintains rigorous electrical safety standards for hybrid turbine systems combining pneumatic and electric drive elements. Kanto manufacturing corridors supply miniature bearing assemblies to OEM assembly lines across precision component networks.
Brazil
Procedural volume growth in São Paulo and Rio de Janeiro dental networks pulls high-speed handpiece replacement cycles forward. ANVISA registration requirements govern imported dental device commercialization across federal jurisdictions. Clinic modernization in Minas Gerais and Paraná is expanding addressable market for mid-speed turbine systems with simplified maintenance protocols.
South Korea
Oral surgery centers in Seoul command fiber optic LED convergence where shadow reduction affects procedural precision. The MFDS regulates medical device quality management systems for turbine cartridge distribution. Busan-Ulsan manufacturing zones serve as export hubs for precision-machined turbine components destined for global OEM assembly lines.
Global Dental Turbine Market Competitive Landscape
The competitive structure tilts toward precision machining specialists with captive bearing supply capabilities. Market concentration remains moderate with tiered differentiation across premium illumination, standard pneumatic, and economy maintenance-simplified segments. Three archetypes dominate: Japanese precision component houses, Austrian-German integrated device manufacturers, and Chinese volume fabricators. Capacity expansion in East Asian cleanroom clusters and strategic partnerships for LED illumination sourcing represent the dominant competitive moves reshaping supplier positioning.
Within the precision machining tier, Nakanishi Inc. exemplifies the Japanese specialist archetype through its Osaka-based heritage in miniature component production. W&H Group occupies a position among Central European integrated manufacturers with in-house ceramic bearing capabilities. KaVo Dental anchors the premium illumination vector through proprietary LED technology positioning. These three entities collectively represent the structural poles around which mid-tier suppliers and regional fabricators organize their competitive responses.
| Leading Market Players |
|---|
| Dentsply Sirona, Inc. |
| Nakanishi Inc. |
| W&H Group |
| KaVo Dental |
| Bien Air |
| BA International |
| A-dec, Inc. |
| Guilin Woodpecker Medical Instrument Co., Ltd. |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between EU MDR-validated turbine cartridges and non-validated alternatives manifests in parallel supply chain configurations, with compliant assemblers commanding premium positioning through East Asian cleanroom infrastructure while uncertified competitors face margin compression from documentation burdens.
Pricing Analysis
Outcome-linked pricing anchors turbine cartridge procurement, with clinics paying premiums for validated sterilization cycles and traceable bearing provenance. Three-tier pricing structure across premium, standard, and economy levels separates LED-illuminated surgical systems from fiber-optic general practice units and non-optic maintenance-simplified configurations. Pricing pressure stems from EU MDR biocompatibility validation costs stretching working capital cycles for mid-tier suppliers. Academic institutions exhibit lowest price sensitivity given standardized curriculum requirements, while Tier-2 Indian clinics face capital-constrained procurement decisions.
Supply Chain Analysis
Cartridge refurbishment flows and bearing replacement services are fragmenting traditional distributor relationships as independent technicians capture aftermarket revenue previously held by authorized dealers. Precision component manufacturing concentrates in Japan, Germany, and South Korea, with Osaka and Busan-Ulsan clusters supplying miniature bearing assemblies to global OEM lines. Ceramic ball production rests on specialized machining capabilities concentrated in Japanese and Swiss regions. Single-source vulnerability in ceramic bearing supply creates structural risk for cartridge assemblers. Distribution runs through multi-location dental service organizations piloting direct manufacturer relationships alongside traditional dental equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance narrative, with EU MDR sterilization and biocompatibility mandates erecting barrier-to-entry moats that favor incumbents with validated cleanroom infrastructure and documented supply chain traceability.
For Market Incumbents: Anticipate brushless electric handpiece substitution threats in premium restorative segments by accelerating captive ceramic bearing production and LED illumination technology partnerships. Backward integration into precision machining capabilities in East Asian clusters defends margin position against emerging Chinese volume fabricators. EU MDR documentation investments create switching-cost advantages for compliant turbine cartridge suppliers. For New Entrants and Emerging Players: Smart connectivity sensors embedded in handpiece bodies offer technology-first wedge opportunities through predictive maintenance subscriptions for multi-location dental service organizations. Underpenetrated Tier-2 and Tier-3 Indian cities present accessible white-space targets for mid-speed turbine systems with simplified maintenance protocols. Direct-to-clinic refurbishment services bypass entrenched distributor relationships in mature markets with aging turbine fleets. For Investors and Strategic Acquirers: Re-rating potential sits with precision machining specialists possessing captive bearing supply capabilities given consolidation pressure from regulatory compliance burdens. Long-term viability favors entities with demonstrated EU MDR validation and East Asian cleanroom access over pure-brand marketing plays. Watch for FDA-EU MDR regulatory convergence announcements as inflection indicators for duplicative compliance cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Validated sterilization documentation opens European clinic procurement channels for compliant cartridge assemblers. |
| Backward Integration into Ceramic Bearings | In-house bearing production insulates margin structures from Japanese and German supply concentration risks. |
| LED Illumination Technology Partnership | Proprietary shadow-reduction systems anchor premium placement in South Korean oral surgery centers. |
| Predictive Maintenance Platform Launch | Usage sensor integration enables subscription revenue from United States dental service organization fleets. |
| East Asian Cleanroom Capacity Expansion | Osaka and Busan-Ulsan manufacturing scale supports OEM assembly line demand from global dental device brands. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, PMDA electrical safety submissions, and ANVISA registration records, complemented by interviews with dental equipment procurement managers, biomedical engineering directors, GPO contracts specialists, and aftermarket service technicians. Secondary validation drew from hospital procurement databases, dental school capital expenditure disclosures, and customs trade data for precision-machined components. Bottom-up clinic fleet sizing and top-down manufacturer shipment data were cross-referenced for triangulation.
Historical utilization patterns were cross-referenced against panel input from equipment planners and distributor inventory managers across the projection horizon. Segmentation modeling captured drive mechanism type, illumination technology, procedural application, and end-user procurement authority. CAGRs were derived from installed base turnover analysis and replacement cycle acceleration factors. Forecast inputs incorporated clinic expansion rates in São Paulo and Rio de Janeiro, academic institution standardization trends in Germany and Japan, and DSO fleet consolidation patterns in Texas and Florida.
Several conditions sit outside the modeled scope, including unforeseen regulatory divergence between FDA and EU MDR requirements, ceramic bearing supply disruptions from geopolitical events, and accelerated electric handpiece substitution beyond current adoption trajectories. Forecasts reflect assumptions regarding procedural volume growth and sterilization validation timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Apex Locator Market
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Dental Sealants Market
Dental Devices
Dental Splints Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Dental Curing Lights Market
Dental Devices
Dental Handpieces Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Orthodontic Wax Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Dental Carpule Market
Dental Devices
Netherlands Dental Devices Market