
 Airport Full Body Scanner Market | 2026-2036
Airport Full Body Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Full Body Scanner Market Analysis
Modular scanner configurations bundled with software analytics and remote monitoring services is realigning procurement patterns across airport authorities. L3Harris Technologies, Inc. leverages its integrated security ecosystem to anchor large-scale deployments at major US hubs. Smiths Detection competes through specialized detection algorithms that extend its footprint across European transportation infrastructure. Nuctech Company Limited dominates manufacturing scale, sustaining cost advantages in portable and fixed installations across Asia-Pacific markets.
Airport full body scanners are non-invasive screening devices that employ millimeter wave or X-ray technology to detect concealed objects under clothing, operating at frequencies between 24-30 GHz with resolution thresholds capable of identifying anomalies at sub-millimeter scale. These systems serve the primary commercial purpose of automated threat detection in high-throughput passenger environments, reducing manual pat-down requirements while maintaining aviation security protocols. Millimeter wave scanners occupy the largest product category due to radiation safety advantages over backscatter X-ray alternatives, while software algorithms represent the fastest-expanding technology segment as airports prioritize automated threat recognition over hardware refresh cycles. Fixed installations retain the dominant share of deployment value, though portable configurations are gaining traction in major events and temporary transportation hub expansions.
TSA, EASA, and ICAO standards collectively shape product certification requirements, mandating specific detection rates, privacy filtering protocols, and passenger throughput minimums that determine market access for equipment vendors. EU AI Act provisions and GDPR privacy frameworks are additionally constraining algorithm development, requiring anonymized avatar outputs rather than photographic imagery in European deployments. Stakeholders must monitor evolving interoperability standards between national aviation authorities and assess whether software upgrade paths or full system replacements offer superior lifecycle economics.
Market Dynamics
Software-defined threat detection is compressing hardware replacement cycles across airport security procurement, redirecting capital expenditure toward algorithm licensing and remote diagnostics platforms rather than standalone scanner unit purchases.
Growth Catalysts
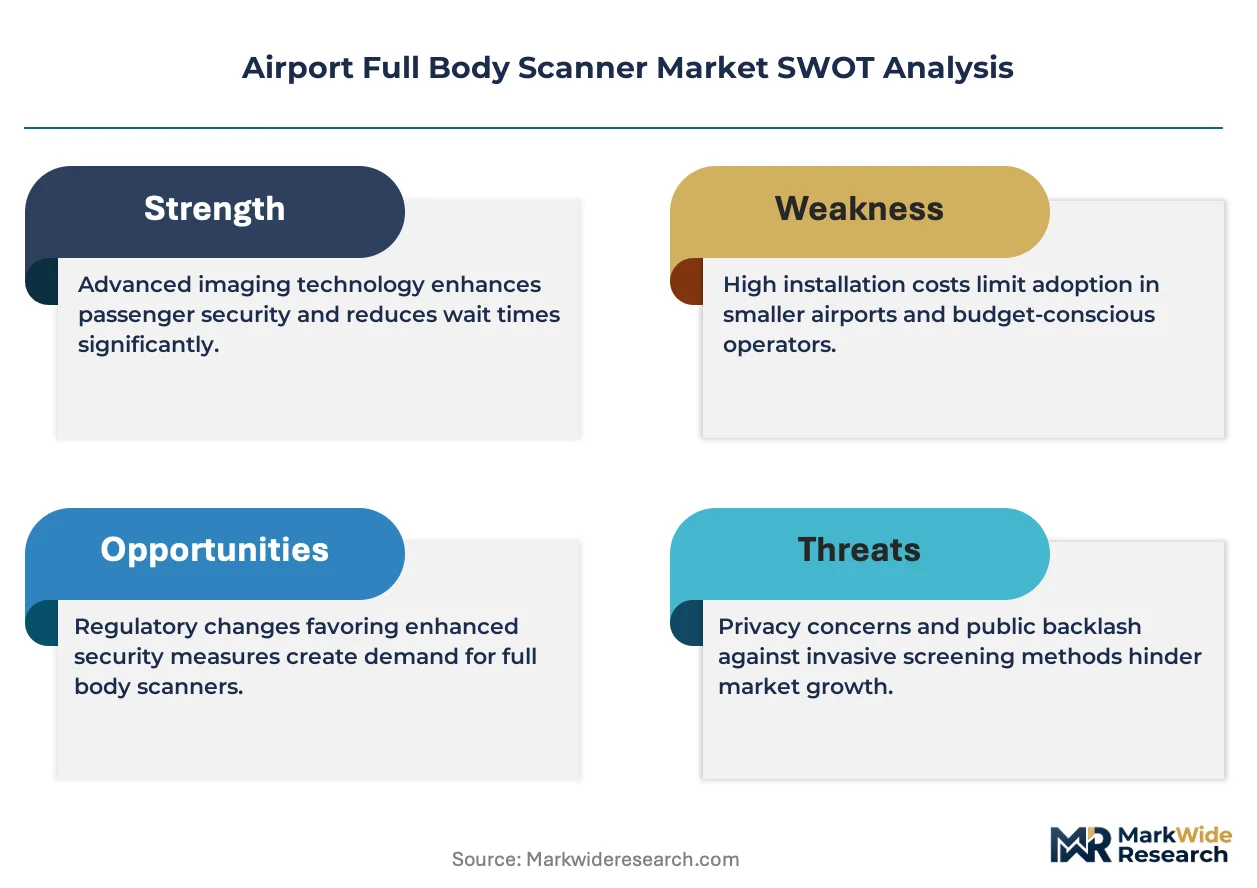
- TSA Advanced Imaging Technology Mandate:Updated US screening protocols require millimeter wave deployment at Category X airports, forcing hub modernization programs and creating sustained equipment demand through 2035.
- Millimeter Wave Safety Advantages:Non-ionizing radiation profiles satisfy health authority concerns in passenger-dense environments, accelerating displacement of backscatter X-ray alternatives in European and Asian installations.
- Hub Modernization Concentration:Major aviation infrastructure expansion in Germany, China, and the United States concentrates procurement volume where passenger throughput requirements justify premium detection systems.
Market Restraints
- GDPR Privacy Compliance Burden:EU AI Act provisions mandate anonymized avatar outputs, forcing algorithm rewrites that extend certification timelines and raise development costs for European deployments.
- Semiconductor Component Concentration:Millimeter wave sensor arrays depend on specialized RF chip fabrication concentrated in East Asian foundries, exposing supply continuity risk to geopolitical friction.
- Interoperability Fragmentation:Divergent national certification standards between FAA, EASA, and CAAC create redundant testing requirements that inflate vendor market entry costs.
Strategic Opportunities
- Temporary Transportation Infrastructure:Portable scanner configurations address security screening gaps at major sporting events and emergency hub expansions where permanent installation economics fail.
- AI-Enhanced Threat Libraries:Machine learning pattern recognition enables detection of non-metallic threats including liquid explosives and ceramic weapons, opening new algorithm licensing revenue streams.
- India Aviation Security Modernization:Bureau of Civil Aviation Security mandates at expanding metro airports create first-mover advantages for vendors establishing local service networks.
Industry Challenges
- Millimeter Wave Engineering Talent Scarcity:Specialized RF design and antenna array optimization skills concentrate at defense contractors, forcing commercial vendors into aggressive compensation competition.
- Legacy System Integration Complexity:New detection algorithms must interface with decade-old security checkpoint architectures without disrupting passenger throughput, requiring costly middleware development.
- Multi-Authority Certification Sequencing:Parallel approval processes with FDA radiation safety, TSA operational testing, and EASA interoperability standards extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Full Body Scanner Market |
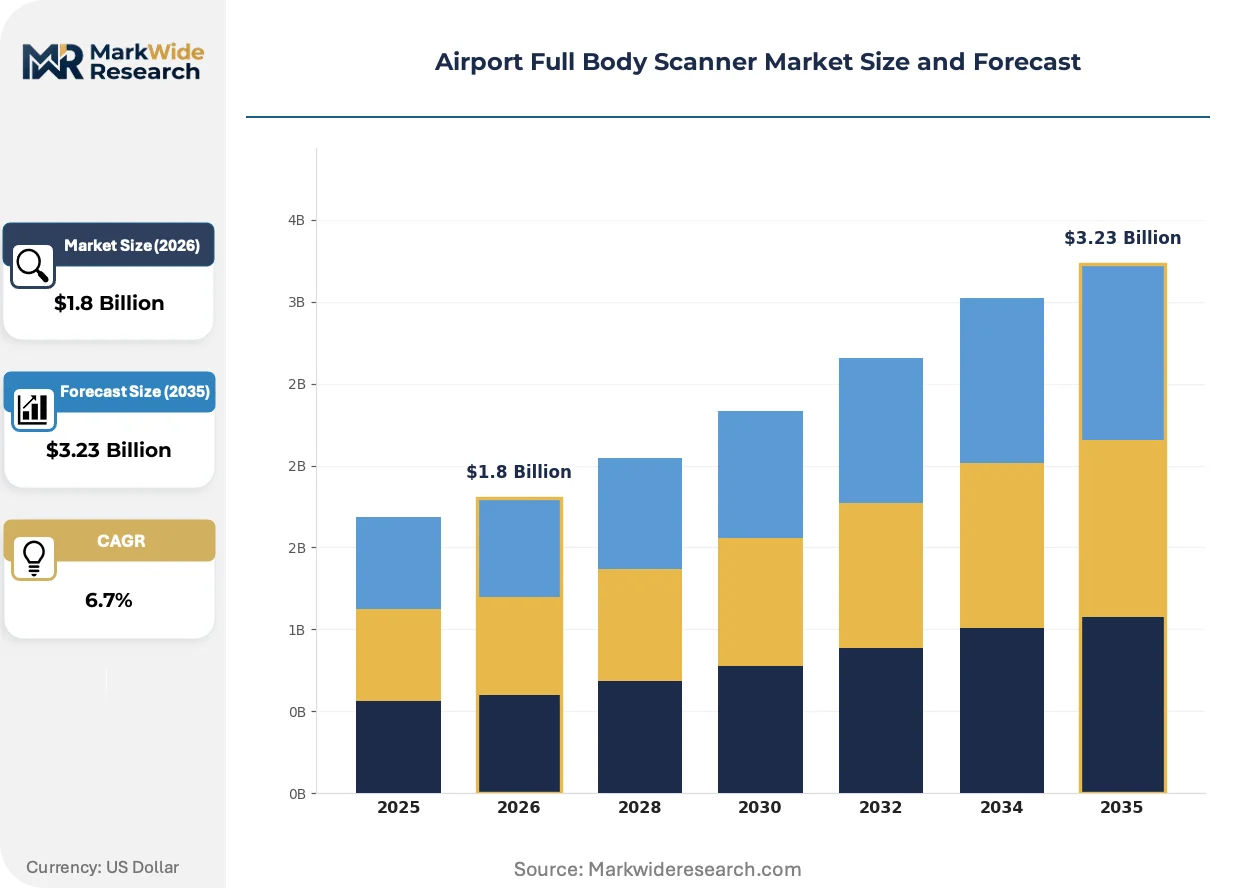
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Millimeter Wave Scanners, X-ray Scanners, Active Scanners, Passive Scanners Technology: 2D Imaging, 3D Imaging, Infrared, Software Algorithms End User: Airports, Transportation Hubs, Public Security, Major Events Installation: Fixed, Portable, Integrated, Standalone |
| Companies Covered | Leidos Holdings, Inc., LINEV Systems Ltd., L3Harris Technologies, Inc., Braun & Co. Limited, Tek84, Inc., Smiths Detection, Nuctech Company Limited, Westminster Group plc, Rapiscan Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Full Body Scanner Market Emerging Trajectories
Detection hardware is fragmenting into interoperable subsystems while software layers absorb an expanding share of security value creation, compressing traditional equipment vendor margins.
Millimeter wave antenna arrays are modularizing into standardized sensor tiles that airports mix and match across checkpoint configurations. Major US hubs now specify tile-based architectures that permit rapid lane reconfiguration during peak travel periods. This shift is modularizing vendor business models toward component supply and away from turnkey system dominance.
EASA mandates under the EU AI Act now require algorithmic transparency documentation for automated threat detection systems deployed at Schengen airports. Equipment vendors must submit training data provenance and bias audit reports before operational certification. German and French hub operators have responded by inserting data governance clauses into procurement specifications that favor European-headquartered software providers.
Checkpoint-as-a-service contracting is displacing capital purchase models at mid-tier airports lacking in-house maintenance capabilities. Third-party security integrators now bundle scanner hardware, software subscriptions, and on-site technical staffing into single monthly fees. This restructuring concentrates most visibly in the United Kingdom and Nordic countries where airport privatization has separated operational responsibility from infrastructure ownership.
Airport Full Body Scanner Market Segmentation
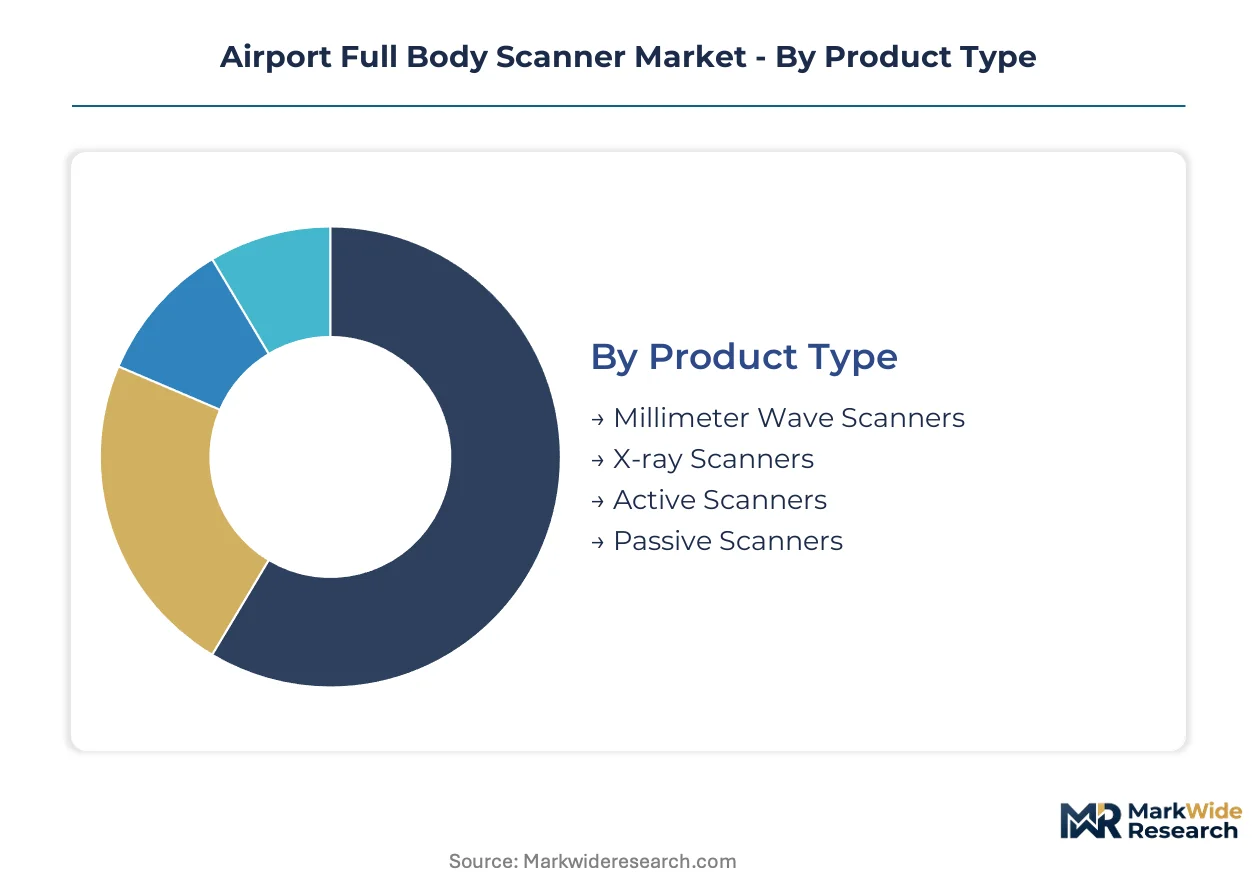
Airport full body scanner procurement patterns diverge sharply across product architectures, detection modalities, deployment settings, and integration depth. Each segmentation axis reveals distinct margin structures and vendor specialization zones that determine competitive positioning.
Product Type:
Standardization dominates at the hardware core while customization concentrates at the detection algorithm layer across this category.
- Millimeter Wave Scanners:Non-ionizing radiation at 24-30 GHz frequencies enables safe passenger throughput without health authority objections. Demand concentrates at Category X airports in the United States following TSA mandate updates, with Germany and China hub operators matching specifications for passenger volume thresholds.
- X-ray Scanners:Backscatter technology delivers sub-millimeter resolution for metallic and non-metallic threat detection but faces displacement pressure from millimeter wave alternatives due to ionizing radiation concerns. European installations under EASA jurisdiction have accelerated phase-out timelines.
- Active Scanners:Transmitter-receiver arrays emit energy toward subjects and analyze reflected signals for concealed object identification.
- Passive Scanners:Natural radiation detection from human body heat eliminates active emission requirements for sensitive deployment environments.
Most installed capacity flows through millimeter wave scanners. Expansion is steepest in active scanner configurations with software-upgradeable detection libraries.
Technology:
Cost tier stratification separates legacy hardware imaging from premium algorithm-driven detection capabilities.
- Software Algorithms:Machine learning pattern recognition enables automated threat classification without human image review, satisfying GDPR anonymization mandates through avatar-based outputs. European procurement specifications under EU AI Act transparency requirements favor vendors with documented training data provenance and bias audit trails.
- 3D Imaging:Volumetric reconstruction eliminates blind spots from single-angle capture, improving detection rates for objects concealed at body contours. Major US hub operators specify 3D capability for primary screening lanes where throughput penalties from secondary inspection are costliest.
- 2D Imaging:Planar capture remains standard for secondary screening and lower-volume checkpoints.
- Infrared:Thermal signature analysis supplements primary detection modalities for specific threat categories.
Most installed capacity flows through 2D imaging hardware. Expansion is steepest in software algorithms as airports prioritize detection capability upgrades over full system replacement.
End User:
Application context determines performance specifications, with passenger throughput requirements scaling from permanent aviation infrastructure to temporary event deployment.
- Airports:Permanent checkpoint installations demand 99%+ detection rates with sub-30-second processing times per passenger. Procurement concentrates at major hubs in the United States, Germany, and China where federal security mandates and passenger volume economics justify premium system specifications.
- Transportation Hubs:Rail and intermodal terminals require adapted form factors for space-constrained environments with variable passenger flow patterns.
- Public Security:Government facility deployment prioritizes threat category breadth over processing speed.
- Major Events:Temporary installations at sporting venues and political summits create demand spikes for rapidly deployable portable configurations.
Most installed capacity flows through airports. Expansion is steepest in major events where temporary infrastructure requirements outstrip permanent installation economics.
Installation:
Customer type segmentation separates capital-purchase airport authorities from service-contracting operators lacking in-house technical capabilities.
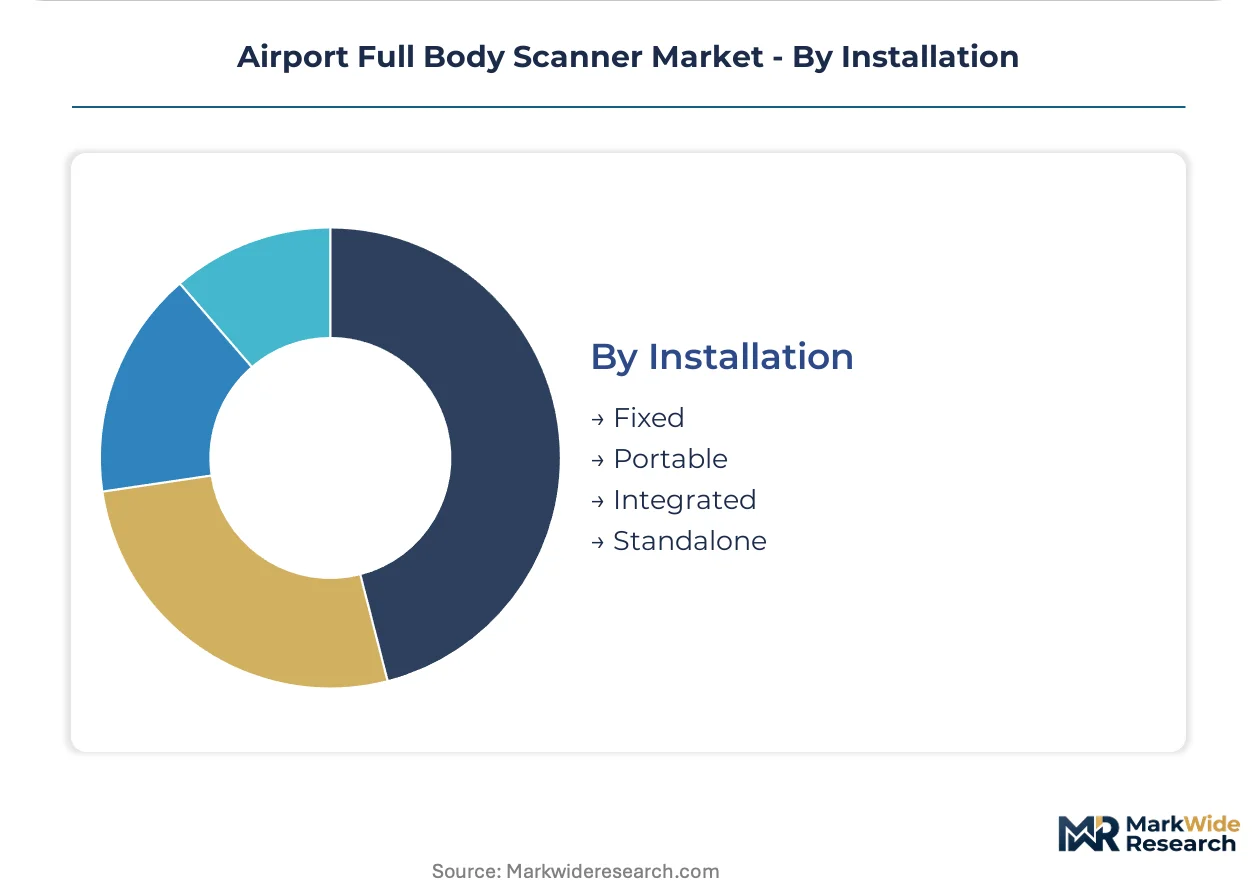
- Fixed:Permanent lane configurations dominate procurement value, with modular tile-based architectures now standard at major US hubs for rapid reconfiguration during peak travel periods. German and French operators have adopted similar specifications under EASA interoperability guidelines.
- Portable:Rapid-deployment units address emergency hub expansions and temporary event security requirements without permanent infrastructure commitment.
- Integrated:Networked scanner arrays with centralized monitoring and remote diagnostics support checkpoint-as-a-service contracting models.
- Standalone:Single-unit operation persists at smaller facilities with limited passenger volumes and constrained capital budgets.
Most installed capacity flows through fixed installations. Expansion is steepest in integrated configurations as third-party security integrators consolidate operational responsibility under service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airport full body scanner technology first achieved commercial scale in the United States following post-2001 aviation security mandates, with TSA procurement establishing the foundational deployment model later replicated across European and Asian hub operators.
United States
Category X airport modernization and TSA Advanced Imaging Technology mandates drive sustained procurement of millimeter wave systems. FDA radiation safety standards and FAA operational certifications shape vendor qualification timelines. Atlanta Hartsfield-Jackson and Dallas-Fort Worth anchor the largest hub deployment programs, with modular lane reconfigurations now standard during peak travel periods.
Germany
Frankfurt and Munich hub expansions concentrate demand for EASA-compliant detection systems with sub-30-second throughput specifications. EU AI Act transparency requirements and GDPR anonymization mandates force algorithm rewrites that extend certification cycles. Bavaria-based operators have inserted data governance clauses favoring European-headquartered software providers into procurement specifications.
China
Beijing Capital, Shanghai Pudong, and Guangzhou Baiyun infrastructure programs sustain manufacturing scale for domestic and export markets. Civil Aviation Administration of China interoperability standards diverge from FAA and EASA protocols, creating parallel testing requirements. Yangtze River Delta hub operators specify integrated scanner networks with centralized remote monitoring capabilities.
United Kingdom
Airport privatization separates infrastructure ownership from operational responsibility, accelerating checkpoint-as-a-service contracting models. UK GDPR implementation exceeds baseline EU requirements for passenger data handling. Heathrow and Gatwick operators now bundle hardware, software subscriptions, and on-site technical staffing into single monthly fee structures.
India
Bureau of Civil Aviation Security mandates at expanding metro airports create first-mover opportunities for vendors establishing local service networks. Delhi Indira Gandhi and Mumbai Chhatrapati Shivaji Maharan modernization programs prioritize throughput capacity for high-volume domestic routes. Maharashtra and Karnataka state aviation authorities are piloting portable configurations for temporary terminal expansions.
Airport Full Body Scanner Market Vendor Landscape
The competitive structure tilts toward integrated security ecosystems rather than standalone hardware vendors. Three distinct archetypes occupy the field: defense contractors leveraging classified RF engineering capabilities, specialized detection algorithm developers, and manufacturing-scale fabricators with cost-optimized production. Consolidation pressure concentrates at the software layer where algorithm licensing generates recurring revenue, while hardware margins compress under modular component standardization. Strategic moves cluster around strategic partnerships for national certification access and geographic expansion into emerging aviation security markets.
Within the defense-contractor tier, L3Harris Technologies, Inc. and Leidos Holdings, Inc. exemplify players with integrated security ecosystems spanning federal aviation mandates. Smiths Detection and Nuctech Company Limited occupy distinct positions on the algorithm-specialist and manufacturing-scale vectors respectively, with the former emphasizing European transportation infrastructure and the latter sustaining cost advantages across Asia-Pacific deployment programs. Rapiscan Systems and Tek84, Inc. represent mid-tier specialists competing on detection modality breadth rather than ecosystem integration depth.
| Leading Market Players |
|---|
| Leidos Holdings, Inc. |
| LINEV Systems Ltd. |
| L3Harris Technologies, Inc. |
| Braun & Co. Limited |
| Tek84, Inc. |
| Smiths Detection |
| Nuctech Company Limited |
| Westminster Group plc |
| Rapiscan Systems |
| Others |
Supply Flow & Price Mechanics
Gallium arsenide wafer price indices cascade through millimeter wave RF component fabrication into tiered equipment pricing at airport procurement desks. Component cost volatility concentrates pricing power with East Asian foundry operators while modular tile architectures compress hardware margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates TSA-certified millimeter wave systems from EASA-compliant configurations and portable event-deployable units. Price differentiation hinges on detection algorithm sophistication and throughput certification tier. Pricing pressure stems from software-defined upgrade paths that extend hardware replacement cycles beyond traditional refresh periods. Mid-tier airports lacking in-house technical staffing exhibit highest price sensitivity, while Category X hub operators prioritize detection performance over capital expenditure constraints.
Supply Chain Analysis
Ocean freight cost fluctuations from East Asian semiconductor hubs to European and North American assembly facilities amplify landed cost variance across procurement cycles. Millimeter wave sensor arrays draw from Taiwan, South Korea, and China for specialized RF chip fabrication. Raw material dependencies span gallium arsenide substrates, high-frequency laminates, and precision antenna substrates. Single-source vulnerability concentrates at advanced node foundries capable of sub-6 GHz RF performance. Distribution runs through third-party security integrators bundling hardware, software licensing, and on-site technical staffing into service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate at the software layer where algorithm licensing generates recurring revenue streams detached from hardware depreciation cycles. Modular component standardization enables cost-down trajectories while premium-tier detection capabilities command pricing premiums.
For Market Incumbents: Deploy algorithm licensing platforms to capture recurring revenue from installed hardware bases. Consolidate certification investment across FAA, EASA, and CAAC jurisdictions to reduce redundant testing overhead. Threat from specialized detection algorithm developers intensifies as airports prioritize software upgrades over full system replacement. For New Entrants and Emerging Players: Enter via portable scanner configurations addressing temporary event security and emergency hub expansion requirements. White-space concentration appears at Indian metro airports and Southeast Asian aviation infrastructure programs. Go-to-market leverage rests on local service network establishment ahead of Bureau of Civil Aviation Security mandate implementation. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm-specialist firms possessing documented training data provenance and EU AI Act compliance pathways. Long-term viability favors vendors with integrated security ecosystems spanning federal aviation mandates. Acquisition target archetype: mid-tier detection algorithm developers with EASA certification traction. Signal to watch: checkpoint-as-a-service contract volume at privatized airport operators.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Platform Launch | Recurring revenue capture from TSA-mandated millimeter wave installations decouples vendor economics from hardware replacement cycles. |
| EASA Certification Pathway Investment | EU AI Act transparency requirements favor European-headquartered software providers with documented bias audit trails. |
| Portable Configuration Development | Major sporting events and emergency hub expansions create demand spikes where permanent installation economics fail. |
| Local Service Network Establishment | Bureau of Civil Aviation Security mandates at Indian metro airports reward first-mover vendors with on-ground technical capabilities. |
| Checkpoint-as-a-Service Partnership | UK airport privatization separates infrastructure ownership from operational responsibility, accelerating bundled contracting models. |
Methodological Framework
Bottom-up airport procurement modeling reconciled against top-down millimeter wave component manufacturing tracking forms the analytical core of this study. Primary interviews with airport security directors, TSA procurement officers, EASA certification specialists, and RF engineering leads at defense contractors combined with secondary validation from FDA radiation safety filings, EASA interoperability guidelines, and ICAO security standards documentation. Top-down triangulation against customs records for millimeter wave sensor array imports and TSA equipment deployment disclosures anchored volume estimates.
Historical trendline analysis across millimeter wave adoption curves and backscatter X-ray displacement patterns informed projection frameworks. Segmentation dimensions modeled include detection modality, deployment setting, integration depth, and regional regulatory cluster. CAGRs derived from equipment procurement schedules at Category X airports and algorithm licensing growth trajectories. Industry-specific forecast inputs encompass TSA Advanced Imaging Technology mandate timelines and EU AI Act implementation sequencing.
Inputs from airport procurement databases and federal security mandate disclosures were available through the study window; gaps in real-time algorithm licensing transaction data introduce uncertainty bands around software revenue projections. Forecasts reflect documented assumptions regarding certification timeline continuity and foundry capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
South America Data Center Physical Security Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
Global Data Center Physical Security Market
Physical Security
France Data Center Physical Security Market
Physical Security
Physical Security Equipment Market
Physical Security
Border Security Technologies Market
Physical Security
Physical Security Services Market
Physical Security
Security Guard Market
Physical Security
Physical Security Market
Physical Security
North America Physical Security Market
Physical Security
Policing Technologies Market
Physical Security
Tactical Lights Market
Physical Security
Body Armor Plates Market
Physical Security
Global Wearable Security Device Market
Physical Security
Security Market