
 Asia-Pacific Data Center Physical Security Market | 2026-2036
Asia-Pacific Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Data Center Physical Security Market Insights
Managed security service contracts are rebalancing vendor revenue models away from one-time hardware sales toward recurring subscription streams. Hangzhou Hikvision Digital Technology Co Ltd leverages its manufacturing scale to dominate camera supply across Chinese and Southeast Asian facilities. Bosch Sicherheitssysteme GmbH anchors premium installations through deep integration of access control and video analytics platforms. Axis Communications AB specializes in edge-computing camera architectures that reduce bandwidth loads for regional operators.
Asia-Pacific data center physical security encompasses perimeter barriers, biometric access systems, video surveillance infrastructure, and environmental threat detection engineered to protect mission-critical computing facilities from unauthorized intrusion, equipment theft, and operational disruption. Systems typically integrate IP-based cameras with minimum 4K resolution, multi-factor biometric readers, and real-time analytics processing at the network edge to enable sub-second incident response. CCTV Systems and access control capture the largest share of current expenditure as legacy facility retrofits continue across established markets. Video analytics represents the fastest-expanding technology segment as AI-powered behavioral detection reduces false alarm rates and staffing requirements for 24/7 operations.
India's BIS certification mandates and Australia's ASD Essential Eight framework shape product compliance requirements for equipment deployed in government and critical infrastructure facilities. China's GB standards for video surveillance interoperability and Japan's METI energy efficiency guidelines for data center operations further constrain vendor design choices and create regional specification fragmentation. Stakeholders must evaluate whether to develop geography-specific product variants or pursue modular platforms adaptable to multiple national certification regimes.
Market Dynamics
Hyperscale cloud providers across Southeast Asia are consolidating facility footprints, forcing security vendors to engineer modular platforms capable of rapid deployment across multi-megawatt campuses while satisfying divergent national certification regimes.
Growth Catalysts
- PLI scheme acceleration:India's production-linked incentive program for electronics manufacturing is spawning local assembly of biometric readers and camera modules, reducing import dependency for domestic data center operators.
- Cloud expansion:Southeast Asian cloud service providers are constructing hyperscale facilities in Singapore, Indonesia, and Malaysia, generating demand for integrated perimeter-to-rack security architectures.
- ASD Essential Eight:Australia's cybersecurity framework mandates multi-factor authentication and privileged access management for critical infrastructure, compelling facility upgrades across Sydney and Melbourne metro markets.
Market Restraints
- Semiconductor input volatility:Edge AI chip shortages for video analytics cameras are extending lead times for 4K camera deployments, compressing project margins for systems integrators.
- Supplier concentration:Chinese manufacturers dominate CMOS sensor supply, exposing regional operators to export control disruptions and tariff exposure on critical imaging components.
- Interoperability friction:China's GB/T 28181 video protocol standards create technical incompatibilities with ONVIF-compliant systems deployed in Australian and Indian facilities, forcing redundant engineering.
Strategic Opportunities
- Vietnam facility construction:Emerging data center clusters in Ho Chi Minh City and Hanoi remain underpenetrated by premium security vendors, offering first-mover positioning before hyperscale commitments finalize.
- AI-video convergence:Behavioral analytics engines are merging with thermal imaging for early fire detection, opening retrofit opportunities in aging Singaporean colocation facilities.
- Managed service channels:Security-as-a-service contracts are displacing capital purchase models, enabling recurring revenue capture from mid-tier enterprises in Thailand and the Philippines.
Industry Challenges
- Cyber-physical skill scarcity:Integration of IT network security with physical access control demands hybrid engineering competencies that regional labor markets currently undersupply.
- BIS certification timelines:India's mandatory testing for electromagnetic compatibility and environmental hardening extends product launch cycles by 8-14 months for foreign equipment vendors.
- Legacy analog retrofit complexity:Established facilities in Japan and Australia retain coaxial cable infrastructure, complicating IP migration without full rip-and-replace capital commitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Data Center Physical Security Market |
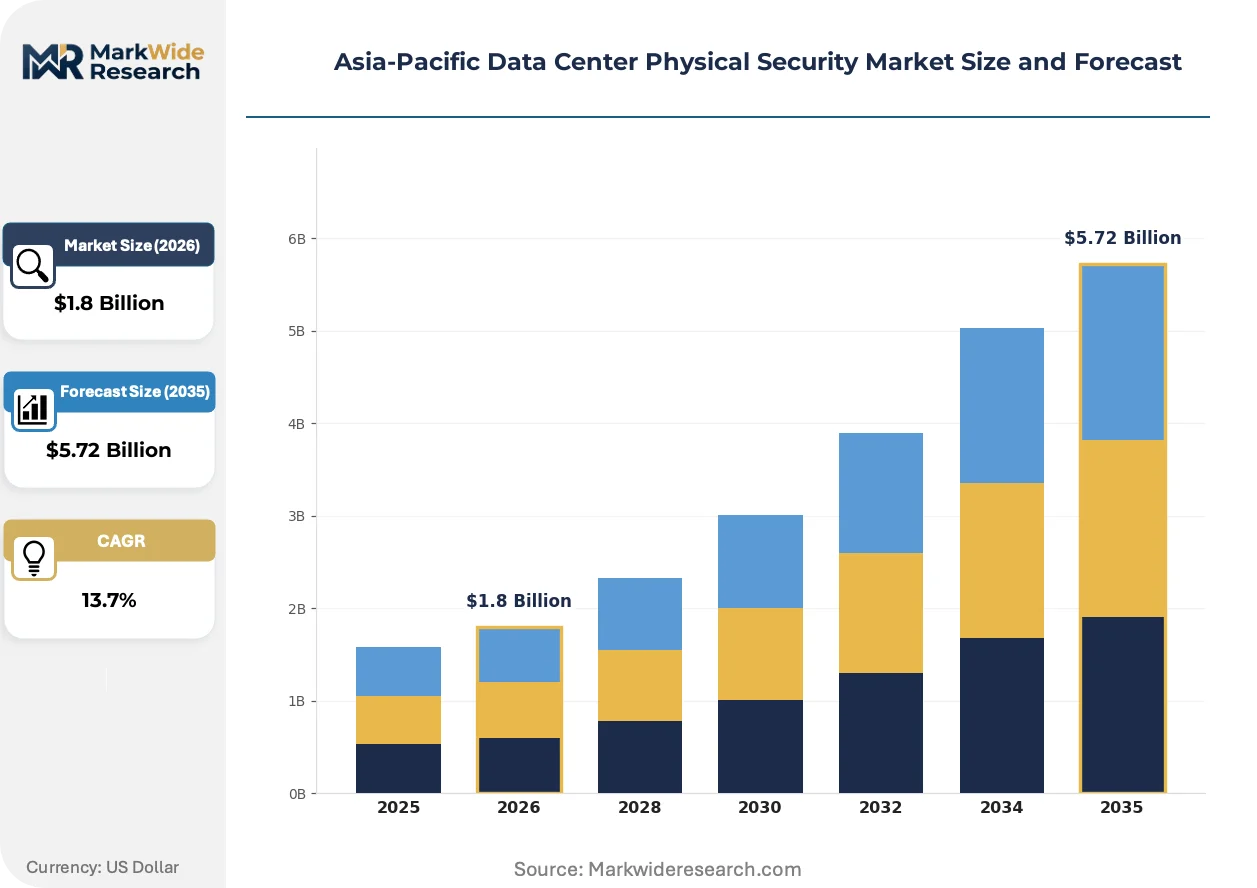
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Control, CCTV Systems, Intrusion Detection, Environmental Monitoring Technology: Biometrics, RFID, Video Analytics, Perimeter Security End User: Telecommunications, Healthcare, BFSI, Government Installation Type: Indoor, Outdoor, Hybrid, Managed Services |
| Companies Covered | Bosch Sicherheitssysteme GmbH, Hangzhou Hikvision Digital Technology Co Ltd, Axis Communications AB, Honeywell International Inc, HID Global Corporation, Zhejiang Dahua Technology Co., Ltd., Johnson Controls International, Schneider Electric, Securitas Technology, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Data Center Physical Security Market Trends and Innovations
Edge computing architectures are redistributing processing loads from central servers to camera endpoints, compressing bandwidth requirements while enabling real-time threat detection without cloud dependency.
Video analytics engines are converging with thermal sensor fusion to enable simultaneous intrusion detection and environmental hazard monitoring from single hardware nodes. Hyperscale operators in Singapore and Sydney are piloting these converged units to reduce rack-space allocation for security infrastructure. The technology is converging with building management systems to unify facility operations under single-pane dashboards, collapsing procurement silos between security and facilities teams.
Australia's ASD Essential Eight framework is mandating privileged access management with just-in-time credential issuance for all critical infrastructure personnel. Equipment vendors must now engineer biometric readers capable of certificate-based authentication rather than static credential storage. Facilities in Melbourne and Perth are prioritizing compliance-ready hardware over cost-optimized alternatives, reshaping competitive bidding criteria.
Colocation tenants are demanding unbundled security service tiers rather than bundled facility packages, forcing operators to price video retention, guard response, and biometric enrollment as discrete line items. This unbundling is most visible in Singapore's competitive wholesale market, where tenant churn sensitivity drives transparency. Channel partners in Mumbai and Bangalore are reconfiguring sales compensation to favor recurring service attach rates over upfront hardware margins.
Asia-Pacific Data Center Physical Security Market Segmentation
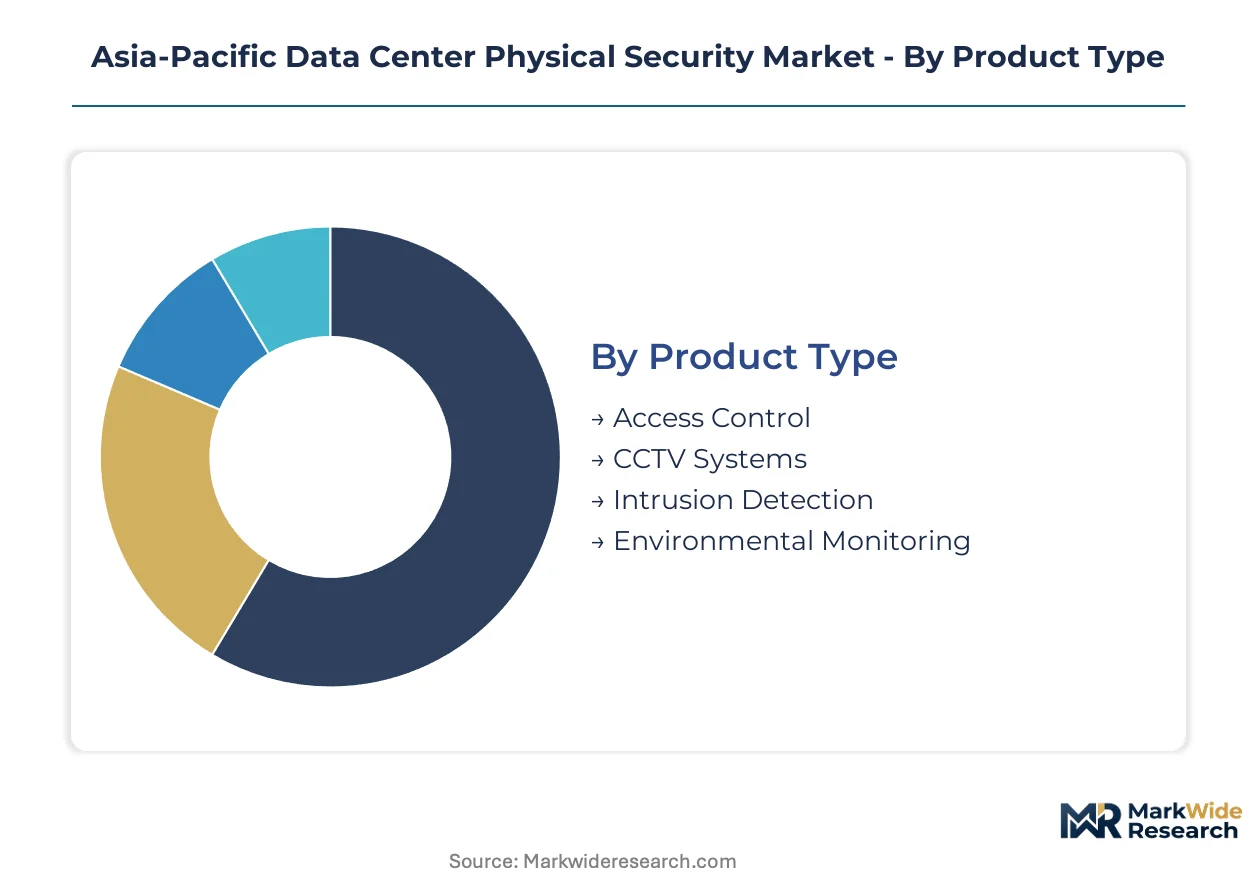
Facility upgrade cycles across the Asia-Pacific region create divergent procurement patterns for physical security components. Retrofit demand in established markets like Australia and Japan favors modular solutions compatible with legacy infrastructure, while greenfield hyperscale construction in India and Southeast Asia drives integrated platform adoption.
Product Type:
Replacement timelines vary sharply by product category, with video infrastructure refreshing every 5-7 years and access control systems extending to 10-12 year cycles.
- CCTV Systems:IP-based camera networks with 4K resolution and edge-computing capabilities now dominate new installations. Singaporean colocation operators are consolidating vendor relationships to secure AI-enabled behavioral analytics for 24/7 unmanned facilities.
- Access Control:Multi-factor biometric readers and certificate-based authentication modules are displacing card-based systems. Australia's ASD Essential Eight mandates are accelerating privileged access management upgrades across Sydney and Melbourne critical infrastructure sites.
- Intrusion Detection:Perimeter sensors and rack-level monitoring devices protect against unauthorized physical entry. Indian data centers are integrating these with BIS-certified electromagnetic hardened enclosures.
- Environmental Monitoring:Temperature, humidity, and leak detection sensors safeguard equipment from operational hazards. Thermal sensor fusion with video analytics is gaining traction in aging Singaporean facilities for early fire detection.
Volume placements concentrate in CCTV Systems; the faster expansion belongs to Environmental Monitoring as thermal-video convergence enables unified hazard detection.
Technology:
Cost tiers separate premium AI-enabled platforms from standardized commodity hardware, with procurement patterns diverging by facility maturity and compliance burden.
- Video Analytics:AI-powered behavioral detection engines process footage at the network edge to reduce bandwidth loads and false alarm rates. Hyperscale operators in Singapore and Sydney are piloting these for sub-second incident response without cloud dependency.
- Biometrics:Fingerprint, iris, and facial recognition readers provide multi-factor authentication for facility entry. India's PLI scheme is accelerating local assembly of biometric modules to reduce import dependency for domestic operators.
- Perimeter Security:Barriers, fencing, and ground sensors protect facility boundaries from intrusion. Vietnamese data center clusters in Ho Chi Minh City remain underpenetrated by premium perimeter vendors.
- RFID:Radio-frequency identification tags track asset movement and enable contactless access credentialing. Legacy deployments persist in Japanese facilities with coaxial infrastructure complicating IP migration.
Biometrics commands the largest procurement volumes; Video Analytics is climbing the fastest as edge AI chip availability improves.
End User:
Application requirements differ materially across verticals, with government and BFSI segments demanding certified compliance hardware while telecommunications prioritizes scale economics.
- Telecommunications:Carrier-neutral facilities and telco-owned data centers require perimeter-to-rack security architectures capable of rapid scaling. Southeast Asian cloud expansion is concentrating demand in Singapore, Indonesia, and Malaysia.
- Government:Critical infrastructure protection mandates drive specification of BIS-certified, ASD-compliant, or GB-standard equipment depending on national jurisdiction. Procurement cycles extend 8-14 months for foreign equipment vendors seeking Indian certification.
- BFSI:Banking and financial services institutions demand audit-ready access logs and privileged credential management. Australian regulatory frameworks are reshaping competitive bidding criteria toward compliance-ready hardware.
- Healthcare:Medical data protection requirements and business continuity needs shape security investments. Facility operators balance physical protection with infection control protocols for personnel movement.
Telecommunications absorbs the heaviest equipment volumes; Government procurement is gaining share fastest on critical infrastructure designation expansion.
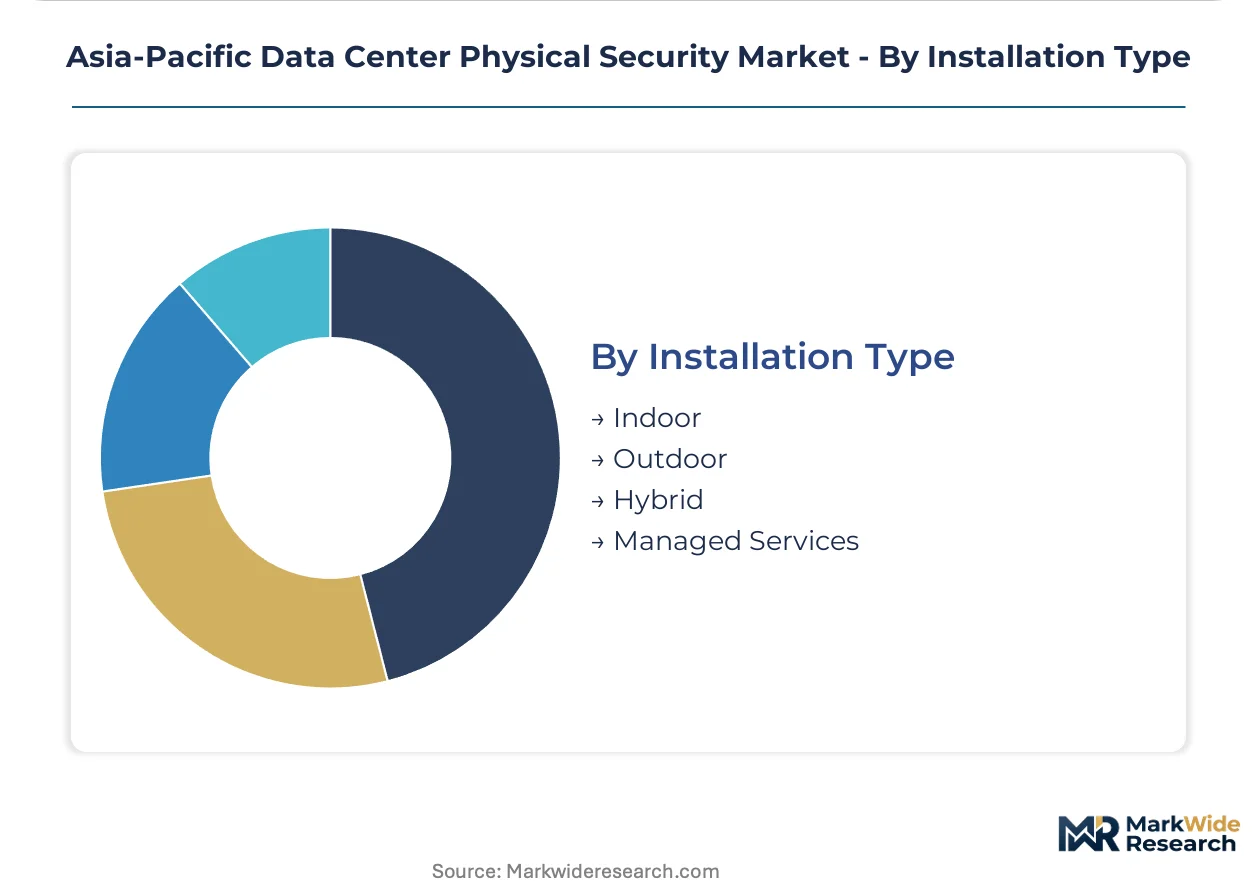
Installation Type:
Customer type stratification separates capital-purchasing enterprises from service-oriented operators, with managed security channels displacing traditional hardware sales.
- Managed Services:Security-as-a-service contracts bundle monitoring, maintenance, and response under recurring subscription models. Mid-tier enterprises in Thailand and the Philippines are shifting procurement from upfront capital expenditure to operational expenditure frameworks.
- Hybrid:Combined indoor-outdoor deployments with unified command interfaces reduce operational complexity. Colocation tenants in Singapore's wholesale market are demanding unbundled security tiers priced as discrete service line items.
- Indoor:Rack-level and facility interior protection systems focus on access control and environmental monitoring. Retrofit complexity in Japanese and Australian legacy facilities favors modular indoor upgrades over full infrastructure replacement.
- Outdoor:Perimeter barriers, lighting, and surveillance protect facility exteriors from intrusion and environmental threats. Vietnam's emerging data center clusters offer first-mover positioning before hyperscale commitments finalize.
Indoor installations retain the largest installed base; Managed Services is expanding most quickly as channel partners reconfigure compensation toward recurring attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Tuas data center corridor anchors regional hyperscale construction, with cloud providers consolidating multi-megawatt campuses that demand integrated perimeter-to-rack security architectures. National certification regimes diverge sharply across jurisdictions, forcing vendors to engineer modular platforms adaptable to BIS, ASD, and GB standards.
Singapore
Hyperscale cloud expansion in Tuas and Changi North drives demand for AI-enabled video analytics and unmanned facility operations. The Infocomm Media Development Authority's data center standards shape procurement specifications for environmental monitoring integration. Colocation operators in the wholesale market are unbundling security tiers as tenant churn sensitivity rises.
India
Mumbai's Navi Mumbai cluster and Chennai's Sriperumbudur corridor concentrate new data center construction requiring BIS-certified biometric readers and electromagnetic-hardened enclosures. The PLI scheme for electronics manufacturing accelerates local assembly of camera modules and access control components. Certification timelines extend 8-14 months for foreign equipment vendors seeking electromagnetic compatibility approval.
Australia
Sydney's Macquarie Park and Melbourne's Derrimut data center zones face ASD Essential Eight compliance mandates for privileged access management and multi-factor authentication. Critical infrastructure designation expands procurement criteria toward certificate-based biometric readers over cost-optimized alternatives. Legacy coaxial infrastructure in established facilities complicates IP migration without full capital replacement.
Japan
Tokyo's Inzai and Osaka's Sakai data center districts retain aging analog systems that favor modular indoor upgrades over rip-and-replace strategies. METI energy efficiency guidelines for data center operations constrain security infrastructure rack-space allocation. Coaxial cable persistence in facilities built during the 2000s complicates edge-computing camera deployments.
Vietnam
Ho Chi Minh City's emerging data center clusters in District 9 and Thu Duc City remain underpenetrated by premium security vendors ahead of hyperscale commitments. The Ministry of Information and Communications' draft data center regulations are shaping early facility design standards. First-mover positioning opportunities exist for perimeter security vendors before cloud provider footprints finalize.
Asia-Pacific Data Center Physical Security Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia-Pacific data center physical security market, with integrated platform vendors holding pricing power over modular component suppliers. The vendor base stratifies into three tiers: multinational conglomerates with building management integration capabilities, specialized security pure-plays with edge AI competencies, and regional manufacturers competing on certification agility. Dominant competitive moves include backward integration into CMOS sensor supply and strategic partnerships with hyperscale cloud operators for reference architecture co-development.
Within the premium-tier vector, Bosch Sicherheitssysteme GmbH and Axis Communications AB occupy positions emphasizing deep system integration and edge-computing architectures respectively. Hangzhou Hikvision Digital Technology Co Ltd exemplifies the scale-driven archetype, leveraging manufacturing footprint to supply camera infrastructure across Chinese and Southeast Asian deployments. These three entities represent contrasting strategic postures: European engineering differentiation, Nordic edge-AI specialization, and Chinese vertical integration into component supply.
| Leading Market Players |
|---|
| Bosch Sicherheitssysteme GmbH |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Axis Communications AB |
| Honeywell International Inc |
| HID Global Corporation |
| Zhejiang Dahua Technology Co., Ltd. |
| Johnson Controls International |
| Schneider Electric |
| Securitas Technology |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between BIS-certified premium hardware and uncertified commodity equipment manifests in divergent margin structures and sourcing footprints across the Asia-Pacific data center security market. Premium vendors absorb extended electromagnetic compatibility testing timelines in India and ASD compliance engineering in Australia, while commodity suppliers leverage China's manufacturing density for cost-down positioning in Southeast Asian greenfield projects.
Pricing Analysis
Margin tightening in the premium tier reflects extended certification cycles for Indian BIS electromagnetic compatibility and Australian ASD Essential Eight privileged access mandates. Three-tier pricing structure across premium, standard, and economy levels separates compliance-ready hardware with certificate-based biometric authentication from cost-optimized alternatives lacking modular upgrade paths. Pricing pressure intensifies in the standard tier as Chinese manufacturers exploit PLI scheme spillover into Southeast Asian markets. Government and BFSI buyers exhibit lowest price sensitivity due to audit-readiness requirements, while telecommunications operators prioritize scale economics over feature depth.
Supply Chain Analysis
Freight cost volatility from Chinese manufacturing hubs to Indian data center clusters in Mumbai and Chennai compounds landed cost uncertainty for edge AI chip-dependent video analytics platforms. CMOS sensor supply concentrates in China, with secondary sourcing from South Korean and Japanese fabrication facilities. Raw material dependencies span silicon wafers, rare-earth magnets for biometric reader motors, and copper for electromagnetic shielding enclosures. Single-source vulnerability in Chinese CMOS sensor supply exposes regional operators to export control disruptions. Distribution runs through systems integrators with certification expertise in target jurisdictions rather than direct vendor-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
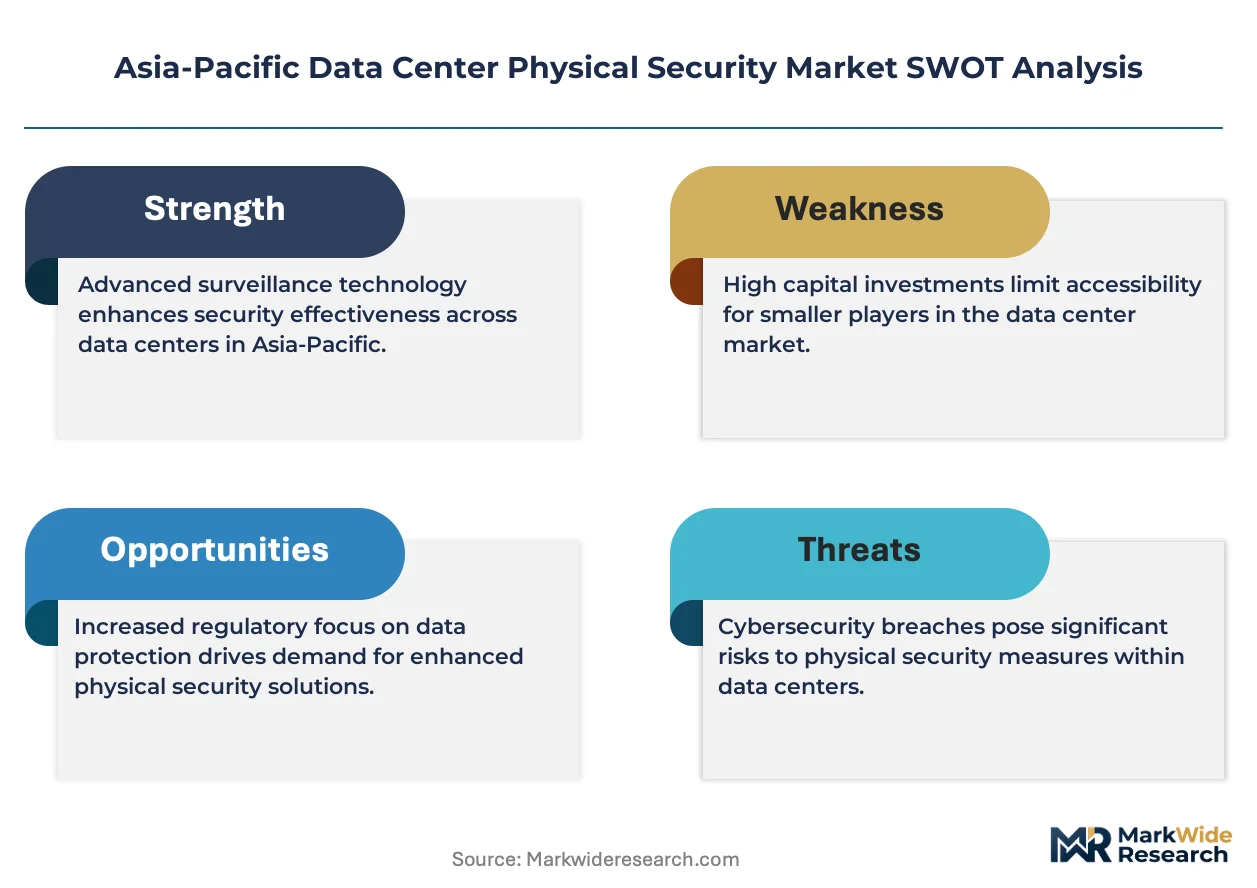
Asia-Pacific data center physical security is consolidating around vendors with multi-jurisdiction certification agility, with semiconductor input volatility and compliance timeline extension forcing sub-scale players toward exit or acquisition.
For Market Incumbents: Cement market position through backward integration into edge AI chip supply and captive certification engineering capabilities in India and Australia. Threat substitution from cloud-native security platforms demands preemptive API development for hyperscale operator integration. Channel control through exclusive systems integrator partnerships in Vietnam and Indonesia represents the priority defensive lever. For New Entrants and Emerging Players: Security-as-a-service digital channels offer the lowest friction route to mid-tier enterprise accounts in Thailand and the Philippines. Vietnam's Ho Chi Minh City data center clusters remain the most penetrable geography ahead of hyperscale commitment finalization. Unbundled service tier pricing for colocation tenants provides the sharpest go-to-market angle against bundled incumbent offerings. For Investors and Strategic Acquirers: Re-rating potential sits with edge-AI-specialized pure-plays given hyperscale pilot program conversion into multi-campus rollouts. Long-term viability over the next decade hinges on modular platform architectures adaptable to evolving BIS, ASD, and GB certification regimes. The signal to watch is PLI scheme beneficiary acquisition by multinational conglomerates seeking Indian manufacturing footprint.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Engineering Investment | BIS and ASD compliance capabilities unlock government and BFSI procurement in India and Australia. |
| Edge AI Chip Supply Agreement | Captive sensor supply hedges against Chinese CMOS export control exposure for video analytics deployments. |
| Managed Service Channel Partnership | Recurring revenue capture from Thai and Philippine mid-tier enterprises displaces capital purchase models. |
| Vietnam Market Entry | First-mover positioning in Ho Chi Minh City clusters before hyperscale cloud provider commitments finalize. |
| Modular Platform Development | Adaptable architectures reduce redundant engineering across China's GB standards and Australia's ONVIF protocols. |
Research Methodology
Multi-period observation of hyperscale facility construction permits, PLI scheme beneficiary registrations, and BIS certification timelines anchored the trend analysis, supplemented by interviews with data center security directors, systems integration firm principals, hyperscale cloud procurement officers, and electromagnetic compatibility testing laboratory managers. Secondary validation drew from Infocomm Media Development Authority data center standards filings, Australian Signals Directorate critical infrastructure guidance, India's BIS product certification databases, and hyperscaler capital expenditure disclosures. Bottom-up facility-level demand aggregation and top-down regional market sizing provided triangulation integrity.
Segment-weighting across product type, technology tier, end-user vertical, and installation model dimensions structured the analytical framework across the projection horizon. CAGRs derived from facility construction pipeline analysis, replacement cycle modeling for CCTV and access control systems, and managed service attach rate trending. Industry-specific forecast inputs included edge AI chip availability curves and national certification regime expansion schedules.
The model holds under stable semiconductor supply conditions and continued hyperscale cloud expansion; deviation in export control escalation or PLI scheme modification would shift vendor competitive positioning. Forecasts reflect documented assumptions about facility construction completion rates and certification timeline standardization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
South America Data Center Physical Security Market
Physical Security
France Data Center Physical Security Market
Physical Security
Smart Police Helmet Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Border Security Technologies Market
Physical Security
Global Wearable Security Device Market
Physical Security
Security Guard Market
Physical Security
Bulletproof Glass Market
Physical Security
Security Market
Physical Security
Physical Security Services Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
Active Geofencing Market
Physical Security
Tactical Lights Market