
 Global Data Center Physical Security Market | 2026-2036
Global Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center Physical Security Market Intelligence
The traditional training cycle for certified physical security technicians is collapsing under the pressure of rapid technology evolution. Schneider Electric SE leverages its expertise in power management and cooling to integrate physical security solutions within the broader data center infrastructure. Honeywell International Inc. specializes in advanced access control and video surveillance systems tailored for high-security environments. ASSA ABLOY AB focuses on securing entry points with sophisticated locking mechanisms and electronic access solutions.
Data center physical security involves technologies preventing unauthorized physical access to servers, networking equipment, and data storage. It employs layered defenses, from perimeter security to rack-level biometric scanners verifying traits like fingerprints or irises. Demand from hyperscale operators and colocation facilities drives investment in scalable, centrally managed security platforms. Biometric systems and advanced video surveillance analytics represent high-growth technology segments, aimed at mitigating insider threats.
Regulatory frameworks like the EU's GDPR create stringent requirements for data protection, which extends to the physical security of the infrastructure housing that data. In the United States, standards from NIST and compliance mandates such as HIPAA for healthcare data dictate specific access control and monitoring protocols. The central challenge for operators is to deploy increasingly sophisticated security measures without impeding the operational agility required by authorized personnel.
Market Dynamics
The central dynamic in the data center physical security market is the escalating requirement for integrated, intelligent security systems. This pressure originates from the convergence of stringent data privacy regulations and the operational scale demanded by hyperscale cloud providers.
Growth Catalysts
- Regulatory Mandates:Frameworks such as the EU's GDPR impose strict data protection duties, which directly translate into requirements for auditable physical access controls, driving investment in compliant security hardware and software.
- Insider Threat Mitigation:Demand from hyperscale operators for rack-level security is rising, fueling adoption of biometric technologies like fingerprint and iris scanners to verify identity at the server level and prevent unauthorized internal access.
- Concentrated Infrastructure Build-Out:The rapid expansion of data center clusters in established hubs, including Northern Virginia in the United States and Singapore's digital parks, creates dense pockets of high-value infrastructure requiring state-of-the-art physical protection.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for advanced solutions, such as multi-layered biometric systems and AI-driven video analytics platforms, can be prohibitive for smaller operators or those upgrading legacy facilities.
- Integration Complexity:Marrying modern IP-based security systems with disparate legacy building management systems and IT infrastructure presents considerable technical challenges, risking operational friction and incomplete integration.
- Lack of Interoperability Standards:A fragmented vendor landscape with proprietary protocols for hardware like access readers and cameras complicates the creation of a truly unified, single-pane-of-glass security management platform.
Strategic Opportunities
- Emerging Geographic Markets:Greenfield data center construction in developing hubs across the Middle East and Southeast Asia provides opportunities to deploy comprehensive, modern security architectures without the constraints of legacy systems.
- Physical-Cyber Convergence:Integrating physical access event data with cybersecurity information and event management (SIEM) platforms enables a holistic security posture, correlating a physical breach with digital activity for faster threat response.
- Security-as-a-Service (SECaaS):Offering subscription-based managed security services, including remote monitoring and access management, lowers the entry barrier for customers by shifting costs from capital to operational expenditure.
Industry Challenges
- Specialized Talent Shortage:A widening skills gap exists for technicians qualified to install, integrate, and maintain complex, networked physical security systems, slowing deployment and increasing labor costs for operators.
- Balancing Security and Agility:Implementing granular, multi-factor access controls at every layer creates operational friction, challenging operators to secure facilities without hindering the rapid access required by authorized personnel for maintenance and repairs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center Physical Security Market |
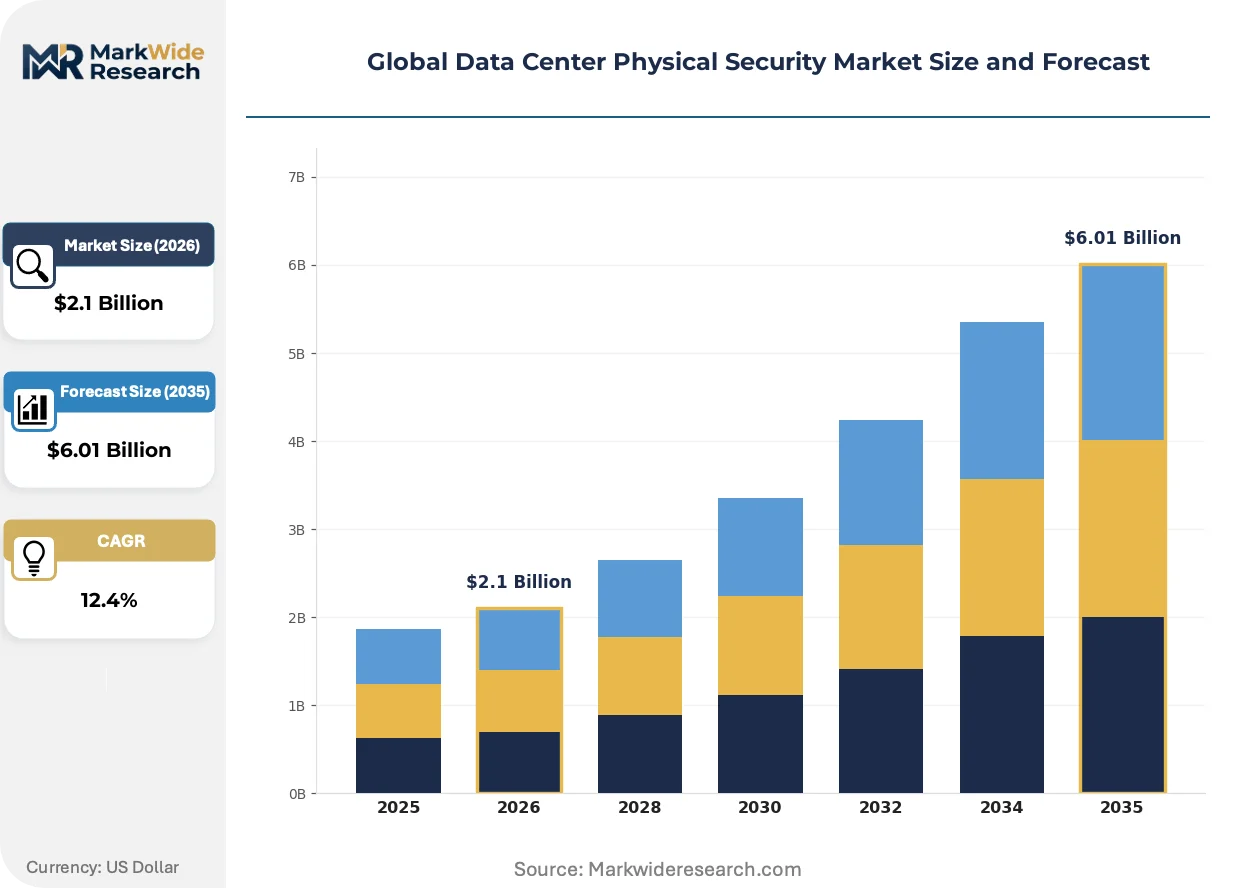
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.01 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Technology: Biometric Systems, Video Surveillance, Access Control, Intrusion Detection, Perimeter Security Deployment Mode: On-Premises, Cloud-Managed, Hybrid, Edge, Virtualized Application Sector: Telecommunications, Financial Services, Cloud Service Providers, Government Agencies, Educational Institutions End User Type: Colocation Facilities, Hyperscale Operators, Managed Service Providers, Enterprise Companies, Research Institutions |
| Companies Covered | Robert Bosch GmbH, Hangzhou Hikvision Digital Technology Co., Ltd., Honeywell International Inc., Axis Communications AB, Zhejiang Dahua Technology Co., Ltd., Schneider Electric SE, ASSA ABLOY AB, Johnson Controls International plc, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center Physical Security Market Strategic Shifts & Innovations
The market is shifting from isolated security components toward unified, intelligent ecosystems. This evolution is driven by the need to automate threat detection, prove regulatory compliance, and simplify management across sprawling, complex data center environments.
AI-powered video analytics provide real-time object classification and behavioral analysis, moving beyond simple motion detection. Hyperscale and major colocation providers are adopting these systems to automate monitoring of vast facilities and reduce reliance on human operators. This intelligent video analysis is displacing traditional passive CCTV monitoring, which depended entirely on human attention to identify security events.
In the United States, compliance frameworks such as HIPAA and NIST standards impose strict physical access logging and auditing requirements. These rules compel data center operators to maintain immutable, detailed records of every access attempt at all secured perimeters and interior doors. The colocation segment is particularly impacted, as providers must demonstrate auditable compliance to tenants from diverse regulated industries.
A preference for unified security platforms is altering purchasing patterns for new data center builds. Operators are moving away from sourcing individual best-of-breed systems for video, access, and intrusion, instead favoring single-vendor suites that offer pre-integrated hardware and software. This trend is most prominent in hyperscale and large enterprise projects where standardization simplifies deployment, training, and lifecycle management.
Global Data Center Physical Security Market Segmentation
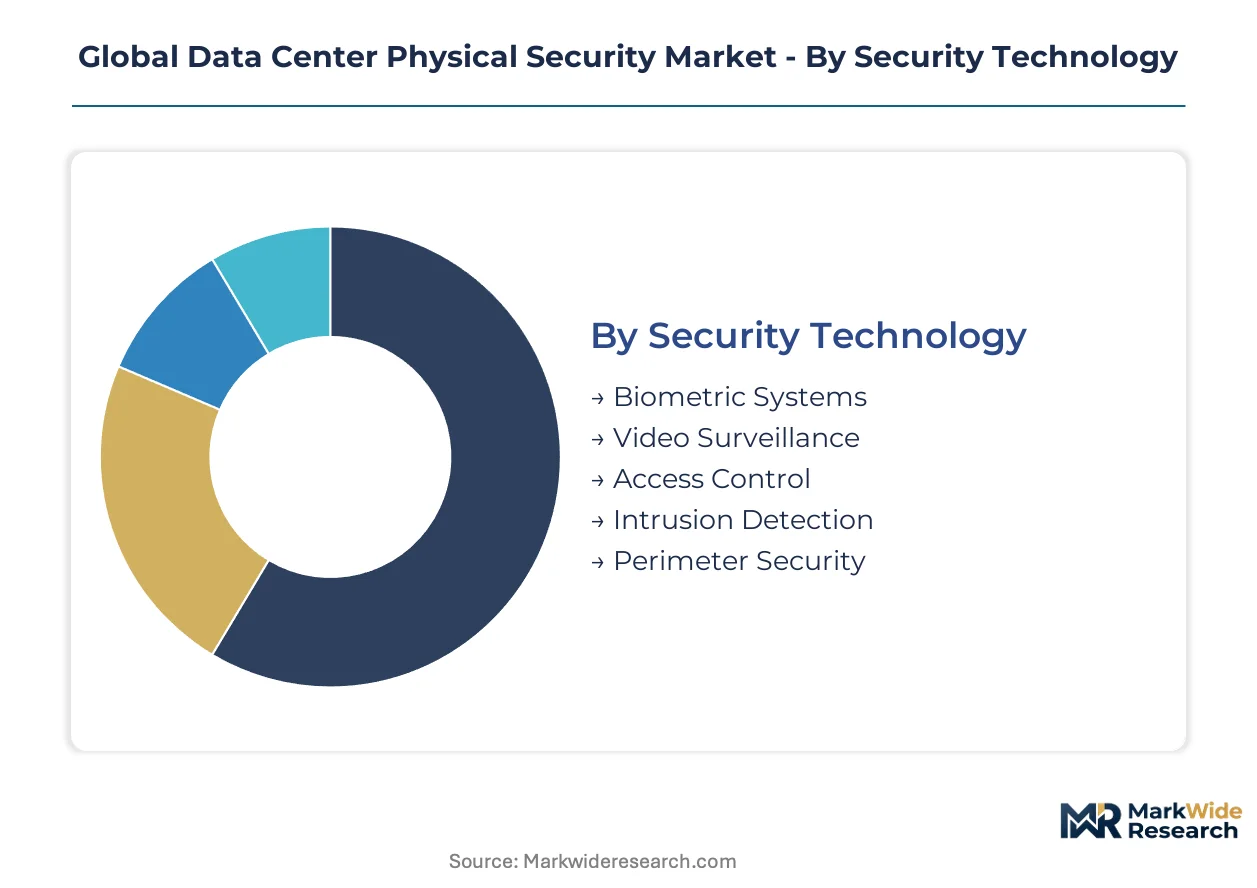
The global data center physical security market segments across multiple dimensions, reflecting the diverse operational requirements and regulatory landscapes confronting operators. Understanding these distinctions helps stakeholders identify specific technology demands and deployment preferences. Each segment addresses unique vulnerabilities and compliance mandates within the data center ecosystem.
Security Technology:
Regulatory frameworks such as the EU's GDPR and the United States' HIPAA drive significant differentiation in security technology adoption, mandating specific levels of data protection and access control. Operators must select technologies that not only deter physical threats but also provide auditable records for compliance.
- Biometric Systems:These systems identify individuals based on unique physiological or behavioral characteristics, such as fingerprints, iris patterns, or facial recognition. Demand is concentrating in hyperscale data centers in Northern Virginia for rack-level access verification to mitigate insider threats.
- Video Surveillance:Advanced video surveillance employs high-resolution cameras and AI-powered analytics for real-time object classification, behavioral analysis, and anomaly detection. Cloud service providers in Singapore's digital parks deploy these systems to automate monitoring across vast facilities.
- Access Control:This category includes electronic locks, card readers, and keypads that manage entry and exit points within a data center.
- Intrusion Detection:Sensors and alarms designed to detect unauthorized entry or activity within secure areas form the core of intrusion detection systems.
- Perimeter Security:Physical barriers, fences, and gate controls establish the outermost layer of defense around data center facilities.
Established volume favors Access Control; emerging adoption favors Biometric Systems.
Deployment Mode:
The operational scale and infrastructure complexity of data centers significantly influence the preferred deployment mode for physical security solutions. Operators balance control, scalability, and integration capabilities when choosing between on-premises, cloud-managed, or hybrid models.
- Cloud-Managed:Security solutions managed remotely through a cloud platform offer scalability, centralized administration, and reduced on-site infrastructure. Managed service providers across Europe increasingly adopt cloud-managed systems for their distributed data center portfolios.
- Hybrid:A combination of on-premises hardware and cloud-based management or analytics provides a flexible approach, leveraging existing infrastructure while gaining cloud benefits. Enterprise companies in the United States often utilize hybrid deployments to integrate legacy systems with newer technologies.
- On-Premises:All security hardware and software are installed and managed directly within the data center facility, offering maximum control.
- Edge:Security processing and analytics occur closer to the data source, reducing latency and bandwidth requirements for distributed environments.
- Virtualized:Security functions are delivered as software instances on virtual machines, enhancing flexibility and resource utilization.
On-premises solutions maintain a substantial base; cloud-managed deployments are expanding most quickly.
Application Sector:
Different application sectors demand tailored physical security solutions due to varying data sensitivity, regulatory compliance requirements, and operational criticality. Each sector presents unique threat profiles and protection priorities for its data center assets.
- Financial Services:This sector requires the highest levels of physical security to protect sensitive transaction data and comply with stringent financial regulations. Major banks in London deploy multi-layered biometric and access control systems for their data centers.
- Cloud Service Providers:These operators manage vast, multi-tenant infrastructures, necessitating scalable and centrally managed security platforms. Hyperscale providers in Japan invest heavily in advanced video analytics and unified security suites.
- Telecommunications:Robust physical security protects critical network infrastructure and ensures continuous service availability for telecommunication companies.
- Government Agencies:Strict access controls and auditing capabilities are paramount for government data centers housing classified or sensitive public information.
- Educational Institutions:Physical security protects research data, student records, and valuable IT equipment within university and college data centers.
The financial services sector holds significant market share; cloud service providers demonstrate the steepest expansion trajectory.
End User Type:
The specific operational models and scale of end-user types dictate their physical security needs, from the massive infrastructure of hyperscale operators to the diverse tenant requirements of colocation facilities. Security solutions must align with each user's unique business objectives and risk tolerance.
- Hyperscale Operators:These large-scale data center operators require highly automated, scalable, and integrated physical security systems to manage vast facilities efficiently. Companies like Google and Amazon implement advanced rack-level biometrics and AI-driven surveillance.
- Colocation Facilities:Providers hosting equipment for multiple tenants must offer auditable compliance and flexible security options to meet diverse client requirements. Colocation centers in Frankfurt prioritize robust access control and detailed logging for tenant accountability.
- Managed Service Providers:These entities offer IT services and often manage data center infrastructure for clients, requiring reliable and remotely manageable security.
- Enterprise Companies:Businesses operating their own data centers need physical security to protect proprietary data and ensure business continuity.
- Research Institutions:Universities and scientific organizations deploy physical security to safeguard valuable research data and specialized computing equipment.
Hyperscale operators represent a significant demand segment; colocation facilities are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HIPAA compliance mandates in the United States drive investment in robust physical security for sensitive data. Data privacy regulations globally elevate the need for advanced access controls and surveillance systems. This pressure shapes regional market dynamics across key data center hubs.
United States
The United States market sees strong demand from hyperscale operators and financial institutions protecting critical data assets. NIST standards and HIPAA compliance dictate specific access control and monitoring protocols for data centers. Northern Virginia continues as a primary hub, experiencing concentrated infrastructure build-out.
Singapore
Singapore's digital parks exhibit high demand for advanced physical security solutions from cloud service providers. The EU's GDPR framework influences security protocols, despite being external, due to international data flows. These parks deploy sophisticated video surveillance systems to automate monitoring across vast facilities.
Germany
German colocation facilities prioritize robust physical security to meet diverse tenant requirements and auditable compliance. GDPR mandates stringent access controls, directly impacting data center operations. Frankfurt's data center cluster is a key focus for investment in advanced security platforms.
United Kingdom
London's financial services sector drives significant investment in multi-layered physical security for its data centers. UK data protection regulations, mirroring GDPR, enforce strict data protection duties. Major banks in the city deploy advanced biometric and access control systems for sensitive transaction data.
Japan
Japanese hyperscale providers invest heavily in scalable and centrally managed security platforms for their extensive infrastructure. Japan's APPI framework necessitates stringent data protection measures, including physical access controls. Tokyo’s data centers lead in adopting advanced video analytics and unified security suites.
Global Data Center Physical Security Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the data center physical security market. The competitive structure is tiered, with established technology conglomerates offering comprehensive solutions alongside niche providers specializing in specific security components. Strategic archetypes include integrated solution providers, access control specialists, and video surveillance innovators. Companies pursue portfolio diversification and strategic partnerships to enhance their market reach and solution breadth.
Integrated solution providers in the market include Schneider Electric SE, which leverages its power management expertise to offer holistic security systems. Honeywell International Inc. exemplifies a major technology conglomerate, occupying a position as a key provider of advanced access control and video surveillance systems. ASSA ABLOY AB, a Sweden-based entity, anchors the segment focused on sophisticated locking mechanisms and electronic access solutions, securing critical entry points for data centers globally. These entities represent diverse approaches to delivering physical security infrastructure.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Honeywell International Inc. |
| Axis Communications AB |
| Zhejiang Dahua Technology Co., Ltd. |
| Schneider Electric SE |
| ASSA ABLOY AB |
| Johnson Controls International plc |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
The data center physical security market often utilizes project-based contracts for large-scale deployments, which establish upfront pricing for complex integrated solutions. These contracts secure both equipment supply and service delivery, providing price visibility for hyperscale operators and colocation facilities.
Pricing Analysis
Project-based pricing dominates large data center physical security installations, reflecting the unique integration requirements of each facility. Price differentiation stems from the customization level of advanced biometrics and the certification grade required for compliance with frameworks like GDPR or NIST standards. Pricing pressure intensifies for smaller operators due to the significant capital expenditure of multi-layered systems. Hyperscale operators exhibit lower price sensitivity, prioritizing comprehensive security and scalability, while smaller enterprises seek more cost-effective, cloud-managed solutions.
Supply Chain Analysis
Inventory levels for specialized physical security components often reflect extended lead times for advanced microcontrollers and optical sensors. Global supply concentration for these critical inputs centers on manufacturing hubs in China and specialized component producers in Germany and the United States. The supply chain faces single-source vulnerability for high-performance biometric readers and AI-powered video analytics processors. Distribution runs through direct sales channels for major hyperscale and colocation providers, while value-added resellers and system integrators serve smaller enterprise data centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data center physical security market presents a defensive-moat story, driven by significant regulatory entrenchment from frameworks like GDPR and HIPAA. These mandates create high barriers to entry and ensure sustained demand for compliant, sophisticated security solutions.
For Market Incumbents: Compound existing expertise by integrating physical security solutions more deeply into broader data center infrastructure, leveraging power management and cooling strengths. Strategic partnerships with AI analytics firms can counter the threat of rapidly evolving, specialized technology entrants. Investing in certifications like NIST compliance for new offerings further entrenches market position against emerging digital threats. Expanding capacity in established hubs such as Northern Virginia also solidifies regional dominance.
For New Entrants and Emerging Players: Managed security services for smaller colocation facilities represent a significant service-layer gap, as incumbents often focus on large hyperscale deployments. Target greenfield data center construction in emerging geographic markets like the Middle East, offering comprehensive, cloud-managed security architectures. A go-to-market angle focusing on subscription-based Security-as-a-Service (SECaaS) lowers capital expenditure barriers for these new facilities. Penetrating the mid-tier enterprise segment with flexible, integrated solutions offers another viable pathway.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated solution providers with strong intellectual property in AI-powered video analytics and biometric systems. Long-term viability (over the next 5-10 years) hinges on platforms that enable physical-cyber convergence for holistic threat response. Acquisition targets should be niche specialists offering proven interoperability with existing building management systems. The signal to watch is the widespread adoption of unified security platforms across diverse regulated industries, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Physical-Cyber Systems | Correlates physical access events with cybersecurity data for enhanced threat detection and response. |
| Develop AI-Powered Video Analytics | Automates monitoring and anomaly detection across vast data center facilities, reducing human operator reliance. |
| Expand SECaaS Offerings | Lowers entry barriers for smaller operators by shifting physical security costs from capital to operational expenditure. |
| Invest in Biometric R&D | Enhances rack-level security and mitigates insider threats through advanced identity verification in hyperscale data centers. |
| Target Emerging Geographic Hubs | Deploys modern security architectures in greenfield data center construction without legacy system integration challenges. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings of this study. Interviews included data center security directors, IT procurement officers, system integrators, and physical security technicians. Secondary validation utilized regulatory filings, technology whitepapers, industry association reports, and financial disclosures from leading providers. The analysis employed both bottom-up market sizing and top-down validation to ensure data integrity.
Sensitivity analysis explored various growth scenarios for the data center physical security market across the analysis window. The analytical framework segmented the market by security technology, deployment mode, application sector, and end-user type, along with regional regulatory compliance requirements. Compound annual growth rates were derived from historical trends, projected technology adoption rates, and anticipated infrastructure build-outs. Forecast inputs included planned data center capacity additions and evolving regulatory enforcement levels.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in unforeseen supply chain disruptions for critical components. Forecasts reflect current technology roadmaps and expected investment cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Canada Data Center Physical Security Market
Physical Security
Physical Security Services Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Policing Technologies Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Physical Security Equipment Market
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
South America Data Center Physical Security Market
Physical Security
Tactical Lights Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Tactical Vests Market
Physical Security
Body Armor Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
Border Security Technologies Market