
 Hong Kong Data Center Physical Security Market | 2026-2036
Hong Kong Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Data Center Physical Security Market Insights
Perimeter hardening and biometric access control is rewriting margin distribution across the Hong Kong data center security value chain. Honeywell International Inc leverages its building automation heritage to anchor integrated fire safety and access control portfolios. Schneider Electric sustains competitive positioning through energy-efficient security infrastructure that reduces facility power overhead. Bosch Sicherheitssysteme GmbH specializes in video analytics and edge-based threat detection for high-density server environments.
Hong Kong Data Center Physical Security encompasses layered protection systems—ranging from mantrap portals and iris scanners to thermal cameras with pixel resolutions of 4K and above—designed to prevent unauthorized physical access, environmental sabotage, and equipment theft in facilities housing critical IT infrastructure. Surveillance Systems capture the largest share of security solution spending as operators demand AI-enhanced video analytics for real-time anomaly detection across multi-tenant halls. Managed Services within installation type is expanding fastest as financial institutions and cloud service providers outsource round-the-clock security operations to avoid capital intensity and staffing gaps.
Hong Kong's Office of the Privacy Commissioner for Personal Data enforces facility audit protocols under the Personal Data (Privacy) Ordinance, compelling operators to demonstrate controlled access logging and visitor traceability. The Security Bureau coordinates with ISO 27001 and PCI DSS compliance frameworks to align physical access controls with information security management standards. Stakeholders must weigh the trade-off between on-premise security staffing and remote monitoring scalability as labor costs and threat sophistication escalate in parallel.
Market Dynamics
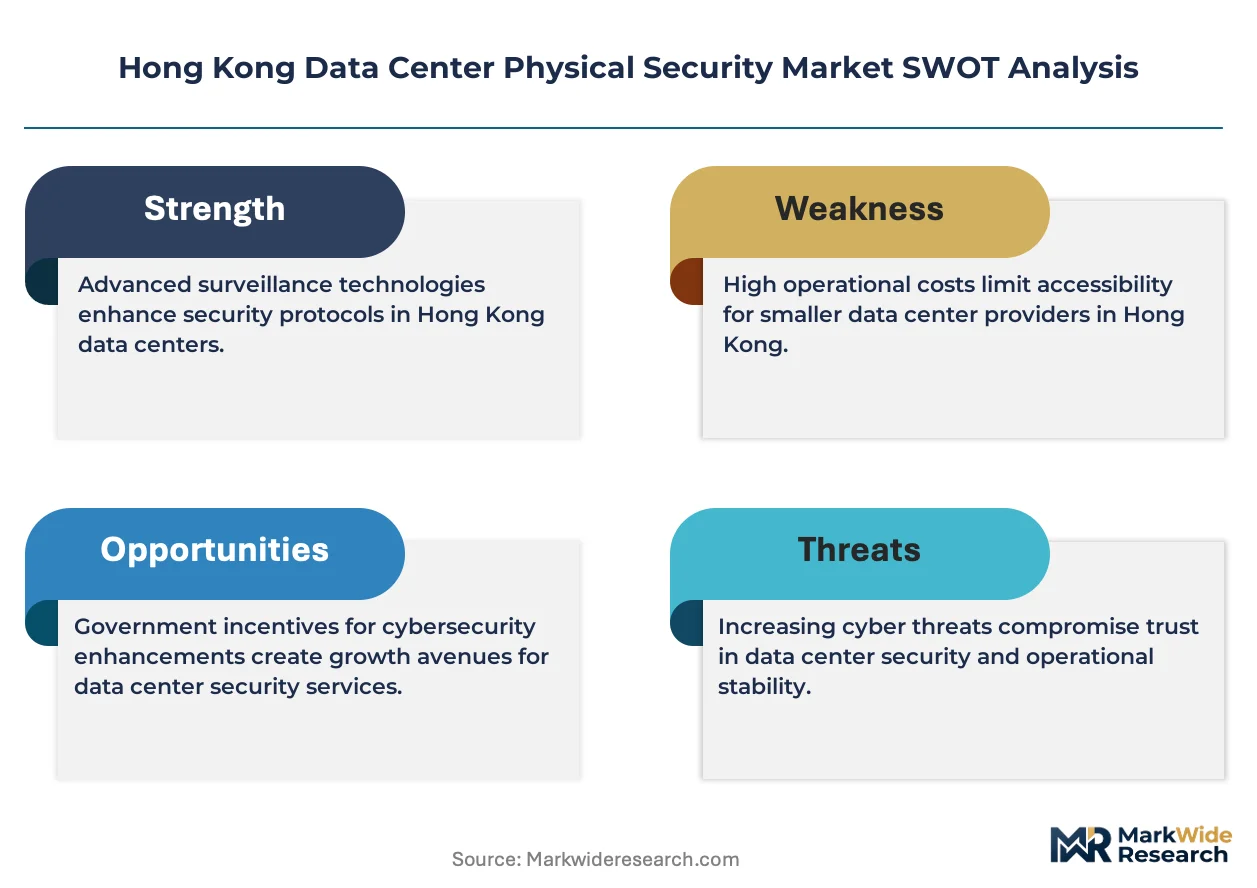
Biometric authentication convergence with AI-driven video analytics is compressing response times and forcing facility operators to consolidate vendor relationships across Hong Kong's dense data center clusters.
Growth Catalysts
- Personal Data (Privacy) Ordinance amendments:Tighter facility audit requirements under Hong Kong's privacy framework are compelling operators to upgrade access logging systems and visitor traceability infrastructure.
- Financial sector colocation expansion:Banks and insurers are expanding physical security budgets for third-party data halls as regulatory scrutiny of outsourced infrastructure intensifies.
- Tseung Kwan O cluster concentration:The industrial estate's high-density server environment creates economies of scale for integrated security deployments across multi-tenant facilities.
Market Restraints
- Specialized technician scarcity:Hong Kong's tight labor market limits availability of certified biometric systems engineers and thermal camera calibration specialists.
- Imported component dependency:Iris scanners and 4K thermal sensors rely heavily on supply chains concentrated in mainland China and Taiwan, exposing operators to cross-border logistics friction.
- PCI DSS compliance complexity:The payment card industry's physical security mandates create overlapping audit burdens with ISO 27001 that slow procurement cycles.
Strategic Opportunities
- Managed security services white space:Cloud service providers and fintechs are outsourcing round-the-clock security operations to avoid capital intensity and staffing gaps.
- Edge-to-core integration:Convergence of on-premise access control with cloud-based security operations centers enables remote monitoring scalability for island facilities.
- Retrofit demand in legacy facilities:Older data halls in Kwai Chung and Tsuen Wan industrial zones require mantrap portal upgrades to meet current insurance underwriting standards.
Industry Challenges
- Multi-standard certification timelines:Simultaneous pursuit of ISO 27001, PCI DSS, and SOC 2 Type II approvals extends deployment schedules by 6-12 months.
- Intergenerational system integration:New AI-enhanced video analytics platforms must interface with legacy analog surveillance infrastructure without triggering facility downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Data Center Physical Security Market |
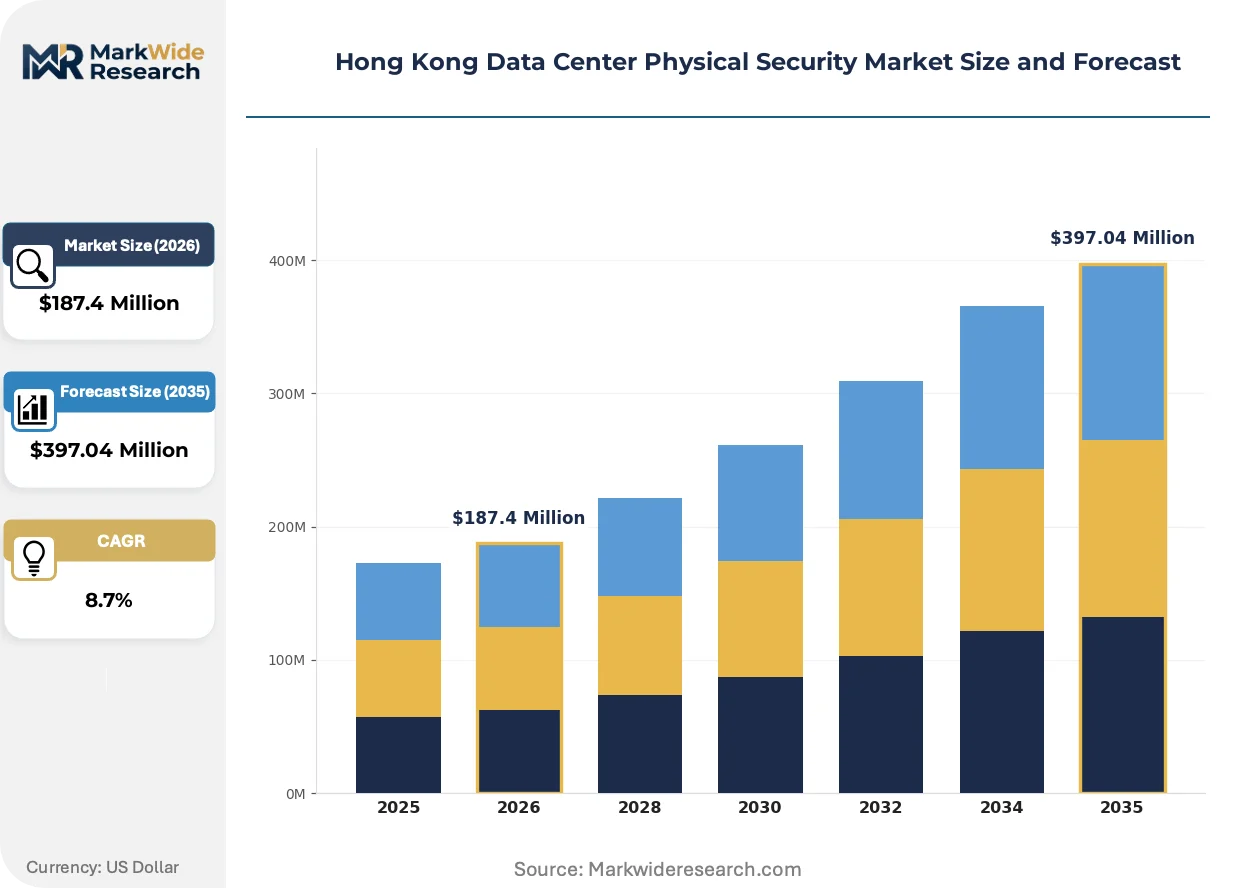
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Solution: Access Control, Surveillance Systems, Intrusion Detection, Fire Safety Installation Type: On-Premise, Remote Monitoring, Managed Services, Hybrid Solutions End User Type: Telecom Providers, Financial Institutions, Cloud Service Providers, Enterprises Compliance Standard: ISO 27001, PCI DSS, SSAE 16, NIST |
| Companies Covered | ABB Ltd, Securitas Technology, Bosch Sicherheitssysteme GmbH, Honeywell International Inc, Schneider Electric, Hangzhou Hikvision Digital Technology Co Ltd, Johnson Controls, Cisco Systems Inc, Dahua Technology Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Data Center Physical Security Market Trends and Innovations
Physical security architecture in Hong Kong data centers is pivoting from perimeter defense to continuous identity verification, compressing the gap between threat detection and automated response.
Software-defined access control is virtualizing credential management across multi-tenant halls. Colocation operators are adopting cloud-native identity platforms that unify biometric, card-based, and mobile credentials under single-pane administration. This convergence is virtualizing the traditional boundary between physical and logical security operations, enabling real-time policy propagation across distributed facilities without on-site controller hardware.
Hong Kong's Office of the Privacy Commissioner for Personal Data is enforcing granular consent mechanisms for biometric data collection under the Personal Data (Privacy) Ordinance. The regulator's facility audit protocols now mandate encrypted storage of fingerprint and iris templates with strict retention limits. High-density financial services data centers are responding by deploying on-premise biometric databases with automated purging workflows rather than cloud-hosted alternatives.
Security procurement is fragmenting as enterprise tenants demand unbundled service contracts. Large cloud providers are separating hardware acquisition from monitoring and maintenance, creating direct relationships with specialized video analytics vendors. This disintermediation is most visible in Tseung Kwan O, where hyperscale operators now contract thermal camera analytics separately from integrated facility management providers.
Hong Kong Data Center Physical Security Market Segmentation
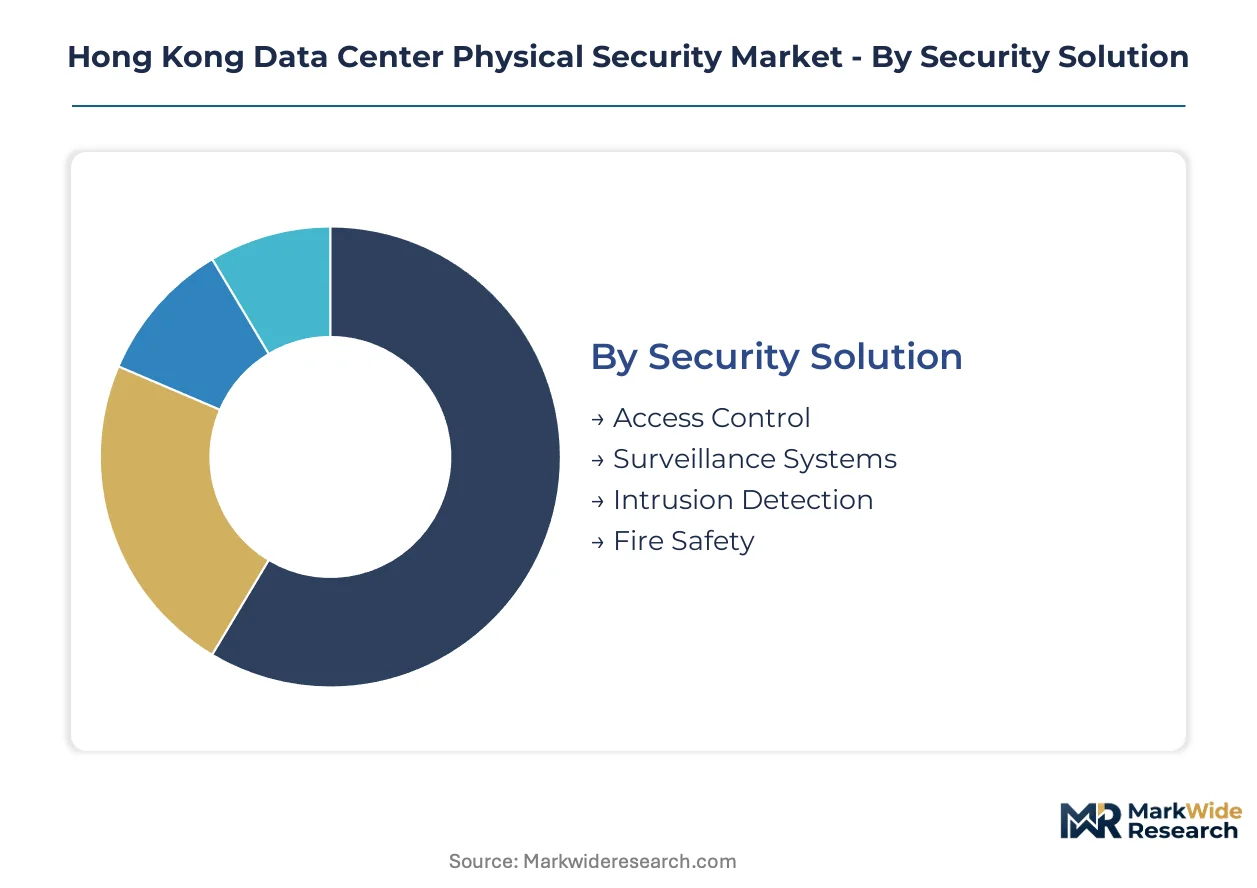
Security procurement in Hong Kong data centers fragments across solution types, deployment models, and compliance frameworks. Each segment carries distinct after-sales service intensity, from thermal camera calibration contracts to 24/7 managed security operations.
Security Solution:
After-sales service intensity varies sharply across physical security layers, with video analytics platforms demanding continuous algorithm updates and biometric systems requiring specialist recalibration.
- Surveillance Systems:AI-enhanced video analytics platforms with 4K thermal cameras and real-time anomaly detection dominate facility spending. Demand concentrates in Tseung Kwan O's multi-tenant halls where financial institutions mandate pixel-perfect perimeter coverage under insurance underwriting standards.
- Access Control:Biometric authentication systems encompassing iris scanners, mantrap portals, and software-defined credential management form the identity verification backbone. Colocation operators in the industrial estate cluster deploy these for visitor traceability compliance under the Personal Data (Privacy) Ordinance.
- Intrusion Detection:Perimeter hardening sensors and motion detection arrays protect against environmental sabotage.
- Fire Safety:Integrated suppression and early warning systems designed for high-density server environments.
Surveillance Systems holds the largest share; momentum sits with Access Control as biometric convergence accelerates.
Installation Type:
Cost tier stratification separates capital-intensive on-premise deployments from operational expenditure models favored by cloud service providers.
- Managed Services:Outsourced round-the-clock security operations covering monitoring, incident response, and compliance reporting. Financial institutions and fintechs in Hong Kong adopt these to bypass certified technician scarcity and avoid staffing gaps.
- Remote Monitoring:Cloud-based security operations centers enabling centralized oversight of distributed island facilities. Edge-to-core integration is climbing the fastest as operators seek scalability without on-site controller hardware.
- On-Premise:Dedicated security staffing and local system administration retained within facility boundaries.
- Hybrid Solutions:Blended architectures combining local access control with cloud-based analytics and backup monitoring.
Managed Services is gaining share fastest; On-Premise retains the largest installed base.
End User Type:
Application requirements diverge between regulated financial infrastructure and hyperscale cloud platforms with standardized security specifications.
- Financial Institutions:Banks and insurers operating colocation facilities with the most stringent audit requirements. These entities expand physical security budgets fastest as regulatory scrutiny of outsourced infrastructure intensifies under PCI DSS and ISO 27001 mandates.
- Cloud Service Providers:Hyperscale operators demanding unbundled service contracts and direct vendor relationships. Procurement in Tseung Kwan O shows these players separating thermal camera analytics from integrated facility management.
- Telecom Providers:Carrier-neutral facilities requiring baseline perimeter protection and access logging.
- Enterprises:Corporate data halls with variable compliance needs based on sector and data sensitivity.
Financial Institutions hold the largest share; Cloud Service Providers show the steepest expansion trajectory.
Compliance Standard:
Certification complexity creates overlapping audit burdens that extend procurement cycles and favor integrated security vendors.
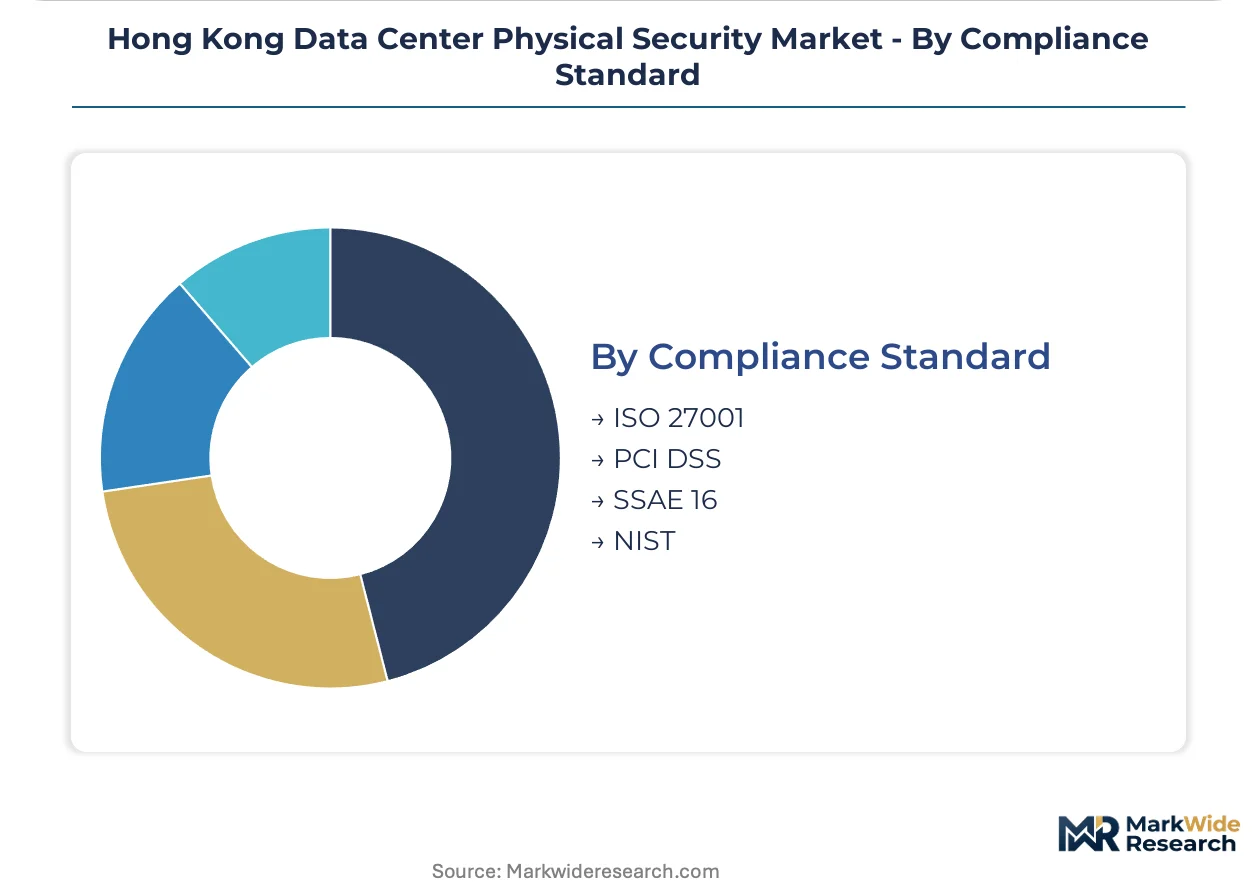
- ISO 27001:Information security management standards mandating controlled access logging and physical access controls. The Security Bureau coordinates with this framework to align facility protocols across Hong Kong data centers.
- PCI DSS:Payment card industry physical security mandates creating specific requirements for cardholder data environments. Financial services operators face the heaviest overlap with ISO 27001, slowing deployment schedules.
- SSAE 16:Service organization control reporting for outsourced security operations.
- NIST:Cybersecurity framework guidelines increasingly referenced by multinational enterprises.
ISO 27001 holds the largest share; PCI DSS generates the most procurement friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across Hong Kong's data center clusters. Financial institutions in core districts absorb premium security costs without volume reduction, while colocation operators in outlying industrial zones negotiate aggressively on per-rack monitoring fees.
Tseung Kwan O Industrial Estate
Hyperscale cloud providers and multi-tenant colocation facilities drive demand for integrated mantrap portals and 4K thermal surveillance. The Office of the Privacy Commissioner for Personal Data enforces granular biometric data retention limits here. Tseung Kwan O's high-density server environment creates procurement economies for standardized access control across adjacent facilities.
Kwai Chung Industrial Zone
Legacy data halls require retrofit mantrap upgrades to meet current insurance underwriting standards. The Security Bureau coordinates ISO 27001 alignment with facility audit protocols for these older buildings. Operators in Kwai Chung face compressed margins as they balance compliance spending against aging infrastructure depreciation schedules.
Tsuen Wan Industrial Area
Mid-tier colocation providers concentrate here, prioritizing remote monitoring scalability over on-premise staffing. The Personal Data (Privacy) Ordinance amendments compel visitor traceability system investments. Tsuen Wan facilities increasingly outsource round-the-clock security operations to managed services vendors to bypass certified technician scarcity.
Hong Kong Island Core
Financial services headquarters and premium enterprise data centers anchor the highest security spending per square meter. The Security Bureau's PCI DSS coordination with ISO 27001 creates overlapping audit burdens that slow procurement cycles. Central district facilities deploy on-premise biometric databases with automated purging workflows rather than cloud-hosted alternatives.
Hong Kong Data Center Physical Security Market Competitive Landscape
Capability concentration sits with integrated building automation specialists; scale advantage sits with pure-play security technology vendors. The vendor base stratifies into three tiers: multinational conglomerates with cross-sold facility infrastructure portfolios, regional specialists in video analytics and edge detection, and emerging managed services operators. Consolidation pressure favors players with energy-efficient security infrastructure and cloud-native identity platforms. Dominant competitive moves include strategic partnerships between hardware OEMs and managed security providers, plus portfolio diversification into software-defined access control.
Within the integrated infrastructure tier, Honeywell International Inc and Schneider Electric anchor competitive positioning through building automation heritage and energy-efficient security portfolios respectively. Bosch Sicherheitssysteme GmbH occupies a specialist position in video analytics and edge-based threat detection. These three exemplify the capability-scale trade-off defining vendor selection in Hong Kong's dense data center clusters.
| Leading Market Players |
|---|
| ABB Ltd |
| Securitas Technology |
| Bosch Sicherheitssysteme GmbH |
| Honeywell International Inc |
| Schneider Electric |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Johnson Controls |
| Cisco Systems Inc |
| Dahua Technology Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in certified biometric systems engineering across Hong Kong is compressing margins for installation providers while amplifying pricing power for vendors with captive technician networks. Facility operators facing audit deadlines under the Personal Data (Privacy) Ordinance absorb premium labor costs without volume reduction, while procurement teams in legacy industrial zones negotiate aggressively on per-rack monitoring fees to offset retrofit capital burdens.
Pricing Analysis
After-sales service contracts covering thermal camera calibration and biometric recalibration drive lifetime value for security infrastructure vendors. Three-tier pricing structure across premium, standard, and economy levels separates financial institutions demanding ISO 27001-compliant installations from mid-tier colocation providers in Tsuen Wan. Cost compression in standard-tier access control intensifies because mainland Chinese component suppliers are expanding direct sales channels. Cloud service providers exhibit the lowest price sensitivity as they prioritize uptime guarantees over per-unit hardware costs.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for iris scanner and 4K thermal sensor procurement as vendors absorb working capital pressure from mainland China and Taiwan manufacturing partners. Hong Kong's physical security infrastructure draws from concentrated component supply in mainland China, Taiwan, and South Korea for advanced imaging sensors and edge computing chipsets. Single-source vulnerability in thermal sensor modules creates exposure to cross-border logistics friction at Shenzhen-Hong Kong checkpoints. Distribution runs through integrated facility management providers in Tseung Kwan O, with direct vendor relationships emerging among hyperscale cloud operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility operators across Hong Kong are competing for a finite pool of biometric systems engineers and PCI DSS compliance specialists, creating asymmetric returns for vendors with training academy investments or captive certification pipelines.
For Market Incumbents: Harden defensive moats by acquiring managed security services operators in Tsuen Wan and Kwai Chung to secure technician deployment capacity. Invest in on-premise biometric database development to capture financial institution demand for encrypted template storage under Privacy Commissioner audit protocols. Cloud-native identity platform entrants threaten traditional hardware margins; vertical integration into software-defined access control preserves pricing power. For New Entrants and Emerging Players: Retrofit demand in legacy Kwai Chung data halls represents the most penetrable entry point for mantrap portal upgrades meeting current insurance underwriting standards. Managed services white space among mid-tier colocation providers in Tsuen Wan offers recurring revenue conversion without capital-intensive hardware competition. Lead with remote monitoring scalability propositions that bypass Hong Kong's certified technician scarcity through edge-to-core integration architectures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed security services operators with financial institution client concentrations and multi-year compliance reporting contracts. Long-term viability rests on regulatory complexity deepening rather than simplifying across the projection horizon. Target acquisition archetypes include regional specialists in video analytics with existing Privacy Commissioner audit relationships. The signal to watch is amendment timing for the Personal Data (Privacy) Ordinance—accelerated enforcement would compress procurement cycles for compliant infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Access Control Platform Launch | Virtualizes credential management across Tseung Kwan O multi-tenant halls without on-site controller hardware. |
| Managed Security Services Acquisition | Captures technician deployment capacity and financial institution compliance reporting relationships. |
| On-Premise Biometric Database Development | Addresses Privacy Commissioner encrypted storage mandates with automated template purging workflows. |
| Edge-to-Core Integration Partnership | Enables remote monitoring scalability for island facilities through cloud-native security operations centers. |
| Retrofit Mantrap Portal Deployment | Upgrades legacy Kwai Chung and Tsuen Wan facilities to current insurance underwriting standards. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center facility managers, physical security system integrators, biometric technology vendors, and compliance officers at financial institutions. Secondary validation drew from Security Bureau coordination documents, Office of the Privacy Commissioner for Personal Data audit protocols, ISO 27001 and PCI DSS framework publications, and customs records for thermal camera and iris scanner imports. Bottom-up sizing of facility-level security spending was triangulated against top-down market aggregation across the analysis window.
Calibration against historical procurement cycles and regulatory enforcement timelines anchored the projection framework. Segmentation dimensions modeled include security solution type, installation model, end-user archetype, and compliance standard tier, with cross-segment interaction effects for multi-tenant versus single-tenant facility configurations. CAGRs were derived from regression analysis of capital expenditure patterns against audit intensity metrics. Industry-specific forecast inputs incorporated Privacy Commissioner staffing levels and financial sector colocation expansion announcements.
Practitioners should monitor cross-border logistics friction at Shenzhen-Hong Kong checkpoints and Privacy Commissioner enforcement staffing for early signals of supply constraint or compliance acceleration. Forecasts reflect assumptions about regulatory amendment timing and technician certification pipeline stability. Macroeconomic deviation affecting financial sector outsourcing budgets, regulatory enforcement intensity changes, or breakthroughs in cloud-hosted biometric encryption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Tactical Vests Market
Physical Security
Border Security Technologies Market
Physical Security
North America Physical Security Market
Physical Security
Body Armor Plates Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Physical Security Equipment Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Body Armor Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Canada Data Center Physical Security Market
Physical Security
Europe Cargo Inspection Market
Physical Security
Security Guard Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
Europe Physical Security Market