
 Asia-Pacific Green Carbon Market | 2026-2036
Asia-Pacific Green Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Green Carbon Market Analytics
China's dual carbon goals is expanding compliance obligations across energy-intensive sectors. EKI Energy Services leverages its project development footprint across South and Southeast Asia to sustain origination capacity. Climate Impact X anchors Singapore's carbon trading hub with exchange infrastructure for nature-based credits. South Pole competes through specialized forestry and cookstove methodologies that differentiate its portfolio quality.
Green carbon encompasses verified emissions reductions, removal credits, and transferable allowances issued under compliance or voluntary frameworks, typically quantified in metric tonnes of carbon dioxide equivalent and fungible across registries. The primary commercial purpose is to transfer environmental liability from emitters to project developers while creating price signals for abatement investment. Carbon credits dominate transaction flow as the most liquid instrument class, while blockchain-based verification infrastructure represents the fastest-growing technology segment due to demand for immutable provenance tracking. Renewable Energy Certificates occupy a mature niche with standardized issuance protocols, whereas emission allowances concentrate margin pools in regulated compliance markets.
China's MEE enforces national emissions trading scheme expansion, while Australia's Clean Energy Regulator administers Safeguard Mechanism reforms that tighten baselines for major facilities. Japan's METI guides corporate decarbonization through GX League commitments that standardize voluntary claim integrity. India's BIS is developing domestic carbon credit certification protocols that will reshape market access rules for foreign project developers. Stakeholders must monitor divergence between national registry standards and interoperability frameworks before committing capital to cross-border credit pipelines.
Market Dynamics
China's MEE is tightening compliance baselines under the national emissions trading scheme expansion, forcing steel and cement majors into active offset procurement rather than passive quota compliance.
Growth Catalysts
- Steel sector decarbonization mandates:China's dual carbon goals require heavy industry buyers to secure verified removal credits for residual emissions that process efficiency cannot eliminate.
- Safeguard Mechanism reforms:Australia's Clean Energy Regulator is ratcheting down facility baselines, converting voluntary offset demand into compliance-driven procurement for LNG and alumina producers.
- Southeast Asia reforestation corridor:Indonesia, Malaysia, and Vietnam concentrate nature-based project development where carbon stock permanence attracts premium pricing from Japanese GX League participants.
Market Restraints
- Verification cost inflation:Remote sensing and third-party validation expenses for nature-based credits consume 15-25% of project revenue, compressing developer margins.
- Registry fragmentation:Divergence between China's national registry, Australia's Clean Energy Regulator protocols, and Singapore's Climate Impact X standards creates cross-border settlement friction.
- Permanence risk in tropical forestry:Fire and illegal logging exposure in Indonesian peatland projects undermines credit fungibility for risk-averse compliance buyers.
Strategic Opportunities
- Vietnam's nascent voluntary market:Limited domestic registry infrastructure creates first-mover advantage for foreign developers establishing local verification partnerships.
- Blue carbon methodologies:Mangrove restoration protocols aligned with Japan's METI GX League standards open premium pricing for coastal ecosystem projects.
- Blockchain provenance infrastructure:Immutable transaction ledgers are converging with satellite monitoring to reduce counterparty risk in over-the-counter credit sales.
Industry Challenges
- Methodology standardization delays:India's BIS has yet to finalize domestic certification protocols, freezing project registration pipelines and extending developer capital lockup periods.
- Cross-registry interoperability:Incompatible serial number formats between Australia's Clean Energy Regulator and Singapore-based exchanges complicate portfolio aggregation for multinational buyers.
- Technical capacity scarcity:Shortages of accredited validation bodies in Southeast Asia extend project approval timelines beyond investor return thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Green Carbon Market |
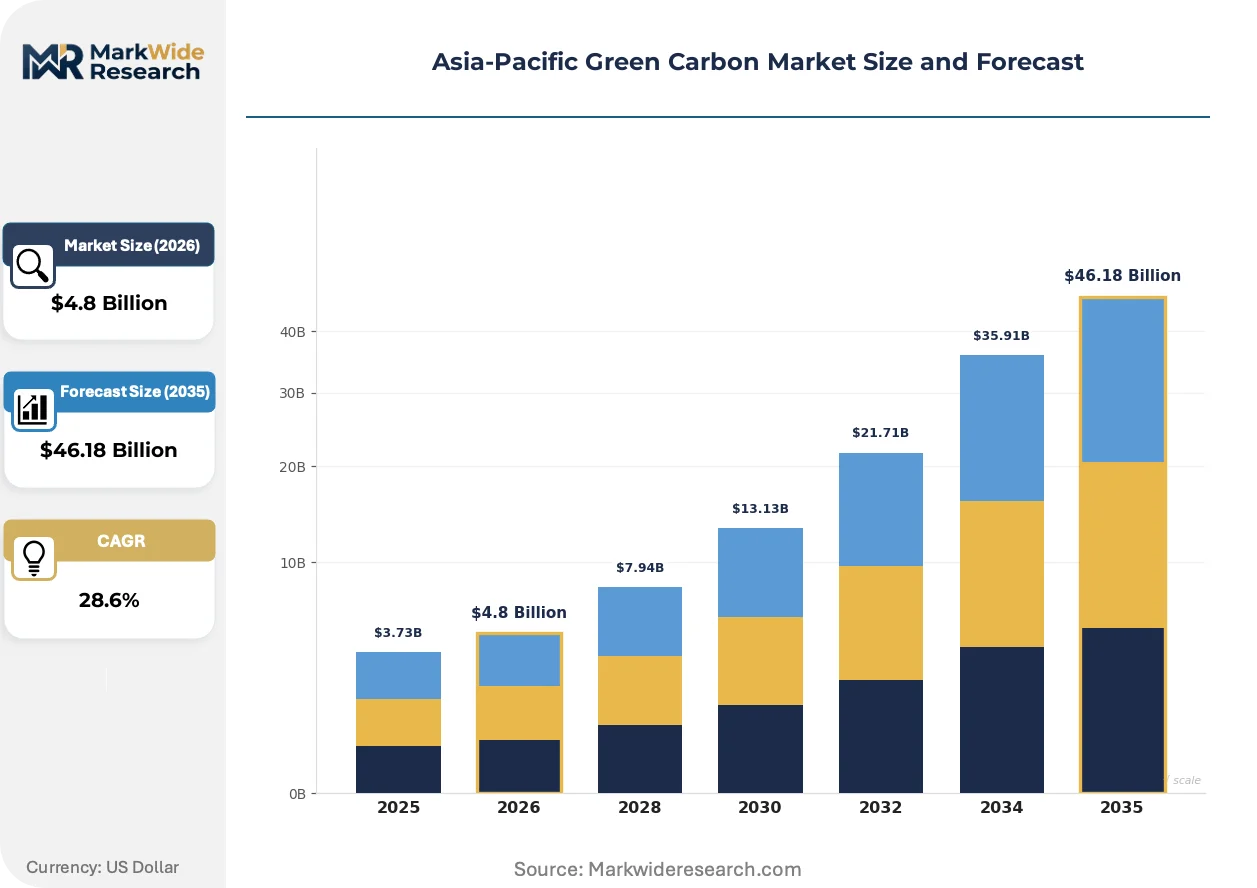
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Credits, Offsets, Renewable Energy Certificates, Emission Allowances End User: Corporations, Governments, NGOs, Financial Institutions Technology: Carbon Capture, Blockchain, AI Analytics, Renewable Energy Solutions Application: Sustainable Development, Climate Strategy, Emission Trading, Corporate Sustainability |
| Companies Covered | Climate Impact X, South Pole, Verra, EKI Energy Services, Finite Carbon, NativeEnergy, Carbon Care Asia, ClearSky, ACX, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Green Carbon Market Evolving Landscape
Digital verification infrastructure and policy-linked procurement mandates are restructuring how credits originate, trade, and settle across the Asia-Pacific corridor.
Blockchain-based monitoring systems are converging with satellite imagery analytics to create immutable audit trails for nature-based credits. Heavy industry buyers in Australian LNG and Japanese steel are mandating this dual-verification stack for procurement decisions. The structural consequence is compressing due diligence cycles from months to weeks while elevating price premiums for transparently sourced removals.
Japan's METI GX League commitments are standardizing voluntary claim integrity through standardized disclosure templates. Corporate participants must document credit retirement against residual emissions with third-party assurance. Japanese automotive and electronics manufacturers are most affected, redirecting procurement toward Singapore-based exchanges with integrated retirement tracking.
Steel and cement majors are consolidating offset purchasing through direct offtake agreements with project developers, bypassing intermediaries. This channel disintermediation concentrates volume commitments with top-tier developers holding established Southeast Asia pipelines. The shift is most visible in China, where state-owned steel groups negotiate multi-year prepayment structures for Indonesian reforestation credits.
Asia-Pacific Green Carbon Market Segmentation
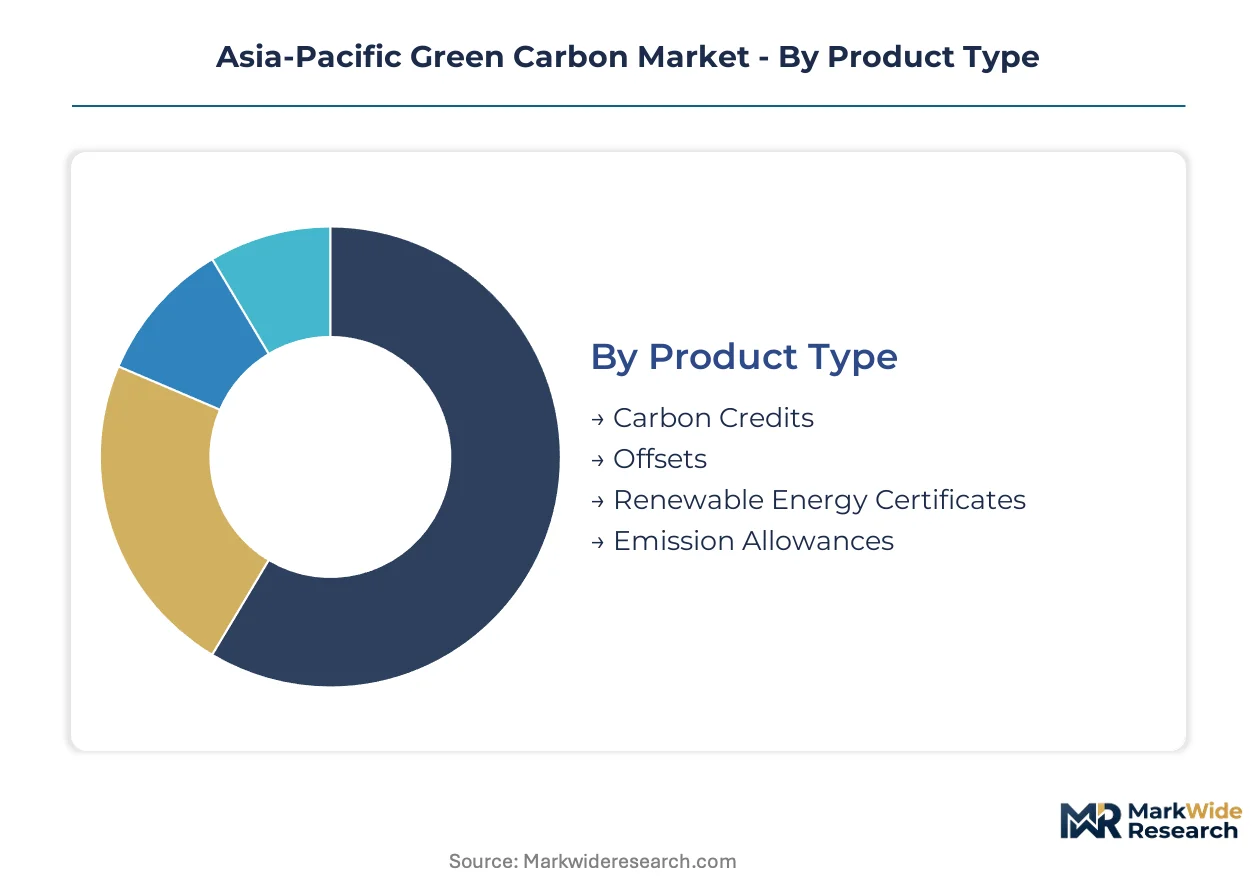
Segmentation in the Asia-Pacific green carbon market reveals how compliance obligations, verification technologies, and buyer sophistication create distinct commercial corridors. Each dimension shapes procurement patterns, pricing power, and project development economics across the region's fragmented regulatory landscape.
Product Type:
Carbon credit issuance concentrates in Southeast Asian project pipelines where nature-based methodologies command premium pricing from Japanese and Australian compliance buyers.
- Carbon Credits:Verified emissions reductions and removal credits trade as the most liquid instrument class, with Indonesian reforestation projects supplying bulk volume to Australian LNG producers under Safeguard Mechanism reforms. Chinese steel majors now source removal credits directly from Malaysian peatland developers through multi-year offtake structures that bypass intermediary exchanges.
- Offsets:Voluntary market instruments carry permanence risk premiums that vary by verification rigor, with Singapore-based Climate Impact X establishing benchmark pricing for tropical forestry offsets through integrated satellite monitoring. Japanese GX League participants pay structural premiums for offsets with blockchain-tracked provenance.
- Renewable Energy Certificates:Mature issuance protocols dominate Indian and Australian solar and wind project monetization, though fungibility constraints limit cross-border trading.
- Emission Allowances:China's national ETS concentrates margin pools in state-administered compliance markets with limited international interoperability.
Today's leader: Carbon Credits. Tomorrow's challenger: Offsets.
End User:
Procurement sophistication varies sharply across buyer categories, with compliance-driven entities demanding stricter verification stacks than voluntary participants.
- Corporations:Heavy industry buyers in Australian alumina and Japanese automotive sectors mandate dual-verification infrastructure combining satellite imagery with blockchain audit trails. Steel majors in China negotiate direct developer relationships that compress transaction costs but extend capital lockup periods.
- Governments:National procurement concentrates in China's MEE-administered ETS expansion and Australia's Clean Energy Regulator baseline tightening, converting policy mandates into structured offset demand.
- NGOs:Conservation-focused buyers prioritize permanence in Indonesian and Vietnamese reforestation corridors, accepting lower liquidity for higher environmental integrity claims.
- Financial Institutions:Singapore-based trading houses and Japanese banks intermediate credit aggregation, though registry fragmentation complicates portfolio construction across Australian and Chinese standards.
Corporations dominate transaction flow. Financial institutions are gaining share fastest.
Technology:
Verification infrastructure investment determines project developer margins, with remote sensing costs consuming substantial revenue shares in nature-based methodologies.
- Carbon Capture:Direct air capture and industrial point-source technologies remain nascent in the Asia-Pacific corridor, with Australian pilot projects attracting Japanese GX League procurement commitments for engineered removals.
- Blockchain:Immutable transaction ledgers converge with satellite monitoring to reduce counterparty risk in over-the-counter credit sales, with Singapore exchanges integrating retirement tracking for Japanese automotive buyers.
- AI Analytics:Machine learning models process satellite imagery for carbon stock estimation in Indonesian peatland projects, compressing validation timelines but requiring scarce technical expertise.
- Renewable Energy Solutions:Solar and wind project monitoring relies on standardized production data protocols with limited differentiation in verification economics.
Blockchain anchors near-term infrastructure investment. AI Analytics holds the steepest expansion trajectory.
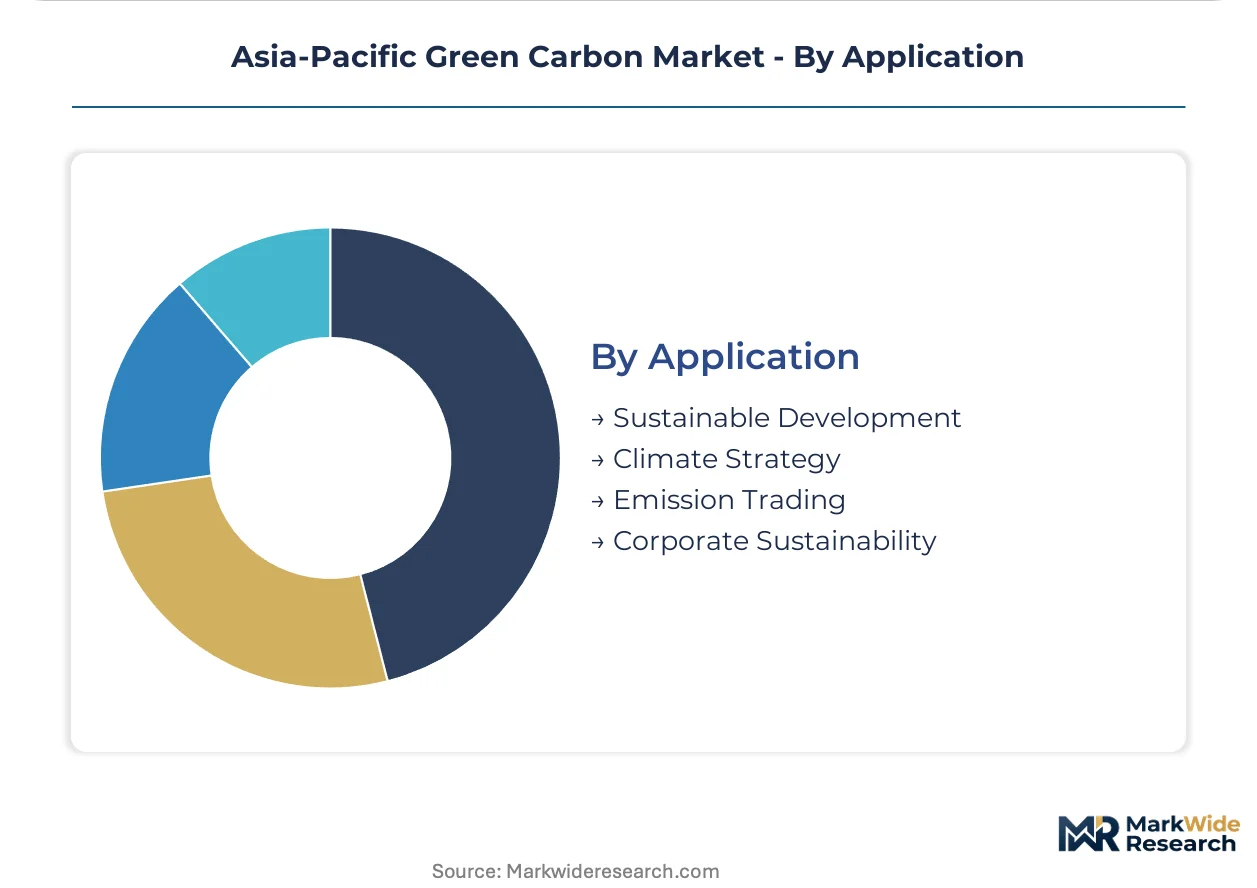
Application:
End-use purpose shapes credit quality requirements, with compliance applications demanding stricter permanence guarantees than voluntary sustainability claims.
- Sustainable Development:Co-benefit certification in Vietnamese and Malaysian projects attracts premium pricing from European-linked buyers, though methodology standardization delays under India's BIS freeze pipeline expansion.
- Climate Strategy:Residual emissions management drives Chinese steel and cement majors into active offset procurement, with removal credits preferred over avoidance-based instruments.
- Emission Trading:Australia's Safeguard Mechanism and China's ETS create compliance-linked demand with distinct registry protocols that complicate cross-border arbitrage.
- Corporate Sustainability:Voluntary claim integrity standards under Japan's METI GX League redirect procurement toward Singapore-based exchanges with integrated disclosure templates.
Emission Trading commands volume concentration. Climate Strategy is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon trading infrastructure first scaled in Australia's compliance markets before spreading through Southeast Asian project corridors and China's national exchange expansion. The region's regulatory fragmentation now shapes distinct procurement geographies across five national markets.
China
Steel and cement majors drive removal credit demand under MEE's national ETS expansion. Dual carbon goals mandate state-owned enterprises secure verified offsets for residual emissions beyond process efficiency gains. Shanghai's carbon exchange anchors liquidity for compliance-linked transactions.
Australia
LNG and alumina producers face tightened Safeguard Mechanism baselines from the Clean Energy Regulator. Compliance-driven procurement now dominates voluntary offset demand. Sydney-based trading houses intermediate credit aggregation for industrial facilities.
Japan
Automotive and electronics manufacturers align procurement with METI GX League disclosure standards. Corporate participants document credit retirement against residual emissions with third-party assurance. Tokyo anchors demand for blockchain-tracked provenance.
Indonesia
Peatland reforestation projects supply nature-based credits to Australian and Japanese buyers. Fire and illegal logging exposure compresses credit fungibility for risk-averse compliance purchasers. Kalimantan concentrates project development pipelines.
Singapore
Climate Impact X infrastructure anchors the region's voluntary trading hub with integrated retirement tracking. Exchange standards diverge from Australian and Chinese registry protocols. The city-state intermediates cross-border settlement for multinational buyers.
Asia-Pacific Green Carbon Market Competitive Landscape
Capital-heavy project developers compete with asset-light verification specialists across distinct margin pools. The market structure fragments between origination-intensive players holding Southeast Asian land access and technology-anchored platforms selling audit infrastructure. Three archetypes dominate: pipeline developers with established reforestation corridors, exchange operators with integrated registry standards, and methodology specialists differentiating through proprietary carbon quantification protocols. Strategic moves concentrate on direct offtake negotiations and blockchain verification partnerships.
Within the exchange operator tier, Climate Impact X anchors Singapore's trading infrastructure. Among methodology specialists, South Pole and Verra occupy positions defined by forestry and cookstove protocol differentiation. EKI Energy Services represents the pipeline developer archetype with origination capacity across South and Southeast Asian project corridors.
| Leading Market Players |
|---|
| Climate Impact X |
| South Pole |
| Verra |
| EKI Energy Services |
| Finite Carbon |
| NativeEnergy |
| Carbon Care Asia |
| ClearSky |
| ACX |
| Others |
Value Network & Pricing Analysis
Blockchain-based verification infrastructure is simultaneously elevating cost structures for project developers and concentrating origination capacity among capitalized players capable of absorbing upfront technology investment. This dual shift compresses margins for smaller developers while embedding premium pricing tiers for credits with immutable provenance tracking.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transaction flows, with premium tiers commanding structural premiums for blockchain-tracked removal credits from Japanese GX League participants. Price differentiation hinges on verification rigor and permanence guarantees, with fire-risk exposure in Indonesian peatland projects compressing fungibility for risk-averse Australian compliance buyers. Cost compression in standard-tier nature-based credits is intensifying because remote sensing validation expenses now consume 15-25% of project revenue. Financial institutions demonstrate lowest price sensitivity, while Vietnamese project developers facing limited domestic registry infrastructure exhibit highest elasticity.
Supply Chain Analysis
Domestic-content mandates under India's BIS certification protocol development are reshaping sourcing patterns, forcing foreign developers to establish local validation partnerships or exit pipeline registration queues. Geographic supply concentration centers on Indonesia, Malaysia, and Vietnam for nature-based credit origination, with Australian LNG producers and Japanese automotive manufacturers as primary offtake anchors. Raw material dependencies draw from satellite imagery analytics, accredited validation body capacity, and peatland carbon stock inventories. Single-source vulnerability around Southeast Asia's limited pool of accredited validation bodies extends project approval timelines beyond investor thresholds. Distribution runs through Singapore-based exchange infrastructure with integrated retirement tracking for multinational buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific green carbon market compounds steadily as compliance mandates across China's MEE-administered ETS and Australia's Safeguard Mechanism convert policy thresholds into structural offset demand.
For Market Incumbents: Anticipate registry fragmentation between China's national standards and Singapore's Climate Impact X protocols by investing in dual-certification capacity that preserves cross-border settlement optionality. Defensive consolidation through direct offtake negotiations with Indonesian and Malaysian project developers secures volume commitments before baseline tightening accelerates procurement competition. Vertical integration into satellite monitoring partnerships reduces third-party validation cost exposure that currently compresses margins. For New Entrants and Emerging Players: Launch via Vietnam's nascent voluntary market where limited domestic registry infrastructure creates first-mover positioning for foreign developers establishing local verification partnerships. Blue carbon methodologies aligned with Japan's METI GX League standards represent the most penetrable white-space, with mangrove restoration protocols attracting premium pricing from coastal ecosystem demand. Go-to-market execution should anchor on blockchain-tracked provenance infrastructure that differentiates from incumbent verification stacks. For Investors and Strategic Acquirers: Valuations sit cheapest among project developers holding established Southeast Asian land access but lacking integrated exchange relationships or retirement tracking capabilities. Long-term viability across the analysis window favors pipeline developers with origination capacity across multiple national regulatory frameworks rather than single-registry dependence. Acquisition target archetype: mid-tier developers with Indonesian or Malaysian reforestation corridors and unexploited blue carbon methodology potential. The signal to watch is India's BIS protocol finalization, which will unfreeze capital deployment into previously stalled registration pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Verification Partnership | Immutable provenance tracking reduces counterparty risk in over-the-counter credit sales to Japanese buyers. |
| Direct Offtake Negotiation | Multi-year prepayment structures with Chinese state-owned steel groups bypass intermediary exchange fees. |
| Blue Carbon Methodology Development | Mangrove restoration protocols aligned with METI GX League standards open premium coastal ecosystem pricing. |
| Dual-Registry Certification Investment | Parallel registration under Australian Clean Energy Regulator and Singapore Climate Impact X preserves arbitrage optionality. |
| Local Validation Partnership Establishment | Vietnamese verification alliances circumvent India's BIS protocol delays freezing foreign developer pipelines. |
Research Methodology
Coverage spans China, Australia, Japan, Indonesia, and Singapore, with primary inputs from each national market combining structured interviews with carbon project developers, exchange operators, and compliance officers at heavy industrial facilities with secondary validation. Stakeholder roles engaged include MEE policy implementation leads, Clean Energy Regulator baseline administrators, METI GX League corporate sustainability directors, peatland project validation specialists, and Singapore-based trading house credit aggregation desks. Secondary sources draw from national emissions trading scheme disclosure filings, Safeguard Mechan mechanism compliance reports, GX League disclosure templates, and project development database registries. Bottom-up credit volume aggregation triangulates against top-down policy mandate quantification.
Rate-of-change decomposition separates volume expansion from price trajectory across the projection horizon, with segmentation modeled by product type (carbon credits, offsets, renewable energy certificates, emission allowances), end user (corporations, governments, NGOs, financial institutions), technology (blockchain, AI analytics, carbon capture, renewable energy solutions), and application (sustainable development, climate strategy, emission trading, corporate sustainability). CAGRs derive from regression analysis against policy implementation timelines and industrial facility baseline tightening schedules. Industry-specific forecast inputs include satellite monitoring cost curves and accredited validation body capacity expansion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under India's BIS protocol finalization delays or Indonesian peatland fire events that undermine credit permanence claims. Forecasts reflect assumptions around MEE ETS expansion pace, Safeguard Mechanism baseline ratchet schedules, and GX League disclosure standard adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market